
 North America High Voltage Switchgear Market | 2026-2036
North America High Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
North America High Voltage Switchgear Market Insights
Multi-sourced component procurement is recalibrating as OEMs rebuild domestic supply chains for critical breaker and relay assemblies. ABB Ltd. leverages its North American manufacturing footprint to shorten lead times for utility-scale installations. Siemens Energy AG anchors its position through integrated digital monitoring platforms paired with primary switchgear hardware. General Electric Company competes on transformer-switchgear bundling for large transmission substation projects.
High voltage switchgear encompasses electrical disconnect and protection apparatus rated above 36 kV, engineered with vacuum interrupters, SF6 insulation chambers, or hybrid dielectric systems to isolate fault currents and maintain grid stability across transmission networks. Gas insulated switchgear commands premium positioning due to compact footprint requirements in dense urban substations, while vacuum technology gains share in environmentally constrained jurisdictions. The renewable energy end-user segment represents the fastest-growing demand pool as offshore wind and utility-scale solar farms require new collector substations with specialized switching protocols.
FERC Order 2023 interconnection reforms and NERC CIP reliability standards are tightening procurement specifications for grid-connected switchgear across the United States. The EPA's phasedown of hydrofluorocarbons and SF6 emissions limits under the American Innovation and Manufacturing Act are reshaping product design priorities for manufacturers serving Canadian and US utilities. Stakeholders must weigh the capital cost gap between conventional gas-insulated systems and emerging vacuum-hybrid architectures against accelerating compliance timelines and carbon accounting pressures from utility offtakers.
Market Dynamics
EPA's phasedown of sulfur hexafluoride emissions under the American Innovation and Manufacturing Act is forcing utilities across the United States and Canada to accelerate retirement schedules for gas-insulated switchgear and validate vacuum-interrupter alternatives for transmission-grade applications.
Growth Catalysts
- FERC Order 2023:Interconnection queue reforms mandate standardized grid-impact studies that compress project timelines for renewable collector substations requiring specialized high-voltage switching protocols.
- Offshore wind buildout:Atlantic coast lease rounds from Massachusetts to North Carolina require purpose-built 230 kV and 345 kV collector substations with marine-environment switchgear specifications.
- Texas ERCOT expansion:Utility-scale solar and battery storage interconnections in West Texas drive demand for outdoor-rated switchgear assemblies capable of extreme temperature cycling.
Market Restraints
- Copper and rare earth price volatility:Vacuum interrupter manufacturing depends on copper-chromium contact materials and permanent magnet actuators, exposing OEMs to commodity swings that compress margin on fixed-price utility contracts.
- Domestic casting capacity concentration:High-voltage breaker tank and enclosure fabrication concentrates in a narrow Midwest supplier base, creating single-source vulnerability for critical structural components.
- SF6 banked inventory lock-in:Utilities with substantial installed gas-insulated switchgear bases face stranded asset risk and retrofit cost uncertainty as EPA compliance timelines tighten.
Strategic Opportunities
- Mexico transmission modernization:CFE's grid reinforcement programs along the Baja California and Yucatan corridors present entry points for vacuum-technology suppliers meeting NOM certification requirements.
- Digital twin integration:Convergence of switchgear hardware with edge-computing sensors and cloud-based asset management platforms enables recurring software revenue streams alongside equipment sales.
- IRA domestic content bonuses:Production tax credit adders for projects sourcing North American-manufactured electrical equipment incentivize OEMs to expand US-based breaker and relay assembly lines.
Industry Challenges
- High-voltage vacuum engineering talent scarcity:Specialized expertise in 145 kV+ vacuum interrupter design and dielectric testing concentrates at a handful of research institutions and legacy manufacturer engineering centers.
- NERC CIP-014 physical security certification:Transmission substation switchgear procurement now requires documented compliance with sabotage protection standards, extending bid-to-award cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America High Voltage Switchgear Market |
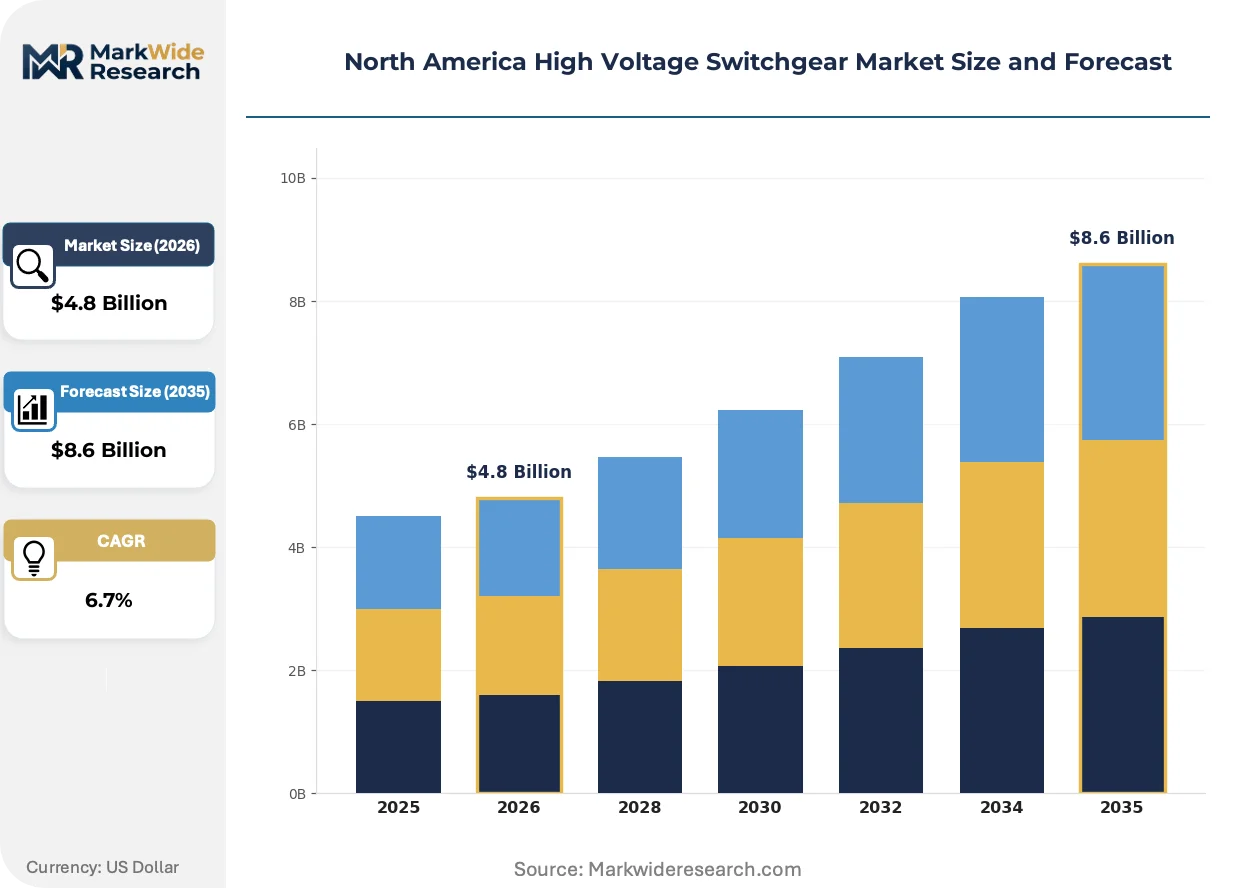
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Switchgear, Outdoor Switchgear, Hybrid Switchgear, Modular Switchgear End User: Utilities, Industrial, Commercial, Renewable Energy Installation Type: Stationary, Mobile, Packaged, Pinned Technology: Air Insulated, Gas Insulated, Vacuum, Hybrid |
| Companies Covered | ABB Ltd., Schneider Electric SE, Siemens Energy AG, General Electric Company, Eaton Corporation, Mitsubishi Electric Corporation, Toshiba Corporation, Fuji Electric Co Ltd., Alstom SA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America High Voltage Switchgear Market Trends and Innovations
Intelligent monitoring systems and alternative insulation technologies are compressing the traditional 30-year replacement cycle for transmission switchgear while redefining how utilities negotiate service contracts and technology roadmaps.
Self-monitoring switchgear is automating fault prediction and maintenance scheduling through embedded partial discharge sensors and mechanical wear indicators. Mid-sized municipal utilities in the PJM Interconnection corridor are adopting these systems fastest, driven by staffing constraints and reliability-based rate recovery mechanisms. The technology is automating the transition from time-based to condition-based asset management, compressing OEM service revenue models toward predictive analytics subscriptions.
The EPA's SF6 emissions reporting mandate under the Greenhouse Gas Reporting Program is tightening leak detection and inventory tracking requirements for utilities operating gas-insulated switchgear above 17,000 pounds CO2-equivalent nameplate capacity. Equipment owners must now install calibrated monitoring systems and submit annual emissions data, accelerating capital planning for vacuum and hybrid-dielectric retrofits. Canadian utilities under parallel federal regulations are advancing coordinated North American procurement specifications for SF6-free alternatives.
Consolidated procurement consortia are displacing individual utility specification development across the Southwest Power Pool and Midcontinent ISO regions. State-affiliated buying cooperatives now aggregate demand for standardized 138 kV and 345 kV switchgear configurations, compressing vendor negotiation leverage and flattening price curves. This concentration is most visible among rural electric cooperatives in the Great Plains states, where pooled volumes qualify for tiered pricing previously reserved for investor-owned utilities.
North America High Voltage Switchgear Market Segmentation
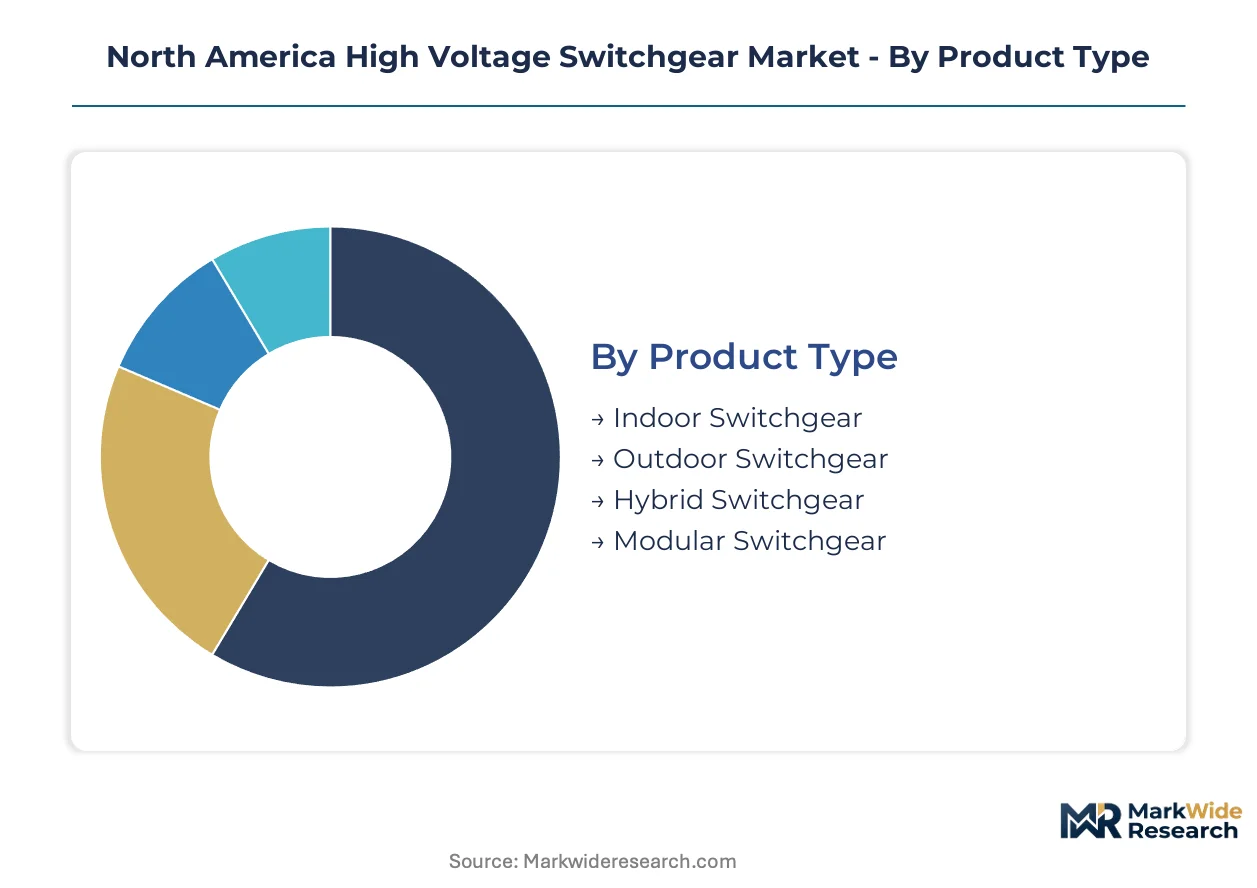
High voltage switchgear procurement patterns diverge sharply across installation environments, buyer sophistication, and regulatory exposure. Segment-level strategy requires matching dielectric technology to grid location constraints while calibrating service models to utility versus industrial maintenance capabilities.
Product Type:
Buyers in this category differentiate primarily by footprint constraints and environmental exposure tolerance.
- Indoor Switchgear:Metal-enclosed assemblies rated for controlled substation environments with climate-controlled housing and reduced clearances. Demand concentrates in dense urban load centers across the Northeast corridor where land scarcity drives vertical substation designs and EPA proximity rules restrict SF6 alternatives.
- Outdoor Switchgear:Weather-hardened enclosures engineered for temperature cycling, humidity, and particulate exposure without building infrastructure. Texas ERCOT expansion zones and California solar collector substations drive specifications for 60°C ambient operation and seismic qualification.
- Hybrid Switchgear:Configurations combining gas-insulated buswork with vacuum interruption modules to balance compactness against emissions compliance.
- Modular Switchgear:Factory-integrated skid-mounted assemblies enabling rapid deployment for temporary grid reinforcements or emergency restoration.
Volume sits with Outdoor Switchgear; growth tilts toward Hybrid Switchgear.
End User:
Procurement sophistication and compliance burden separate buyers across this dimension.
- Utilities:Investor-owned and municipal transmission operators with dedicated engineering staff, long-term asset management frameworks, and direct EPA reporting obligations. PJM Interconnection and California ISO members are consolidating specifications through pooled procurement consortia to compress vendor pricing.
- Renewable Energy:Offshore wind developers and utility-scale solar farm operators requiring collector substation switchgear with specialized fault-ride-through protocols and rapid islanding capabilities. Atlantic coast lease rounds from Massachusetts to North Carolina are expanding the fastest.
- Industrial:Heavy manufacturing and petrochemical facilities with captive substations prioritizing arc-flash containment and short-circuit withstand ratings over grid-code compliance.
- Commercial:Data center operators and large retail distribution hubs procuring switchgear as part of bundled electrical infrastructure packages with limited in-house high-voltage expertise.
Procurement volume clusters with Utilities; the steepest expansion trajectory belongs to Renewable Energy.
Installation Type:
Mobility requirements and foundation permanence distinguish deployment economics in this category.
- Stationary:Permanent concrete-pad installations with 30-40 year design life, engineered for seismic and wind loading per IEEE C37 standards. Dominates utility transmission substations across the United States and Canadian provinces with established grid infrastructure.
- Mobile:Trailer-mounted or containerized assemblies for emergency restoration, seasonal load relief, or construction-phase temporary service. Gulf Coast utilities deploy these for hurricane response and industrial turnaround maintenance.
- Packaged:Pre-integrated substation modules combining switchgear, transformers, and protection in single transport units for rapid field assembly.
- Pinned:Direct-buried or pole-mounted configurations for space-constrained urban distribution interconnections and rural tap-line extensions.
Stationary installations command installed base volume; Mobile configurations are gaining share fastest in storm-prone regions.
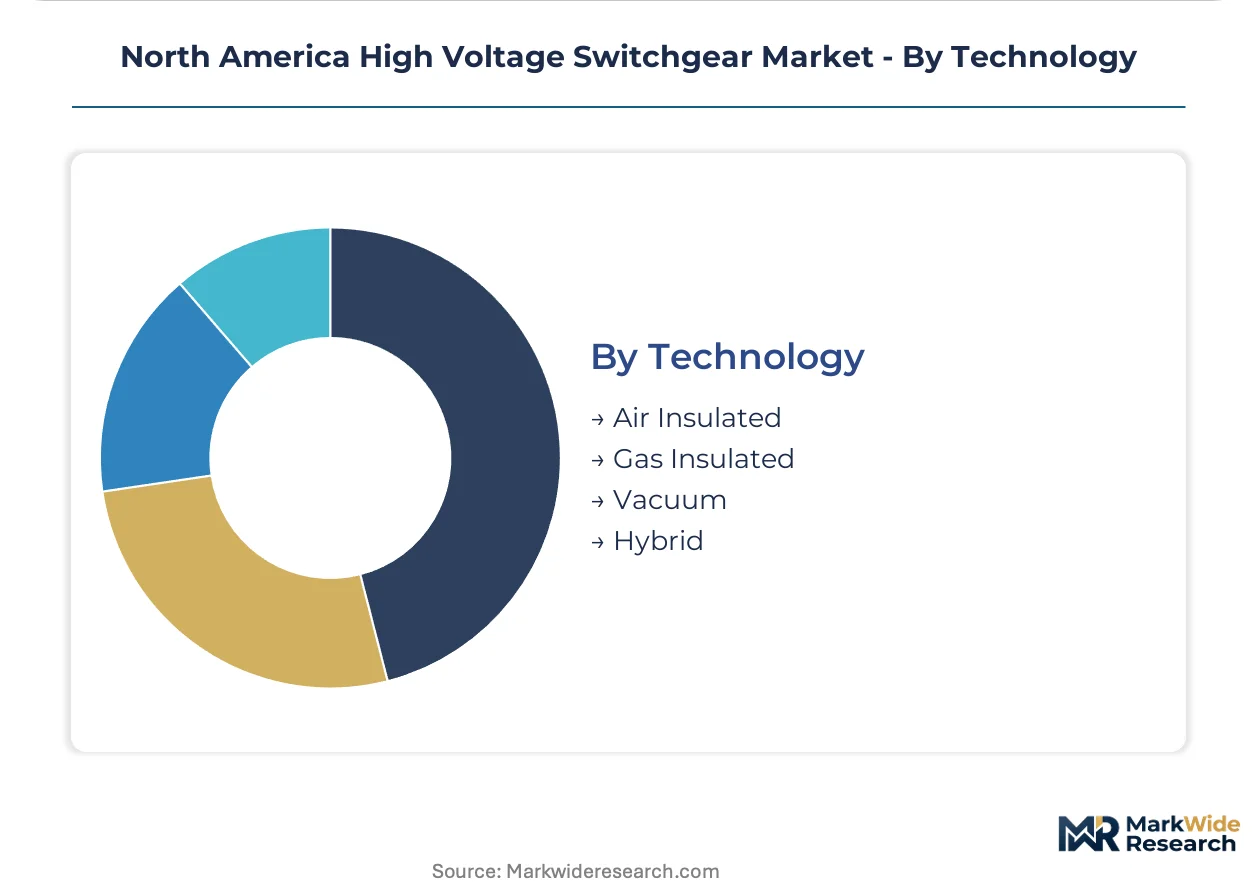
Technology:
Dielectric medium selection now hinges on emissions compliance timelines rather than pure technical performance.
- Gas Insulated:SF6-based systems offering the smallest footprint and highest reliability in contaminated environments, now facing accelerated retirement schedules under EPA phasedown mandates. Banked inventory in legacy United States utility fleets creates stranded asset exposure as leak monitoring requirements tighten.
- Vacuum:Interrupter technology eliminating greenhouse gas insulation entirely, with 145 kV+ designs now validated for transmission-grade applications. Canadian utilities are coordinating procurement specifications with United States counterparts under parallel federal regulations.
- Air Insulated:Conventional open-bus designs with largest footprint but lowest capital cost and simplest maintenance access.
- Hybrid:Systems combining vacuum interruption with reduced SF6 volumes or alternative gases to bridge performance and compliance requirements during transition periods.
Gas Insulated retains installed base dominance; Vacuum technology is climbing the fastest as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper-chromium contact material supply from Midwestern foundries anchors North American high voltage switchgear fabrication. Vacuum interrupter assembly concentrates near these feedstock sources before distribution to coastal transmission projects. Mexico's electrical steel and aluminum casting capacity provides complementary structural component supply.
United States
Texas ERCOT expansion and Atlantic offshore wind interconnection drive transmission-grade switchgear demand. EPA's SF6 phasedown under the American Innovation and Manufacturing Act accelerates vacuum technology validation for 345 kV applications. Houston and Corpus Christi host fabrication clusters serving Gulf Coast petrochemical and renewable collector substations.
Canada
Hydro-Québec and Ontario transmission reinforcement programs require cold-climate switchgear specifications for sub-zero operation. Federal SF6 emissions regulations parallel US EPA timelines, creating coordinated procurement standards across the border. Toronto and Montreal engineering centers concentrate vacuum interrupter design expertise for 145 kV+ systems.
Mexico
CFE's Baja California and Yucatán corridor modernization expands 230 kV and 400 kV substation requirements. NOM certification mandates shape supplier qualification for vacuum and hybrid switchgear technologies. Monterrey and Mexico City house breaker tank foundries and relay assembly operations serving domestic and export markets.
California
Utility-scale solar and battery storage interconnection in the Imperial Valley drives outdoor-rated switchgear specifications for 60°C ambient operation. California ISO reliability standards and CARB emissions rules tighten procurement beyond federal baselines. Los Angeles Basin substations concentrate hybrid switchgear deployment in dense urban footprints.
PJM Interconnection Corridor
Mid-Atlantic offshore wind lease areas from New Jersey to Virginia require 345 kV collector substation switchgear with marine environment ratings. FERC Order 2023 interconnection reforms compress project timelines for standardized grid-impact studies. Philadelphia and Baltimore utility procurement consortia aggregate demand for tiered pricing on 138 kV and 230 kV configurations.
North America High Voltage Switchgear Market Competitive Landscape
Capacity expansion dominates the current landscape as OEMs rebuild North American breaker and relay assembly lines to capture IRA domestic content bonuses. The vendor base concentrates among integrated electrical equipment conglomerates with captive transformer and protection relay portfolios. Three archetypes define competitive positioning: full-system integrators bundling switchgear with digital monitoring platforms, component specialists supplying vacuum interrupters to third-party assemblers, and regional fabricators serving utility maintenance and retrofit markets. M&A activity and geographic expansion represent the dominant competitive vectors as European and Japanese parents consolidate North American manufacturing footprints.
Among Swiss and German-based electrical equipment conglomerates, ABB Ltd. and Siemens Energy AG exemplify the full-system integrator archetype through integrated hardware-software positioning. General Electric Company anchors the domestic manufacturing tier with transformer-switchgear bundling capabilities for large transmission substations. These three occupy positions reflecting parent-company engineering heritage and regional market access strategies rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric SE |
| Siemens Energy AG |
| General Electric Company |
| Eaton Corporation |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Fuji Electric Co Ltd. |
| Alstom SA |
| Others |
Pricing and Supply Chain Analysis
Family-owned Midwestern foundries with multi-generational copper-chromium casting expertise anchor vacuum interrupter feedstock supply, translating captive technical knowledge into pricing power over breaker tank assemblies while resisting the margin compression that rolls through OEM utility contracts.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from transactional competitors, with integrated digital monitoring platforms commanding sustained pricing premiums against unbundled hardware-only bids. Price differentiation rests on EPA certification tier and after-sales service depth, with SF6-compliant vacuum systems carrying cost premiums over legacy gas-insulated alternatives. Cost compression in standard-grade outdoor switchgear is intensifying because pooled procurement consortia flatten volume discounts across the Southwest Power Pool. Rural electric cooperatives exhibit the highest price sensitivity due to constrained capital budgets, while investor-owned utilities prioritize reliability-based rate recovery over upfront cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Ohio and Pennsylvania-based copper-chromium foundries that feed vacuum interrupter assembly lines across the Great Lakes manufacturing corridor. Raw material dependencies center on electrical steel from Canada, permanent magnet alloys from domestic rare earth processors, and aluminum castings from Monterrey fabrication clusters. Supply chain risk concentrates in tariff exposure on Canadian electrical steel imports under evolving USMCA enforcement. Distribution runs through utility procurement consortia and EPC contractor channels serving transmission substation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America High Voltage Switchgear Market sits in a technology-transition phase as vacuum interruption systems displace SF6-insulated legacy installations under EPA phasedown mandates.
For Market Incumbents: Lock in captive supply of copper-chromium contact materials through backward integration into Midwestern foundry operations or long-term offtake agreements with family-owned casting specialists. Defend installed base revenue streams by accelerating predictive analytics platform deployment to capture recurring service contracts before third-party software vendors penetrate utility accounts. For New Entrants and Emerging Players: Enter via Mexico's CFE modernization corridors where NOM certification requirements create qualified supplier scarcity and incumbent presence remains thin. Target mobile switchgear configurations for Gulf Coast hurricane response applications, leveraging trailer-mounted assembly expertise from oilfield services supply chains to bypass stationary substation engineering talent bottlenecks. For Investors and Strategic Acquirers: Distressed-cycle entries favor vacuum interrupter engineering specialists in Toronto and Montreal research clusters where specialized 145 kV+ design expertise concentrates at legacy manufacturer spin-outs. Long-term viability hinges on positioning ahead of EPA compliance deadline clustering. The signal to watch is accelerated utility RFP issuance for SF6-free alternatives as annual emissions reporting thresholds tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Acquisition | Captive copper-chromium supply secures margin control against commodity volatility in vacuum interrupter manufacturing. |
| Digital Twin Platform Launch | Edge-computing sensor integration enables recurring software revenue from PJM Interconnection municipal utilities. |
| IRA Domestic Content Certification | North American assembly qualification unlocks production tax credit adders for renewable collector substation projects. |
| Mexico NOM Certification Investment | Regulatory qualification opens CFE transmission corridors in Baja California and Yucatán grid reinforcement programs. |
| Mobile Switchgear Product Line | Trailer-mounted assemblies address Gulf Coast hurricane response demand and industrial turnaround maintenance cycles. |
Research Methodology
Document review covered FERC interconnection dockets, EPA Greenhouse Gas Reporting Program filings, and NERC reliability standards, complemented by interviews with utility transmission planning officers, EPC contractor procurement leads, vacuum interrupter engineering directors, and aftermarket service heads at OEMs. Secondary validation drew from EIA generation interconnection queues, Canadian federal emissions regulations, and CFE infrastructure investment disclosures. Bottom-up unit economics triangulated against top-down grid investment forecasts.
Cross-referencing historical deployment patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include dielectric technology type, installation environment, end-user category, and regional regulatory cluster. CAGRs were derived from utility capital expenditure trajectories, renewable interconnection queue velocities, and equipment replacement cycle compression under EPA compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated SF6 phasedown schedules or copper price spike scenarios. Forecasts reflect documented assumptions about interconnection reform implementation pace and domestic manufacturing capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Servo Valves Market
Valves
Safety Valve Test Benches Market
Valves
Pipeline Equipment Market
Valves
Insulation Flanges Market
Valves
Fin Tube Market
Valves
Valve Seat Inserts Market
Valves
Subsea Valves Market
Valves
Portable Valve Actuator Market
Valves
Middle East and Africa Machined Seals Market
Valves
Industrial Safety Valves Market
Valves
Global Fluid Management Systems Market
Valves
Global Valve Positioners Market
Valves
Global Valves in Chemical Market
Valves
Global Automotive Valves Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Sanitary Valves Market