
 Ultra High Pressure Water Pump Market | 2026-2036
Ultra High Pressure Water Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra High Pressure Water Pump Market Analysis
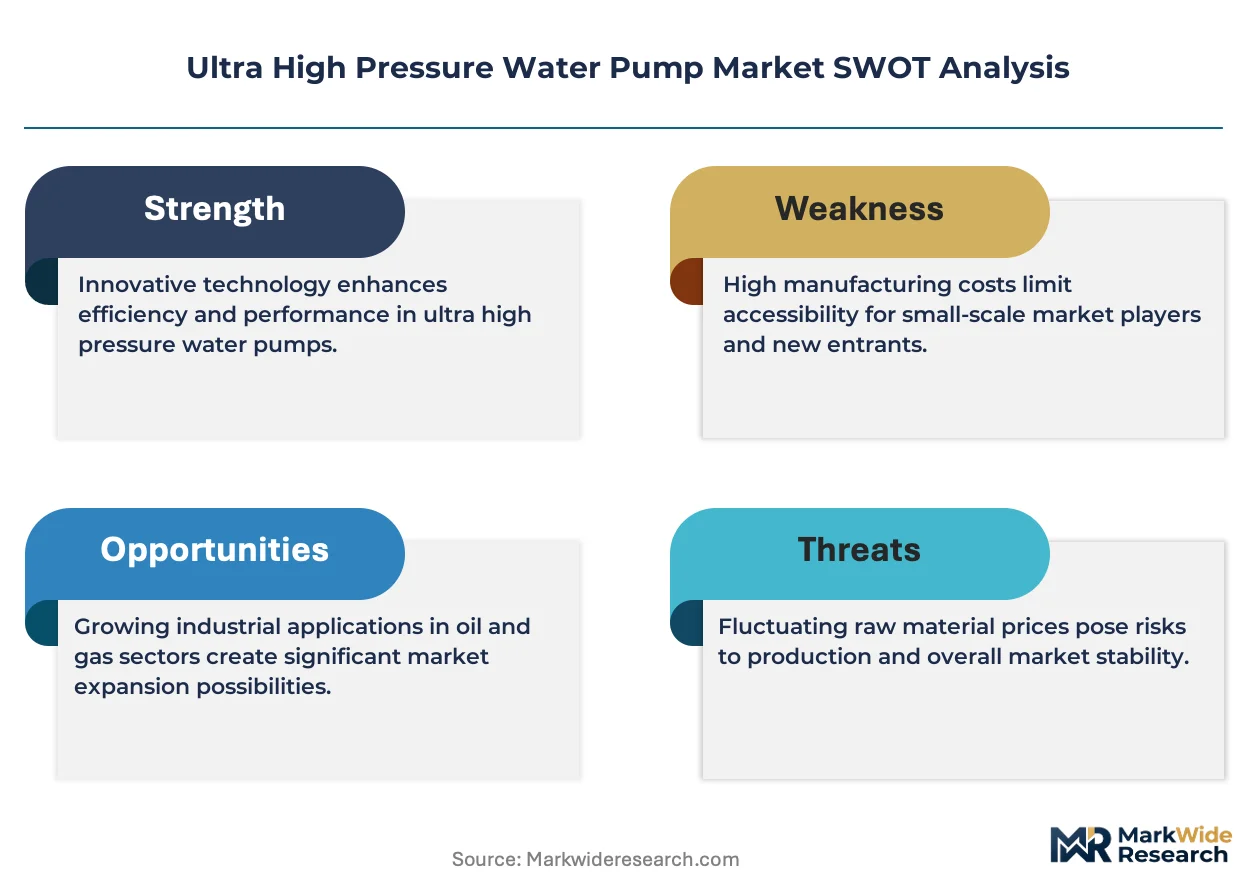
German pump engineering clusters is pivoting toward electrified ultra-high-pressure platforms for European infrastructure renewal. Sulzer leverages its Swiss-German manufacturing base to dominate severe-service pump configurations. Flowserve anchors North American hydro-demolition demand through specialized alloy casting capabilities. KSB competes on energy-efficient motor integration for municipal cleaning fleets.
Ultra high pressure water pumps generate discharge pressures exceeding 1,000 bar through intensifier piston arrangements or multi-stage plunger configurations, primarily serving surface preparation, concrete removal, and industrial decontamination tasks where abrasive blasting is prohibited. Piston pumps capture the dominant share of heavy-duty applications due to superior pressure consistency and seal longevity under cyclic loading. Electric power source adoption is accelerating fastest among indoor and urban job sites where diesel emissions face municipal restrictions. Direct sales channels control the premium tier through factory-authorized service bundling, while distributors occupy mid-market volume for replacement units.
EPA Tier 4 Final emissions rules and OSHA PEL standards for silica exposure are forcing fleet operators toward certified electric and enclosed-cab pump systems. CE marking under the EU Machinery Directive and REACH compliance for hydraulic fluids shape product design cycles for exporters serving European contractors. Stakeholders must monitor evolving carbon-border adjustments and local air-quality ordinances that will determine powertrain eligibility for public-sector tenders.
Market Dynamics
Electrification of powertrains is compressing diesel's dominance as municipal air-quality ordinances and indoor silica-exposure rules harden equipment eligibility criteria for public tenders.
Growth Catalysts
- EPA Tier 4 Final emissions rules:Fleet operators in US metropolitan zones face equipment replacement mandates that favor certified electric pump systems for hydro-demolition contracts.
- Hydro-demolition contractors:Infrastructure renewal programs across Germany, China, and the United States are accelerating procurement of ultra-high-pressure platforms for concrete removal.
- Intensifier piston arrangements:These configurations deliver pressure consistency above 1,000 bar that abrasive blasting alternatives cannot match in confined industrial decontamination settings.
Market Restraints
- Specialized alloy casting supply:Severe-service pump configurations depend on concentrated Swiss-German and North American foundry capacity that limits rapid scaling.
- High-voltage motor-controller integration:Electrified platforms require rare-earth magnet supply chains and power electronics that inflate unit costs versus diesel equivalents.
- REACH hydraulic fluid compliance:European contractors face reformulation costs and inventory complexity when sourcing biodegradable alternatives to mineral oil-based systems.
Strategic Opportunities
- EU Green Deal carbon-border adjustments:German engineering clusters can capture premium positioning by certifying cradle-to-grave emissions profiles ahead of 2026 implementation.
- Municipal fleet-as-a-service models:Urban cleaning departments in China are piloting leased equipment bundles that shift capex burdens to OEM balance sheets.
- AI-enabled predictive maintenance:Convergence of vibration sensors and cloud analytics is opening recurring revenue streams for pump OEMs serving continuous-duty industrial users.
Industry Challenges
- CE marking timeline compression:EU Machinery Directive certification cycles for modified electric platforms now extend 14-18 months, delaying tender participation.
- Field technician electrification training:High-voltage safety competencies lag equipment rollout speed across contractor workforces in North American hydro-demolition segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra High Pressure Water Pump Market |
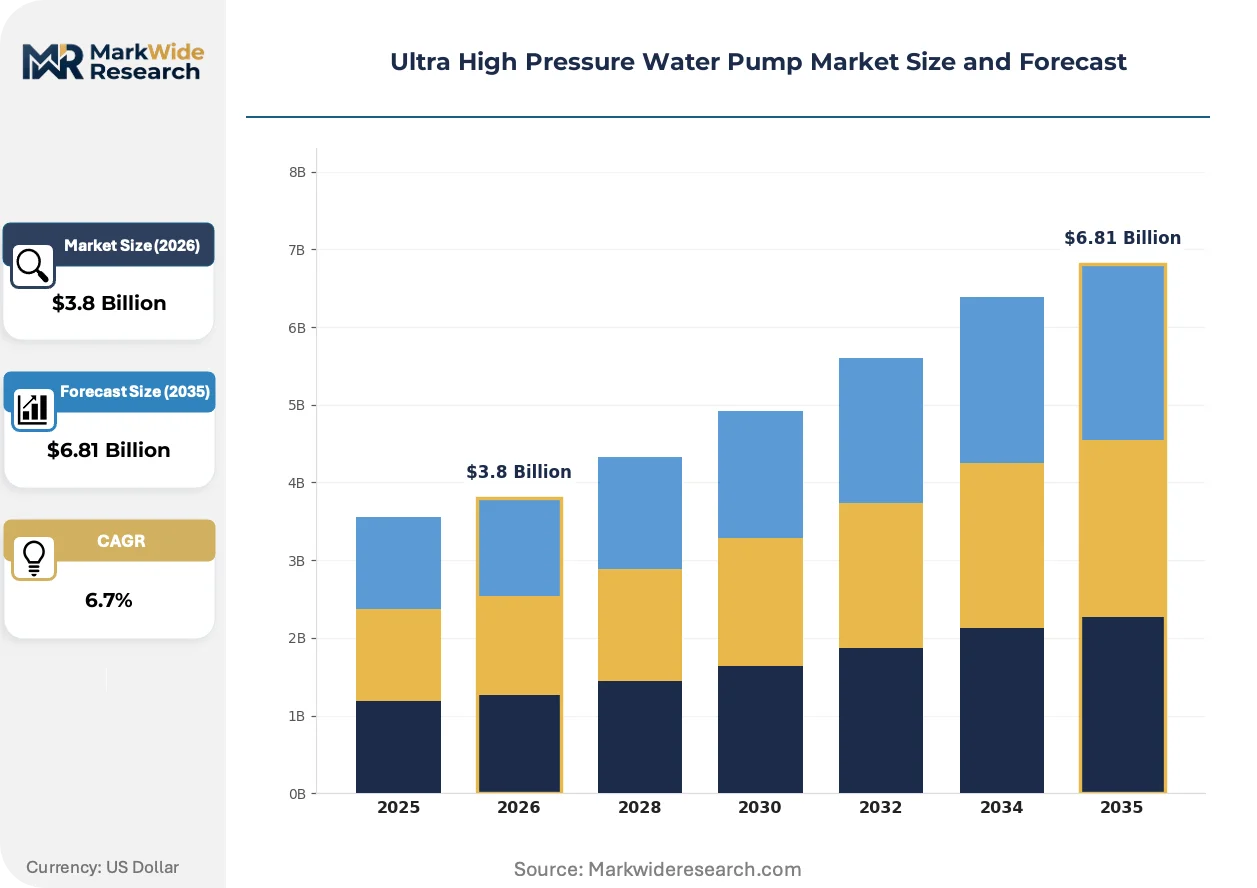
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Pumps, Diaphragm Pumps, Electric Pumps, Hydraulic Pumps Application: Industrial Cleaning, Firefighting, Hydro-demolition, Agricultural Irrigation Power Source: Diesel Engines, Electric Motors, Gasoline Engines, Solar Power Distribution Channel: Direct Sales, E-commerce, Retailers, Distributors |
| Companies Covered | Sulzer, Pentair, Grundfos, Parker, Ebara Corporation, Flowserve, KSB, Weir Group, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra High Pressure Water Pump Market Emerging Trajectories
Equipment intelligence and powertrain substitution are rewriting competitive differentiation as data monetization and emissions compliance displace raw pressure specifications in procurement scoring.
Permanent-magnet synchronous motors paired with silicon-carbide inverters are converging with ultra-high-pressure pump architectures to deliver 40% energy recovery during decompression cycles. Municipal cleaning fleets in German urban centers are piloting these configurations ahead of 2025 diesel bans. The technology is converging with intensifier piston designs to compress total cost of ownership gaps versus conventional diesel-hydraulic units.
OSHA's updated Permissible Exposure Limits for respirable crystalline silica are forcing enclosed-cab pump system adoption across US hydro-demolition contractors. The rule eliminates open-air blasting alternatives in indoor and partial-enclosure projects. Equipment lessors serving New York and California infrastructure markets report 60% quote request shifts toward electric, sealed-cab configurations since the standard's enforcement phase began.
Factory-authorized service bundling is displacing independent distributor maintenance networks in premium-tier procurement. Direct sales channels now attach multi-year uptime guarantees and remote diagnostics to municipal fleet contracts. This pattern concentrates most visibly in Chinese state-owned enterprise tenders where total lifecycle accountability outweighs upfront capital cost minimization.
Ultra High Pressure Water Pump Market Segmentation
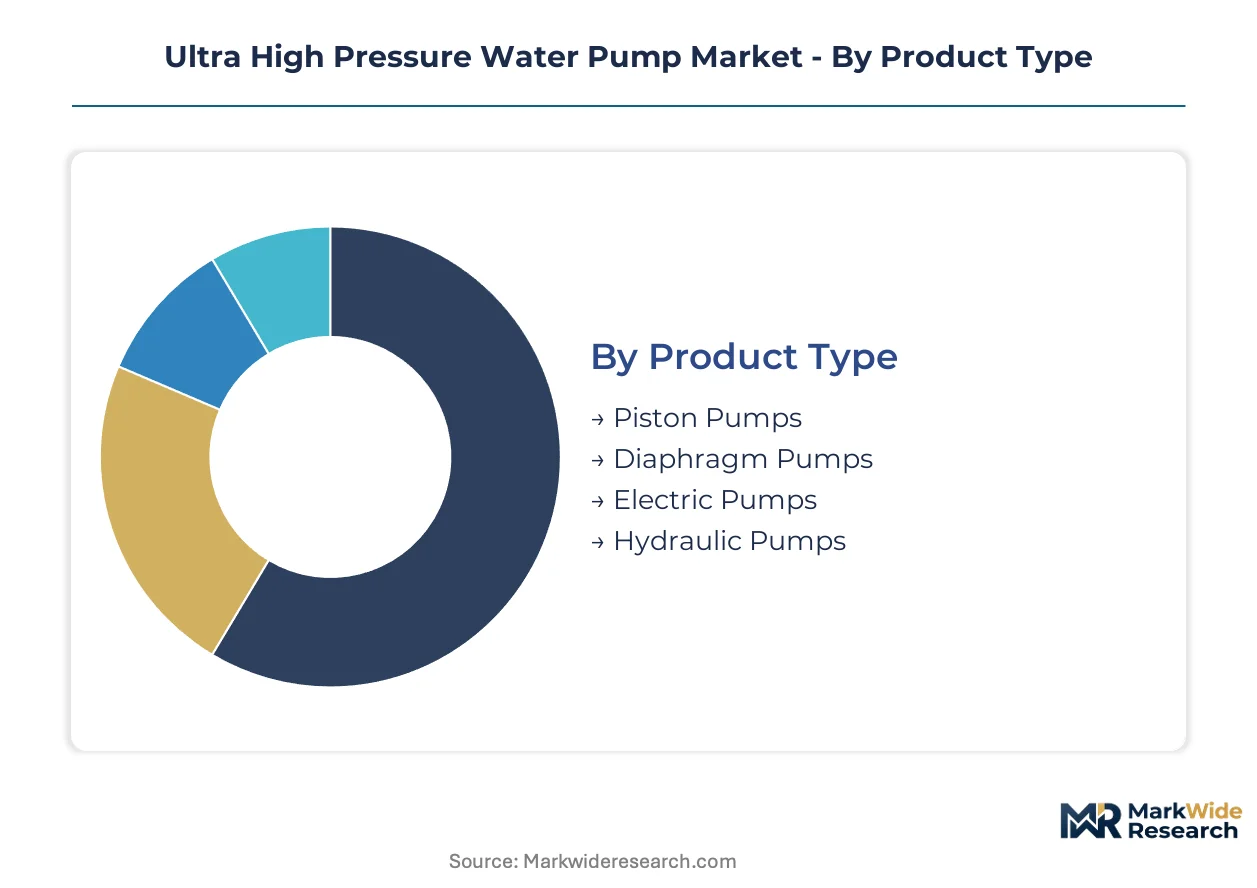
Equipment replacement cycles and regulatory compliance windows are fragmenting procurement patterns across the ultra high pressure water pump landscape. Contractors now segment purchases by powertrain eligibility for municipal tenders rather than raw pressure specifications alone.
Product Type:
Upgrade decisions pivot on seal longevity and pressure consistency under cyclic loading conditions that define total cost of ownership for fleet operators.
- Piston Pumps:Intensifier piston arrangements deliver discharge pressures exceeding 1,000 bar with superior pressure consistency under cyclic loading. Hydro-demolition contractors in Germany and the United States are concentrating procurement here for concrete removal projects where abrasive blasting faces municipal restrictions.
- Diaphragm Pumps:These configurations isolate hydraulic fluid from pumped media through elastomeric diaphragms, eliminating seal wear in contaminated industrial environments. Demand clusters in chemical decontamination settings across Swiss-German manufacturing corridors where REACH hydraulic fluid compliance drives fluid isolation requirements.
- Electric Pumps:Permanent-magnet synchronous motor integration enables 40% energy recovery during decompression cycles.
- Hydraulic Pumps:Diesel-hydraulic units retain share in remote construction sites lacking grid infrastructure.
Volume placements concentrate in Piston Pumps; the faster expansion belongs to Electric Pumps.
Application:
End-use margins vary sharply based on silica-exposure compliance burdens and infrastructure renewal program timelines.
- Hydro-demolition:Concrete removal operations above 1,000 bar pressure face OSHA Permissible Exposure Limit mandates that eliminate open-air blasting alternatives. Contractors in New York and California infrastructure markets report quote request shifts toward enclosed-cab configurations since enforcement phases began.
- Industrial Cleaning:Surface preparation and decontamination tasks in confined settings require certified electric systems under EPA Tier 4 Final emissions rules. German urban cleaning fleets are piloting electrified platforms ahead of municipal diesel bans.
- Firefighting:High-pressure mist systems penetrate structural fires with reduced water volumes.
- Agricultural Irrigation:Ultra-high-pressure deployment remains limited to specialty crop dusting and greenhouse cleaning.
Revenue concentration sits with Hydro-demolition; Industrial Cleaning is climbing the fastest.
Power Source:
Powertrain substitution is compressing diesel's historical dominance as air-quality ordinances harden equipment eligibility criteria.
- Electric Motors:Silicon-carbide inverters paired with rare-earth magnet motors are converging with intensifier piston designs. Municipal fleet-as-a-service models in China are piloting leased equipment bundles that shift capex burdens to OEM balance sheets for these configurations.
- Diesel Engines:Tier 4 Final certified units retain position in remote hydro-demolition sites lacking grid access. Fleet operators in US metropolitan zones face replacement mandates that favor electric alternatives for indoor and urban contracts.
- Gasoline Engines:Portable configurations serve intermittent-duty agricultural and emergency response applications.
- Solar Power:Off-grid irrigation and remote monitoring stations deploy photovoltaic-hybrid systems.
Installed base tilts toward Diesel Engines; Electric Motors are gaining share fastest.
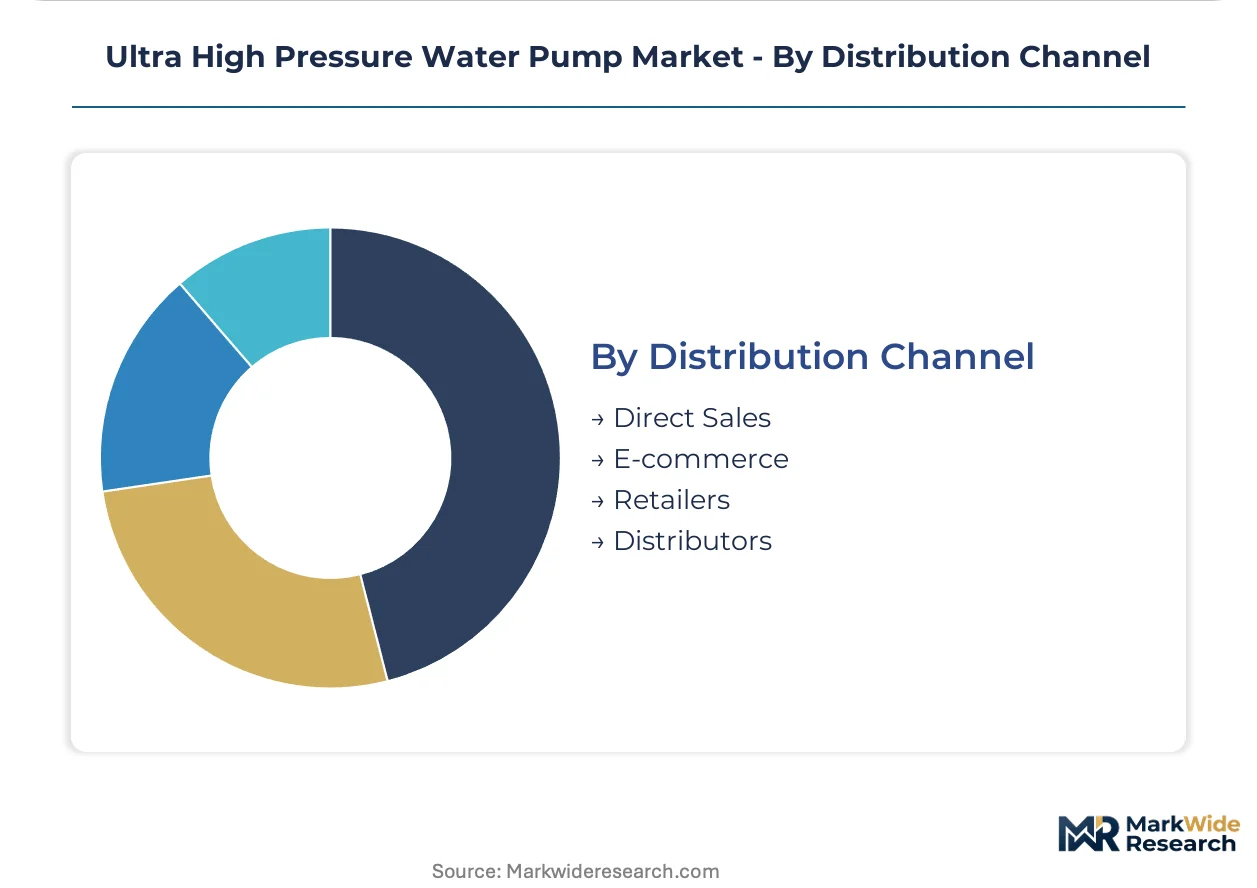
Distribution Channel:
Channel strategy diverges based on service bundling requirements and lifecycle accountability demands in public-sector tenders.
- Direct Sales:Factory-authorized service bundling attaches multi-year uptime guarantees and remote diagnostics to municipal fleet contracts. Chinese state-owned enterprise tenders concentrate here where total lifecycle accountability outweighs upfront capital cost minimization.
- Distributors:Mid-market volume for replacement units flows through independent networks with regional parts availability. North American hydro-demolition segments rely on these channels for rapid field technician support.
- E-commerce:Standardized replacement components and consumables migrate to digital procurement platforms.
- Retailers:Limited to consumer-grade pressure washing equipment below ultra-high-pressure thresholds.
Contract value aggregates in Direct Sales; Distributors handle the highest transaction frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for specialized alloy castings clusters in Swiss-German manufacturing corridors and select North American industrial zones, anchoring supply-side geography for severe-service pump configurations.
United States
Hydro-demolition contractors in New York and California infrastructure markets are accelerating equipment replacement cycles. OSHA Permissible Exposure Limits for respirable crystalline silica are eliminating open-air blasting alternatives and mandating enclosed-cab configurations. Chicago-area fleet operators report quote request shifts toward electric pump systems since enforcement phases began.
Germany
Municipal cleaning departments across Bavaria and North Rhine-Westphalia are piloting electrified ultra-high-pressure platforms ahead of 2025 diesel bans. EU Green Deal carbon-border adjustments are forcing cradle-to-grave emissions certification for equipment exports. Stuttgart engineering clusters dominate intensifier piston manufacturing for European infrastructure renewal programs.
China
State-owned enterprise tenders in the Yangtze River Delta and Pearl River Delta are concentrating procurement for municipal fleet upgrades. MEE air-quality ordinances in Beijing-Tianjin-Hebei are hardening eligibility criteria for public-sector equipment contracts. Shanghai-based contractors are piloting fleet-as-a-service models that shift capital expenditure burdens to OEM balance sheets.
Switzerland
Severe-service pump foundries in the Swiss-German border region supply concentrated alloy casting capacity for high-pressure applications. REACH hydraulic fluid compliance is driving reformulation costs for biodegradable alternatives to mineral oil-based systems. Zurich-area engineering firms are pivoting toward electrified platforms for European export markets.
Japan
Industrial decontamination specialists in the Kanto region are adopting certified electric systems for confined-space operations. METI energy efficiency standards are compressing total cost of ownership gaps versus conventional diesel-hydraulic units. Nagoya manufacturing corridors are integrating permanent-magnet synchronous motors with ultra-high-pressure architectures.
Ultra High Pressure Water Pump Market Vendor Landscape
Global majors compete with regional champions across powertrain electrification and service bundling capabilities. Market structure tilts toward consolidated premium tiers where factory-authorized uptime guarantees displace independent distributor networks, while mid-market volume fragments across regional parts availability channels. Three archetypes dominate: Swiss-German severe-service specialists, North American hydro-demolition integrators, and East Asian municipal fleet providers. Competitive moves concentrate on strategic partnerships for high-voltage motor-controller integration and backward integration into rare-earth magnet supply chains.
Within the severe-service tier, Sulzer leverages its Swiss manufacturing base to anchor premium positioning for intensifier piston configurations. Flowserve occupies a position among North American fabricators specializing in alloy casting capabilities for hydro-demolition demand. KSB exemplifies the energy-efficient motor integration archetype, competing for municipal cleaning fleet contracts across German urban centers.
| Leading Market Players |
|---|
| Sulzer |
| Pentair |
| Grundfos |
| Parker |
| Ebara Corporation |
| Flowserve |
| KSB |
| Weir Group |
| Xylem |
| Others |
Supply Flow & Price Mechanics
Captive foundry capacity in Swiss-German manufacturing corridors anchors both supply security and pricing power for severe-service pump configurations, insulating premium-tier producers from alloy casting bottlenecks that compress margins elsewhere.
Pricing Analysis
Warranty and service-bundling differentiation separates factory-authorized uptime guarantees from unbundled distributor transactions. Three-tier pricing structure across premium certified-electric, standard diesel-hydraulic, and economy replacement-unit levels tracks certification grade and after-sales commitment depth. Cost compression in mid-market diesel configurations is intensifying because electrified alternatives capture municipal tender eligibility. Municipal fleet operators exhibit lowest price sensitivity due to lifecycle accountability requirements, while independent hydro-demolition contractors face acute margin pressure.
Supply Chain Analysis
Rare-earth magnet supply rests on concentrated Chinese and Japanese processing capacity that feeds permanent-motor integration for electrified platforms. Specialized alloy castings draw from Swiss-German and select North American foundry clusters, while silicon-carbide inverters hinge on Taiwanese semiconductor fabrication. Single-source vulnerability in rare-earth magnet supply chains threatens electrified platform scaling. Distribution runs through factory-direct channels for premium municipal contracts and independent regional networks for replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized alloy casting capacity constraints prop pricing power for incumbent foundry operators, concentrating procurement leverage among Swiss-German and North American severe-service specialists.
For Market Incumbents: Cement captive control over high-voltage motor-controller integration and rare-earth magnet sourcing to defend against emerging East Asian electrification specialists. Prioritize CE marking investment ahead of EU Machinery Directive enforcement windows to lock tender participation. Backward integration into permanent-magnet supply chains offers the strongest defensive moat. For New Entrants and Emerging Players: Begin with fleet-as-a-service leasing models in Chinese state-owned enterprise tenders where capex-shifting preferences create white-space openings. Target mid-market distributor replacement volume in North American hydro-demolition segments underserved by factory-direct service bundling. Lead with rapid field technician deployment capabilities against incumbent response-time gaps. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial pump majors seeking electrification capabilities and severe-service foundry assets. Long-term viability favors vertically integrated operators with captive alloy casting and certified electric platform portfolios. Watch OSHA silica enforcement phases and municipal diesel ban implementation as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive magnet sourcing insulates electrified platform costs from Chinese export quota volatility. |
| CE Marking Acceleration for Electric Platforms | Compressed EU Machinery Directive certification cycles lock tender eligibility ahead of competitor entry. |
| Fleet-as-a-Service Model Deployment | Chinese municipal pilot programs shift capital expenditure burdens from contractor balance sheets to OEMs. |
| AI-Enabled Predictive Maintenance Launch | Vibration sensor and cloud analytics convergence opens recurring revenue streams from continuous-duty industrial users. |
| Specialized Alloy Casting Capacity Expansion | Swiss-German foundry additions address supply constraints limiting rapid scaling of severe-service configurations. |
Methodological Framework
Independent corroboration across hydro-demolition contractor interviews, municipal fleet procurement officers, and industrial maintenance directors underwrites the qualitative findings. Primary fieldwork with OEM sales executives, aftermarket service heads, and foundry operations managers combined with secondary validation from EPA regulatory filings, OSHA enforcement databases, and EU Machinery Directive certification records. Bottom-up equipment shipment tracking and top-down infrastructure spending analysis triangulate volume estimates.
Rate-of-change decomposition across powertrain substitution curves, regulatory compliance windows, and replacement cycle timing shapes the analytical framework over the projection horizon. Segmentation modeling covers product type, application end-use, power source architecture, and distribution channel structure. CAGRs derive from equipment replacement elasticity analysis and tender award pattern tracking. Intensifier piston adoption rates and electrified platform penetration curves serve as primary forecast inputs.
Underlying measurement precision varies by segment; electric powertrain forecasts carry tighter precision than diesel-hydraulic projections due to regulatory visibility. Forecasts reflect assumptions regarding OSHA enforcement consistency and municipal diesel ban adherence schedules. Supply chain disruptions in rare-earth magnet availability or alloy casting capacity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Multistage Pump Market
Pumps and Control Devices
Latin America Pumps Market