
 Marine Low-Voltage Battery Market | 2026-2036
Marine Low-Voltage Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Low-Voltage Battery Market Insights
Electric propulsion in harbor craft and short-sea shipping is realigning the marine low-voltage battery landscape. Corvus Energy dominates integrated maritime energy storage with factory-certified module assemblies. Leclanché SA specializes in high-cycle lithium-ion architectures for hybrid retrofit projects. Saft SA anchors defense and commercial marine contracts through its IEC-qualified cell platforms.
Marine low-voltage batteries store and discharge electrical energy at nominal voltages typically below 150V DC, employing lithium iron phosphate or absorbed glass mat chemistries in modular rack configurations sealed against salt spray ingress per IEC 60529. These systems power auxiliary loads, electric thrusters, and hotel services aboard vessels where full high-voltage architecture remains uneconomical. Lithium-ion leads newbuild installations due to energy density advantages and declining cell costs, while lead acid retains aftermarket replacement demand in price-sensitive recreational segments. Electric propulsion applications command premium pricing but require shore charging infrastructure co-investment. Solar charging integration grows fastest among charging methods as deck-mounted photovoltaic arrays supplement generator runtime on long-duration voyages.
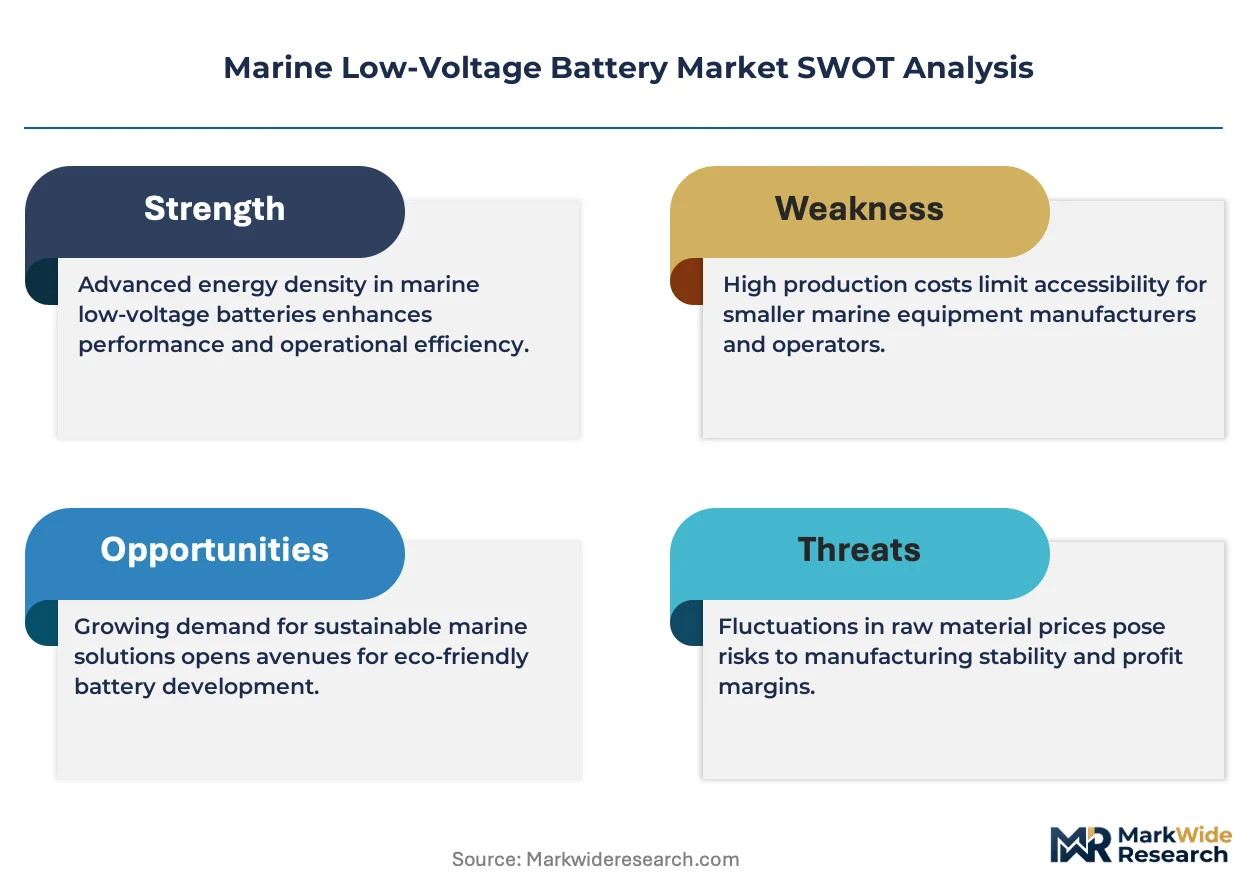
The International Electrotechnical Commission's IEC 62619 standard for lithium cell safety in industrial applications shapes product certification requirements, while EU MRV and IMO DCS emissions frameworks push commercial operators toward electrified auxiliary power. Norway's NOx fund and Germany's BAFA maritime innovation grants directly subsidize battery-hybrid conversions, tightening compliance windows for conventional diesel fleets. Stakeholders must weigh cell chemistry selection against port infrastructure availability and residual vessel service life when evaluating retrofit economics.
Market Dynamics
Harbor tug and coastal ferry electrification is compressing diesel auxiliary demand as port electrification mandates force fleet operators toward lithium-ion architectures before residual vessel service life expires.
Growth Catalysts
- NOx Fund Subsidies:Norway's maritime innovation grants cover up to 40% of battery-hybrid conversion costs for harbor craft, accelerating payback periods for fleet operators.
- IEC 62619 Certification:Standardized lithium cell safety protocols reduce insurer risk premiums for electric propulsion installations, expanding addressable vessel categories.
- Inland Waterway Decarbonization:Germany's BAFA funding and Netherlands port authority mandates create procurement pull for modular low-voltage systems in short-sea shipping.
Market Restraints
- Lithium Carbonate Volatility:Cell material input costs swing 30-50% annually, squeezing module assembler margins and deterring long-term vessel retrofit contracts.
- Shore Infrastructure Gaps:Southeast Asian port electrification lags vessel conversion timelines, stranding battery investments where charging capacity remains undeveloped.
- Lead Acid Replacement Cycles:Price-sensitive recreational boating segments extend absorbent glass mat service life through 7-10 year maintenance protocols, delaying lithium penetration.
Strategic Opportunities
- Deck-Mounted Solar Integration:Photovoltaic array suppliers are partnering with battery system integrators to offer generator-reduction packages for long-duration voyages.
- Defense Marine Electrification:Naval auxiliary vessel programs in Germany and France specify IEC-qualified low-voltage architectures for reduced acoustic signatures.
- Second-Life Automotive Cells:Repurposed electric vehicle lithium iron phosphate modules enter marine retrofit channels at 40-60% of new cell cost.
Industry Challenges
- Marine Electrical Engineering Talent:Certified technicians for salt-sealed rack installations and thermal management commissioning command 35-50% wage premiums over automotive battery specialists.
- IEC 62619 Testing Timelines:Cell-level abuse testing and system-level fault propagation studies extend product certification cycles 18-24 months, delaying new chemistry introductions.
- Legacy Diesel Integration:Hybrid retrofit projects require custom power electronics to synchronize battery discharge profiles with existing genset governor response characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Low-Voltage Battery Market |
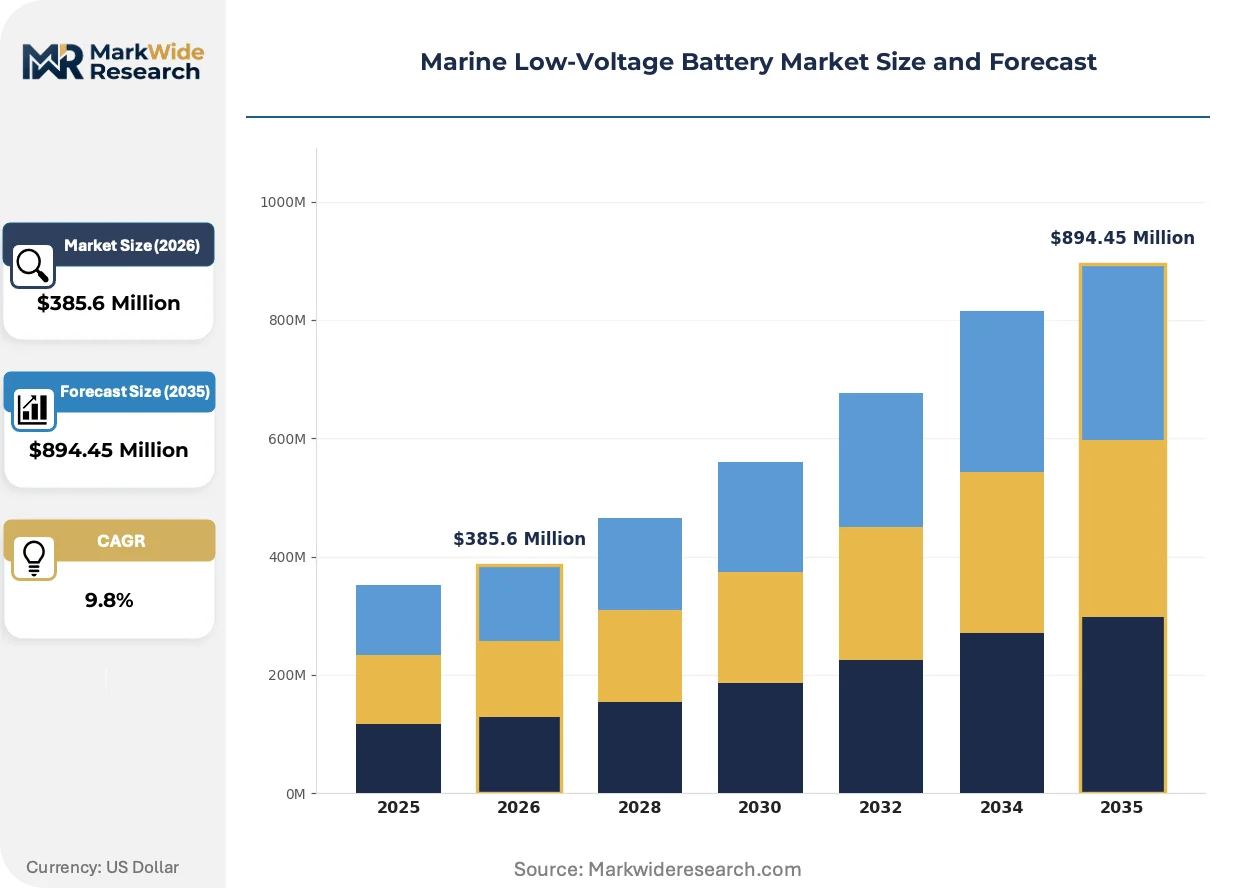
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $894.45 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead Acid, Lithium-ion, AGM, Gel Application: Marine Vessels, Yachts, Fishing Boats, Electric Propulsion Charging Method: Solar Charging, Shore Power, Generator Charging, Wind Power End User: Commercial Operators, Recreational Users, Fleet Services, Government Agencies |
| Companies Covered | Corvus Energy, Leclanché SA, Siemens Energy, EST Floattech, Saft SA, EnerSys, Toshiba Corporation, Victron Energy, Mastervolt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Low-Voltage Battery Market Trends and Innovations
Cell chemistry advancement and modular thermal architecture are compressing system footprints while regulatory pressure on harbor emissions accelerates procurement timelines for integrated energy storage.
Lithium iron phosphate chemistry is integrating fire-suppression-integrated module designs that eliminate external cooling loops. Harbor tug operators in Rotterdam and Singapore specify these sealed rack configurations to reduce engine room footprint by 40% versus lead acid banks. The technology is integrating with shore charging infrastructure investments, forcing terminal operators to coordinate vessel scheduling with grid capacity.
EU Green Deal maritime provisions and IMO DCS emissions frameworks are tightening compliance windows for conventional diesel auxiliary power. Commercial operators face 2025-2027 reporting deadlines that expose fuel consumption inefficiencies. Short-sea shipping routes between Netherlands, Germany, and Denmark show earliest retrofit response as fleet managers front-load battery investments to secure yard slots.
Buyers are consolidating procurement around factory-certified module assemblies rather than component sourcing. Integrated system warranties covering cells, battery management, and thermal regulation displace piecemeal supplier arrangements. Norwegian ferry operators and German inland waterway cooperatives lead this specification shift, demanding single-point accountability for 10-year service life guarantees.
Marine Low-Voltage Battery Market Segmentation
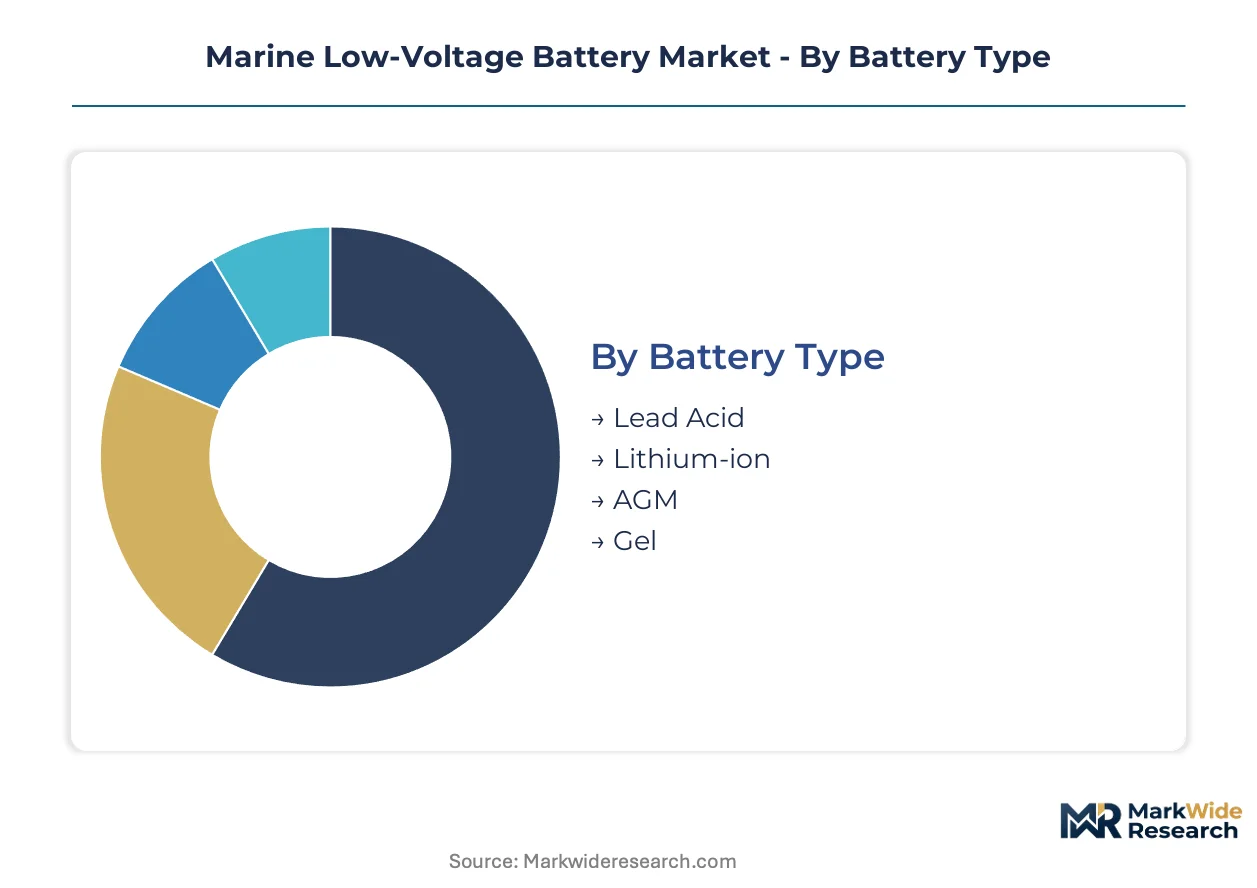
Marine low-voltage battery procurement divides across technical specifications, operational profiles, and regulatory exposure. Segmentation clarity guides vessel operators through certification requirements and total cost of ownership calculations.
Battery Type:
IEC 62619 certification burdens fall heaviest on lithium-ion architectures, while lead acid and absorbed glass mat systems navigate less stringent safety protocols for recreational installations.
- Lithium-ion:Lithium iron phosphate cells dominate newbuild harbor craft and coastal ferry electrification, achieving energy densities above 160 Wh/kg with integrated thermal management. Norwegian fleet operators specify these systems for hybrid retrofits subsidized by the NOx Fund, though cell material volatility squeezes assembler margins.
- Lead Acid:Flooded and valve-regulated designs persist in price-sensitive recreational segments where 7-10 year replacement cycles delay lithium conversion. Southeast Asian fishing fleets extend service life through aggressive maintenance protocols.
- AGM:Absorbed glass mat construction suits engine-starting and shallow-cycle auxiliary loads on mid-size yachts.
- Gel:Thixotropic electrolyte formulations tolerate deep discharge cycling in sailboat house banks.
Lithium-ion sits at the top of the volume ranking, with AGM climbing the fastest among legacy chemistries as a bridge technology for hybrid conversions.
Application:
Application segmentation tracks electrification depth, from hotel load supplementation to full propulsion replacement, with shore infrastructure availability determining feasibility at each tier.
- Electric Propulsion:Harbor tugs and short-sea ferries in Rotterdam, Hamburg, and Singapore specify 100-150V DC architectures for zero-emission maneuvering. These installations command premium pricing but require terminal co-investment in high-capacity charging.
- Marine Vessels:Commercial cargo and passenger ships deploy low-voltage systems for auxiliary power and dynamic positioning. German inland waterway operators front-load battery investments to secure yard slots before EU MRV reporting deadlines.
- Yachts:Superyacht builders integrate modular lithium racks for silent hotel services at anchor.
- Fishing Boats:Deck-mounted photovoltaic arrays supplement generator runtime on long-duration voyages.
Marine Vessels captures the largest installed base, with Electric Propulsion gaining share fastest as port electrification mandates tighten.
Charging Method:
Charging infrastructure segmentation reflects grid dependency versus energy autonomy trade-offs, with solar integration expanding where shore power remains undeveloped.
- Solar Charging:Deck-mounted photovoltaic arrays partner with battery integrators to offer generator-reduction packages. Long-duration voyages across Southeast Asian archipelagos favor this approach where port electrification lags vessel conversion timelines.
- Shore Power:High-amperage connections at Norwegian, Dutch, and German terminals enable rapid turnaround for electric harbor craft. Terminal operators coordinate vessel scheduling with grid capacity constraints.
- Generator Charging:Diesel-electric hybrid architectures persist where shore infrastructure gaps strand pure battery investments.
- Wind Power:Small-scale turbine integration supplements charging on blue-water sailing vessels.
Shore Power anchors commercial fleet procurement, with Solar Charging expanding most quickly among charging methods for autonomous operations.
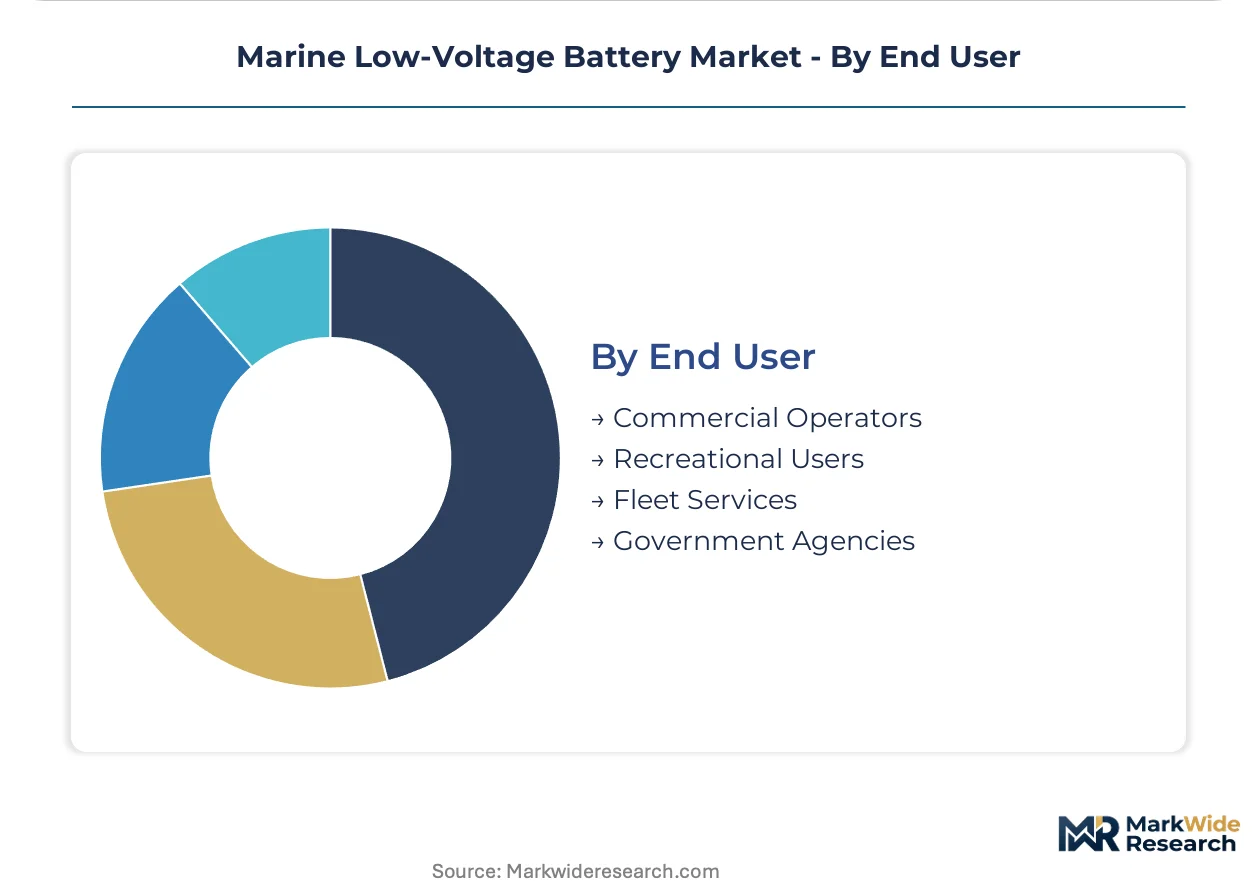
End User:
End user segmentation separates subsidy-eligible commercial operators from price-driven recreational buyers, with defense marine programs specifying IEC-qualified architectures for acoustic signature reduction.
- Commercial Operators:Harbor tug cooperatives and ferry consortia in Norway, Germany, and the Netherlands consolidate procurement around factory-certified module assemblies with 10-year single-point warranties. BAFA maritime innovation grants accelerate payback periods.
- Fleet Services:Third-party vessel management companies standardize battery specifications across mixed-age fleets to simplify maintenance.
- Government Agencies:Naval auxiliary programs in Germany and France specify low-voltage lithium architectures.
- Recreational Users:Individual yacht owners extend lead acid service life through maintenance protocols, delaying lithium penetration.
Commercial Operators lead procurement volume, with Government Agencies climbing fastest as defense marine electrification programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor jurisdictions with subsidy density and certification infrastructure, concentrating battery system integration in Nordic and North Sea economies where port electrification mandates compress compliance costs for vessel operators.
Norway
Harbor tug cooperatives in Oslo and Bergen drive procurement volumes through NOx Fund subsidies covering conversion costs. The Norwegian Maritime Authority enforces strict emissions reporting that accelerates diesel displacement timelines. Yard clusters in Vestland county specialize in hybrid retrofit installations for coastal ferry fleets.
Germany
BAFA maritime innovation grants attract inland waterway operators along the Rhine and Elbe corridors toward lithium-ion architectures. The Federal Maritime and Hydrographic Agency coordinates with EU Green Deal implementation timelines. Hamburg port authority mandates shore power compatibility that locks in battery-hybrid specifications for terminal craft.
Netherlands
Rotterdam port electrification programs create procurement pull for harbor craft serving Europe's largest container terminal complex. The Netherlands Enterprise Agency administers fleet conversion subsidies tied to EU MRV compliance deadlines. Maritime service clusters in the Randstad region integrate battery system commissioning with shore charging infrastructure deployment.
Singapore
Port Authority of Singapore electrification mandates for harbor craft create demand for sealed rack configurations tolerant of tropical humidity. The Maritime and Port Authority coordinates vessel conversion timelines with terminal grid capacity expansion. Shipyard clusters in Tuas integrate photovoltaic arrays with battery systems for autonomous auxiliary power.
United States
California Air Resources Board harbor craft regulations drive retrofit demand in Los Angeles and Long Beach port complexes. The EPA coordinates with state agencies on diesel auxiliary displacement timelines. Pacific Northwest ferry operators in Washington State front-load battery investments to secure yard capacity ahead of compliance deadlines.
Marine Low-Voltage Battery Market Competitive Landscape
Factory-certified module assembly dominates the current landscape as procurement consolidates around integrated system warranties. The vendor base stratifies between maritime-specialized integrators and diversified industrial battery suppliers, with tiering driven by IEC 62619 certification depth and thermal management integration capabilities. Three archetypes occupy distinct positions: Nordic maritime energy storage specialists, diversified European industrial battery manufacturers, and Asian electronics conglomerates with marine divisions. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as assemblers secure cell supply agreements and thermal architecture IP.
Among Nordic maritime specialists, Corvus Energy and Leclanché SA exemplify the factory-certified integration archetype, while Saft SA represents the diversified industrial battery manufacturer position with defense and commercial marine exposure. These three anchors sit within a competitive structure where single-point accountability for decade-long service life guarantees determines procurement outcomes.
| Leading Market Players |
|---|
| Corvus Energy |
| Leclanché SA |
| Siemens Energy |
| EST Floattech |
| Saft SA |
| EnerSys |
| Toshiba Corporation |
| Victron Energy |
| Mastervolt |
| Others |
Pricing and Supply Chain Analysis
Factory-certified module assembly standardization is compressing cost differentials between maritime-specialized integrators and diversified industrial battery suppliers while simultaneously concentrating procurement leverage among Nordic and North Sea system assemblers. This dual compression rewards IEC 62619 certification depth with pricing power while penalizing component-sourcing fragmentation across cell supply agreements and thermal architecture IP.
Pricing Analysis
Direct-to-OEM discounts dominate commercial harbor craft procurement, with factory-certified module assemblies commanding premium positioning over piecemeal component sourcing. Pricing stratifies across IEC 62619 certification grade, volume scale, and single-point warranty bundling. Cost compression in lithium carbonate feedstock is intensifying assembler margin pressure. Recreational yacht owners exhibit highest price sensitivity, deferring lithium conversion through extended lead acid maintenance protocols.
Supply Chain Analysis
Second-life automotive cell refurbishment flows are anchoring reverse logistics economics for marine retrofit channels, with repurposed lithium iron phosphate modules entering at 40-60% of new cell cost. Cell production concentrates in China, South Korea, and Japan. Raw material sourcing draws from Chilean lithium brine, Indonesian nickel laterite, and Australian spodumene. Single-source vulnerability sits with cathode precursor refining. Distribution runs through maritime system integrators with factory-certified assembly capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine low-voltage battery procurement is evolving toward margin expansion as factory-certified module assemblies displace fragmented component sourcing, with IEC 62619 certification depth and thermal management integration capturing premium-tier pricing power.
For Market Incumbents: Deepen captive supply agreements for lithium iron phosphate cells to offset carbonate volatility exposure. Fortify factory-certified assembly capacity in Vestland county and Hamburg port clusters against emerging Asian electronics conglomerates with marine divisions. Prioritize thermal architecture IP development to sustain single-point warranty pricing premiums. For New Entrants and Emerging Players: The mid-tier pricing gap between premium IEC-certified systems and economy lead acid replacements offers white-space entry. Southeast Asian fishing fleets with undeveloped shore infrastructure present most penetrable demand. Solar charging integration partnerships provide differentiated go-to-market positioning against established shore-power-dependent incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among diversified industrial battery manufacturers with underutilized maritime certification infrastructure. Long-term viability hinges on defense marine electrification program exposure and second-life automotive cell sourcing relationships. Monitor NOx Fund and BAFA subsidy renewal trajectories as policy inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Supply | Captive lithium iron phosphate sourcing insulates assembler margins against carbonate volatility. |
| IEC 62619 Certification Investment | Standardized safety protocols reduce insurer risk premiums and expand addressable vessel categories. |
| Deck-Mounted Solar Partnership | Photovoltaic array integration captures autonomous auxiliary power demand in Southeast Asian archipelagos. |
| Second-Life Automotive Cell Sourcing | Repurposed electric vehicle modules enter marine retrofit channels at substantial cost advantage. |
| Defense Marine Electrification Pursuit | Naval auxiliary programs in Germany and France specify low-voltage architectures for acoustic signature reduction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vessel operators, maritime system integrators, port authority electrification planners, battery management system engineers, and marine insurers with secondary validation. Regulatory filings from the Norwegian Maritime Authority, German Federal Maritime and Hydrographic Agency, and Netherlands Enterprise Agency anchored policy trajectory assessment. Customs data, IEC certification registries, and NOx Fund disbursement records supplied volume triangulation against bottom-up vessel fleet analysis.
Historical reference periods spanning vessel retrofit completion cycles and subsidy program phases anchored the projection horizon. Segmentation modeling incorporated battery chemistry tier, application depth from auxiliary to propulsion, charging infrastructure dependency, and end-user subsidy eligibility. CAGRs derived from installed base turnover rates and fleet electrification mandate compliance windows. Forecast inputs included lithium carbonate price volatility indices and shore charging infrastructure deployment timelines.
Caveats apply where lithium carbonate volatility, subsidy program discontinuation, or shore infrastructure deployment delays could materially shift the outlook. Practitioners should monitor IEC 62619 certification timeline extensions and port electrification mandate enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Middle East and Africa SLI Battery Market
Batteries
Europe Consumer Battery Market
Batteries
Italy SLI Battery Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
South Asia Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Elastic Battery Binders Market
Batteries
Nanicl Battery Market
Batteries
Battery Materials Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Battery Light Towers Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
Power-Sports Batteries Market
Batteries
United States Household Battery Market