
 Nitrous Oxide Market | 2026-2036
Nitrous Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrous Oxide Market Outlook
On-site generation technology is narrowing the cost gap between captive production and bulk delivery for large consumers. Messer Group GmbH leverages its European cylinder infrastructure to sustain dense coverage of hospital networks. Linde plc anchors global supply through integrated air separation and distribution assets. Taiyo Nippon Sanso Corporation specializes in ultra-high-purity grades for semiconductor and research end uses.
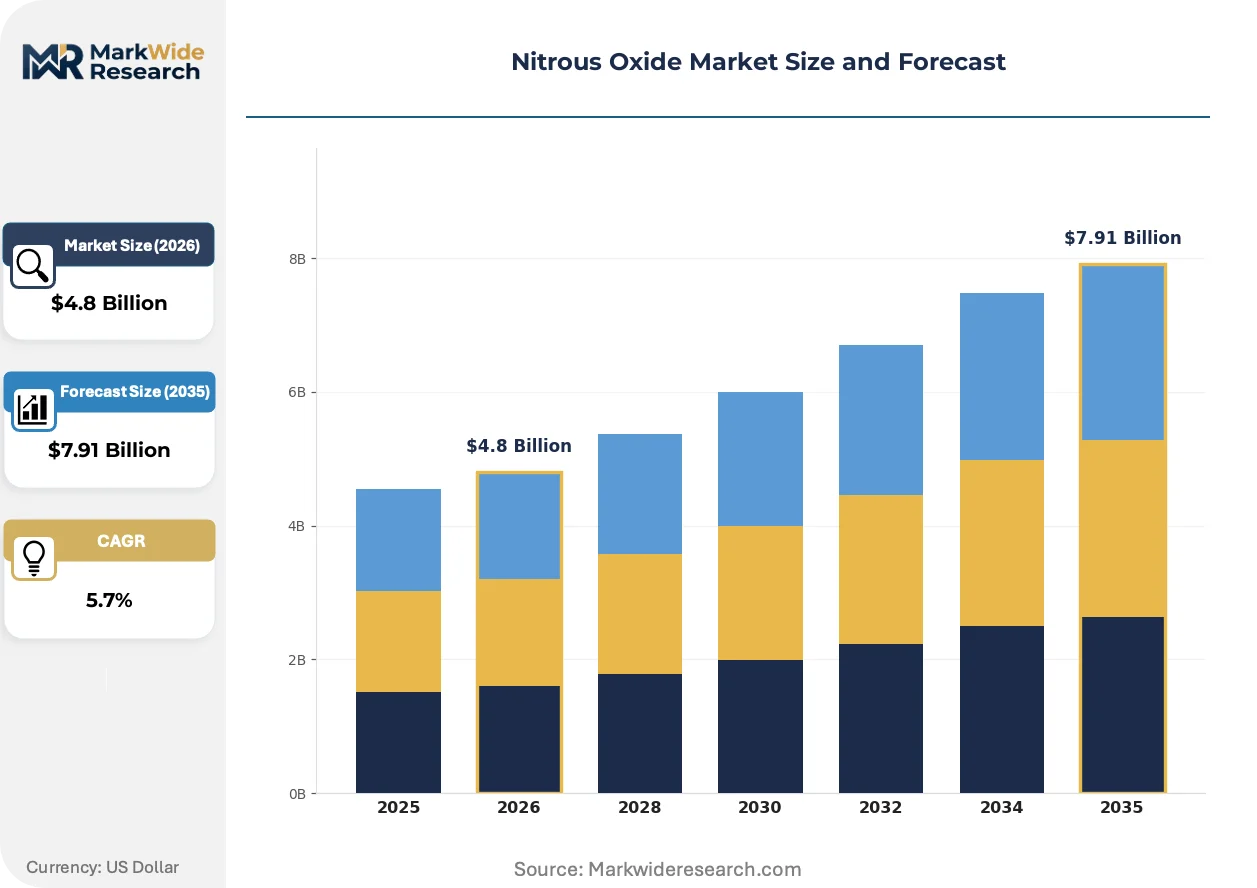
Nitrous oxide is a colorless, non-flammable gas with the chemical formula N₂O, produced primarily by thermal decomposition of ammonium nitrate at controlled temperatures; it serves as an oxidizer, propellant, and anesthetic agent across industrial and clinical settings. Medical Grade product type commands premium pricing due to FDA and pharmacopeia compliance burdens, while Industrial Grade occupies volume leadership in chemical synthesis and rocket propulsion. Application demand in anesthesia remains structurally entrenched in developed healthcare systems, whereas Rocket Propellant application is accelerating with renewed government space budgets and private launch vehicle programs.
The US FDA regulates medical nitrous oxide as a prescription drug under current Good Manufacturing Practice standards, while the EPA governs industrial emissions through Clean Air Act provisions on greenhouse gas reporting. EMA pharmacovigilance requirements and REACH registration obligations in Europe add layered compliance costs that favor producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving rocket propulsion contracts and hospital procurement consolidation to align capacity investments with demand trajectories.
Market Dynamics
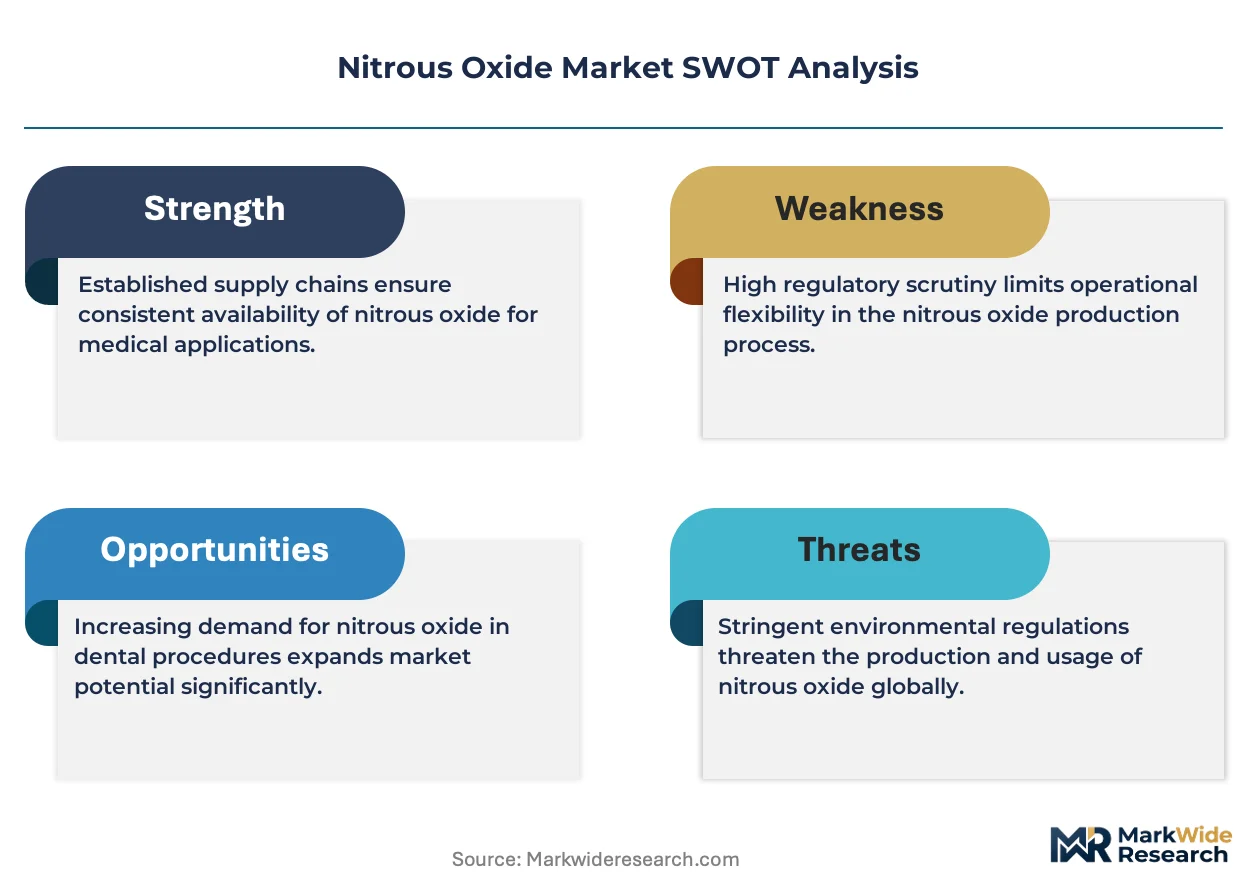
On-site generation technology is compressing the cost differential between captive production and bulk delivery, forcing traditional merchant suppliers to defend hospital contracts through integrated service models rather than volume discounts alone.
Growth Catalysts
- EMA pharmacovigilance tightening:Stricter medical gas purity documentation is accelerating hospital upgrades to certified clinical-grade supply chains, eliminating marginal producers from procurement shortlists.
- Rocket propulsion procurement:Government space agency budgets and private launch vehicle programs are expanding oxidizer demand for reusable engine architectures.
- China hospital infrastructure:Domestic pharmaceutical manufacturing scale-up and surgical capacity expansion are concentrating regional demand for anesthesia-grade product.
Market Restraints
- Ammonium nitrate feedstock volatility:Fertilizer market cyclicality and explosive precursor controls create input cost instability for thermal decomposition production.
- Supply concentration in European cylinder networks:Dense hospital coverage by incumbent gas distributors limits new entrant access to last-mile clinical delivery infrastructure.
- Greenhouse gas reporting under EPA Clean Air Act:Industrial emissions disclosure requirements add compliance overhead to production economics without revenue offset.
Strategic Opportunities
- India pharmaceutical manufacturing:Contract research and manufacturing organization expansion creates underpenetrated demand for process-grade oxidizer in active pharmaceutical ingredient synthesis.
- Semiconductor ultra-high-purity grades:Advanced lithography and deposition processes require contamination thresholds below 10 ppb, commanding specialty pricing unavailable to standard industrial supply.
- EU Green Deal industrial decarbonization incentives:Carbon border adjustment mechanism credits favor on-site generation investments that eliminate transport emissions from cylinder logistics.
Industry Challenges
- Pharmacopeia certification timelines:FDA and EMA current Good Manufacturing Practice validation for medical-grade production requires 18-24 month facility qualification before commercial release.
- Cryogenic storage capex intensity:Bulk liquid handling infrastructure for large hospital systems demands specialized tankage and vaporization equipment with decade-long depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrous Oxide Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Medical Grade, Food Grade, Laboratory Grade Application: Anesthesia, Food Processing, Rocket Propellant, Chemical Manufacturing End User: Healthcare Providers, Food Industry, Aerospace, Research Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Messer Group GmbH, SOL Group, Air Liquide, Matheson Tri-Gas, Inc., Airgas, Inc., Linde plc, Taiyo Nippon Sanso Corporation, Praxair Technology, Inc., Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrous Oxide Market Strategic Shifts
Production technology, regulatory stringency, and procurement rationalization are converging to reshape competitive positioning across medical and industrial supply tiers.
Membrane separation and pressure swing adsorption systems are rendering obsolete traditional ammonium nitrate thermal decomposition for mid-scale hospital and industrial consumers. Regional gas distributors in Germany and Japan are deploying skid-mounted units at customer sites, eliminating cylinder exchange logistics and reducing working capital requirements for healthcare procurement managers.
REACH registration obligations and EU F-Gas Regulation phase-down schedules are tightening industrial gas supply chain documentation requirements. Chemical manufacturers must now demonstrate full substance lifecycle transparency, favoring producers with dedicated regulatory affairs capacity and integrated quality management systems over merchant traders lacking technical dossier depth.
Hospital procurement consolidation through group purchasing organizations is compressing supplier margins while extending contract durations. Large integrated delivery networks in the United States are unbundling equipment lease arrangements from gas supply agreements, forcing distributors to compete on transparent unit economics rather than bundled service lock-in.
Nitrous Oxide Market Segmentation
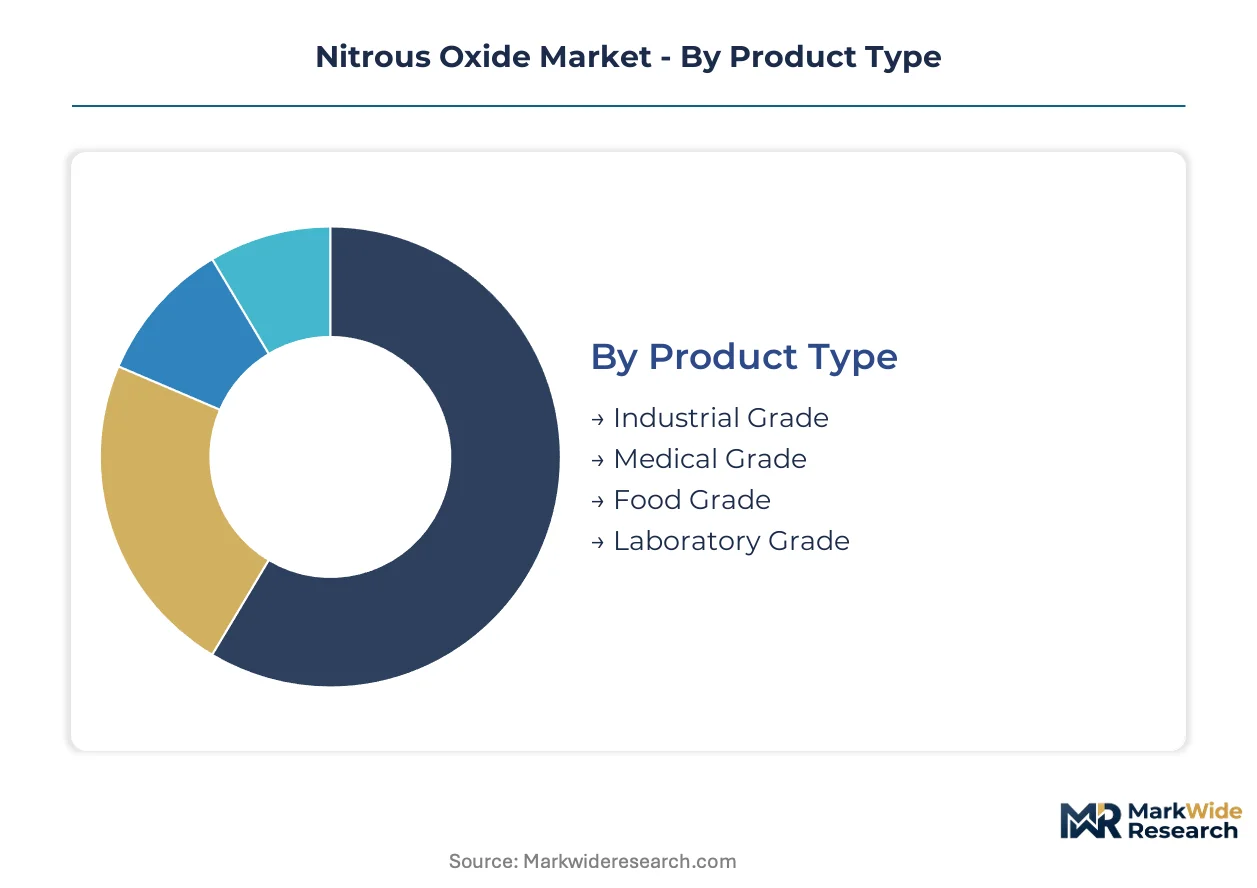
Nitrous oxide segmentation reflects divergent purity standards, regulatory burdens, and supply chain configurations across clinical and industrial domains. Each tier commands distinct certification requirements, pricing premiums, and customer relationships that shape producer specialization strategies.
Product Type:
Cost tier differentiation separates commodity industrial supply from premium-certified grades demanding pharmacopeia compliance and traceability documentation.
- Medical Grade:Clinical-grade N₂O meets FDA current Good Manufacturing Practice and pharmacopeia monograph specifications for human administration. Demand concentrates in US hospital systems upgrading surgical suites and Chinese healthcare infrastructure modernization, where EMA-equivalent documentation requirements are tightening procurement standards.
- Industrial Grade:Standard purity product serves chemical synthesis, semiconductor fabrication, and propulsion applications without medical certification overhead. Volume leadership resides in rocket propellant procurement from government space agencies and private launch programs, though ammonium nitrate feedstock volatility compresses margin stability.
- Food Grade:Nitrous oxide certified for food contact applications functions as a propellant in whipped cream dispensers and packaging atmosphere modification. Regulatory compliance centers on FDA food additive regulations and EFSA safety assessments.
- Laboratory Grade:Ultra-high-purity specification supports analytical instrumentation calibration and research applications requiring contamination thresholds below 100 ppb. Japanese and German research clusters drive specialized demand.
Medical Grade commands the established base. The steepest expansion runs through Laboratory Grade.
Application:
Application segmentation tracks how functional requirements—oxidation potential, biological activity, or inerting capability—determine purity specifications and delivery modalities.
- Anesthesia:Inhalational anesthetic delivery in surgical settings requires precise concentration control and scavenging systems to prevent occupational exposure. US and European hospital networks are consolidating procurement through group purchasing organizations, extending contract durations while compressing unit margins.
- Rocket Propellant:Oxidizer function in liquid-fueled engines demands high specific impulse performance and storage stability. NASA, SpaceX, and European Space Agency procurement cycles are accelerating with reusable engine architecture development.
- Food Processing:Whipping agent and packaging gas applications leverage N₂O solubility in fats and microbiostatic properties. Commercial bakery and dairy processing facilities in North America and Western Europe constitute the primary demand concentration.
- Chemical Manufacturing:Process feedstock for caprolactam and other organic synthesis routes consumes volume production without purity premiums. Chinese petrochemical complexes and Indian active pharmaceutical ingredient manufacturers anchor regional demand.
Anesthesia retains the revenue base. Rocket Propellant is climbing the fastest.
End User:
Customer type segmentation reveals how procurement sophistication, contract scale, and technical service requirements fragment the vendor landscape.
- Healthcare Providers:Hospital systems and ambulatory surgical centers require 24/7 supply assurance, emergency backup systems, and clinical staff training support. US integrated delivery networks are unbundling equipment leases from gas supply agreements.
- Aerospace:Government agencies and private launch vehicle manufacturers impose stringent material certification, lot traceability, and security screening protocols. Long-term program commitments span multi-year production horizons.
- Food Industry:Commercial food manufacturers and equipment distributors prioritize cost efficiency and consistent cylinder exchange logistics over technical service intensity.
- Research Institutions:Universities and national laboratories demand ultra-high-purity grades with comprehensive certificate of analysis documentation for publication-grade reproducibility.
Healthcare Providers anchor the installed base. Aerospace is gaining share fastest.
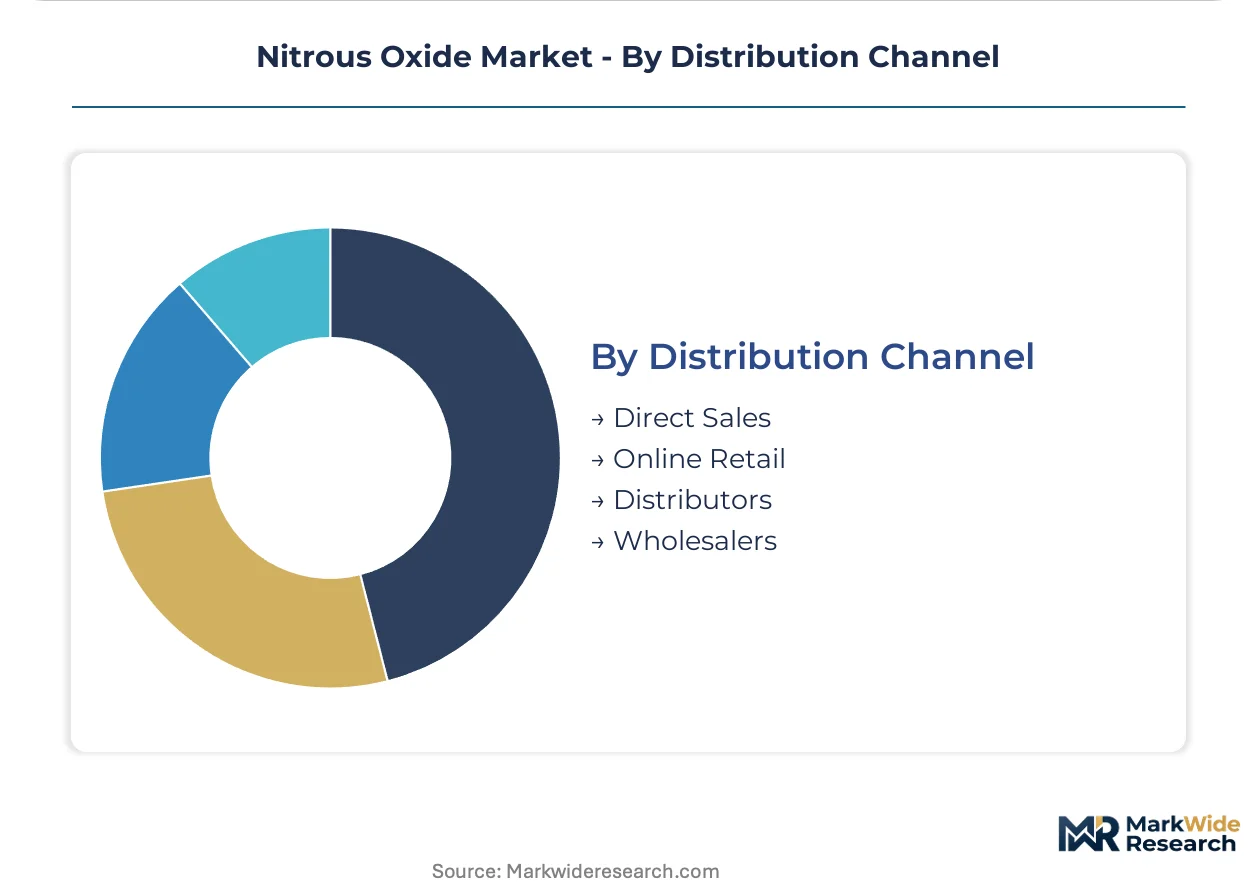
Distribution Channel:
Supply concentration determines whether producers capture margin through direct relationships or concede value to intermediary networks.
- Direct Sales:Producer-to-customer contracts for large-volume hospital systems and aerospace manufacturers eliminate distributor markups while requiring dedicated account management infrastructure. Linde and Messer Group leverage integrated air separation assets to defend these relationships.
- Distributors:Regional gas distributors with dense cylinder exchange networks dominate medical and industrial last-mile delivery, particularly in European hospital coverage where incumbent infrastructure limits new entrant access.
- Wholesalers:Bulk volume aggregation serves mid-scale industrial consumers without dedicated supply contracts, though margin compression is severe.
- Online Retail:E-commerce platforms facilitate small-cylinder sales to food service operators and hobbyist propellant users, with limited penetration in certified medical or aerospace segments.
Direct Sales commands premium economics. Distributors retain volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports industrial-grade nitrous oxide to Indian pharmaceutical manufacturers while Germany supplies medical-grade cylinders to hospital networks across Central Europe. This trade-flow pattern reflects divergent production specializations and regulatory compliance burdens across major consuming geographies.
United States
FDA current Good Manufacturing Practice standards tighten medical gas purity documentation for hospital anesthesia applications. The EPA Clean Air Act greenhouse gas reporting requirements add compliance overhead to industrial production economics. Texas and Louisiana host concentrated chemical manufacturing clusters where process-grade oxidizer demand anchors regional consumption.
Germany
EMA pharmacovigilance obligations and REACH registration requirements favor producers with dedicated regulatory affairs capacity over merchant traders. The EU F-Gas Regulation phase-down schedules tighten industrial gas supply chain documentation. The Rhine-Ruhr industrial corridor sustains dense cylinder distribution infrastructure defending incumbent market positions.
China
Domestic pharmaceutical manufacturing scale-up and hospital infrastructure modernization concentrate regional anesthesia-grade demand. NMPA-equivalent documentation requirements tighten procurement standards for clinical-grade supply chains. The Yangtze River Delta pharmaceutical manufacturing belt drives process-grade oxidizer consumption for active pharmaceutical ingredient synthesis.
India
Contract research and manufacturing organization expansion creates underpenetrated demand for process-grade oxidizer in pharmaceutical synthesis. CDSCO medical device and gas quality regulations are converging toward international pharmacopeia standards. Gujarat and Maharashtra pharmaceutical clusters anchor regional consumption growth for certified production inputs.
Japan
METI industrial gas quality standards and PMDA pharmaceutical oversight maintain stringent certification requirements for medical-grade supply. Ultra-high-purity grades for semiconductor fabrication command specialty pricing unavailable to standard industrial supply. The Kansai semiconductor manufacturing corridor sustains specialized demand for contamination thresholds below 10 ppb.
Nitrous Oxide Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent supply chain configurations. The market structure consolidates around integrated air separation operators with captive production assets and dense distribution infrastructure. Three archetypes dominate: global industrial gas majors with integrated air separation, regional cylinder distributors with last-mile hospital networks, and specialty ultra-high-purity producers for semiconductor and research applications. Competitive moves center on hospital procurement consolidation defense through integrated service bundling and on-site generation technology deployment to compress captive production economics.
Among European-integrated operators, Messer Group GmbH and Linde plc exemplify the channel-control archetype through cylinder infrastructure and air separation asset integration. Taiyo Nippon Sanso Corporation occupies a specialist position representing the ultra-high-purity tier for contamination-sensitive semiconductor and research applications. These three anchors illustrate how geographic origin and corporate structure map to divergent competitive positioning across medical, industrial, and specialty grade supply tiers.
| Leading Market Players |
|---|
| Messer Group GmbH |
| SOL Group |
| Air Liquide |
| Matheson Tri-Gas, Inc. |
| Airgas, Inc. |
| Linde plc |
| Taiyo Nippon Sanso Corporation |
| Praxair Technology, Inc. |
| Air Products and Chemicals, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta pharmaceutical manufacturing belt concentrates industrial-grade nitrous oxide capacity, and this geographic density grants incumbent producers leverage over pricing negotiations with Indian contract manufacturers seeking process-grade oxidizer imports.
Pricing Analysis
On-site generation technology is compressing the pricing gap between legacy ammonium nitrate thermal decomposition and membrane separation systems for mid-scale consumers. Three-tier pricing structure across medical-grade premium, industrial-grade standard, and food-grade economy levels separates FDA-certified clinical supply from commodity chemical feedstock. Cost compression in medical-grade tiers is intensifying because hospital procurement consolidation through group purchasing organizations extends contract durations while squeezing unit margins. Research institutions demonstrate the lowest price sensitivity due to ultra-high-purity contamination thresholds below 10 ppb.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk planning for pharmaceutical oxidizer procurement. Production gravity centers on China, Germany, and the United States, with Chinese thermal decomposition capacity feeding Indian active pharmaceutical ingredient manufacturers and German cylinder networks supplying Central European hospital systems. Feedstock volatility in ammonium nitrate fertilizer markets and explosive precursor controls create input cost instability. Distribution runs through regional gas distributors with dense last-mile cylinder exchange infrastructure, particularly in European hospital coverage where incumbent networks limit new entrant access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation through group purchasing organizations has shifted bargaining power toward healthcare buyers, fragmenting supplier margins across anesthesia-grade supply contracts.
For Market Incumbents: Pre-empt membrane separation technology displacement by deploying skid-mounted on-site generation units at customer sites, eliminating cylinder logistics and locking in long-term service relationships. Deepen captive production economics through backward integration into air separation assets. Defend European hospital network positions against emerging regional challengers by bundling emergency backup systems with transparent unit pricing. For New Entrants and Emerging Players: Pursue underpenetrated demand in Indian pharmaceutical manufacturing clusters where contract research and manufacturing organization expansion outpaces certified oxidizer supply. Target Gujarat and Maharashtra active pharmaceutical ingredient producers with process-grade product positioned below European import pricing. Establish go-to-market presence through direct technical sales to quality assurance directors rather than distributor intermediaries. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because pharmacopeia certification timelines and 18-24 month FDA current Good Manufacturing Practice validation create durable barriers against commodity competition. Acquisition targets should display integrated quality management systems with dedicated regulatory affairs capacity. Monitor rocket propulsion procurement cycles from NASA, SpaceX, and European Space Agency as inflection signals for industrial-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Generation Deployment | Skid-mounted membrane units at hospital sites eliminate cylinder logistics and reduce customer working capital requirements. |
| Pharmacopeia Certification Investment | FDA and EMA current Good Manufacturing Practice validation secures procurement shortlist inclusion for anesthesia-grade supply. |
| Backward Integration into Air Separation | Captive production assets defend margin compression from merchant traders lacking integrated gas generation infrastructure. |
| Ultra-High-Purity Capacity Addition | Contamination thresholds below 10 ppb for semiconductor lithography command specialty pricing unavailable to standard industrial grades. |
| Rocket Propulsion Supply Agreement | Long-term oxidizer contracts with SpaceX and government space agencies span multi-year production horizons with material certification requirements. |
Study Parameters
The analysis maps medical-grade, industrial-grade, food-grade, and laboratory-grade supply tiers, each validated through hospital procurement managers, pharmaceutical quality directors, gas distribution executives, and semiconductor process engineers. Primary interview findings triangulate against customs trade data, FDA medical gas facility inspection records, EMA pharmacovigilance documentation, and air separation industry capacity disclosures. Bottom-up demand modeling from end-use consumption patterns reconciles with top-down production capacity estimates across major manufacturing clusters.
Assumptions hold ammonium nitrate feedstock cost cyclicality within historical bands and EPA Clean Air Act greenhouse gas reporting requirements stable across the projection horizon. Segmentation dimensions include product purity grade, application function, end-user procurement sophistication, and regional regulatory framework. CAGRs derive from volume-demand elasticity modeling against healthcare infrastructure investment cycles and rocket propulsion procurement timelines. Forecast inputs incorporate hospital surgical capacity expansion rates and semiconductor fabrication equipment spending patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical producers or accelerated membrane technology adoption by hospital systems would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Europe Molecular Sieve Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Europe Modified Bitumen Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Honing Oil Market