
 Knitting Oils Market | 2026-2036
Knitting Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Knitting Oils Market Foresight
Aftermarket technical service revenue is narrowing as a distinct margin pool, with blenders and distributors folding consulting and fluid management into core supply contracts. KLÜBER LUBRICATION leverages its application engineering network to embed oil change protocols directly into mill maintenance schedules. TotalEnergies anchors its position through backward integration into base oil refining, securing cost visibility across mineral and synthetic grades. BECHEM competes on specialty ester formulations designed for high-speed seamless knitting machines.
Knitting oils are formulated lubricants applied to needles, sinkers, and yarn guides during weft and warp knitting to reduce friction, prevent needle wear, and inhibit static buildup on synthetic fibers; typical formulations incorporate refined mineral bases, polyalphaolefins, or ester synthetics with anti-oxidant and anti-corrosion additive packages at viscosity ranges of 15–68 cSt at 40°C. Synthetic oils command premium positioning as mills upgrade to electronic jacquard and multi-feeder circular machines running above 3,500 revolutions per minute. Biodegradable oils represent the fastest-growing product category, driven by zero-discharge mandates in European textile finishing clusters and emerging requirements in China's Zhejiang province. Mineral oils still dominate volume in price-sensitive South Asian markets where open-width finishing tolerates higher lubricant carryover.
REACH registration in Europe and China's MEE discharge standards for textile wet processing jointly elevate compliance costs for conventional petroleum-based formulations, pushing blenders toward bio-based feedstocks and extended fluid-life additive systems. India's BIS lubricant quality certification and Tamil Nadu's state pollution control board effluent norms create a dual-layer regulatory environment for mills in Coimbatore and Tiruppur. Stakeholders must monitor how per-needle oil consumption rates evolve as machine builders integrate closed-loop micro-mist lubrication systems that promise 40–60% fluid reduction.
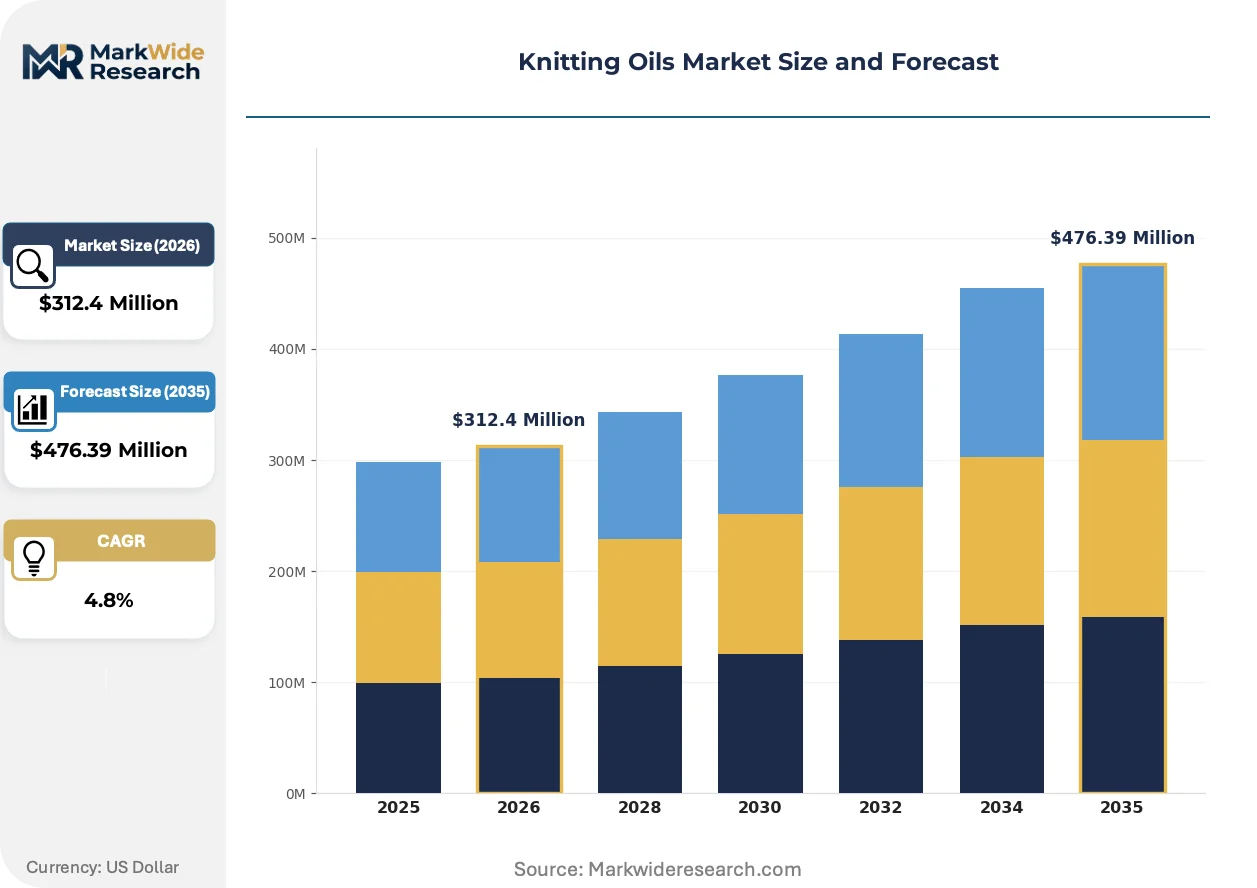
Market Dynamics
Machine builder consolidation around closed-loop micro-mist lubrication architectures is compressing per-needle fluid consumption rates, forcing blenders to reformulate for extended service intervals and lower carryover volumes.
Growth Catalysts
- High-speed seamless knitting machines:Electronic jacquard and multi-feeder circular systems running above 3,500 rpm demand synthetic ester formulations with superior thermal stability and oxidation resistance.
- Zero-discharge mandates in European textile finishing clusters:REACH registration requirements and effluent restrictions under ECHA frameworks are accelerating mill migration toward biodegradable base stocks and extended-life additive packages.
- Tamil Nadu and Gujarat textile belt expansion:Circular knitting machine density in Coimbatore and Tiruppur drives bulk procurement of high-performance mineral and synthetic grades for export-oriented garment production.
Market Restraints
- Base oil price volatility:Refined mineral and polyalphaolefin feedstock costs fluctuate with crude oil indices, squeezing blender margins on standard-grade formulations.
- Supply concentration in specialty ester production:Captive production of high-performance synthetic bases clusters among integrated petrochemical complexes in Germany and the United States.
- Technical limitation in bio-based oxidation stability:Vegetable-derived base stocks degrade faster under high-speed needle friction, limiting deployment in electronic jacquard applications above 4,000 rpm.
Strategic Opportunities
- Underpenetrated Zhejiang province wet processing clusters:China's MEE discharge standards for textile finishing create first-mover advantage for biodegradable oil suppliers with GB-standard compliance documentation.
- Fluid management service bundling:Mill maintenance outsourcing trends enable oil suppliers to embed oil change protocols and waste fluid recovery into multi-year supply contracts.
- Technology convergence of micro-mist systems and IoT sensors:Real-time lubricant condition monitoring allows predictive replenishment models that reduce total fluid consumption by 40-60 percent.
Industry Challenges
- Specialized tribology expertise scarcity:Formulation chemists with combined knowledge of textile machinery mechanics and synthetic lubricant additive chemistry command premium compensation.
- BIS certification timeline compression:India's quality certification processes for industrial lubricants create 8-12 month product approval cycles that delay market entry for new biodegradable formulations.
- Legacy mineral oil infrastructure lock-in:South Asian mills with open-width finishing equipment tolerate higher lubricant carryover, slowing capital redeployment toward synthetic-compatible closed-loop systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knitting Oils Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oils, Synthetic Oils, Biodegradable Oils, Palm Oil Application: Textile Industry, Automotive Industry, Home Textiles, Industrial Fabrics Form: Liquid, Gel, Emulsion, Powder End User: Manufacturers, Retailers, Wholesalers, Individual Crafters |
| Companies Covered | BECHEM, Vickers Oils, Nye Lubricants, KLÜBER LUBRICATION, Hindustan Petroleum Corporation Limited, Behran Oil Co., Eastern Petroleum Pvt. Ltd., TotalEnergies, LUBCON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knitting Oils Market Shifts & Advancements
Digital integration of lubrication systems with machine control architectures is redefining fluid consumption models and supplier value propositions across textile manufacturing clusters.
Micro-mist lubrication technology is digitizing oil delivery precision through electronically controlled needle-specific dispensing. High-speed circular knitting operations in Turkey and Bangladesh are retrofitting multi-feeder machines with sensor-enabled closed-loop systems. This architecture is digitizing maintenance scheduling by correlating real-time consumption data with predictive wear algorithms.
REACH registration in Europe and China's evolving GB standards on industrial lubricant discharge are jointly elevating compliance documentation burdens. Conventional petroleum-based formulations face extended substance evaluation timelines under ECHA frameworks. Biodegradable ester categories are capturing specification share in European finishing clusters and Zhejiang province wet processing facilities.
Aftermarket technical service unbundling is compressing standalone consulting revenue pools. Blend distributors in India's Tamil Nadu belt now fold fluid analysis and waste management into core supply agreements rather than charging separately. This bundling pattern is most visible in Tiruppur's export-oriented circular knitting sector, where mills prioritize total cost-per-garment metrics over unit oil pricing.
Knitting Oils Market Segmentation
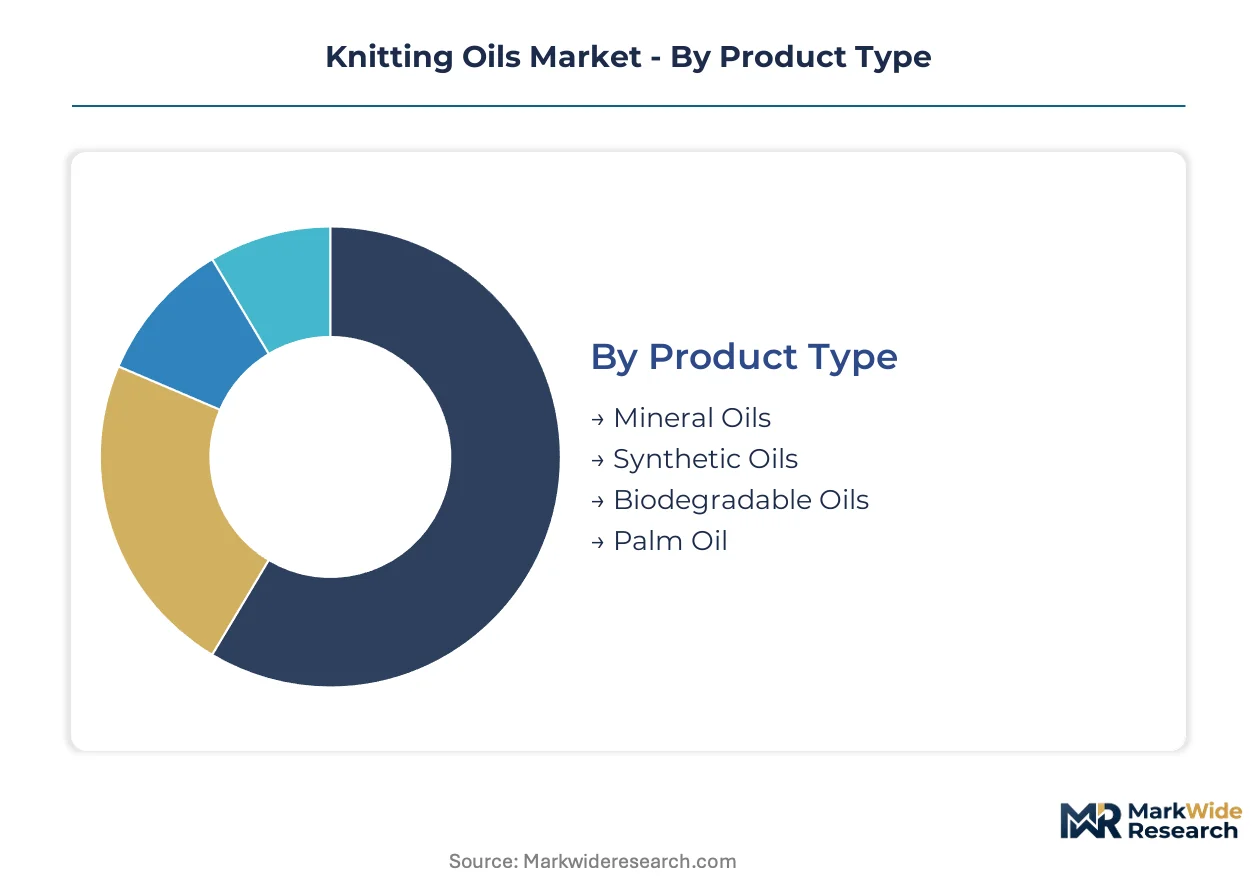
Knitting oil procurement patterns diverge sharply across product chemistries and end-use applications, with formulation selection directly tied to machine speed requirements and discharge compliance obligations. Service bundling intensity varies by segment, creating distinct margin architectures for suppliers.
Product Type:
After-sales-service intensity peaks with synthetic and biodegradable grades, where technical consulting on fluid management and waste recovery commands premium positioning.
- Mineral Oils:Refined petroleum-based formulations dominate volume in price-sensitive South Asian markets. Tamil Nadu's circular knitting belt in Coimbatore and Tiruppur drives bulk procurement for export garment production where open-width finishing tolerates higher lubricant carryover.
- Synthetic Oils:Polyalphaolefin and ester-based formulations deliver thermal stability above 3,500 rpm on electronic jacquard machines. Demand concentrates in Turkey and Bangladesh where high-speed seamless knitting operations require oxidation-resistant additive packages.
- Biodegradable Oils:Vegetable-derived base stocks with extended-life additives respond to zero-discharge mandates in European finishing clusters and Zhejiang province wet processing facilities.
- Palm Oil:Cost-competitive natural base stock with limited high-speed deployment due to oxidation stability constraints under sustained needle friction.
Mineral oils hold the largest share; momentum sits with biodegradable formulations as discharge standards tighten across multiple geographies.
Application:
Cost tier stratification separates premium synthetic deployment in high-speed textile machinery from economy mineral grades in lower-velocity applications.
- Textile Industry:Circular and flat knitting operations consume the majority of formulated lubricants, with warp and weft systems requiring needle, sinker, and yarn guide protection across viscosity ranges of 15–68 cSt.
- Automotive Industry:Technical textile production for seat covers and interior fabrics demands synthetic ester compatibility with electronic jacquard controls.
- Home Textiles:Blanket and upholstery knitting in India's Gujarat belt operates on mineral oil formulations with standard additive packages.
- Industrial Fabrics:Geotextile and filtration media production requires specialized anti-static properties for synthetic fiber processing.
Textile applications command the dominant revenue pool; automotive technical fabrics are climbing the fastest on specification upgrades.
Form:
Volume concentration favors liquid delivery systems compatible with conventional circulation and emerging micro-mist architectures.
- Liquid:Standard circulation system compatibility across all machine generations, with 40–60% consumption reduction possible via closed-loop micro-mist retrofits.
- Gel:Targeted needle lubrication for specific high-wear zones in multi-feeder circular machines.
- Emulsion:Water-based formulations for processes requiring reduced oil carryover into downstream finishing stages.
- Powder:Dry lubricant application for specialized yarn guide treatments in moisture-sensitive fiber processing.
Liquid forms retain the largest installed base; emulsion formats are gaining share fastest on effluent compliance pressures.
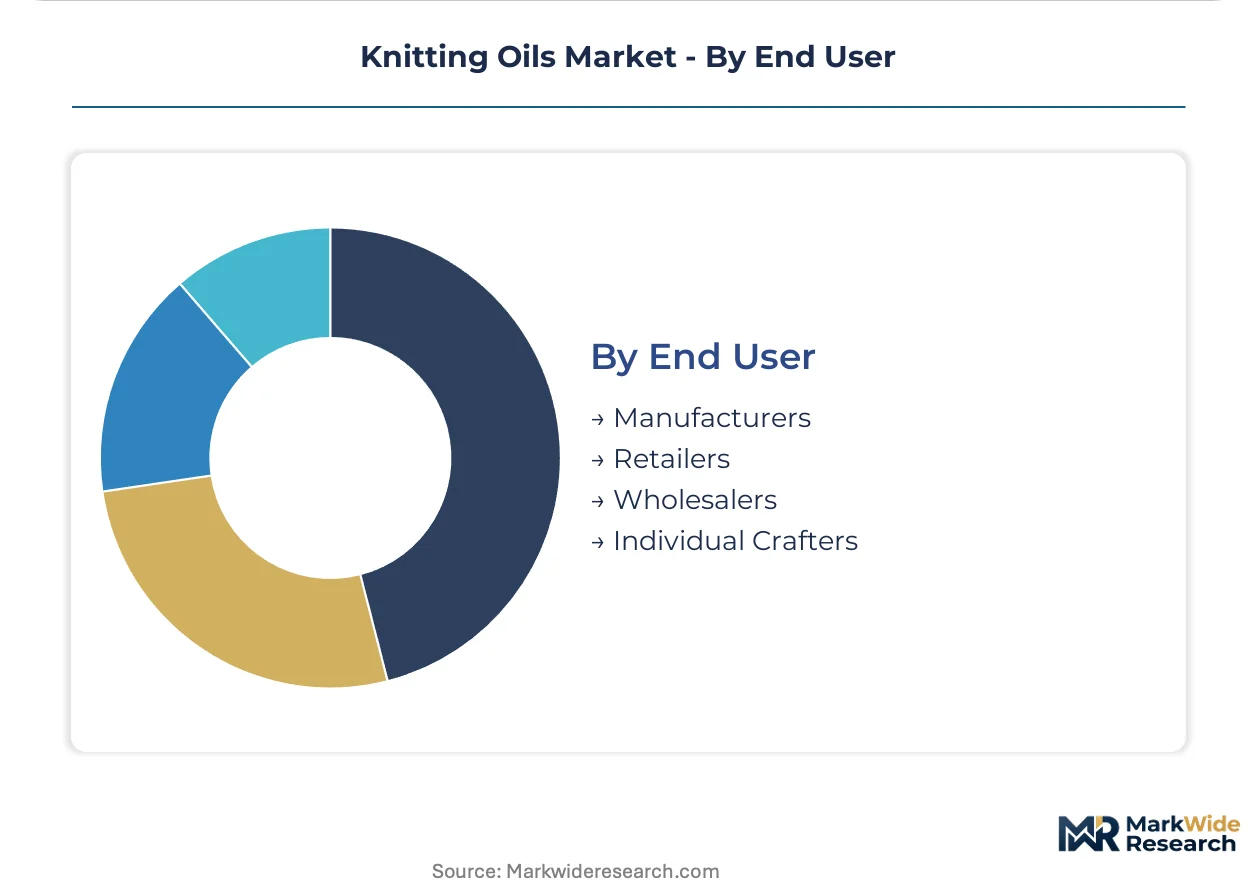
End User:
Customer type determines procurement scale and service bundling depth, with manufacturer consolidation driving multi-year fluid management contracts.
- Manufacturers:Large-scale textile mills in Asia-Pacific knitting clusters negotiate integrated supply agreements embedding oil change protocols and waste fluid recovery.
- Retailers:Smaller-volume procurement for maintenance departments in regional garment production facilities.
- Wholesalers:Distribution intermediaries serving fragmented machine repair networks with standard-grade mineral formulations.
- Individual Crafters:Niche demand from hand-knitting and small-scale artisan equipment with minimal volume impact.
Manufacturers represent the largest consumption segment; service-integrated procurement models are expanding most quickly among this group.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Asian knitting belts display acute price elasticity, while European and East Asian mills absorb premium synthetic grades with minimal volume sensitivity. This demand bifurcation shapes regional formulation strategies and service bundling intensity.
China
Zhejiang province wet processing clusters drive biodegradable oil procurement as MEE discharge standards tighten effluent controls. GB standards on industrial lubricant discharge elevate compliance documentation burdens for petroleum-based formulations. Shaoxing and Hangzhou textile hubs are retrofitting circular knitting facilities with closed-loop micro-mist architectures to reduce fluid consumption.
India
Tamil Nadu's Coimbatore and Tiruppur belt concentrates bulk demand for mineral and synthetic grades serving export garment production. BIS lubricant quality certification and state pollution control board effluent norms create dual-layer regulatory hurdles for new market entrants. Gujarat's Surat and Ahmedabad clusters are expanding circular knitting capacity for home textile exports.
Germany
REACH registration requirements under ECHA frameworks accelerate mill migration toward bio-based feedstocks and extended-life additive packages. Specialty ester production clusters among integrated petrochemical complexes in the Rhine-Ruhr region. Technical textile manufacturers in Baden-Württemberg deploy synthetic formulations compatible with electronic jacquard controls.
Turkey
Gaziantep and Bursa knitting hubs demand synthetic ester formulations for high-speed seamless machines running above 3,500 rpm. The country's alignment with EU environmental directives pressures mills toward biodegradable alternatives. Istanbul-based technical textile producers are upgrading multi-feeder circular systems for automotive seat cover applications.
United States
EPA effluent guidelines for textile wet processing shape formulation roadmaps in North Carolina's knitting corridor. Technical textile production for industrial fabrics and filtration media requires specialized anti-static properties. Georgia's carpet and upholstery knitting sector maintains steady mineral oil consumption for standard-velocity equipment.
Knitting Oils Market Competitive Landscape
Capability concentration sits with specialty ester formulators; scale advantage sits with integrated petrochemical majors with backward integration into base oil refining. The vendor base stratifies across three tiers: multinational lubricant conglomerates with captive additive technology, regional blenders serving price-sensitive South Asian markets, and niche specialists in biodegradable formulations. Consolidation pressure intensifies as machine builders specify fluid performance requirements directly. Competitive moves center on M&A for tribology expertise and strategic partnerships for micro-mist system integration.
Within the specialty synthetic tier, KLÜBER LUBRICATION and BECHEM exemplify formulation-intensive positioning anchored in German engineering heritage. TotalEnergies occupies a scale-driven position through upstream control over base oil supply chains. Among Asia-Pacific distributors, Hindustan Petroleum Corporation Limited represents state-affiliated volume leverage in India's textile belts. These three anchors illustrate how competitive positioning diverges across technical specialization, vertical integration depth, and geographic density.
| Leading Market Players |
|---|
| BECHEM |
| Vickers Oils |
| Nye Lubricants |
| KLÜBER LUBRICATION |
| Hindustan Petroleum Corporation Limited |
| Behran Oil Co. |
| Eastern Petroleum Pvt. Ltd. |
| TotalEnergies |
| LUBCON |
| Others |
Supply & Pricing Matrix
Rhine-Ruhr specialty ester production clusters in Germany anchor upstream pricing power for synthetic knitting oil formulations, with captive additive technology concentrating margin capture among integrated petrochemical majors. This geographic supply dominance translates directly into premium positioning for high-speed seamless machine applications, while South Asian blenders compete on volume throughput of mineral grades.
Pricing Analysis
Aftermarket technical service contracts now drive lifetime value capture, with fluid management bundling replacing standalone consulting fees. Three-tier pricing structure across premium synthetic, standard mineral, and economy bulk grades separates specification tiers by oxidation stability and REACH compliance certification. Cost compression in mineral oil segments is intensifying due to crude-linked base oil volatility, eroding blender margins on standard formulations. Export-oriented mills in Tamil Nadu display highest price sensitivity, while European technical textile producers absorb synthetic premiums with minimal volume resistance.
Supply Chain Analysis
Contract manufacturing capacity for specialty ester bases clusters among integrated petrochemical complexes in Germany, the United States, and Japan. Formulation production draws from polyalphaolefin feedstocks, vegetable-derived bio-base stocks, and antioxidant additive packages sourced from regional chemical distributors. Single-source vulnerability sits with high-performance synthetic base production, where limited qualified suppliers constrain rapid formulation pivots. Distribution runs through authorized blender networks in textile manufacturing clusters, with mill-direct contracts displacing wholesale intermediaries in high-volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Knitting oils represent an early-cycle expansion story as closed-loop micro-mist lubrication architectures penetrate high-speed circular knitting operations, with per-needle fluid consumption compression creating sustained demand for reformulated extended-life products.
For Market Incumbents: Pre-empt biodegradable formulation patent positioning in Zhejiang province wet processing clusters before MEE discharge standards fully crystallize. Secure backward integration into palm oil and vegetable ester feedstocks to hedge petroleum base oil volatility. Anchor mill maintenance outsourcing contracts in Tiruppur's export garment sector to embed oil change protocols directly into multi-year supply agreements.
For New Entrants and Emerging Players: Zhejiang province biodegradable oil procurement represents the most penetrable entry point for GB-standard compliant suppliers without established European REACH portfolios. Tamil Nadu's fragmented wholesale mineral oil distribution layer offers channel disruption potential through direct mill relationships. Lead with fluid analysis and waste recovery service bundling rather than unit price competition to differentiate from incumbent blenders.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty synthetic formulators with captive tribology expertise and machine builder specification relationships. Five-to-ten year viability favors suppliers with demonstrated REACH and GB standard compliance documentation rather than commodity mineral blenders. Monitor per-needle oil consumption rate declines across installed circular knitting machine bases as the inflection signal for reformulation investment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Formulation Development | REACH and MEE compliance documentation accelerates mill procurement decisions in European and Chinese clusters. |
| Micro-Mist System Integration Partnership | Machine builder alliances embed oil suppliers into closed-loop lubrication architectures reducing fluid consumption. |
| Fluid Management Service Bundling | Multi-year maintenance contracts in Tamil Nadu capture total cost-per-garment procurement preferences. |
| Specialty Ester Backward Integration | Captive base oil production secures margin visibility against crude-linked mineral feedstock volatility. |
| Regional Certification Investment | BIS lubricant quality certification in India compresses 8-12 month approval timelines for new market entrants. |
Research Methodology
Operator-level perspectives from textile mill maintenance directors, lubricant procurement managers at circular knitting operations, formulation chemists at specialty blenders, and distribution channel partners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade data, BIS certification registries, ECHA REACH substance databases, and SEC filings from integrated petrochemical majors. Bottom-up machine installation counts and top-down lubricant consumption intensity models were triangulated to establish volume baselines.
Scenario-bracketing framed demand trajectories across the projection horizon, with segmentation modeling across product chemistry tiers, machine speed application bands, and regional regulatory clusters. CAGRs were derived from correlated growth in circular knitting machine density and per-unit oil consumption compression rates. Forecast inputs incorporated micro-mist retrofit penetration curves, biodegradable formulation specification share shifts, and discharge standard implementation timelines.
Practitioners should monitor base oil price volatility indices, REACH substance evaluation timelines, and closed-loop lubrication system retrofit rates for early signals of forecast revision. Quarterly review of per-needle consumption data from machine builder technical bulletins and state pollution control board effluent enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Trimethylolpropane (TMP) Market