
 Global Chlorothalonil Market | 2026-2036
Global Chlorothalonil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chlorothalonil Market Foresight
Technical-grade purity upgrades toward 98 percent active ingredient content is unwinding older formulation standards across the chlorothalonil supply base. Syngenta Group leverages its integrated agrochemical platform to sustain premium positioning in flowable concentrate development. Limin Group Co. Ltd. anchors Chinese export volumes through captive intermediate production. FMC Corporation differentiates in North American turf management channels with specialized wettable powder grades.
Chlorothalonil is a broad-spectrum organochlorine fungicide with a tetrachloroisophthalonitrile structure, manufactured through catalytic chlorination of isophthalonitrile and valued for its multi-site contact activity against foliar pathogens. The wettable powder segment retains cost-sensitive volume in cereal crop applications across South Asia and Eastern Europe, while flowable formulations capture margin pools in precision agriculture systems. Emulsifiable concentrate demand is accelerating among commercial greenhouse operators who prioritize tank-mix compatibility with systemic fungicides.
EPA re-registration reviews and EU REACH substance evaluation are tightening residue limits and buffer zone requirements, forcing reformulation investments and label amendments across export-oriented manufacturers. China's MEE environmental compliance audits and India's CEA chemical handling standards are adding facility-level certification costs for producers serving regulated markets. Stakeholders must monitor regulatory divergence between jurisdictions with maintained registrations and those phasing out organochlorine fungicides, as this split will determine which formulation investments retain commercial viability.
Market Dynamics
EPA re-registration reviews and EU REACH substance evaluation are forcing dual-track formulation investments, splitting manufacturer portfolios between maintained-registration markets and phase-out jurisdictions.
Growth Catalysts
- Brazilian soybean belt expansion:Farmers in Mato Grosso and Paraná are prioritizing broad-spectrum fungal disease coverage as planting densities intensify.
- REACH compliance upgrade cycle:Export-oriented producers are capturing premium positioning by meeting tightened EU residue limits and buffer zone requirements ahead of competitors.
- Flowable concentrate technology:Precision agriculture systems in North American turf management are absorbing higher-margin formulations with improved tank-mix compatibility.
Market Restraints
- Isophthalonitrile feedstock concentration:Chinese intermediate producers control catalytic chlorination capacity, exposing downstream formulators to input cost volatility.
- Organochlorine substitution pressure:Biological fungicides and SDHI chemistry are displacing contact-activity products in greenhouse vegetable operations.
- EU F-Gas Regulation alignment:Formulation standards for export markets require costly label amendments that smaller producers cannot absorb.
Strategic Opportunities
- Indian vegetable-growing states:Uttar Pradesh and Maharashtra present underpenetrated demand for wettable powder grades in cereal-fungicide rotation programs.
- China MEE environmental compliance:Facility-level certification requirements are creating tiered supply access for producers with audit-ready manufacturing assets.
- Drone application compatibility:Low-volume flowable formulations are converging with aerial spraying platforms in Brazilian commercial farming cooperatives.
Industry Challenges
- Dual-registration maintenance burden:Producers must simultaneously manage EPA label amendments and EU REACH dossier updates with diverging scientific endpoints.
- Technical-grade purity transition:Shifting captive production to 98 percent active ingredient specifications requires reactor reconfiguration and quality system overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chlorothalonil Market |
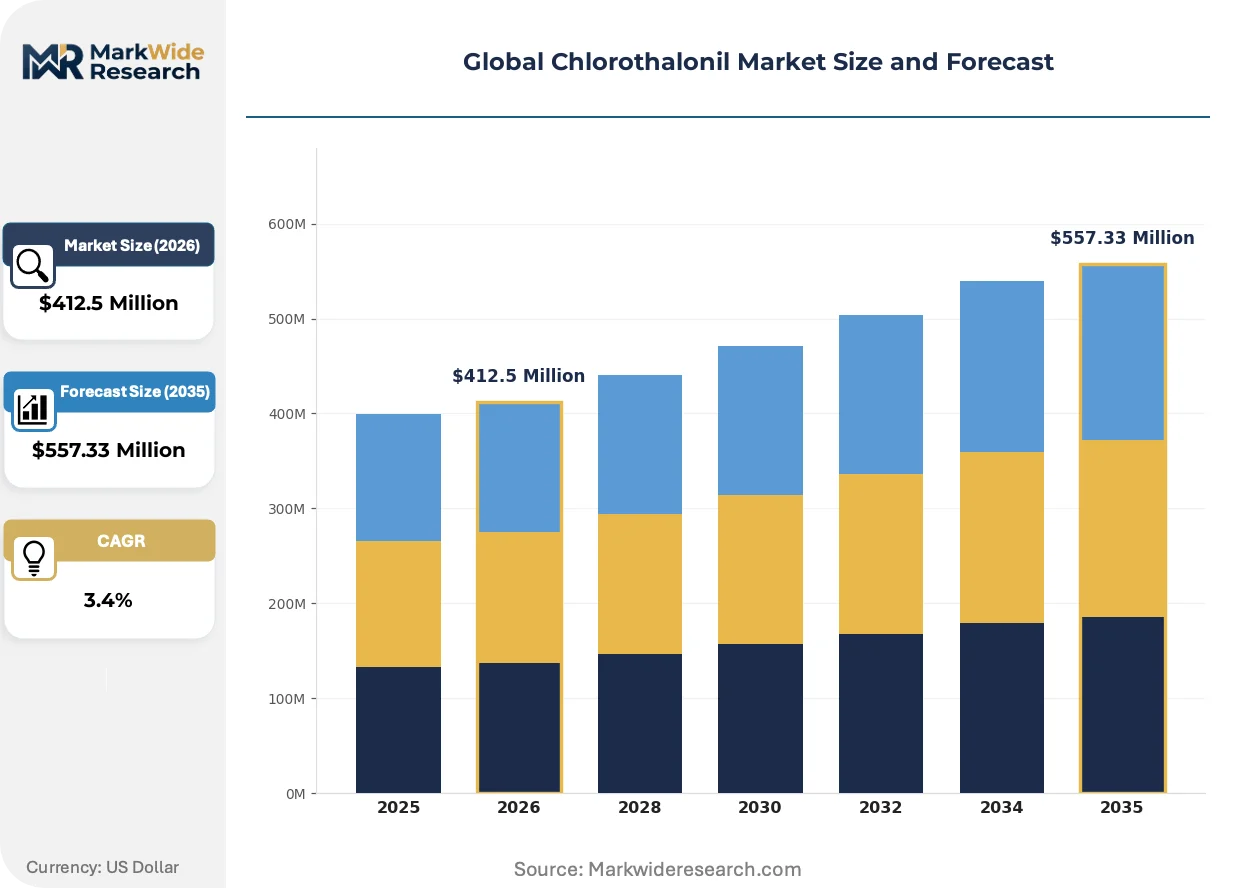
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $557.33 Million |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wettable Powder, Emulsifiable Concentrate, Granular, Liquid Suspension, Flowable Application: Cereal Crops, Vegetables, Fruits, Ornamentals, Turf Management, Floriculture End User: Commercial Farms, Greenhouses, Landscape Service Providers, Turf Managers Packaging Type: Plastic Bottles, Metal Drums, Jerry Cans, Pouches, Box Containers |
| Companies Covered | Jiangsu Xinhe, Limin Group Co. Ltd., Syngenta Group, BASF SE, UPL Limited, SDS Biotech K.K., Jiangsu Weunite, FMC Corporation, Jiangyin Suli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chlorothalonil Market Shifts & Advancements
Formulation chemistry and application technology are diverging across regulatory boundaries, with producers developing distinct product architectures for maintained-registration versus phase-out markets.
Micro-encapsulated chlorothalonil delivery systems are bifurcating the fungicide market between extended-release turf applications and conventional agricultural sprays. Golf course superintendents in Florida and Arizona are adopting these formulations for reduced application frequency. The technology is compressing commodity wettable powder margins while enabling premium pricing in amenity horticulture channels.
ECHA's REACH substance evaluation process is tightening residue limits for tetrachloroisophthalonitrile metabolites in imported food commodities. Export-oriented Chinese manufacturers are reformulating active ingredient loads and co-formulant packages to meet descending maximum residue levels. Brazilian soybean processors are demanding third-party certification of EU-compliant supply chains to avoid import rejection at Rotterdam.
Commercial greenhouse operators in the Netherlands and Spain are unbundling fungicide procurement from full-service crop protection contracts. Large vegetable cooperatives are establishing direct relationships with technical-grade suppliers to secure volume commitments and bypass distribution markups. This disintermediation is most visible in Almería's tomato and pepper production clusters, where cooperative buying groups now represent substantial flowable concentrate offtake.
Global Chlorothalonil Market Segmentation
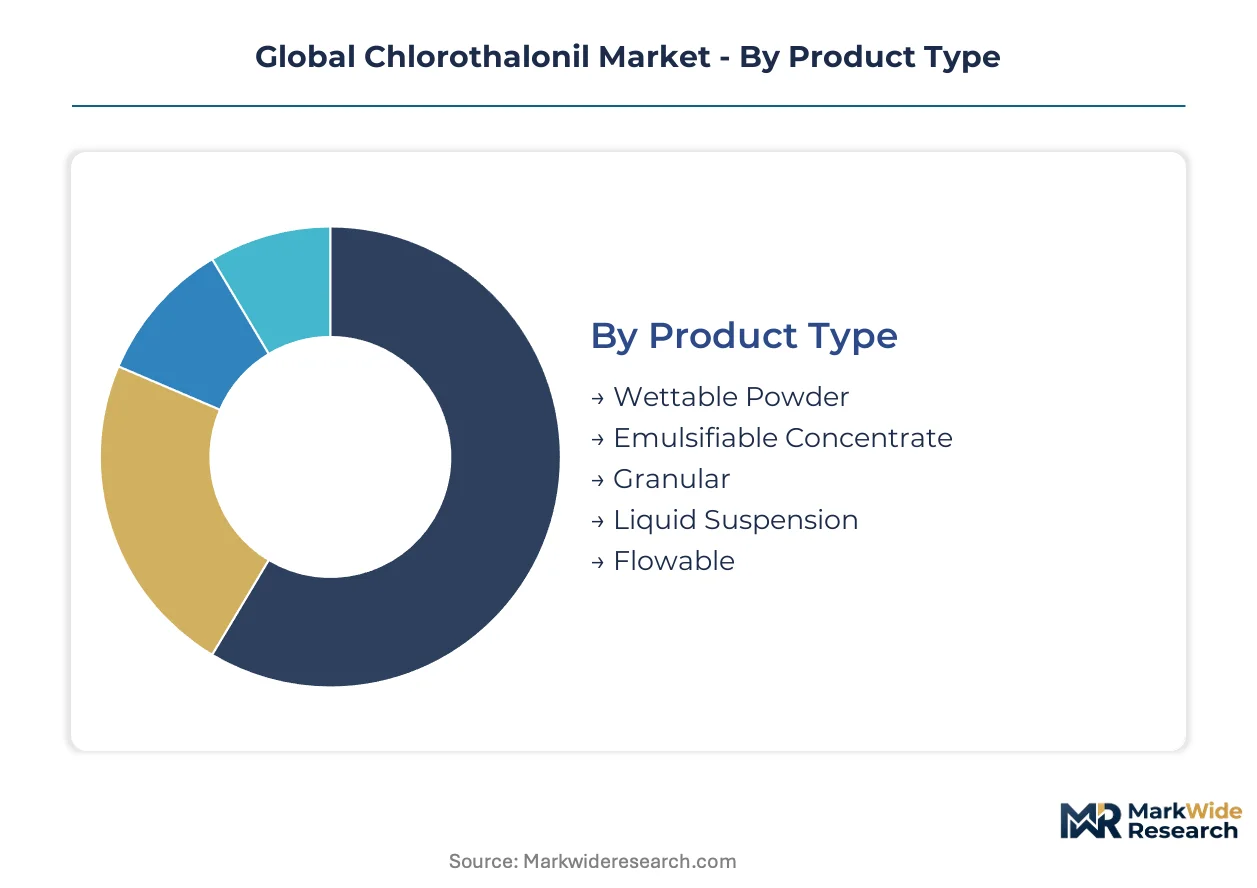
Formulation standards diverge sharply across regulatory jurisdictions, forcing manufacturers to maintain parallel product architectures. Segmentation reveals which delivery systems retain commercial viability in maintained-registration markets versus those facing substitution pressure in phase-out regions.
Product Type:
Substitution pressure from biological fungicides and SDHI chemistry concentrates most intensely on legacy solid formulations, while precision-compatible liquid systems defend their positions.
- Wettable Powder:Dry powder formulations containing technical-grade active ingredient blended with dispersants and wetting agents. Cost-sensitive cereal applications in South Asia and Eastern Europe absorb volume, though biological alternatives are eroding share in greenhouse vegetable operations.
- Flowable:Aqueous suspension concentrates with reduced dust exposure and superior tank-mix compatibility. North American turf management channels and Brazilian commercial cooperatives prioritize these formulations for drone application compatibility and precision agriculture integration.
- Emulsifiable Concentrate:Oil-based solutions with surfactant packages enabling rapid dispersion. Commercial greenhouse operators favor these for systemic fungicide tank-mixing flexibility.
- Liquid Suspension:Stable aqueous dispersions with extended shelf stability. Large-scale field operations in Mato Grosso soybean belts specify these for aerial spraying efficiency.
- Granular:Slow-release matrix formulations for soil-borne disease suppression. Turf establishment and ornamental bed applications in Florida and Arizona absorb limited but stable volume.
Wettable powder anchors the volume base while flowable gains share at the steepest rate.
Application:
Margin concentration follows crop value intensity, with high-value protected cultivation commanding formulation premiums that commodity cereal applications cannot support.
- Vegetables:Intensive foliar spray programs in India's Uttar Pradesh and Maharashtra states drive wettable powder consumption. Farmers prioritize broad-spectrum contact activity against Alternaria and Cercospora in tomato and pepper production clusters.
- Turf Management:Golf course superintendents in Florida and Arizona specify micro-encapsulated flowable grades for reduced application frequency. Premium pricing power exceeds agricultural channels by substantial margins.
- Cereal Crops:Wheat and barley protection programs across Eastern Europe retain cost-optimized wettable powder specifications. Generic manufacturers compete primarily on delivered price per hectare.
- Fruits:Orchard applications in Brazil's citrus belt and Spanish citrus cooperatives face tightening EU residue limits. Producers are reformulating active ingredient loads to meet descending maximum residue levels.
- Ornamentals:Nursery stock and landscape plantings in North American amenity channels absorb specialized wettable powder and flowable grades.
- Floriculture:Protected rose and chrysanthemum production in the Netherlands and Spain increasingly substitutes biological fungicides for organochlorine contact products.
Vegetable applications concentrate the largest absolute volume while turf management captures the highest margin per treated hectare.
End User:
Procurement sophistication varies dramatically across user categories, with cooperative buying groups and integrated service providers rewriting traditional distribution economics.
- Commercial Farms:Large-scale soybean and cereal operations in Brazil and Eastern Europe negotiate direct technical-grade supply relationships. Volume commitments secure pricing leverage unavailable through distribution channels.
- Greenhouses:Dutch and Spanish vegetable cooperatives in Almería production clusters are disintermediating full-service crop protection contracts. Direct supplier relationships now represent substantial flowable concentrate offtake.
- Turf Managers:Golf course and sports field maintenance operations in North America specify premium micro-encapsulated formulations. Application frequency reduction justifies substantial price premiums over agricultural grades.
- Landscape Service Providers:Ornamental and amenity horticulture contractors in fragmented regional markets absorb standard wettable powder and emulsifiable concentrate specifications.
Commercial farms generate the highest tonnage demand while greenhouse cooperatives are restructuring procurement fastest.
Packaging Type:
Regulatory compliance costs and logistics efficiency are reshaping container specifications, with export-oriented producers investing in certification-ready packaging assets.
- Plastic Bottles:High-density polyethylene containers dominate retail-scale flowable and emulsifiable concentrate distribution. EPA and REACH labeling requirements drive specification standardization.
- Metal Drums:Steel containers with UN certification handle bulk technical-grade shipments from Chinese intermediate producers to downstream formulators.
- Jerry Cans:Stackable HDPE containers optimize pallet efficiency for mid-volume agricultural supply chains.
- Pouches:Flexible film packaging gains traction in Indian vegetable-growing states for wettable powder single-use sachets.
- Box Containers:Corrugated fiberboard with inner barriers serves granular and powder formulations in amenity horticulture channels.
Metal drums dominate international technical-grade trade while plastic bottles expand most quickly in finished formulation retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and India exhibit high price elasticity, absorbing cost-optimized wettable powder grades for commodity soybean and cereal applications. Turf managers in the United States pay substantial premiums for micro-encapsulated flowable formulations. Chinese intermediate producers face divergent compliance costs between export-oriented technical-grade supply and domestic formulation markets.
Brazil
Commercial farming cooperatives in Mato Grosso and Paraná drive flowable concentrate demand for aerial spraying compatibility with drone platforms. ANVISA residue monitoring aligns with EU import standards for Rotterdam-bound soybean shipments. The Mato Grosso soybean belt concentrates procurement volume as farmers intensify planting densities and prioritize broad-spectrum fungal coverage.
China
Captive isophthalonitrile production in Jiangsu and Shandong provinces supplies downstream formulators across Asia-Pacific export markets. MEE environmental compliance audits tier facility access, with audit-ready manufacturers capturing premium positioning in regulated jurisdictions. Yangtze River Delta chemical clusters absorb reactor reconfiguration costs for 98 percent technical-grade purity transitions.
India
Uttar Pradesh and Maharashtra vegetable farmers prioritize wettable powder economics for tomato and pepper foliar spray programs against Alternaria and Cercospora. CEA chemical handling standards add facility certification costs for producers serving domestic regulated markets. Almería-style cooperative buying groups remain underdeveloped, leaving distribution markups intact.
United States
Florida and Arizona golf course superintendents specify micro-encapsulated flowable grades at margins exceeding agricultural channels by substantial multiples. EPA re-registration reviews force label amendments and buffer zone investments that smaller formulators cannot absorb. Precision agriculture integration in North American turf management channels sustains premium pricing for tank-mix-compatible systems.
Netherlands
Almería tomato and pepper cooperatives disintermediate full-service crop protection contracts through direct technical-grade supplier relationships. ECHA REACH substance evaluation tightens tetrachloroisophthalonitrile metabolite limits in imported food commodities. Dutch and Spanish greenhouse operators unbundle fungicide procurement, capturing volume commitments and distribution bypass savings.
Global Chlorothalonil Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the chlorothalonil supply base. Integrated agrochemical platforms sustain premium positioning in flowable concentrate development, while captive intermediate producers anchor export volume through catalytic chlorination scale. The market structures around three archetypes: multinational formulation specialists, Chinese technical-grade suppliers with backward integration into isophthalonitrile, and regional generic manufacturers competing on delivered price per hectare. Dominant competitive moves include dual-track registration investments for maintained-registration versus phase-out markets, and reactor reconfiguration for 98 percent purity specifications.
Among Chinese technical-grade suppliers, Limin Group Co. Ltd. and Jiangsu Xinhe occupy positions defined by captive intermediate production and environmental audit readiness. Syngenta Group exemplifies the integrated multinational archetype, leveraging global registration infrastructure to sustain premium flowable positioning. FMC Corporation anchors North American turf management specialization. These three represent the structural divergence between cost-driven export volume and margin-defended premium channels.
| Leading Market Players |
|---|
| Jiangsu Xinhe |
| Limin Group Co. Ltd. |
| Syngenta Group |
| BASF SE |
| UPL Limited |
| SDS Biotech K.K. |
| Jiangsu Weunite |
| FMC Corporation |
| Jiangyin Suli |
| Others |
Supply & Pricing Matrix
Catalytic chlorination scale economies in Jiangsu and Shandong provinces concentrate technical-grade production among three to four integrated players, compressing price floors for export-oriented formulators while elevating entry barriers for non-captive producers. This concentration transmits directly into formulation tiering, with audit-ready manufacturers capturing premium positioning in EU REACH-compliant supply chains.
Pricing Analysis
EU REACH substance evaluation dictates the pricing tier structure across export markets, separating audit-ready producers from non-compliant suppliers. Three-tier pricing stratifies across premium flowable concentrates for North American turf, standard wettable powders for Brazilian soybean cooperatives, and economy grades for South Asian cereal applications. Cost compression in wettable powder tiers is intensifying because biological fungicide substitution erodes volume commitments. Brazilian commercial farms exhibit the highest price elasticity, while Florida golf course superintendents absorb substantial premiums for micro-encapsulated formulations.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Rotterdam trade lane expose just-in-time formulators to technical-grade delivery interruptions. Supply concentrates in China's Yangtze River Delta, with secondary formulation hubs in India and Brazil. Isophthalonitrile feedstock, dispersant packages, and surfactant blends draw from petrochemical and specialty chemical streams. Single-source vulnerability in Chinese intermediate production creates structural risk. Distribution runs through technical-grade bulk shipments to downstream formulators, then finished formulation retail through agricultural supply cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around dual-track EPA and EU registration dossiers creates formidable defensive moats for incumbent producers with established compliance infrastructure. Switching costs for downstream formulators rise with each label amendment cycle.
For Market Incumbents: Secure dual-registration maintenance capabilities by building parallel scientific teams for EPA re-registration reviews and ECHA REACH dossier updates. Anchor capacity addition in audit-ready Chinese manufacturing assets to capture tiered supply access under MEE environmental compliance protocols. Biological fungicide substitution in greenhouse vegetable operations and SDHI chemistry displacement threaten contact-activity market share, requiring accelerated flowable concentrate R&D in drone-compatible delivery systems. For New Entrants and Emerging Players: Differentiate on environmental audit readiness as the primary axis, targeting technical-grade supply relationships with Indian CEA-certified facilities serving domestic regulated markets. The most penetrable white-space sits in Uttar Pradesh and Maharashtra vegetable-growing states, where cooperative buying groups remain underdeveloped and distribution markups persist. A direct-to-cooperative go-to-market angle bypasses established full-service crop protection contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors producers with captive isophthalonitrile production and 98 percent technical-grade purity capabilities. Long-term viability over a five-to-ten year window hinges on maintaining registrations in Brazil and India while EU phase-out jurisdictions decline. Acquisition targets should display backward integration into catalytic chlorination capacity and MEE audit certification. The signal to watch is ANVISA alignment with EU residue standards tightening for Rotterdam-bound soybean shipments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isophthalonitrile | Captive intermediate production insulates Jiangsu-based formulators from feedstock cost volatility. |
| MEE Environmental Compliance Certification | Audit-ready manufacturing assets unlock tiered supply access to EU REACH-regulated export markets. |
| Flowable Concentrate Technology Investment | Drone-compatible formulations capture premium positioning in Brazilian Mato Grosso aerial spraying cooperatives. |
| Dual-Track Registration Dossier Maintenance | Parallel EPA and ECHA scientific teams defend market access across maintained-registration and phase-out jurisdictions. |
| Direct Cooperative Supply Relationships | Bypassing distribution markups in Almería-style greenhouse clusters compresses customer acquisition costs. |
Research Methodology
A spread of perspectives from agrochemical plant managers, downstream formulator procurement leads, Brazilian cooperative buying group representatives, and ECHA regulatory affairs specialists converged on the working assumptions around dual-track registration investments and purity transition timelines. Primary interview insights combined with secondary validation from customs trade data, SEC 10-K filings of listed agrochemical producers, EPA re-registration review documents, and ECHA REACH substance evaluation dossiers. Bottom-up technical-grade production estimates and top-down formulation demand projections underwent iterative triangulation.
Segmentation dimensions modeled span formulation type, application crop, end-user procurement sophistication, and regional regulatory cluster across the projection horizon. CAGRs derived from annualized growth rate calculations applied to base-year value and volume estimates. Industry-specific forecast inputs include isophthalonitrile capacity utilization rates in Chinese chemical clusters and Brazilian soybean planting density intensification curves.
The analysis sits within stated boundaries; outcomes outside maintained EU registrations or accelerated EPA phase-out timelines would require recalibration. Forecasts reflect documented assumptions around regulatory divergence persistence and biological substitution rates in protected cultivation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Mining Explosives Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Global Dodecanedioic Acid Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Europe Modified Bitumen Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Industrial Closures Market