
 Asia-Pacific Activated Carbon Market | 2026-2036
Asia-Pacific Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Activated Carbon Market Analytics
Water treatment is restructuring demand patterns across the Asia-Pacific activated carbon landscape. Kuraray Co Ltd anchors Japanese supply through specialized phenolic resin-based products for semiconductor process water. Kureha Corporation dominates high-performance spherical activated carbon for pharmaceutical and medical applications. Osaka Gas Co Ltd leverages its integrated carbon fiber technology pipeline to sustain R&D intensity in advanced adsorption materials.
Activated carbon comprises a highly porous form of carbon processed to achieve extensive internal surface area, typically ranging from 500 to 1,500 square meters per gram, engineered primarily for adsorption of organic compounds, color bodies, and contaminants from liquid and gas streams. Granular activated carbon commands the largest volume position in municipal and industrial water treatment infrastructure across the region. Powdered activated carbon competes in seasonal taste-and-odor control and emergency response applications where rapid deployment outweighs regeneration economics. Coconut shell sourced material is capturing margin pools as beverage and food processors prioritize low-ash, high-hardness carbon for decolorization and purification duties.
China's Ministry of Ecology and Environment enforces tightening effluent standards that compel industrial facilities to upgrade activated carbon systems or face operational penalties. Japan's METI promotes circular economy frameworks that incentivize thermal reactivation services and spent carbon recovery networks. India's Central Pollution Control Board mandates specific adsorption capacity benchmarks for common effluent treatment plants serving textile and dyeing clusters. Stakeholders must weigh feedstock security against reactivation infrastructure investments as regulatory stringency diverges across national boundaries.
Market Dynamics
Coconut shell feedstock is displacing coal-based carbon across Asia-Pacific manufacturing networks as sustainability mandates from Japan's METI and China's MEE restructure procurement specifications and supplier qualification protocols.
Growth Catalysts
- Semiconductor process water purity mandates:Fabrication facilities in eastern China and South Korea now specify ultra-high purity activated carbon for removing trace organics from rinse water, creating specialized demand pools that command technical premiums over commodity grades.
- MEE effluent standard tightening:China's Ministry of Ecology and Environment now enforces discharge limits that compel textile, petrochemical, and electronics manufacturers to upgrade granular activated carbon systems or face operational suspension.
- Circular economy frameworks:Japan's METI incentivizes thermal reactivation infrastructure and spent carbon recovery networks, extending effective carbon life cycles and creating service revenue streams for equipment suppliers.
Market Restraints
- Coconut shell supply concentration:Premium feedstock availability depends heavily on Sri Lankan and Indonesian agricultural harvest cycles, exposing processors to weather-driven price volatility and geopolitical sourcing risk.
- Coal-based carbon displacement friction:Existing municipal water treatment infrastructure in India and Southeast Asia was engineered around bituminous coal feedstock specifications, creating technical and economic barriers to rapid feedstock switching.
- Reactivation infrastructure gaps:Thermal regeneration facilities remain concentrated in Japan and eastern China, leaving Southeast Asian and Indian users dependent on virgin carbon replacement rather than cost-efficient reactivation cycles.
Strategic Opportunities
- India's Central Pollution Control Board mandates:Specific adsorption capacity benchmarks for common effluent treatment plants serving textile and dyeing clusters create standardized demand specifications that favor qualified suppliers with proven performance documentation.
- Powdered activated carbon emergency response protocols:Municipal utilities across Southeast Asia are formalizing rapid-deployment frameworks for seasonal taste-and-odor events, creating recurring spot demand outside conventional granular carbon procurement cycles.
- Spherical activated carbon medical applications:Hemoperfusion and pharmaceutical purification specifications in Japan and South Korea reward specialized manufacturing capabilities that commodity producers cannot easily replicate.
Industry Challenges
- Reactivation technician scarcity:Thermal regeneration operations require specialized furnace management and quality control expertise that remains concentrated among Japanese and Korean engineering teams, constraining regional capacity expansion.
- Feedstock certification complexity:Beverage and food processors now demand chain-of-custody documentation for coconut shell sourcing that many Southeast Asian suppliers cannot yet provide, disqualifying them from premium segment participation.
- Legacy system integration:Industrial facilities upgrading from single-pass to regenerable activated carbon systems face significant piping, control, and wastewater handling modifications that extend project timelines and capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Activated Carbon Market |
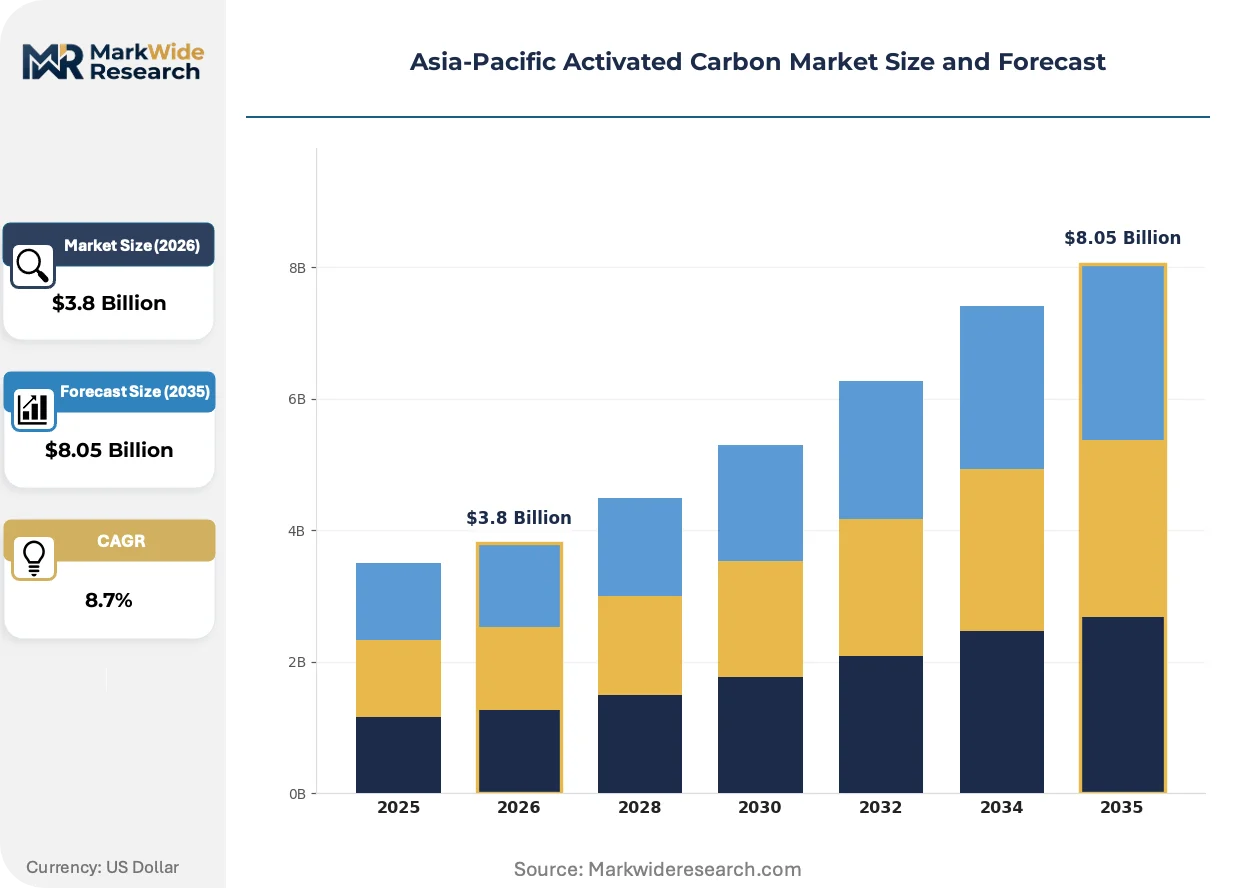
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Activated Carbon, Powdered Activated Carbon, Pelletized Activated Carbon, Extruded Activated Carbon End Use Industry: Water Treatment, Air Purification, Food & Beverage, Pharmaceutical Application: Gas Adsorption, Liquid Phase Adsorption, Catalytic Applications, Medical Applications Source Material: Wood, Coal, Coconut Shell, Peat |
| Companies Covered | Osaka Gas Co Ltd, Kuraray Co Ltd, Kureha Corporation, Haycarb PLC, Cabot Corporation, Donau Carbon GmbH, Oxbow Activated Carbon LLC, BASF SE, Silcarbon Aktivkohle GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Activated Carbon Market Evolving Landscape
Phenolic resin-based activated carbon formulations are capturing specialized demand segments as semiconductor and pharmaceutical end-users prioritize batch-to-batch consistency and ultra-low extractable profiles over commodity cost economics.
Impregnated activated carbon variants engineered for mercury and hydrogen sulfide removal are consolidating technical specifications across coal-fired power and natural gas processing applications in China and India. Plant operators now specify these functionalized grades rather than maintaining separate adsorbent inventories for different contaminant streams. This consolidation is compressing supplier margins on standard unimpregnated products while rewarding chemical treatment capabilities.
China's GB standards for drinking water treatment chemicals now mandate specific iodine number and methylene blue adsorption minimums that exceed previous industry practice. Municipal procurement departments have revised technical specifications accordingly, disqualifying lower-grade imports and favoring domestic producers with certified testing protocols. Eastern Chinese manufacturers have invested in automated quality control systems to maintain consistent compliance documentation.
Integrated service contracts now bundle activated carbon supply with spent carbon removal and reactivation scheduling for large industrial users in Japan and South Korea. Chemical processors and food manufacturers are outsourcing adsorption system management rather than maintaining in-house carbon handling operations. This model is most visible in the Kanto and Kansai industrial corridors where logistics networks support efficient carbon exchange cycles.
Asia-Pacific Activated Carbon Market Segmentation
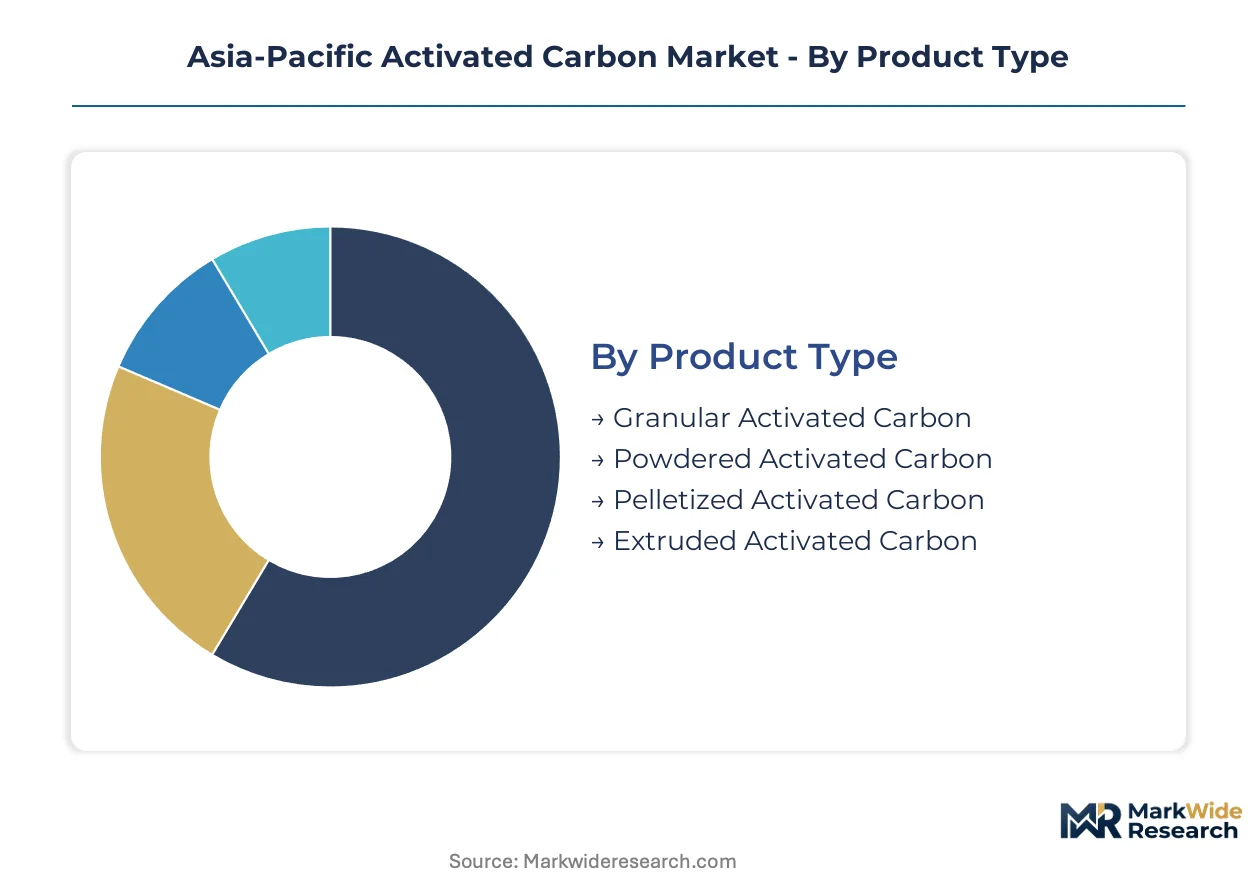
Activated carbon segmentation in Asia-Pacific tracks divergent procurement logics across industrial utilities, semiconductor fabs, and food processors. Product form, feedstock origin, and purity grade determine supplier qualification pathways and pricing bandwidths in this fragmented supply landscape.
Product Type:
Engineering specifications and regeneration economics drive buyer selection between fixed-bed and dispersible carbon forms.
- Granular Activated Carbon:Irregular-shaped particles sized 0.2-5 mm dominate fixed-bed filtration infrastructure. Municipal water utilities in eastern China and industrial effluent treatment plants across the Pearl River Delta specify this form for its pressure-drop characteristics and thermal reactivation compatibility.
- Powdered Activated Carbon:Finely ground particles below 0.18 mm serve rapid-response applications where batch dosing outweighs recovery economics. Seasonal taste-and-odor events in Southeast Asian reservoir systems and emergency spill response protocols generate spot demand outside long-term supply contracts.
- Pelletized Activated Carbon:Cylindrical extrusions optimize gas-phase pressure drop in vapor recovery units and air treatment systems. Petrochemical clusters in South Korea specify uniform pellet dimensions for automated handling systems.
- Extruded Activated Carbon:Mechanically compressed forms balance hardness with adsorption kinetics for specialty chemical processing. Pharmaceutical solvent recovery operations in Japan favor this grade for consistent bed packing density.
Volume sits with granular forms in municipal infrastructure; growth tilts toward powdered variants in emergency response frameworks.
End Use Industry:
Regulatory enforcement intensity and discharge standard timelines create divergent demand cycles across vertical markets.
- Water Treatment:Municipal utilities and industrial effluent systems represent the foundational demand base. China's MEE enforcement actions against textile and electronics manufacturers sustain upgrade cycles for granular carbon systems in the Yangtze and Pearl River basins.
- Air Purification:Indoor air quality mandates and industrial emission controls expand activated carbon deployment in HVAC and stack gas treatment. Coal-fired power plants in India specify impregnated grades for mercury capture compliance.
- Food & Beverage:Decolorization and deodorization duties in sugar refining, edible oil processing, and alcoholic beverage production command low-ash, high-hardness coconut shell material. Sri Lankan and Indonesian sourcing documentation requirements increasingly filter supplier pools.
- Pharmaceutical:Ultra-high purity specifications for active pharmaceutical ingredient purification and solvent recovery reward batch-to-batch consistency. Japanese and South Korean manufacturers dominate this technical premium segment.
Water treatment commands current procurement volumes; pharmaceutical and food-grade specifications are climbing the fastest.
Application:
Mass transfer requirements and contaminant chemistry determine the functional carbon selection for each adsorption task.
- Gas Adsorption:Vapor-phase contaminant removal from air and process gas streams requires specialized pore size distributions. Natural gas processing facilities in Australia and industrial solvent recovery units deploy activated carbon for hydrocarbon and volatile organic compound capture.
- Liquid Phase Adsorption:Dissolved organic removal from water and process liquids constitutes the largest application volume. Surface water treatment plants across Southeast Asia and semiconductor rinse water systems in Taiwan and South Korea drive specification refinement.
- Catalytic Applications:Activated carbon serves as catalyst support or participates directly in chemical transformation processes. Chemical manufacturers in eastern China employ carbon-supported catalysts for hydrogenation and oxidation reactions.
- Medical Applications:Hemoperfusion cartridges and pharmaceutical purification systems demand spherical activated carbon with ultra-low extractable profiles. Japanese medical device manufacturers and South Korean dialysis suppliers source from specialized phenolic resin-based production lines.
Liquid phase systems absorb the majority of regional volume; medical and catalytic applications show the steepest expansion trajectory.
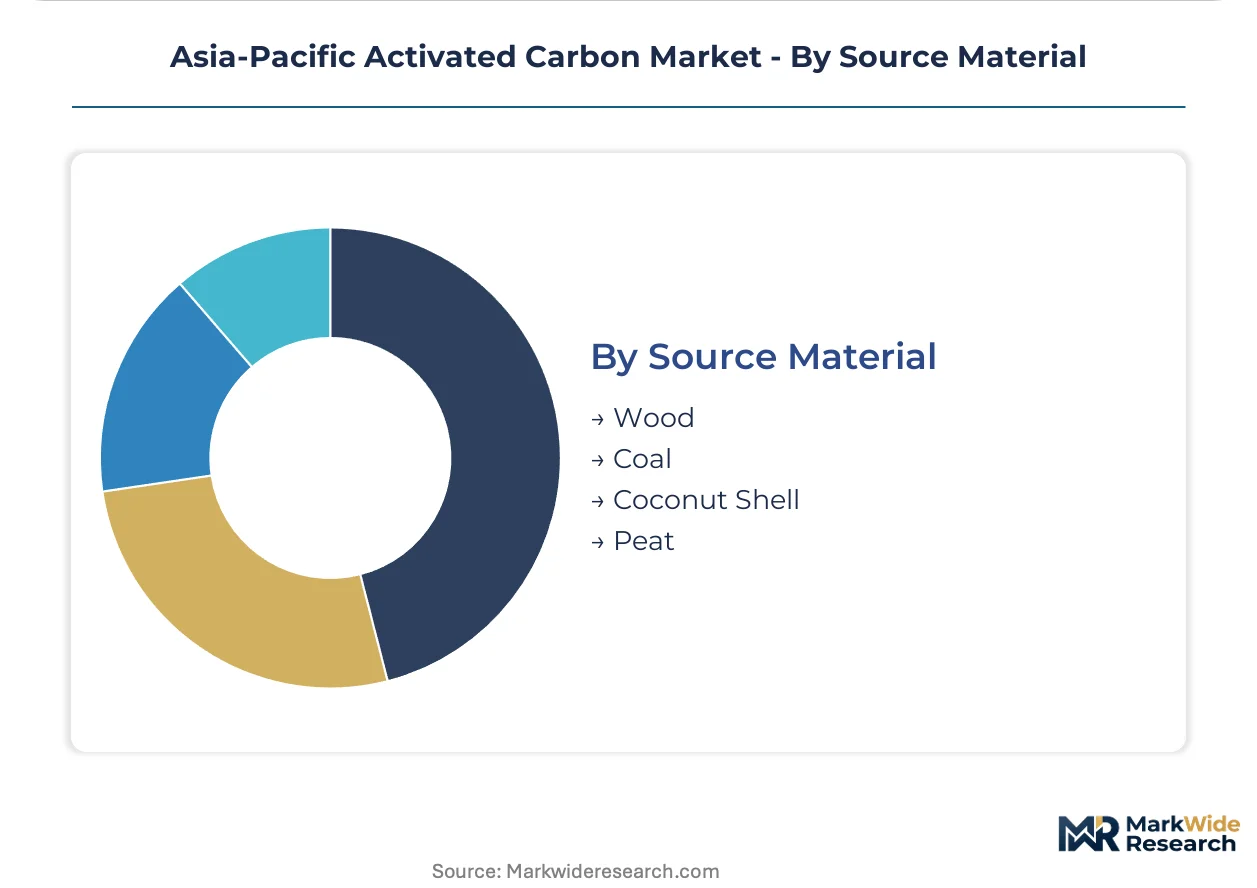
Source Material:
Feedstock provenance increasingly determines carbon pricing tiers and customer qualification status under sustainability mandates.
- Wood:Hard and soft wood precursors yield mesoporous carbon suited for decolorization and large-molecule adsorption. Pulp and paper industry byproduct sourcing in northern China and Southeast Asia supports regional production cost structures.
- Coal:Bituminous and sub-bituminous feedstocks provide macroporous carbon for general water treatment. Existing municipal infrastructure in India and legacy industrial systems retain coal-based specifications despite sustainability-driven displacement pressure.
- Coconut Shell:Agricultural waste from tropical harvesting generates microporous, high-hardness, low-ash carbon preferred for drinking water and food-grade applications. Sri Lankan and Indonesian supply concentration creates procurement risk that Japanese and Chinese processors hedge through multi-origin contracting.
- Peat:Partially decomposed organic matter yields carbon with intermediate porosity characteristics for specialty chemical applications. Limited commercial scale in Asia-Pacific confines this feedstock to niche European-imported material.
Coal retains volume leadership in legacy infrastructure; coconut shell sourcing is gaining share fastest under METI and MEE sustainability procurement guidelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across eastern China concentrate activated carbon demand as semiconductor fabs and petrochemical clusters expand ultra-high purity filtration capacity. Tax incentives in Yangtze River Delta development corridors accelerate infrastructure investment timelines.
China
Petrochemical complexes in Jiangsu and Zhejiang provinces drive granular activated carbon procurement for process water treatment. MEE effluent enforcement actions compel textile manufacturers in Shaoxing and Nantong to upgrade adsorption systems or face operational suspension. Yangtze River Delta cities now specify coconut shell material for municipal drinking water plants under sustainability procurement guidelines.
Japan
Semiconductor rinse water specifications from Tokyo Electron and Shin-Etsu Chemical sustain demand for phenolic resin-based activated carbon with ultra-low extractable profiles. METI circular economy frameworks incentivize thermal reactivation infrastructure investment across Kanto and Kansai industrial corridors. Osaka-based medical device manufacturers source spherical activated carbon for hemoperfusion cartridges under PMDA quality protocols.
India
Textile dyeing clusters in Surat and Tiruppur expand common effluent treatment plant capacity to meet Central Pollution Control Board adsorption benchmarks. Coal-based carbon dominates legacy municipal infrastructure in Delhi and Mumbai despite sustainability displacement pressure. Western and southern industrial zones now trial coconut shell feedstock for food-grade decolorization applications.
South Korea
Memory chip fabrication facilities in Giheung and Pyeongtaek specify ultra-high purity activated carbon for removing trace organics from rinse water. MFDS pharmaceutical purification standards reward batch-to-batch consistency in solvent recovery operations. Busan-Ulsan petrochemical complexes deploy pelletized carbon for vapor recovery unit optimization.
Southeast Asia
Municipal utilities in Bangkok and Jakarta expand granular carbon filtration to meet tightening discharge standards for surface water treatment. Indonesian and Sri Lankan coconut shell harvests supply regional processors with low-ash, high-hardness feedstock. Seasonal taste-and-odor events across Mekong River basin reservoirs generate spot demand for powdered activated carbon emergency response protocols.
Asia-Pacific Activated Carbon Market Competitive Landscape
Top-tier vendors anchor premium specialty segments, while mid-scale fabricators compete on feedstock security and reactivation service bundling. Japanese chemical conglomerates dominate spherical and phenolic resin-based formulations for medical and semiconductor applications. Regional specialists concentrate on coconut shell sourcing networks across Indonesian and Sri Lankan supply bases. Competitive moves center on backward integration into feedstock plantations and multi-year service contracts bundling carbon supply with spent material recovery.
Within the premium specialty tier, Kuraray Co Ltd and Kureha Corporation exemplify Japanese precision manufacturing archetypes focused on batch consistency and ultra-low extractable specifications. Osaka Gas Co Ltd occupies a distinctive position leveraging integrated carbon fiber technology pipelines for advanced adsorption material development. Among Southeast Asian feedstock-integrated processors, Haycarb PLC represents the agricultural waste valorization model securing multi-origin coconut shell contracts. Cabot Corporation and BASF SE sit within the multinational diversified materials archetype, competing through global logistics networks and impregnated carbon formulation capabilities for industrial gas treatment applications.
| Leading Market Players |
|---|
| Osaka Gas Co Ltd |
| Kuraray Co Ltd |
| Kureha Corporation |
| Haycarb PLC |
| Cabot Corporation |
| Donau Carbon GmbH |
| Oxbow Activated Carbon LLC |
| BASF SE |
| Silcarbon Aktivkohle GmbH |
| Others |
Value Network & Pricing Analysis
Coconut shell commodity indices from Colombo and Jakarta trading posts cascade through Asia-Pacific activated carbon pricing tiers, compressing margins for coal-based processors while rewarding feedstock-integrated suppliers with METI and MEE sustainability procurement qualifications.
Pricing Analysis
Short lead-time premiums for emergency powdered carbon deployments in Southeast Asian reservoir systems command substantial markups over contract granular volumes. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certification levels separates ultra-high purity phenolic resin formulations from commodity bituminous coal material. Cost compression in standard municipal water treatment grades intensifies as Chinese domestic producers automate quality control systems. Industrial effluent processors exhibit highest price sensitivity due to MEE compliance-driven procurement volumes, while semiconductor fabs prioritize batch consistency over unit economics.
Supply Chain Analysis
Specialized furnace technicians in Osaka and Seoul engineering clusters constrain thermal reactivation capacity expansion across Southeast Asian markets. Feedstock supply concentrates in Sri Lankan and Indonesian coconut harvesting regions, with secondary sourcing from Philippine and Vietnamese agricultural waste streams. Raw material procurement draws from tropical shell harvests, phenolic resin precursors, and bituminous coal deposits. Single-source vulnerability in Sri Lankan feedstock exposes processors to monsoon-driven supply interruptions. Distribution runs through integrated service contracts bundling carbon supply with spent material recovery scheduling for Japanese and South Korean chemical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific activated carbon market functions as a vertical-integration race where feedstock plantation control and captive reactivation infrastructure determine margin capture. Players are pursuing backward integration into Sri Lankan and Indonesian coconut shell sourcing networks to secure supply under METI sustainability mandates.
For Market Incumbents: Anchor market position through multi-year service contracts bundling carbon supply with thermal reactivation scheduling for semiconductor and pharmaceutical end-users. Defend against emerging Chinese domestic producers by investing in automated quality control systems that maintain GB standards compliance documentation. Prioritize certification investment for PMDA and MFDS pharmaceutical-grade protocols to sustain technical premium capture. For New Entrants and Emerging Players: India's Central Pollution Control Board mandates for common effluent treatment plants open a window for qualified suppliers with proven adsorption capacity documentation to penetrate Surat and Tiruppur textile clusters. Target municipal water utilities across Mekong River basin cities for powdered activated carbon emergency response frameworks where rapid deployment specifications favor agile suppliers over incumbent volume players. Pursue direct technical sales engagement with plant engineering teams rather than distributor channel reliance. For Investors and Strategic Acquirers: The window for entry favors feedstock-integrated mid-cap specialists with established Sri Lankan or Indonesian plantation relationships and existing reactivation infrastructure. Long-term viability hinges on sustainability certification depth rather than commodity scale economics. Monitor coconut shell harvest yield volatility and MEE enforcement intensity across Yangtze River Delta industrial zones as inflection indicators for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Plantations | Coconut shell plantation control in Sri Lanka secures supply under METI sustainability procurement guidelines. |
| Thermal Reactivation Infrastructure Expansion | Furnace capacity additions in Kanto and Kansai corridors capture circular economy service revenue streams. |
| Pharmaceutical-Grade Certification Investment | PMDA and MFDS spherical carbon protocols unlock hemoperfusion and solvent recovery premium segments. |
| Integrated Service Contract Bundling | Carbon supply plus spent material recovery scheduling deepens customer switching costs in Japan and South Korea. |
| Automated Quality Control System Deployment | GB standards compliance documentation qualifies Chinese domestic producers for municipal procurement tenders. |
Research Methodology
Independent corroboration across customs trade databases, MEE enforcement action records, and METI circular economy policy filings underwrites the qualitative findings in this study. Primary interviews with activated carbon plant managers, municipal water utility procurement directors, semiconductor fab process engineers, and thermal reactivation furnace operators combined with secondary validation from SEC 10-K filings of listed chemical conglomerates and Sri Lankan Coconut Development Authority harvest statistics. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Rate-of-change decomposition across feedstock substitution velocity, reactivation infrastructure deployment pace, and regulatory enforcement intensity frames the analytical approach. Segmentation dimensions modeled include product form, source material provenance, end-use industry vertical, and application chemistry. CAGRs derive from weighted average of demand driver elasticities and supply constraint coefficients. Industry-specific forecast inputs incorporate semiconductor fab construction pipelines and textile cluster effluent treatment plant upgrade cycles.
The model assumes a particular technology adoption path; alternative pathways for phenolic resin-based spherical carbon would alter the outlook if semiconductor rinse water specifications shift toward membrane-based organic removal. Forecasts reflect documented assumptions regarding METI circular economy incentive continuity and MEE enforcement intensity trajectories. Material deviation in coconut shell harvest yields or GB standards revision timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
Commercial Electronic Detonator Market