
 Welding Electrodes Market | 2026-2036
Welding Electrodes Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Electrodes Market Intelligence
Consolidation among specialty alloy producers in Europe is shifting the raw material cost structure for electrode manufacturers. This environment tests the supply chain resilience of major firms. Lincoln Electric Holdings, Inc. leverages its global manufacturing footprint to manage input costs and ensure consistent supply. ESAB differentiates through its extensive portfolio of filler metals and equipment, catering to specialized industrial applications across various geographies.
A welding electrode is a coated metal wire, typically composed of materials similar to the metal being welded, that conducts current to create an electric arc. The coating provides a gaseous shield to protect the weld pool from atmospheric contamination and adds alloying elements. Rutile electrodes maintain a dominant share due to their versatility in general fabrication applications. However, low hydrogen electrodes are seeing increased use, driven by stringent quality requirements in pipeline fabrication and heavy machinery.
Product quality and safety are governed by international standards like ISO 2560 for covered electrodes and regional directives such as the EU's CE marking for construction products. Regulations from bodies like the U.S. EPA on fume generation during welding also influence electrode coating formulations. Stakeholders must monitor the evolution of material standards for high-strength alloys, which will dictate future R&D priorities for electrode chemistries.
Market Dynamics
The imperative to weld advanced high-strength steels and specialty alloys in critical infrastructure projects defines the market's core tension. This material science evolution necessitates a parallel advancement in electrode chemistries to ensure weld integrity, driving R&D and segmenting the market by performance.
Growth Catalysts
- Infrastructure Expansion:Large-scale infrastructure programs, particularly in China and India, for transportation networks and energy grids create sustained volume demand for general and specialized welding consumables.
- Renewable Energy Projects:The fabrication of wind towers, offshore platforms, and geothermal plants requires high-performance electrodes capable of withstanding extreme environmental stress and fatigue, stimulating demand for premium products.
- Advanced Material Adoption:The increasing use of advanced high-strength steels (AHSS) and non-ferrous alloys in automotive and aerospace manufacturing demands new electrode formulations to achieve specific metallurgical properties in the weld.
Market Restraints
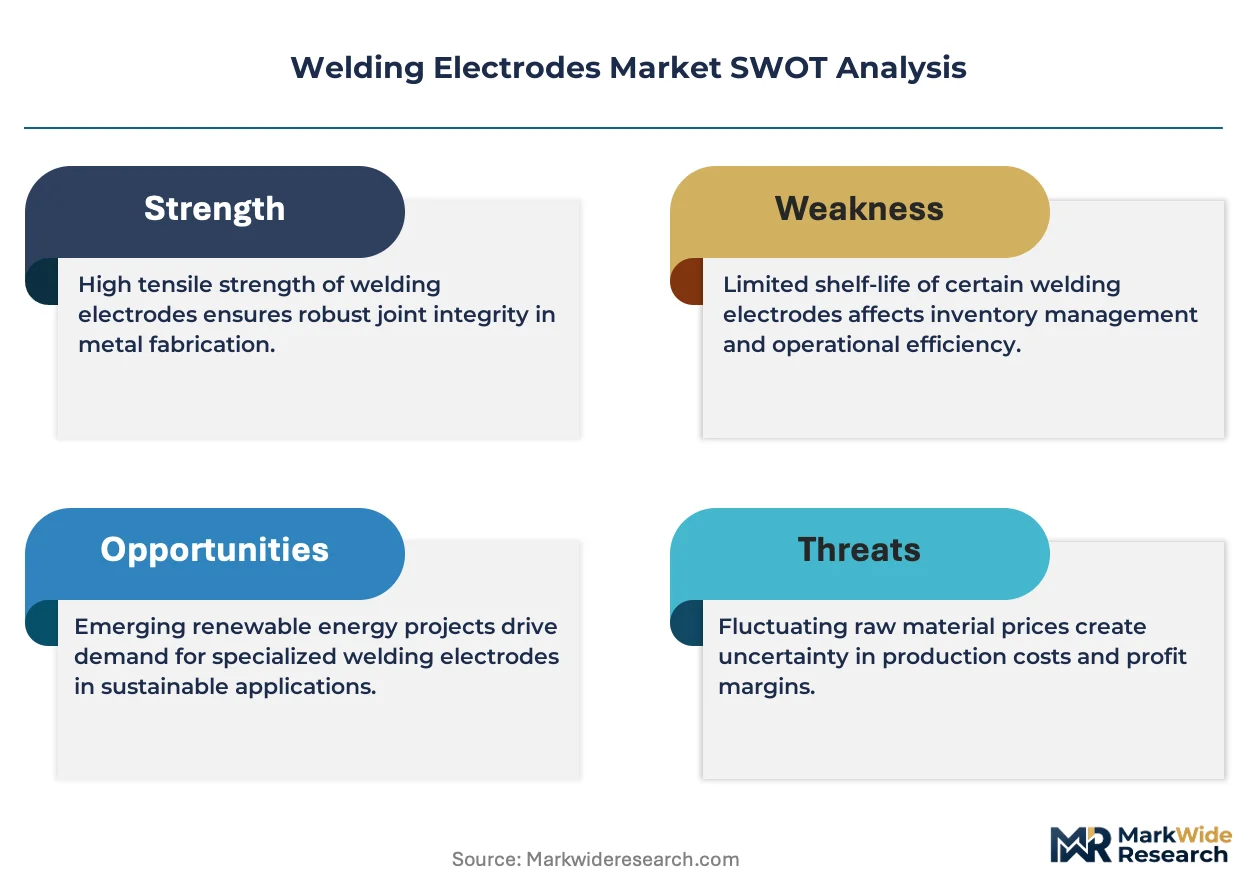
- Raw Material Volatility:Price and supply instability for key minerals like rutile, ilmenite, and manganese, which are sourced from geographically concentrated mines, creates significant cost pressure for electrode manufacturers.
- Threat from Automation:The growing adoption of automated and robotic welding processes, such as Gas Metal Arc Welding (GMAW) and Submerged Arc Welding (SAW), displaces the manual application of covered electrodes in high-volume manufacturing.
- Regulatory Scrutiny:Health and safety regulations, such as those from the U.S. EPA on welding fume constituents like manganese, compel costly research into alternative coating formulations and may restrict the use of certain electrodes.
Strategic Opportunities
- Wire-Arc Additive Manufacturing:The emergence of WAAM as a method for rapid prototyping and manufacturing large metal parts presents a high-value opportunity for developing specialized electrode wires tailored for 3D printing applications.
- Emerging Market Infrastructure:Rapid industrialization and infrastructure build-outs in Southeast Asian countries, including Vietnam and Indonesia, offer new growth frontiers for electrode suppliers outside of traditional markets.
- Low-Hydrogen Electrode Demand:Stringent quality and safety standards in the oil and gas pipeline and nuclear power sectors create a durable, non-discretionary market for premium, certified low-hydrogen electrodes.
Industry Challenges
- Skilled Welder Shortage:A persistent global deficit of certified welders qualified for high-pressure and critical structural welding limits the application of advanced welding procedures and can constrain project execution.
- Certification Complexity:Navigating the complex and time-consuming certification processes, such as ISO standards, CE marking, and specific end-user approvals from naval or energy entities, delays new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Electrodes Market |
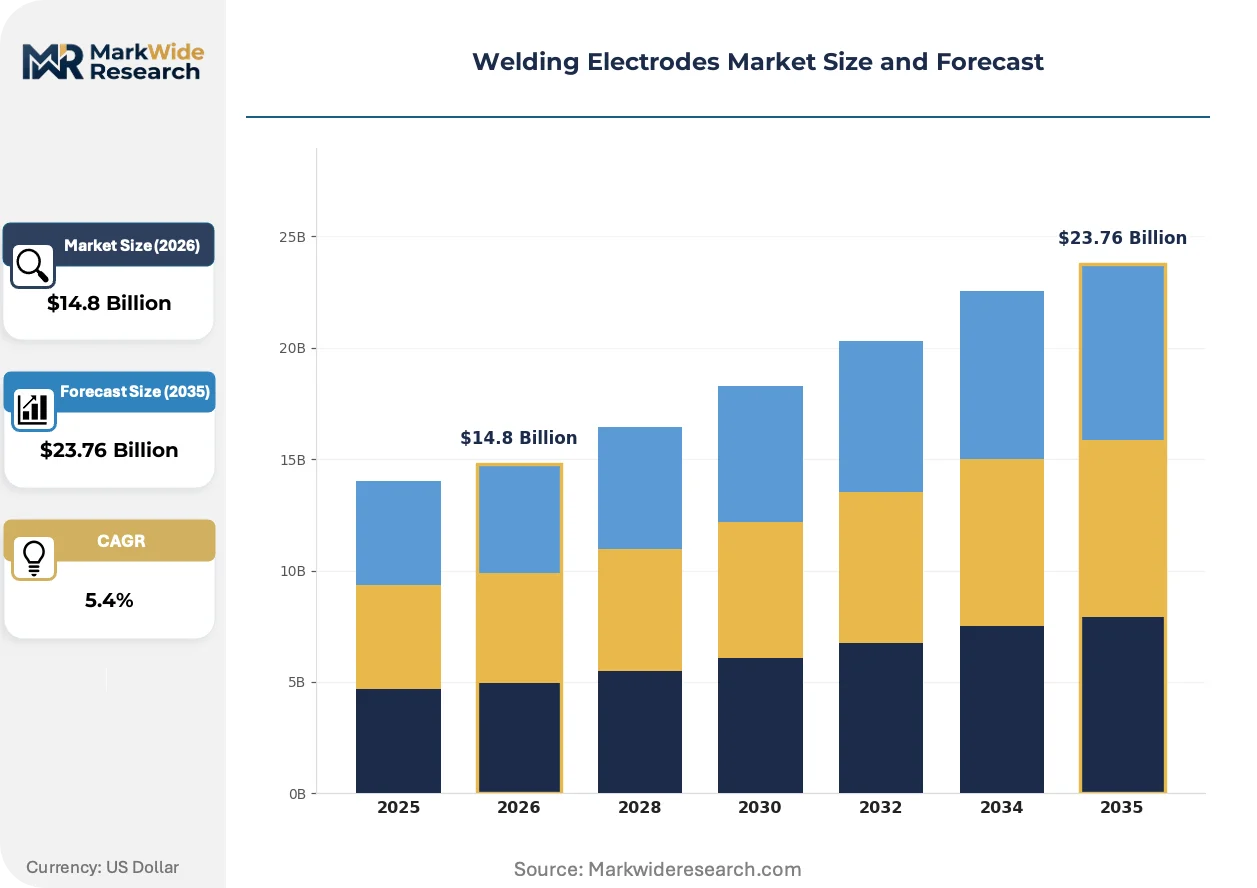
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic, Cellulosic, Rutile, Acid, Low Hydrogen Technology: SMAW, GMAW, FCAW, GTAW, SAW Application: Construction, Shipbuilding, Pipeline Fabrication, Heavy Machinery, Aerospace End User Industry: Manufacturing Plants, Fabrication Workshops, Energy Sector, Defense Contractors |
| Companies Covered | Kobe Steel Welding & Construction Co., Ltd., ThyssenKrupp Schulte GmbH, Lincoln Electric Holdings, Inc., Miller Electric Mfg. LLC, Arcos Welding, ESAB, Böhler Welding, voestalpine AG, Haifei Intelligent Equipment Co., Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Electrodes Market Strategic Shifts & Innovations
Digitalization of the welding workflow and a heightened focus on environmental and operator safety are reshaping product development and competitive strategy. Electrode formulations are evolving to meet stricter fume regulations, while data connectivity is transforming quality assurance from a post-weld inspection to a real-time process.
Digital welding information systems capture and log real-time parameters like amperage and voltage directly from the power source. The pipeline and aerospace sectors are early adopters, using the data for complete weld traceability. This technology is integrating electrode performance characteristics with project-wide quality management systems, enabling predictive maintenance and defect analysis.
The European Union's REACH framework imposes strict controls on chemical substances, directly impacting the composition of electrode coatings. This regulation forces ongoing R&D to find substitutes for materials of concern, such as certain chromium compounds, without degrading arc stability or mechanical properties. The heavy machinery and shipbuilding industries are most affected, driving demand for compliant, low-fume electrodes.
A notable behavioral shift is occurring, where end-users evaluate consumables based on total cost of operation rather than price per stick. This model disrupts traditional distribution channels by emphasizing factors like deposition rate, spatter level, and reduced need for post-weld grinding. This trend is most prominent within the automated fabrication segments in North America and Western Europe.
Welding Electrodes Market Segmentation
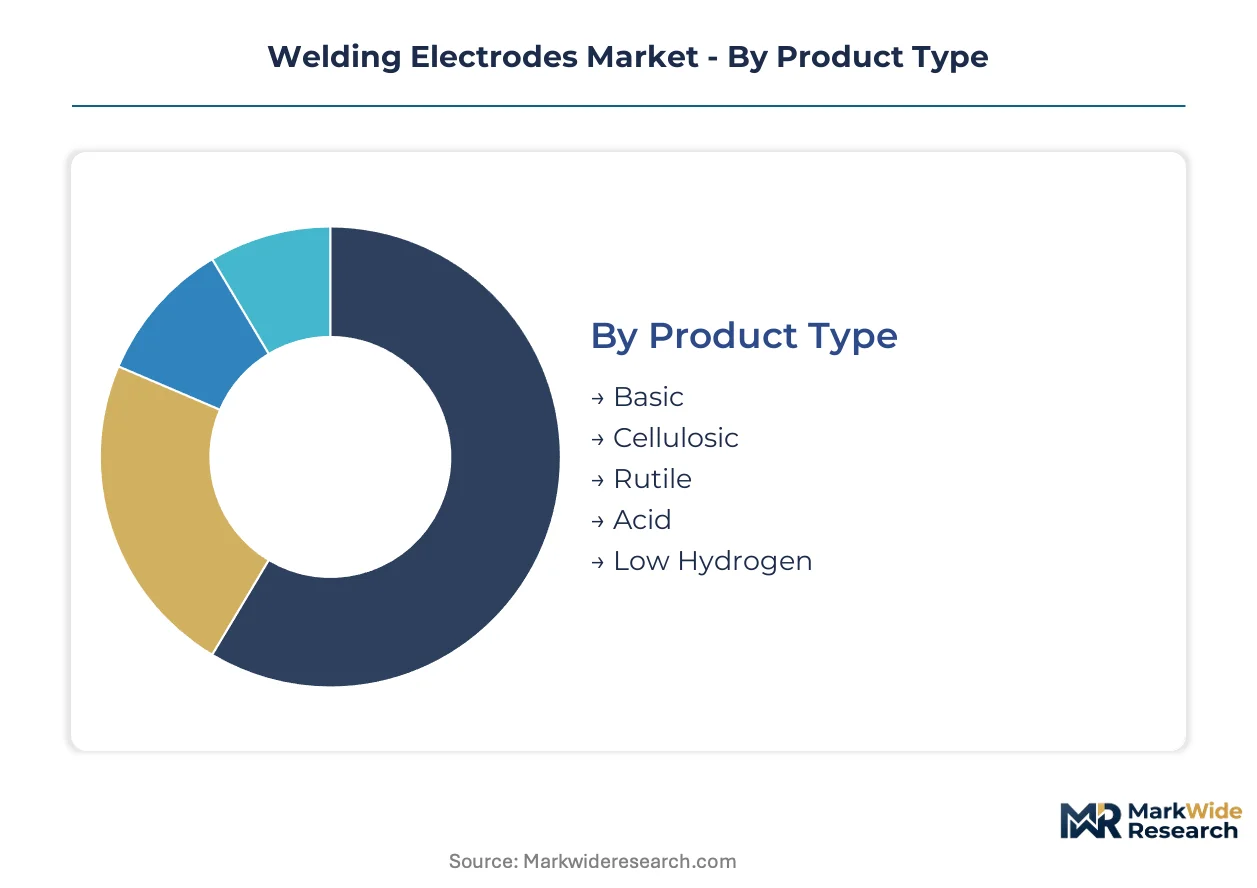
Segmentation clarifies the diverse performance requirements and operational contexts within the welding electrodes market. Understanding distinct product types, technologies, and applications illuminates specific demand drivers. This granular view helps manufacturers align product development with evolving industry needs.
Product Type:
The upgrade and replacement cycles for welding electrodes are fundamentally shaped by the specific product types demanded for various material and structural requirements.
- Basic:Electrodes with a basic coating, offering excellent mechanical properties and crack resistance, often used for critical structural applications.
- Cellulosic:Fast-freezing slag electrodes, providing deep penetration and high deposition rates, commonly employed in pipeline root passes.
- Rutile:Coated electrodes providing a smooth arc and easy slag removal, suitable for general fabrication across diverse sectors. High demand comes from infrastructure projects in China and India, where versatility and ease of use are prioritized.
- Acid:Electrodes producing a fluid slag and good bead appearance, primarily used for general repair and maintenance in less critical applications.
- Low Hydrogen:Electrodes designed to minimize hydrogen content in the weld metal, crucial for preventing cracking in high-strength steels. Pipeline fabrication and heavy machinery sectors in North America require these for critical welds under extreme stress.
Volume placements concentrate in Rutile electrodes; the faster expansion belongs to Low Hydrogen electrodes.
Technology:
Application versatility and process efficiency drive the differentiation across welding technologies, influencing electrode consumption patterns.
- SMAW (Shielded Metal Arc Welding):A manual process using covered electrodes, highly versatile for various materials and field conditions. Construction projects globally rely on SMAW for its adaptability and equipment portability, particularly in remote areas.
- GMAW (Gas Metal Arc Welding):A semi-automatic or automatic process using a continuously fed wire electrode and shielding gas, known for high deposition rates. Automotive and general manufacturing in Germany and Japan increasingly adopt GMAW for speed and efficiency in production lines.
- FCAW (Flux-Cored Arc Welding):Utilizes a continuously fed tubular electrode containing flux, offering high deposition rates and good weld quality in various positions.
- GTAW (Gas Tungsten Arc Welding):Employs a non-consumable tungsten electrode and shielding gas, producing high-quality, precise welds for sensitive materials in aerospace.
- SAW (Submerged Arc Welding):An automated process where a continuously fed wire electrode is submerged under granular flux, ideal for heavy fabrication and long welds.
Traditional SMAW maintains broad market penetration; however, automated GMAW and SAW processes are capturing a growing share in high-volume production.
Application:
The criticality of weld integrity and the specific environmental demands of each application fundamentally dictate the type and performance of welding electrodes required.
- Construction:Represents a high-volume application for general-purpose electrodes and specialized types for structural steel, spanning commercial and infrastructure projects. Large-scale infrastructure programs in China and India consume significant quantities of electrodes for bridges, buildings, and transportation networks.
- Shipbuilding:Requires electrodes resistant to corrosion and fatigue, suitable for welding large steel plates and complex structures in marine environments.
- Pipeline Fabrication:Demands electrodes capable of high strength and ductility, often low-hydrogen types, to withstand extreme pressures and environmental stresses. The oil and gas sector in the Middle East and North America drives consistent demand for certified, high-performance consumables.
- Heavy Machinery:Utilizes robust electrodes for manufacturing and repair of equipment exposed to severe operational conditions, such as mining and agricultural machinery.
- Aerospace:Employs highly specialized and certified electrodes for welding lightweight, high-strength alloys where precision and defect-free welds are paramount.
General fabrication in Construction drives volume; however, Pipeline Fabrication and Aerospace set the highest performance requirements for electrode development.
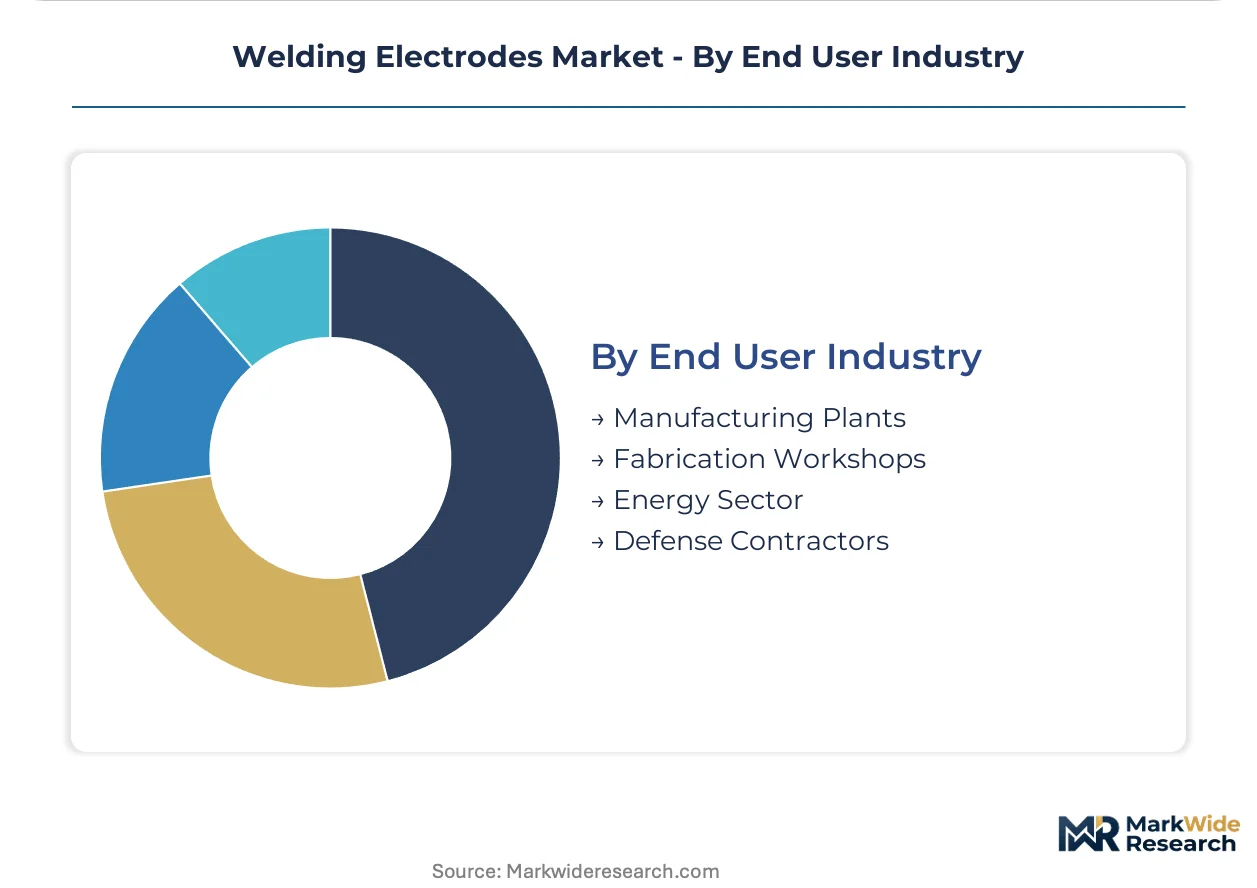
End User Industry:
The scale of operations and the regulatory environment within each end-user industry shape their specific procurement patterns for welding electrodes.
- Manufacturing Plants:Includes automotive, general fabrication, and industrial equipment production, often characterized by high-volume, automated welding processes. Factories in Germany and the USA prioritize electrodes offering high deposition rates and minimal spatter for efficiency.
- Fabrication Workshops:Serve diverse smaller projects and custom work, requiring a broad range of versatile electrodes for varied materials and job requirements.
- Energy Sector:Encompasses oil and gas, nuclear, and renewable energy, requiring electrodes with stringent quality and traceability for critical infrastructure. Projects like offshore wind farms in Europe and nuclear facilities in South Korea demand premium, certified low-hydrogen electrodes.
- Defense Contractors:Demand highly specialized, certified electrodes for military vehicles, naval vessels, and aerospace components, where reliability and material integrity are paramount.
Fabrication Workshops consume a wide array of general-purpose electrodes, while the Energy Sector consistently drives demand for highly specialized and certified products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia, a significant source of rutile and ilmenite, influences the global cost structure for welding electrode manufacturers. This supply dynamic impacts production costs for electrode producers worldwide. Regional demand for welding electrodes is driven by diverse industrial activities and infrastructure development.
China
China's extensive infrastructure projects and shipbuilding industry drive substantial demand for welding electrodes. The country's GB standards dictate material quality and performance for various applications. Industrial hubs like the Yangtze River Delta concentrate manufacturing, requiring vast quantities of general-purpose and specialized electrodes for fabrication.
United States
Pipeline fabrication and heavy machinery sectors in the United States necessitate high-performance low hydrogen electrodes. Regulations from the U.S. EPA on welding fume constituents influence electrode coating formulations. The Gulf Coast region, with its oil and gas infrastructure, sustains consistent demand for certified consumables.
Germany
Advanced manufacturing and automotive production in Germany require specialized electrodes for high-strength steels. The EU's REACH framework imposes strict controls on chemical substances in electrode coatings. Bavaria's industrial machinery cluster relies on compliant, high-performance electrodes for precision welding applications.
India
Large-scale infrastructure programs in India, including transportation networks and energy grids, create sustained volume demand. The Bureau of Indian Standards (BIS) governs product quality and safety for welding consumables. Major industrial corridors in Maharashtra consume significant quantities of rutile electrodes for construction and fabrication.
Saudi Arabia
The oil and gas sector and ambitious construction projects in Saudi Arabia generate consistent demand for robust welding electrodes. Local content requirements and specific project certifications influence procurement patterns. The Eastern Province, a hub for energy infrastructure, drives demand for high-performance and certified products.
Welding Electrodes Market Key Industry Players
Global majors compete with regional champions across product innovation and supply chain resilience within the welding electrodes market. The market exhibits a tiered structure, with a few large global players alongside numerous specialized regional manufacturers. Global integrated suppliers, regional specialists, and niche technology providers represent key strategic archetypes. Companies prioritize strategic partnerships and portfolio diversification to manage input costs and cater to specialized applications.
On the premium-tier vector, Lincoln Electric Holdings, Inc. and ESAB exemplify companies leveraging extensive portfolios and global manufacturing footprints. Lincoln Electric, a US-based entity, occupies a position emphasizing consistent supply and cost management through its worldwide operations. ESAB, known for its broad range of filler metals and equipment, represents a specialist in catering to diverse industrial applications across various geographies. ThyssenKrupp Schulte GmbH, a German-based entity, sits within the distribution and specialty materials segment, influencing raw material cost structures for European electrode manufacturers.
| Leading Market Players |
|---|
| Kobe Steel Welding & Construction Co., Ltd. |
| ThyssenKrupp Schulte GmbH |
| Lincoln Electric Holdings, Inc. |
| Miller Electric Mfg. LLC |
| Arcos Welding |
| ESAB |
| Böhler Welding |
| voestalpine AG |
| Haifei Intelligent Equipment Co., Limited |
| Others |
Cost & Logistics Intelligence
The European Union's REACH framework, imposing strict controls on chemical substances, gates qualified supply for electrode manufacturers and drives premium-tier pricing for compliant formulations. This regulatory environment tests the supply chain resilience of major firms.
Pricing Analysis
Warranty and service bundling for high-performance electrodes influences the total cost of operation for end-users, shifting procurement patterns. The market operates on a transactional, per-unit pricing model, with significant differentiation based on product quality grade and specific certifications like ISO 2560. Pricing softness runs through general-purpose rutile electrodes due to high volume production and increased competition. Pipeline fabrication and aerospace sectors exhibit the least price sensitivity, prioritizing performance and weld integrity over cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks manage the flow of welding electrodes from manufacturers to diverse end-users. Geographic supply concentration for key minerals like rutile from Australia and ilmenite from India creates upstream dependencies. Raw material price volatility for manganese and titanium dioxide constitutes a primary supply chain risk for electrode manufacturers. Downstream distribution typically runs through a network of specialized industrial distributors and direct sales channels for major accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Persistent raw material volatility, coupled with stringent regulatory scrutiny, forces market consolidation as smaller players struggle with compliance costs and input price swings.
For Market Incumbents:
Anticipate further market segmentation driven by advanced material adoption and stricter environmental regulations. Invest in R&D for low-fume and low-hydrogen electrode formulations to meet evolving standards like those from the U.S. EPA. Leverage global manufacturing footprints to manage input costs and ensure consistent supply, mitigating against commodity price volatility. Deepen vertical integration into specialty alloy production to control raw material quality and supply security.
For New Entrants and Emerging Players:
The European Union's REACH framework in Europe opens a window for specialized electrode manufacturers focusing on compliant, high-performance chemistries. Target niche applications in renewable energy projects, such as offshore wind, where demand for electrodes capable of withstanding extreme environmental stress is non-discretionary. A go-to-market angle emphasizing rapid certification for new advanced high-strength steels can capture early adopter segments.
For Investors and Strategic Acquirers:
The increasing adoption of automated welding processes is the leading indicator that value creation will shift towards specialized filler metals and integrated digital solutions. The market exhibits long-term viability over a 5-10 year window, driven by critical infrastructure and advanced manufacturing needs. Seek acquisition targets with strong intellectual property in electrode coating formulations or established positions in premium, certified low-hydrogen electrode segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in R&D for Low-Hydrogen Electrodes | Ensures compliance with stringent quality standards in critical applications like pipeline fabrication. |
| Expand Global Manufacturing Footprint | Mitigates raw material supply chain risks and optimizes production costs for diverse markets. |
| Develop Electrodes for Wire-Arc Additive Manufacturing | Captures high-value opportunities in rapid prototyping and 3D metal printing applications. |
| Strengthen Digital Welding Information Systems | Enables complete weld traceability and predictive maintenance for aerospace and energy sectors. |
| Pursue Strategic Partnerships with Specialty Alloy Producers | Secures access to advanced materials and influences raw material cost structures for electrode production. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with welding engineers, procurement leads, and R&D directors. This approach combined top-down market sizing with bottom-up validation across various industry segments. Secondary sources included ISO standards, U.S. EPA reports, company annual reports, and industry-specific trade publications.
The analysis modeled market dimensions at granular levels, including product type, technology, application, end-user industry, and key regional markets across the analysis window. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected through quantitative models, incorporating inputs such as infrastructure spending forecasts and advanced steel production volumes. This framework provided a comprehensive outlook on segment growth.
The model assumes a particular technology adoption path; alternative pathways for automated welding processes would alter the outlook for covered electrodes. Forecasts reflect assumptions regarding raw material price stability and the evolution of material standards. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Hydrofluoric Acid (HF) for Semiconductor Market
Industrial Chemicals
Europe Biocides Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
India Precipitated Silica Market