
 Isononanol (INA) Market | 2026-2036
Isononanol (INA) Market Size, Share, and Industry Trends Forecast 2026-2036
Isononanol (INA) Market Insights
A capital-intensity divergence between integrated petrochemical majors and specialized oxo-alcohol producers is bifurcating competitive returns in the Isononanol market. BASF SE leverages its Ludwigshafen Verbund complex to sustain backward integration into C4 feedstock streams, while ExxonMobil Chemical Company anchors its position through Baytown-scale manufacturing and Gulf Coast logistics control. KH Neochem Co., Ltd. differentiates via high-purity specialization for pharmaceutical-grade applications, occupying a premium tier that larger commodity players navigate less aggressively.
Isononanol is a branched C9 alcohol produced primarily through hydroformylation of octenes, typically featuring a purity threshold above 99% for plasticizer-grade material and serving as the principal precursor for diisononyl phthalate and non-phthalate plasticizers. Conventional INA dominates volume flows into construction and automotive plasticizer applications where cost sensitivity structures procurement, while bio-based INA captures expanding specification share under EU Green Deal procurement mandates and brand-owner sustainability commitments. The application split reveals plasticizers as the mature revenue base with embedded replacement cycles, whereas coatings and lubricant formulations represent faster-growing margin pools as performance specifications tighten.
REACH registration requirements and the EU F-Gas Regulation constrain feedstock sourcing and emissions profiles for European producers, while China's MEE enforces dual carbon compliance standards that reshape capacity approval timelines and technology choices for new oxo-alcohol investments. FDA food-contact regulations and EPA TSCA obligations in the United States govern downstream plasticizer migration limits and chemical substance reporting, directly influencing formulation decisions by Nan Ya Plastics Corporation and LG Chem Ltd. in their North American supply arrangements. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where specification premiums or compliance penalties will reshape regional supply competitiveness.
Market Dynamics
The Isononanol market is bifurcating around feedstock integration depth, with hydroformylation economics favoring producers commanding captive C4 streams while specialty purity requirements sustain niche positions for non-integrated operators.
Growth Catalysts
- China's dual carbon compliance:The MEE enforcement timeline accelerates oxo-alcohol capacity replacement toward lower-emission hydroformylation catalysts, tightening supply specifications that favor compliant producers.
- EU Green Deal procurement mandates:Brand-owner sustainability commitments in automotive and construction verticals specify bio-based plasticizer content thresholds, expanding addressable volume for certified INA grades.
- Diisononyl phthalate replacement cycles:Construction sector refurbishment activity in Germany and the United States drives recurring demand for high-purity INA in durable goods applications.
Market Restraints
- Propylene feedstock volatility:C4 olefin pricing swings directly compress oxo-alcohol margins for non-integrated producers lacking backward integration into steam cracker outputs.
- REACH registration accumulation:ECHA data requirements for novel hydroformylation catalysts extend approval timelines, freezing process innovation for European operators.
- Phthalate-free substitution pressure:DINCH and DOTP plasticizers capture specification share in sensitive applications, constraining volume growth for conventional diisononyl phthalate derivatives.
Strategic Opportunities
- Pharmaceutical-grade purity tiers:KH Neochem's specialization model demonstrates margin capture above commodity benchmarks for INA meeting USP monograph standards.
- India's BIS standardization gap:Absence of domestic oxo-alcohol purity specifications creates first-mover positioning for imported bio-based grades in packaging applications.
- Coatings solvent convergence:Reactive diluent formulations combining INA esters with UV-curable resins open technical collaboration channels with automotive OEM coating divisions.
Industry Challenges
- Hydroformylation catalyst expertise scarcity:Rhodium and cobalt complex handling requires specialized chemical engineering talent concentrated at Ludwigshafen and Baytown-scale facilities.
- Multi-jurisdiction certification synchronization:FDA food-contact notifications, EPA TSCA section 5 filings, and REACH dossier updates demand parallel regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isononanol (INA) Market |
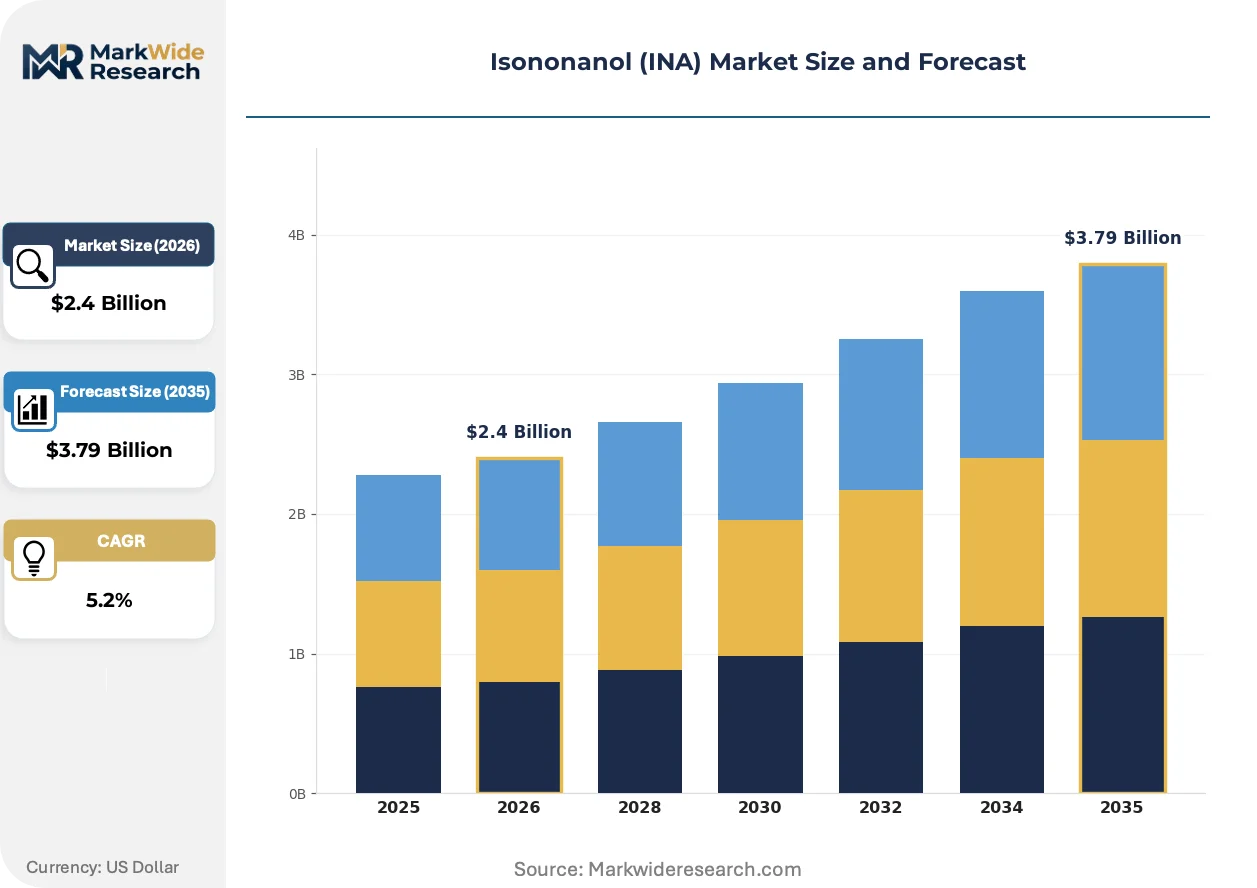
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional INA, Bio-based INA, High Purity INA, Technical INA Application: Plasticizers, Lubricants, Coatings, Detergents End User: Construction, Automotive, Consumer Goods, Pharmaceutical Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Evonik Industries AG, ExxonMobil Chemical Company, BASF SE, Dow Inc., Oxea Corporation, KH Neochem Co., Ltd., Nan Ya Plastics Corporation, INEOS Group, LG Chem Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isononanol (INA) Market Trends and Innovations
Process intensification and regulatory stringency are compressing the viable producer set while opening specification premiums for operators mastering low-carbon hydroformylation pathways.
Membrane-based olefin purification is fragmenting conventional distillation economics in C9 alcohol production. Specialty chemical divisions at integrated petrochemical complexes adopt hybrid separation trains to reduce energy intensity. This technology is fragmenting capital allocation between grassroots hydroformylation investments and retrofit opportunities at existing oxo-alcohol assets.
REACH authorization requirements for 1,2-benzenedicarboxylic acid di-C9 esters tighten migration limits in consumer goods. European formulators reformulate toward non-phthalate plasticizer systems. Automotive interior suppliers in Germany accelerate DINCH adoption, compressing specification tolerance for residual phthalate content in INA-derived materials.
Buyer consolidation among construction chemical distributors concentrates procurement leverage for plasticizer-grade INA. Regional distributors in the United States merge formulating capabilities with logistics networks. This pattern concentrates volume allocation decisions among fewer technical buyers in the Gulf Coast and Midwest construction corridors.
Isononanol (INA) Market Segmentation
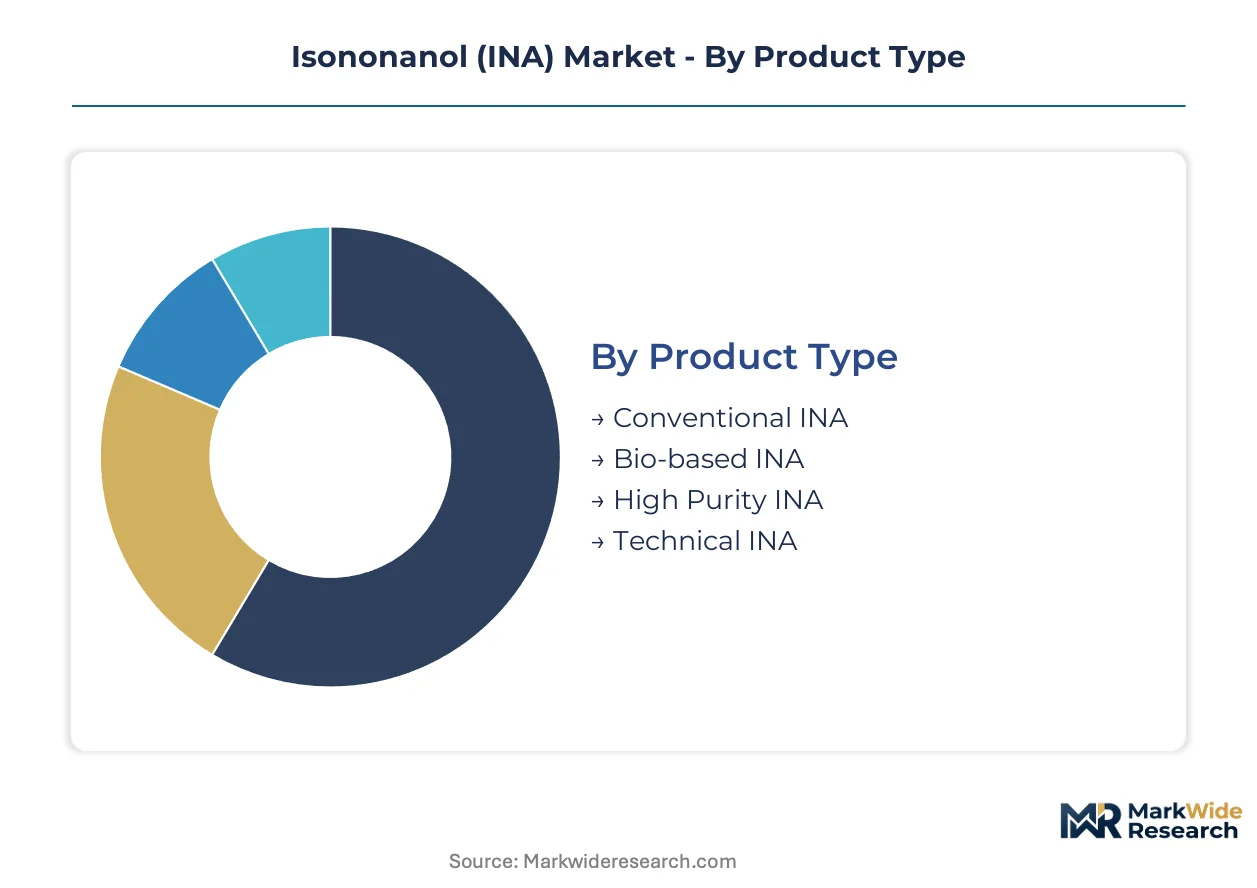
INA procurement patterns diverge sharply between commodity-scale plasticizer operations and specification-driven pharmaceutical and coating applications. Segmentation reveals where integrated producers capture volume economics versus where purity premiums sustain non-integrated specialists.
Product Type:
Geographic demand spread separates captive-supply conventional grades from export-dependent specialty tiers. Domestic absorption dominates commodity flows in China and Germany, while bio-based and high-purity grades move through international certification channels.
- Conventional INA:Standard hydroformylation output meeting 99% purity thresholds for diisononyl phthalate production. Construction sector procurement in China and the United States absorbs the majority of volume, with cost sensitivity favoring producers commanding captive C4 feedstock streams.
- Bio-based INA:Derived from renewable octene feedstocks through advanced hydroformylation pathways. EU Green Deal procurement mandates in Germany and sustainability commitments by automotive OEMs are accelerating specification share for certified grades.
- High Purity INA:Meets USP monograph standards for pharmaceutical excipient applications. KH Neochem's specialization model demonstrates margin capture above commodity benchmarks.
- Technical INA:Intermediate purity grade for industrial solvent and detergent formulations. Price-sensitive procurement concentrates in Asian manufacturing clusters.
Conventional INA commands the established base. The steepest expansion runs through bio-based INA.
Application:
Margin structure separates mature plasticizer replacement cycles from faster-growing performance formulations in coatings and lubricants.
- Plasticizers:Principal downstream consumption for diisononyl phthalate and non-phthalate alternatives. Construction refurbishment activity in Germany and the United States drives recurring demand, though DINCH and DOTP substitution constrains volume growth in sensitive applications.
- Lubricants:Synthetic ester base stocks and metalworking fluid additives. Automotive OEM specifications in Germany and Japan are tightening performance requirements for high-viscosity index formulations.
- Coatings:Reactive diluent applications combining INA esters with UV-curable resins. Automotive OEM coating divisions are opening technical collaboration channels for low-VOC formulations.
- Detergents:Surfactant intermediates and cleaning solvent applications. Formulation shifts toward concentrated products are compressing volume intensity per unit.
Plasticizers anchor revenue stability. Coatings applications are climbing the fastest.
End User:
Customer concentration patterns bifurcate between project-based construction procurement and continuous manufacturing demand from automotive and pharmaceutical operations.
- Construction:Durable goods plasticizer demand tied to refurbishment cycles and infrastructure investment. Regional distributor consolidation in the United States is concentrating procurement leverage among fewer technical buyers.
- Automotive:Interior trim and underhood applications with tightening phthalate migration limits. REACH authorization requirements are accelerating DINCH adoption among German tier suppliers.
- Consumer Goods:Food-contact and childcare applications with zero-tolerance phthalate specifications. FDA notification requirements govern formulation decisions by compounders.
- Pharmaceutical:Excipient and active pharmaceutical ingredient solvent applications. USP monograph compliance creates qualification barriers for new supplier entry.
Construction holds the volume base. Pharmaceutical end use is gaining share fastest.
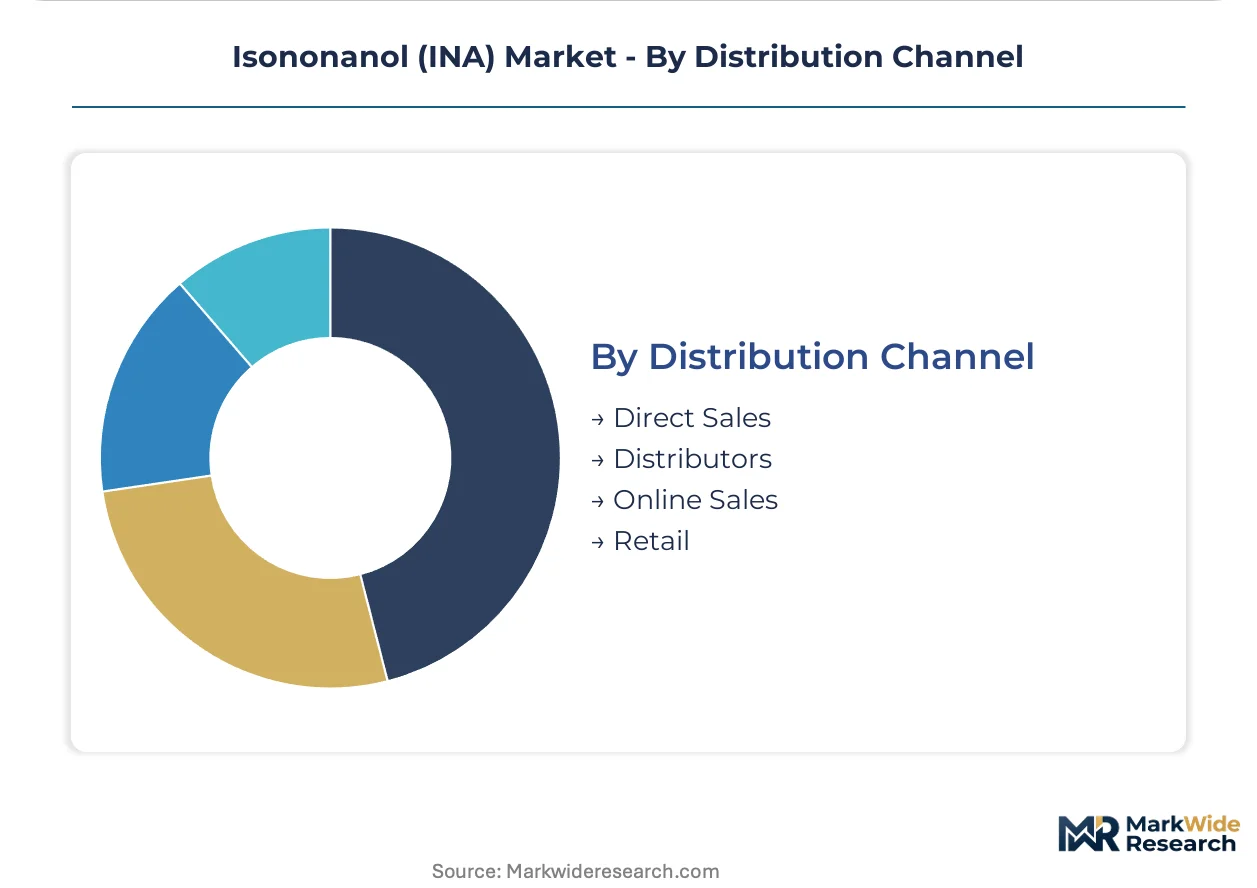
Distribution Channel:
Channel economics reflect shipment scale and technical service intensity required per customer segment.
- Direct Sales:Integrated producers supply plasticizer compounders through dedicated account management. BASF and ExxonMobil anchor relationships with construction chemical distributors.
- Distributors:Regional logistics networks with formulating capabilities serve mid-tier compounders. Gulf Coast and Midwest corridor consolidation is reshaping allocation decisions.
- Online Sales:Emerging channel for technical documentation and sample procurement. Limited to standardized grades with established certification.
- Retail:Minimal presence given bulk shipment requirements and safety handling protocols.
Direct sales dominate value capture. Distributor networks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive construction buyers in China compress margins for conventional grades, while German automotive and pharmaceutical specifications sustain premium tiers for bio-based and high-purity alternatives.
China
Construction sector refurbishment and automotive interior demand absorb the majority of conventional INA volume. MEE enforcement of dual carbon compliance tightens approval timelines for new oxo-alcohol capacity. Yangtze River Delta clusters around Shanghai and Nanjing host integrated producers scaling lower-emission hydroformylation investments.
Germany
Automotive OEM sustainability mandates and pharmaceutical excipient specifications drive demand for certified bio-based and USP-grade material. REACH authorization requirements for phthalate esters accelerate DINCH adoption among tier suppliers. Ludwigshafen and Marl chemical complexes anchor backward-integrated production with captive C4 feedstock control.
United States
Construction chemical distributor consolidation concentrates procurement leverage for plasticizer-grade material in Gulf Coast and Midwest corridors. EPA TSCA section 5 obligations govern novel catalyst introductions. Baytown and Baton Rouge manufacturing clusters leverage Gulf Coast logistics for domestic and export supply.
Japan
Automotive OEM specifications for high-viscosity index lubricant formulations tighten performance requirements for synthetic ester base stocks. METI industrial standards shape purity thresholds for metalworking fluid applications. Chubu and Kansai industrial belts host specialty chemical operations serving precision manufacturing demand.
India
Packaging sector growth and infrastructure investment expand addressable volume for imported bio-based grades. Absence of domestic BIS purity specifications for oxo-alcohols creates first-mover positioning opportunities. Maharashtra and Gujarat industrial corridors concentrate downstream plasticizer compounding capacity.
Isononanol (INA) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated petrochemical complexes commanding hydroformylation economics while specialty operators capture purity premiums. The market structures around three tiers: backward-integrated majors with captive feedstock, regional scale producers serving construction verticals, and high-purity specialists qualifying for pharmaceutical applications. Dominant competitive moves include capacity expansion at integrated sites and strategic partnerships for bio-based feedstock certification.
Among German-based integrated chemical groups, BASF SE and Evonik Industries AG occupy positions spanning commodity and specialty tiers. ExxonMobil Chemical Company anchors the North American scale-driven segment. KH Neochem Co., Ltd. exemplifies the high-purity specialist archetype serving pharmaceutical-grade specifications.
| Leading Market Players |
|---|
| Evonik Industries AG |
| ExxonMobil Chemical Company |
| BASF SE |
| Dow Inc. |
| Oxea Corporation |
| KH Neochem Co., Ltd. |
| Nan Ya Plastics Corporation |
| INEOS Group |
| LG Chem Ltd. |
| Others |
Pricing and Supply Chain Analysis
REACH registration tiers and ECHA dossier completeness gate both supplier qualification and price differentiation in European Isononanol procurement. MEE dual carbon compliance standards in China create parallel certification barriers that segment domestic supply into emission-grade tiers with attached premiums.
Pricing Analysis
After-sales technical service contracts for hydroformylation catalyst management drive lifetime value capture for integrated producers. Three-tier pricing structure across pharmaceutical-grade, plasticizer-grade, and technical-grade levels segments buyers by purity specification and certification burden. Cost compression in conventional plasticizer-grade material intensifies because propylene feedstock volatility squeezes non-integrated operators. Construction sector procurement in China exhibits highest price sensitivity, while pharmaceutical excipient buyers in Germany accept substantial premiums for USP monograph compliance.
Supply Chain Analysis
Rhodium catalyst supply concentration in South Africa and Russia underwrites hydroformylation economics for oxo-alcohol producers worldwide. Manufacturing gravity centers on China, Germany, and the United States, with each cluster drawing from distinct C4 olefin feedstock configurations. Raw material dependencies span octene streams, synthesis gas, and precious metal catalyst complexes. Single-source vulnerability for rhodium and cobalt concentrates creates procurement risk for European operators lacking long-term offtake agreements. Distribution runs through direct sales relationships with plasticizer compounders and construction chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized hydroformylation catalyst engineering talent pools are contracting faster than capacity expansion timelines, creating a capability bottleneck that favors incumbents with embedded expertise over new entrants seeking rapid qualification.
For Market Incumbents: Fortify backward integration into captive C4 feedstock streams to defend margin position against propylene price volatility. BASF's Ludwigshafen model demonstrates how Verbund complex economics neutralize raw material swings. Prioritize MEE-compliant capacity additions in Yangtze River Delta clusters to capture specification premiums as dual carbon enforcement tightens. Secure long-term rhodium catalyst supply contracts to neutralize precious metal concentration risk. For New Entrants and Emerging Players: Differentiate on bio-based certification pathways to bypass commodity-grade price wars in conventional plasticizer applications. India's BIS standardization gap offers the most penetrable geography for imported certified grades targeting packaging sector growth. Pursue technical collaboration models with automotive OEM coating divisions rather than competing for construction distributor volume. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across low-emission hydroformylation investments as MEE compliance requirements extend project timelines. High-purity specialists with pharmaceutical-grade qualification barriers represent the preferred acquisition archetype over commodity-scale operators facing margin compression. Watch for rhodium price spikes as inflection indicators that reshape competitive economics between integrated and non-integrated producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Feedstock | Captive olefin supply insulates BASF and ExxonMobil from propylene volatility. |
| Green Manufacturing Transition | MEE-compliant hydroformylation catalysts unlock Chinese market access premiums. |
| Long-term Supply Agreement | Rhodium offtake contracts neutralize South African supply concentration risk. |
| Joint Venture | Automotive OEM partnerships accelerate DINCH formulation adoption in Germany. |
| Capacity Expansion | Yangtze River Delta additions capture construction sector demand in China. |
Research Methodology
Desk research of customs trade databases, ECHA registration dossiers, and SEC chemical division filings preceded structured interviews with oxo-alcohol plant managers, plasticizer procurement leads at construction chemical distributors, hydroformylation R&D directors, and MEE compliance officers. Primary fieldwork with downstream compounders in China, Germany, and the United States validated secondary volume estimates. Bottom-up capacity modeling triangulated against top-down demand segmentation across plasticizer, coating, and pharmaceutical applications.
Variance decomposition across feedstock cost, capacity utilization, and specification premium drivers shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry vertical, and regional production hub regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating construction cycle intensity and automotive interior specification shifts. Forecast inputs incorporated MEE enforcement timeline scenarios and REACH authorization phase-out schedules.
Material uncertainties — rhodium supply disruptions, MEE capacity approval delays, and DINCH substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about hydroformylation catalyst technology diffusion and dual carbon compliance trajectory. Practitioners should keep alternative scenarios live as precious metal market conditions and automotive plasticizer specification evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Global Aerosol Propellant Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Tetrafluoroethane (R134A) Refrigerant Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market