
 Global Anhydrous Aluminum Chloride Market | 2026-2036
Global Anhydrous Aluminum Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anhydrous Aluminum Chloride Market Intelligence
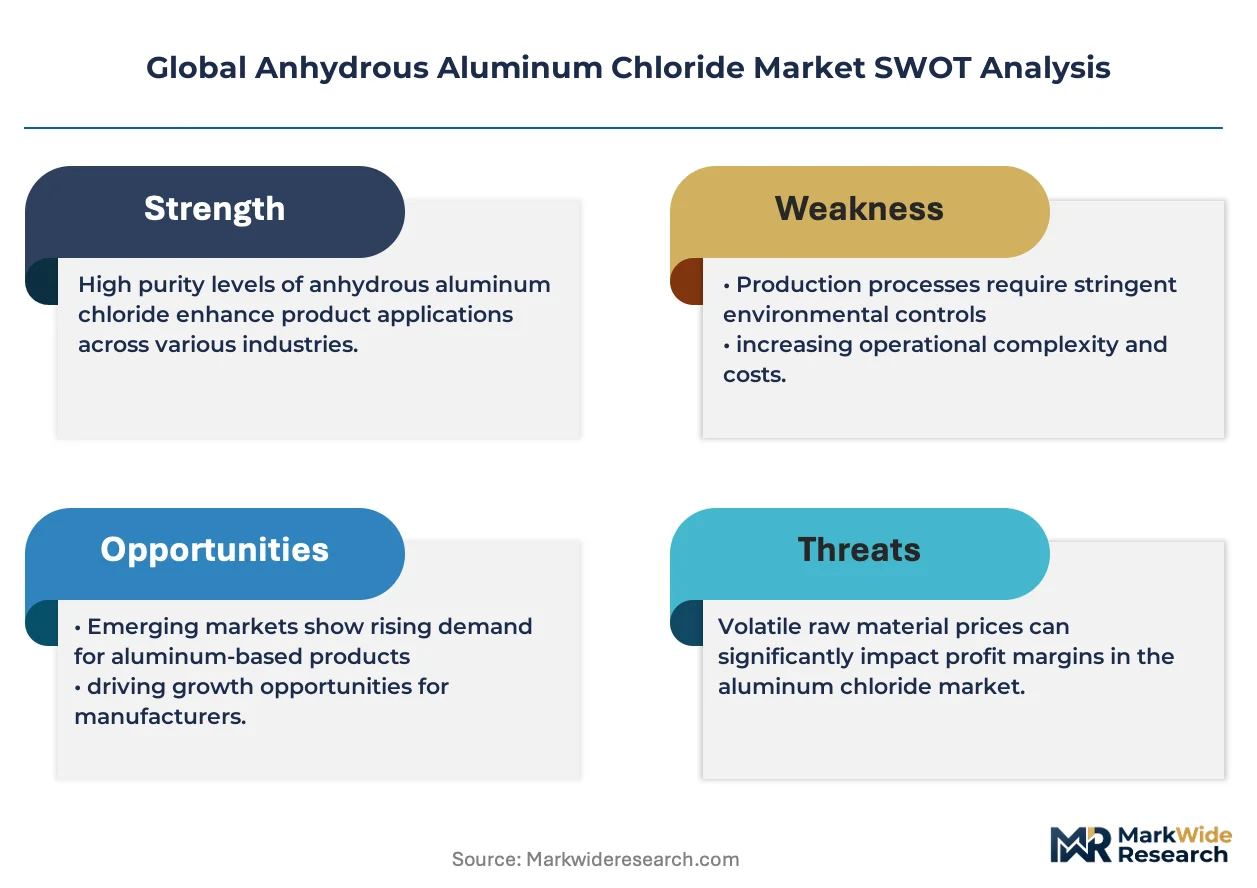
The gap between pharmaceutical-grade and commodity-grade anhydrous aluminum chloride is broadening as purity thresholds diverge across end-use sectors. BASF SE leverages its integrated catalyst supply chain to command premium positioning in European pharmaceutical applications. Gujarat Alkalies and Chemicals Limited anchors volume supply for Asian water treatment and petrochemical buyers through coastal manufacturing scale.
Anhydrous aluminum chloride (AlCl₃) is a hygroscopic, subliming solid produced via chlorination of alumina or aluminum metal in exothermic reactor systems, typically supplied at 98-99.5% purity depending on end-use tolerance. It functions primarily as a Lewis acid catalyst in Friedel-Crafts alkylation and acylation reactions across dye, pharmaceutical, and fragrance synthesis. Granular and powder grades dominate current offtake, with granular formats capturing margin pools in automated pharmaceutical catalyst dosing systems while powder sustains higher volumes in water treatment coagulation where dissolution kinetics matter less. Catalyst applications lead value generation, whereas coagulant demand in municipal water treatment represents the most mature, price-sensitive consumption tier.
EPA standards under the Safe Drinking Water Act and REACH registration requirements in Europe constrain impurity profiles for material entering potable water and pharmaceutical supply chains, with China's NMPA issuing parallel purity directives for imported catalyst grades. India's BIS certification and CDSCO import testing protocols add compliance layers for suppliers targeting subcontinent pharmaceutical manufacturers. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and industrial-grade specifications, as certification costs will increasingly determine accessible market segments.
Market Dynamics
Pharmaceutical-grade purity specifications are diverging sharply from industrial-grade tolerances as regulators impose trace-metal limits that chlorination reactors struggle to meet without costly retrofit.
Growth Catalysts
- Friedel-Crafts catalyst demand:Active ingredient synthesis in Indian and Chinese pharmaceutical corridors is expanding procurement of high-purity AlCl₃ for acylation reactions in antihistamine and antibiotic production.
- REACH purity mandates:ECHA registration requirements for substances in pharmaceutical supply chains are filtering import-grade material toward certified producers capable of sub-50ppm iron content.
- Gujarat chemical corridor expansion:Coastal chlor-alkali integration at Dahej and Hazira is concentrating merchant supply capacity for Asian water treatment and petrochemical buyers.
Market Restraints
- Alumina feedstock volatility:Smelter-grade alumina price swings transmitted through chlorination economics compress margin predictability for non-integrated producers.
- Chlorine supply concentration:Captive chlorine from caustic soda integration at Gulf Coast and Gujarat sites disadvantages standalone chlorination units in freight-cost terms.
- Zeolite substitution in FCC:Rare-earth stabilized Y-zeolites are displacing AlCl₃ in fluid catalytic cracking for transport fuels, eroding a legacy volume anchor.
Strategic Opportunities
- Specialty fragrance synthesis:Supercritical fluid extraction paired with AlCl₃ catalysis is opening novel terpene acylation pathways for luxury perfume houses in Grasse and Dubai.
- Indonesian water infrastructure:Municipal coagulant demand in Jakarta and Surabaya is outpacing domestic chlor-alkali capacity, creating import windows for granular-grade suppliers.
- EPA Lead and Copper Rule revisions:Tightened corrosion control mandates in US municipal systems are expanding specification-grade coagulant volumes beyond commodity tenders.
Industry Challenges
- Pharmaceutical certification timelines:CDSCO import testing protocols for catalyst-grade material extend qualification cycles to 18-24 months, freezing supplier switching.
- Reactor corrosion management:Nickel-alloy cladding degradation in high-temperature chlorination units demands scheduled turnaround capital that merchant producers struggle to amortize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anhydrous Aluminum Chloride Market |
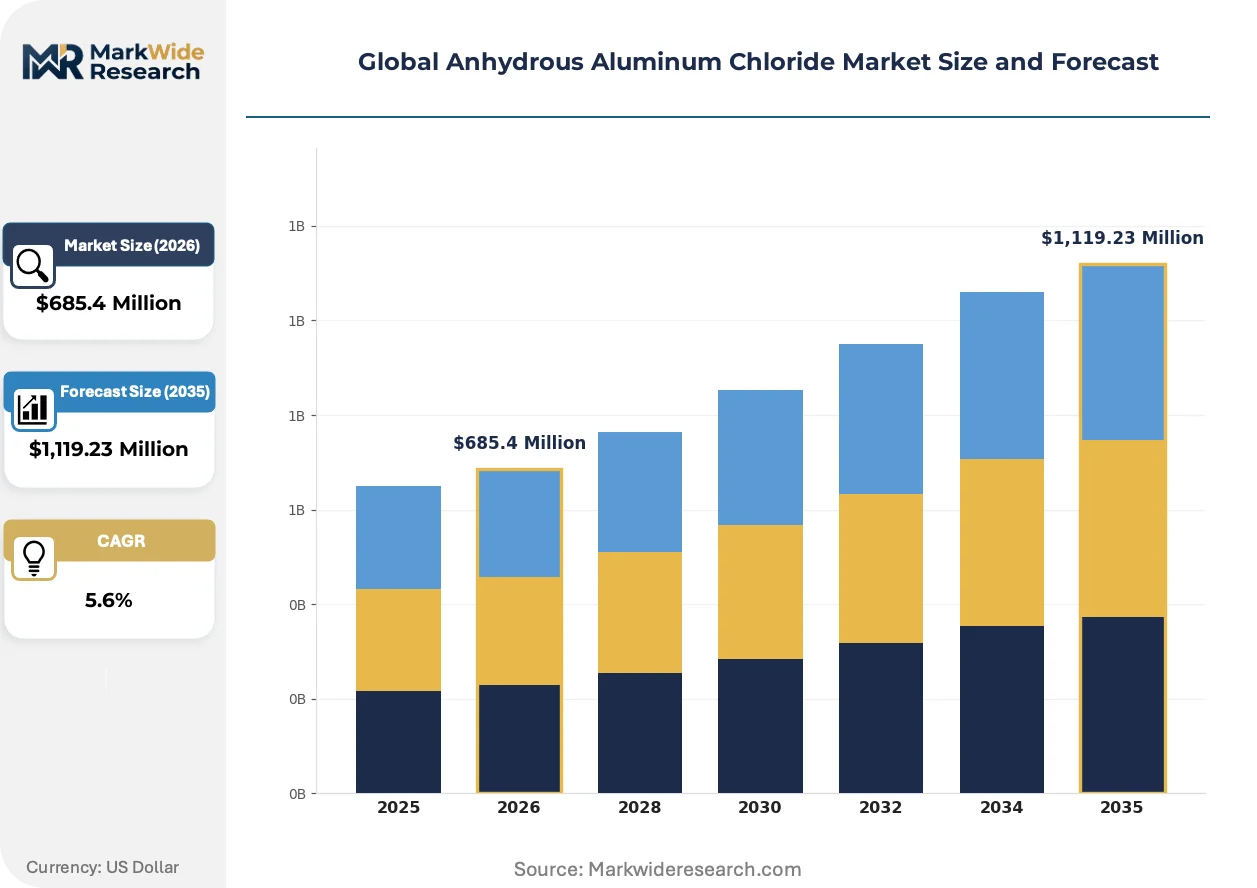
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,119.23 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Pellet, Flake End User: Chemical Manufacturing, Water Treatment, Petrochemical, Pharmaceuticals Application: Catalyst, Coagulant, Desiccant, Intermediate Packaging Type: Bulk, Bags, Drums, Containers |
| Companies Covered | BASF SE, Gujarat Alkalies and Chemicals Limited, Aditya Birla Chemicals, DCM Shriram Ltd., Nippon Light Metal Co., Ltd., Kanto Denka Kogyo Co., Ltd., Tanfac Industries Limited, Solvay S.A., SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anhydrous Aluminum Chloride Market Strategic Shifts & Innovations
Continuous chlorination reactor designs and automated dosing systems are compressing batch-to-batch variability while regulatory digitization is accelerating certificate-of-analysis verification.
Granular AlCl₃ with controlled particle size distribution is overtaking powder formats in automated pharmaceutical catalyst dosing systems. Contract manufacturers in Basel and Shanghai are retrofitting loss-in-weight feeders to handle free-flowing granules. This format shift is compressing labor input per kilogram dosed and reducing dust exposure liability in GMP facilities.
REACH substance evaluation under the 2023-2025 rolling action plan is tightening ecotoxicity data requirements for AlCl₃ used in water treatment applications. ECHA's updated dossier demands are forcing non-EU exporters to commission new aquatic toxicity studies. German and Dutch municipal buyers are now requiring REACH-compliant safety data sheets as tender preconditions.
Long-term offtake contracting is displacing spot procurement for catalyst-grade material among mid-sized pharmaceutical API manufacturers. Buyers in Hyderabad and Suzhou are locking 24-36 month supply agreements with fixed purity bands to insulate against feedstock volatility. This pattern is most visible in antiviral and oncology intermediate supply chains where qualification costs deter supplier rotation.
Global Anhydrous Aluminum Chloride Market Segmentation
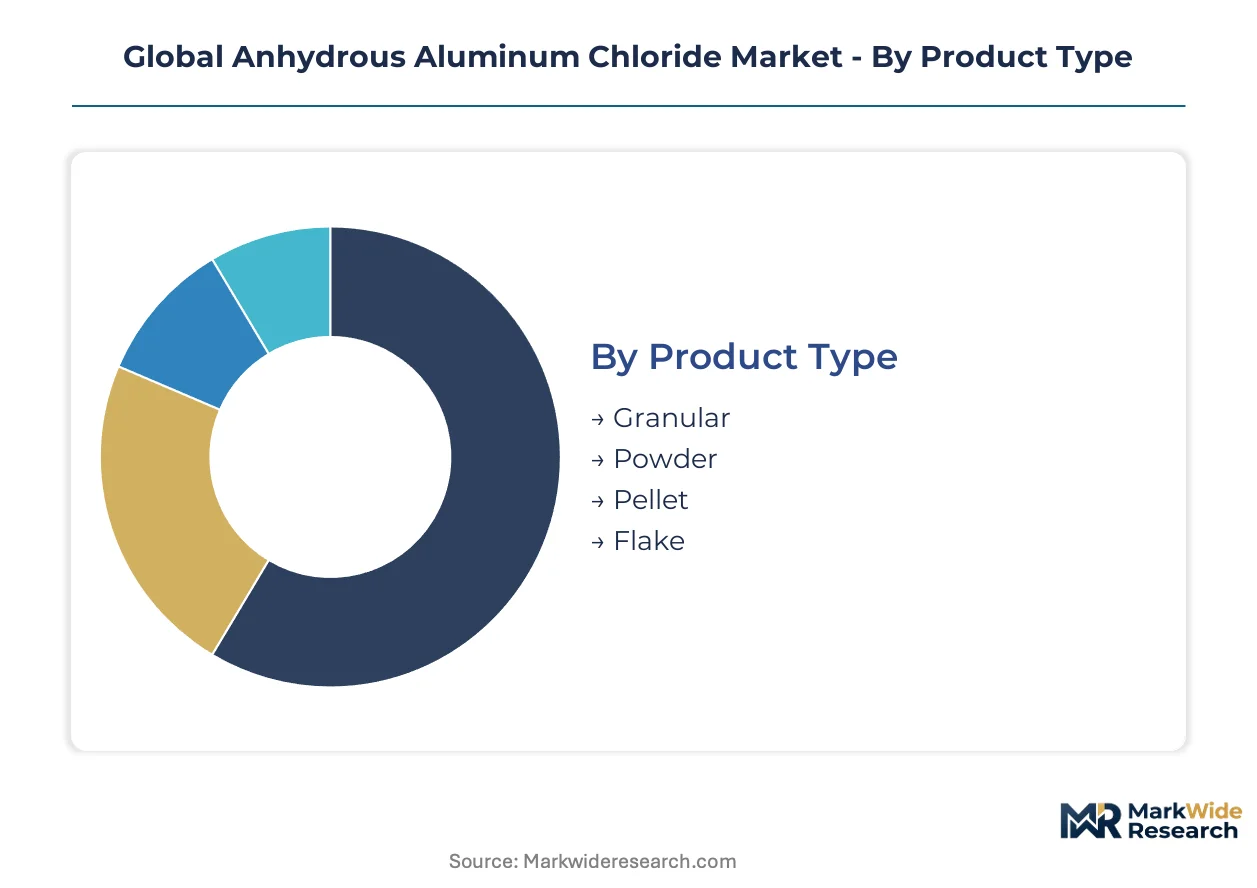
Segmentation in anhydrous aluminum chloride markets tracks the divergence between commodity-grade material and certified catalyst grades. Format specifications and packaging protocols increasingly determine accessible customer tiers and margin capture.
Product Type:
Format selection reflects upgrade cycles in customer dosing infrastructure and the capital intensity of switching between powder and automated granular systems.
- Granular:Free-flowing particles with controlled size distribution enable automated loss-in-weight feeding in pharmaceutical GMP facilities. Contract manufacturers in Basel and Shanghai are retrofitting equipment to handle this format, compressing labor input per kilogram and reducing dust exposure liability.
- Powder:Fine particulate matter dominates water treatment coagulation where rapid dissolution kinetics matter less than unit cost. Municipal procurement in Gujarat and the US Gulf Coast sustains this segment's volume anchor despite handling inefficiencies.
- Pellet:Compressed cylindrical format suits niche desiccant applications requiring minimal dust generation during drum loading operations.
- Flake:Thin crystalline layers serve specialty fragrance synthesis in Grasse where sublimation control during terpene acylation reactions proves critical.
Powder sits at the top of the volume ranking, with granular climbing the fastest as pharmaceutical automation spreads.
End User:
Customer type stratification follows purity tolerance thresholds and the regulatory burden of qualifying suppliers for each tier.
- Pharmaceuticals:Active ingredient synthesis demands sub-50ppm iron content for Friedel-Crafts acylation in antihistamine and antibiotic production. CDSCO import testing protocols extend qualification cycles to 18-24 months, freezing supplier relationships.
- Chemical Manufacturing:Dye and fragrance intermediates consume mid-purity grades where REACH registration suffices without pharmaceutical-grade certification overhead.
- Water Treatment:Municipal coagulation represents the most mature, price-sensitive consumption tier with EPA Lead and Copper Rule revisions tightening specification-grade volumes beyond commodity tenders.
- Petrochemical:Fluid catalytic cracking applications face zeolite substitution pressure as rare-earth stabilized Y-zeolites displace AlCl₃ in transport fuel production.
Water treatment commands the largest volume position, while pharmaceuticals posts the steepest expansion trajectory on catalyst procurement growth.
Application:
Functional use determines the technical specification depth and the longevity of customer-supplier relationships.
- Catalyst:Lewis acid functionality drives Friedel-Crafts alkylation and acylation across dye, pharmaceutical, and fragrance synthesis. Long-term offtake contracting now spans 24-36 months among API manufacturers in Hyderabad and Suzhou seeking insulation from feedstock volatility.
- Coagulant:Municipal water treatment relies on rapid hydrolysis for turbidity removal, with Indonesian demand in Jakarta and Surabaya outpacing domestic chlor-alkali capacity.
- Desiccant:Hygroscopic properties serve sealed packaging applications where moisture control protects sensitive intermediates.
- Intermediate:Further chemical transformation into aluminum-based complexes supports polymerization catalysts and specialty ceramics.
Coagulant applications lead absolute volume, with catalyst use gaining share fastest on pharmaceutical corridor expansion.
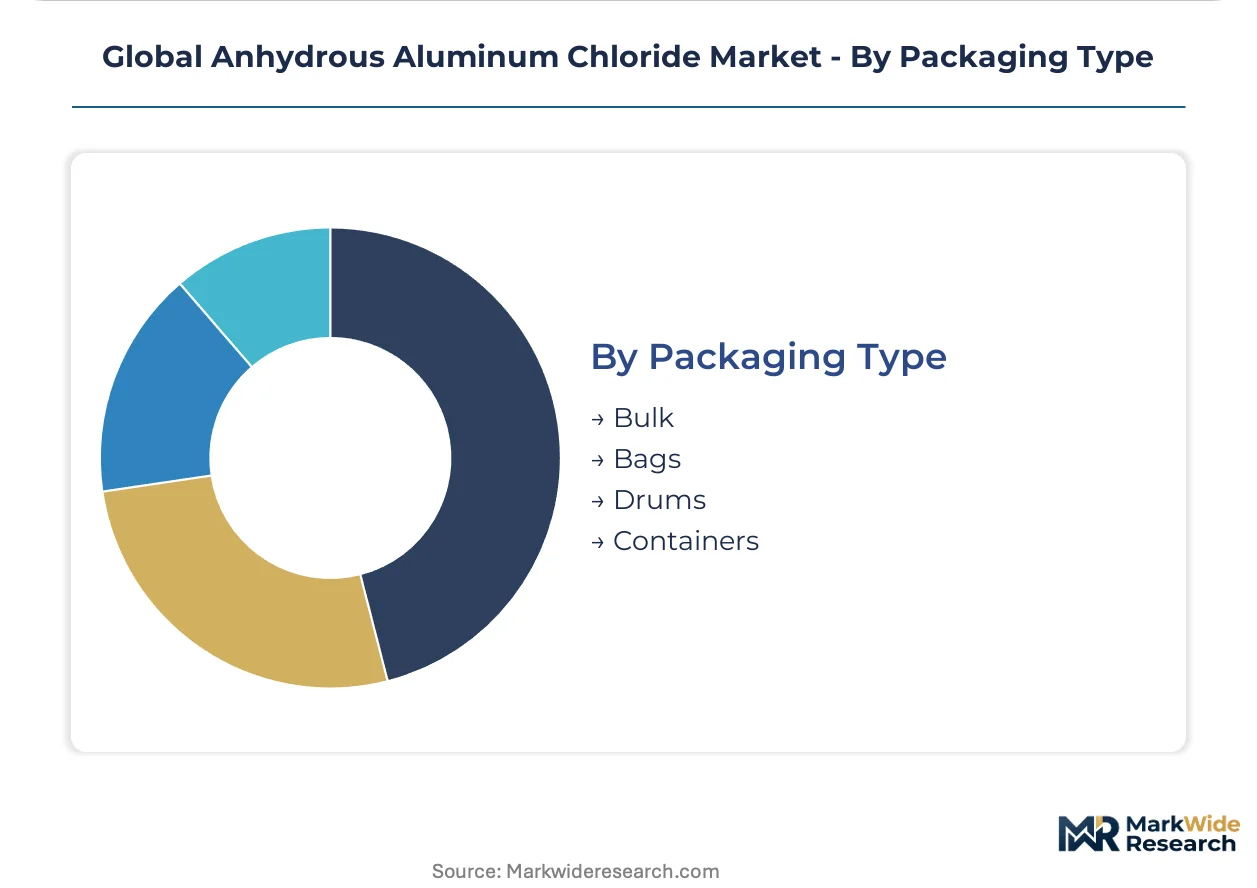
Packaging Type:
Logistics configuration aligns with customer scale, regulatory documentation requirements, and the corrosion sensitivity of AlCl₃ to atmospheric moisture.
- Drums:Steel containers with nitrogen padding dominate pharmaceutical-grade shipments where certificate-of-analysis verification accompanies each lot. ECHA's updated dossier demands now require REACH-compliant safety data sheets as tender preconditions for German and Dutch buyers.
- Bulk:Tanker or hopper car delivery serves integrated chlor-alkali consumers at Dahej and Hazira with captive consumption or coastal merchant supply.
- Bags:Multi-layer polymer sacks with moisture barriers address mid-scale water treatment procurement in Southeast Asian municipal systems.
- Containers:ISO tank configurations facilitate intermodal shipment for export-grade material subject to BIS certification and DGFT scrutiny.
Drums capture the premium pricing tier, with bulk formats expanding most quickly on coastal manufacturing concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's pharmaceutical corridors outpace US Gulf Coast petrochemical demand in catalyst-grade procurement, while India's coastal chlor-alkali integration reshapes Asian merchant supply economics.
United States
EPA Lead and Copper Rule revisions tighten corrosion control mandates across municipal water systems, expanding specification-grade coagulant volumes beyond commodity tenders. Gulf Coast petrochemical hubs at Houston and Corpus Christi sustain fluid catalytic cracking demand despite zeolite substitution pressure in transport fuel production.
Germany
ECHA's REACH substance evaluation under the 2023-2025 rolling action plan imposes stricter ecotoxicity data requirements for water treatment applications. BASF SE leverages integrated catalyst supply chains from Ludwigshafen to command premium positioning in European pharmaceutical Friedel-Crafts applications.
China
NMPA purity directives for imported catalyst grades filter procurement toward certified producers capable of sub-50ppm iron content. Suzhou and Hyderabad API manufacturers lock 24-36 month supply agreements to insulate against feedstock volatility in antiviral and oncology intermediate synthesis.
India
CDSCO import testing protocols extend qualification cycles to 18-24 months for catalyst-grade material, freezing supplier relationships. Gujarat's chemical corridor at Dahej and Hazira concentrates coastal chlor-alkali integration, anchoring volume supply for Asian water treatment and petrochemical buyers.
Indonesia
Municipal coagulant demand in Jakarta and Surabaya outpaces domestic chlor-alkali capacity, creating import windows for granular-grade suppliers. BIS certification and DGFT scrutiny govern ISO tank configurations for export-grade material entering Southeast Asian municipal systems.
Global Anhydrous Aluminum Chloride Market Key Industry Players
Top-tier vendors anchor integrated chlor-alkali production, while merchant chlorination units compete on coastal freight economics and pharmaceutical certification depth. The vendor base stratifies across captive chlorine advantage, REACH registration capability, and CDSCO qualification timelines. Three archetypes dominate: integrated chemical majors with alumina-to-catalyst pipelines, regional chlor-alkali specialists serving municipal coagulant tenders, and pharmaceutical-grade purity specialists commanding premium positioning. Competitive moves concentrate on long-term offtake contracting and automated dosing format upgrades.
Within the integrated major tier, BASF SE and Solvay S.A. exemplify European REACH-registered supply chains. Gujarat Alkalies and Chemicals Limited anchors volume positioning for Asian water treatment procurement. Among Japanese precision specialists, Nippon Light Metal Co., Ltd. and Kanto Denka Kogyo Co., Ltd. occupy positions in high-purity catalyst segments.
| Leading Market Players |
|---|
| BASF SE |
| Gujarat Alkalies and Chemicals Limited |
| Aditya Birla Chemicals |
| DCM Shriram Ltd. |
| Nippon Light Metal Co., Ltd. |
| Kanto Denka Kogyo Co., Ltd. |
| Tanfac Industries Limited |
| Solvay S.A. |
| SABIC |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade certification ladders manifest in divergent pricing bands and supply chain configurations, with REACH-registered producers commanding premium positioning while commodity-grade suppliers compete on coastal freight economics at Dahej and Hazira. This bifurcation concentrates margin capture among integrated chlor-alkali majors while merchant chlorination units absorb alumina feedstock volatility through spot market exposure.
Pricing Analysis
Capacity additions in Gujarat are reshaping price floors for granular-grade material as coastal chlor-alkali integration compresses unit costs for Asian water treatment procurement. Contract-based long-term offtake agreements now span 24-36 months among API manufacturers, with price differentiation driven by iron content certification and CDSCO qualification depth. Cost compression in powder-grade coagulants is intensifying because Indonesian municipal buyers issue commodity tenders with minimal purity specifications. Water treatment procurement remains most price-sensitive, while pharmaceutical catalyst supply chains tolerate premium positioning due to qualification cost barriers.
Supply Chain Analysis
Freight cost differentials favor coastal manufacturing clusters over inland chlorination units, with supply concentrating in India, China, and Germany for distinct grade tiers. Raw material flows draw from smelter-grade alumina, captive chlorine from caustic soda integration, and nickel-alloy reactor components. Single-source vulnerability around chlor-alkali integration at Gulf Coast and Gujarat sites disadvantages standalone producers. Distribution runs through drum shipments with nitrogen padding for pharmaceutical-grade material and bulk tanker delivery for integrated coastal consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's 2023-2025 rolling action plan on REACH substance evaluation tightens ecotoxicity data requirements and filters procurement toward certified producers.
For Market Incumbents: Anticipate zeolite substitution pressure in fluid catalytic cracking by deepening catalyst-grade purity specialization and securing backward integration into alumina supply. Defensive moves center on locking 36-month offtake agreements with Suzhou and Hyderabad API manufacturers while retrofitting continuous chlorination reactors to compress batch-to-batch variability. CDSCO import testing protocols extending to 24 months create switching cost moats worth reinforcing through dedicated regulatory affairs staffing. For New Entrants and Emerging Players: The premium-to-economy price gap in Indonesian municipal coagulant procurement offers white-space entry for granular-grade suppliers with ISO tank logistics capability. Target Surabaya and Jakarta water infrastructure expansion where domestic chlor-alkali capacity lags demand growth. A certification-light go-to-market angle serving mid-purity dye and fragrance intermediates bypasses pharmaceutical-grade qualification timelines while building operational track record. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone chlorination units struggle to amortize nickel-alloy reactor turnaround capital against integrated coastal majors. Long-term viability favors REACH-registered producers with captive chlorine and automated granular format capability. Acquisition target archetypes include regional chlor-alkali specialists with BIS certification and underutilized coastal freight infrastructure. The signal to watch is CDSCO qualification pipeline velocity as a proxy for supplier relationship freeze duration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Supply | Captive feedstock sourcing insulates margin predictability against smelter-grade price swings transmitted through chlorination economics. |
| Continuous Chlorination Reactor Deployment | Automated reactor designs at Dahej and Hazira compress batch-to-batch variability for pharmaceutical-grade certification. |
| Long-term Supply Agreement Structuring | 24-36 month offtake contracts with Hyderabad API manufacturers lock volume against feedstock volatility in antiviral intermediate synthesis. |
| Granular Format Capacity Expansion | Loss-in-weight feeder compatibility at Basel contract manufacturers captures automation-driven format shift in GMP facilities. |
| REACH Registration Dossier Enhancement | ECHA-compliant aquatic toxicity data satisfies German and Dutch municipal tender preconditions for water treatment applications. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at chlor-alkali facilities, procurement leads at downstream pharmaceutical API manufacturers, distribution channel partners in Asian water treatment markets, and technical R&D directors at catalyst suppliers. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical majors, and ECHA registration dossiers. Bottom-up volume modeling triangulated against top-down industry association aggregates.
Segment-weighting approaches applied across the analysis window distributed value and volume projections by grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from historical trajectory analysis and forward-looking capacity announcements without year-specific anchoring. Industry-specific forecast inputs incorporated alumina price correlation coefficients and CDSCO qualification pipeline velocity as demand-side indicators.
Caveats apply where alumina feedstock volatility, chlorine supply concentration shifts, or regulatory divergence between pharmaceutical-grade and industrial-grade specifications could materially shift the outlook. Forecasts reflect documented assumptions about capacity addition timelines and certification cost amortization patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ethanolamine Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Germany Methanol Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
China Amines Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
p-Coumaric Acid Market
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Lime Sulfur Market
Chemicals
Sulfuric Acid Market
Chemicals
Chromium Trioxide Market