
 Wire Compound and Cable Compound Market | 2026-2036
Wire Compound and Cable Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Compound and Cable Compound Market Intelligence
Direct sales from compounders to large-scale cable manufacturers is tilting the competitive balance away from traditional multi-tiered distribution networks. Dow Inc. leverages its vast polyethylene production scale to influence raw material costs and supply dynamics. Meanwhile, Borealis AG differentiates through its proprietary Borlink technology for demanding high-voltage applications. Teknor Apex occupies a specialized niche by providing custom thermoplastic elastomer formulations for specific industrial and medical device clients.
Wire and cable compounds are specialized polymer formulations engineered for electrical insulation and protective jacketing. These materials, including cross-linked polyethylene (XLPE), must exhibit high dielectric strength and long-term thermal stability to ensure safe power transmission. While polyvinyl chloride compounds command significant volume in lower-spec construction applications, XLPE dominates the high-voltage power transmission segment. Thermoplastic elastomers represent the fastest-growing product type, driven by needs in flexible automotive wiring and consumer electronics.
Compliance with regulations such as the EU's RoHS directive and China's national GB standards dictates material formulation, restricting substances like lead and certain flame retardants. The US EPA's oversight of chemical substances under the Toxic Substances Control Act also influences the portfolio of permissible polymer additives. Future competitive advantage will hinge on developing cost-effective, high-performance compounds that meet increasingly stringent international environmental and safety protocols.
Market Dynamics
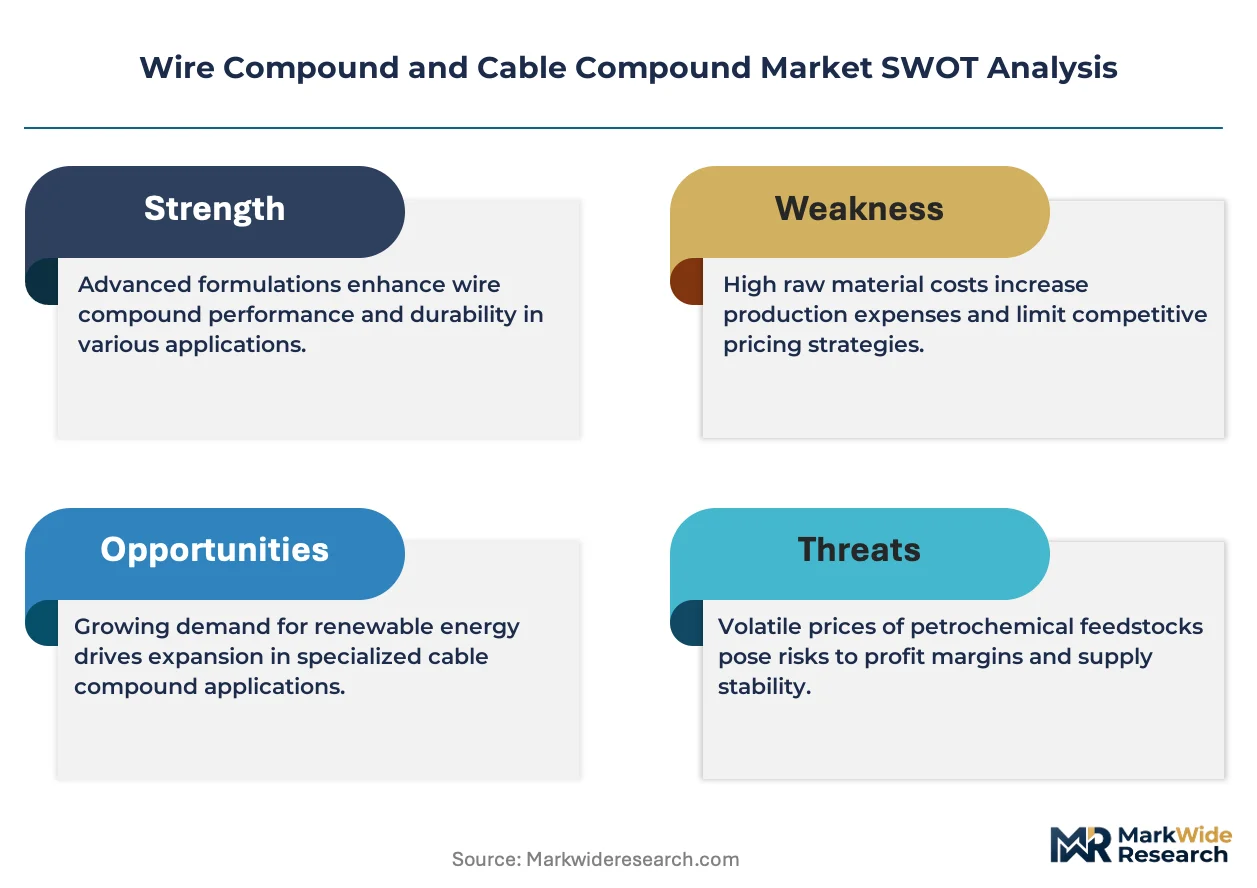
The imperative to meet stringent environmental and safety regulations, such as Europe's REACH and RoHS directives, is the central force shaping material innovation. This pressure compels compounders to develop high-performance, compliant formulations for demanding applications like electric vehicle power systems.
Growth Catalysts
- Electric Vehicle Transition:The shift to electric mobility requires complex wiring harnesses with advanced compounds for battery packs, charging systems, and high-voltage internal wiring, stimulating demand for materials with superior thermal and electrical properties.
- 5G Network Expansion:The global build-out of 5G infrastructure necessitates high-frequency cables with specialized low-loss compounds to ensure signal integrity, creating a significant demand vector for advanced polymer formulations.
- India's PLI Scheme:Production-Linked Incentive schemes in India are attracting electronics and automotive manufacturing investment, directly boosting local consumption of wire and cable compounds for a wide range of consumer and industrial goods.
Market Restraints
- Raw Material Volatility:Compound pricing and availability are highly sensitive to fluctuations in the cost of key polymer precursors like polyethylene and plasticizers, creating margin pressure and supply chain uncertainty for manufacturers.
- Regional Supply Concentration:The heavy concentration of polymer and additive production within specific geographic zones, such as China's Pearl River Delta, exposes the supply chain to significant disruption risk from localized logistical or policy changes.
- Substitution from Lower-Spec Materials:In cost-sensitive segments like residential construction, persistent price pressure from lower-performance polyvinyl chloride (PVC) compounds can limit the adoption of higher-spec, safer materials like XLPE or halogen-free alternatives.
Strategic Opportunities
- Bio-Compatible Compounds:The growing medical device and wearable technology markets present an opportunity for developing specialized thermoplastic elastomers that meet stringent biocompatibility and sterilization-resistance standards, such as those governed by the ISO 10993 series.
- Circular Economy Formulations:European Union mandates for recyclability and material circularity create a commercial opening for compounds designed for easier disassembly and recycling, particularly those incorporating post-consumer recycled content without compromising performance.
- Data Center Cabling:The expansion of hyperscale data centers requires massive quantities of flame-retardant, low-smoke communication cables, opening a specialized, high-volume market for compliant compound formulations.
Industry Challenges
- Multi-Regional Regulatory Compliance:Navigating the complex and divergent requirements of regulations like Europe's REACH, China's GB standards, and the US EPA's TSCA for chemical substances adds significant testing costs and time-to-market delays.
- Capital-Intensive Production:Manufacturing high-performance compounds, especially cross-linked materials for high-voltage applications, requires significant capital investment in specialized compounding lines and cleanroom-level quality control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Compound and Cable Compound Market |
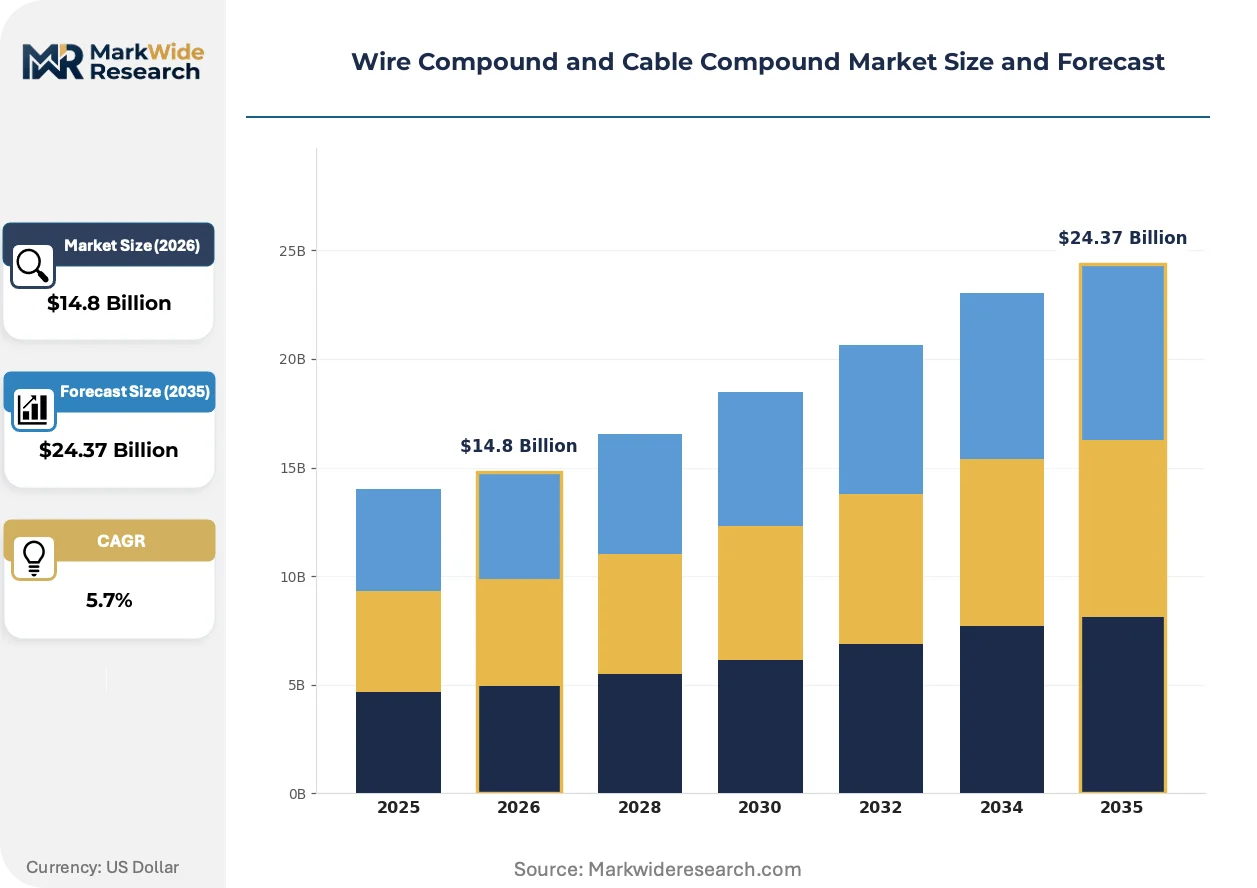
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Propylene Rubber, Polyvinyl Chloride, Cross-linked Polyethylene, Thermoplastic Elastomers, Silicone Rubber Application: Power Transmission, Automotive Wiring, Telecommunications, Consumer Electronics, Aerospace End User Industry: Utilities, Vehicle Manufacturers, Telecom Operators, Electronics Manufacturers, Aviation Sector Form: Pellets, Granules, Sheets, Liquid, Powder |
| Companies Covered | Avient Corporation, SCG Chemicals, Borealis AG, ExxonMobil Corporation, Teknor Apex, Dow Inc., Solvay, Sumitomo Electric Industries, Nexans SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Compound and Cable Compound Market Strategic Shifts & Innovations
Material science is advancing to resolve the market's core tension between escalating performance demands in applications like electric vehicles and the simultaneous regulatory push for greater environmental safety. This is driving innovation in both polymer chemistry and compound formulation to meet dual objectives.
Thermoplastic elastomers (TPEs) are advanced polymers that provide a unique combination of rubber-like elasticity and thermoplastic processability. The automotive and consumer electronics sectors are rapidly adopting these materials for flexible and durable cables. This adoption is hybridizing the material landscape, allowing for the creation of compounds that merge the performance benefits of traditional thermosets with the manufacturing efficiencies of thermoplastics.
China's national GB standards impose strict limits on hazardous substances and mandate specific flame-retardant performance for materials used in construction and electronics. This policy directly forces compounders to reformulate products, often moving away from traditional halogenated additives. The consumer electronics cable segment is most affected, requiring suppliers to validate and certify new, compliant formulations to maintain market access.
Large-scale cable manufacturers are altering procurement patterns by pursuing direct co-development partnerships with polymer compounders for critical projects. This model displaces the role of traditional intermediaries and distributors for high-volume or technically specific materials. The trend is most visible within the automotive supply chains of India and Germany, where collaboration is essential to meet the exacting specifications of new vehicle platforms.
Wire Compound and Cable Compound Market Segmentation
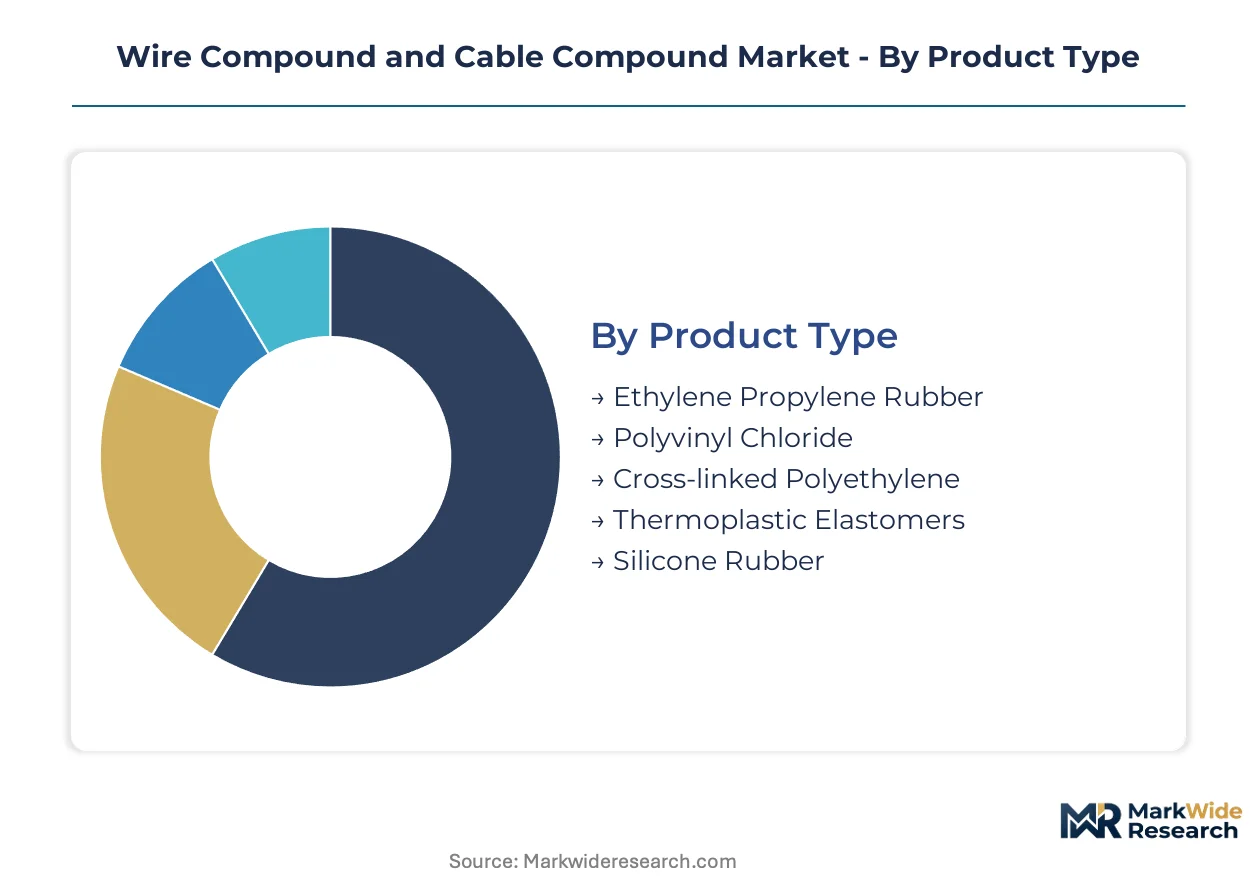
Understanding the segmentation of the wire compound and cable compound market is critical for identifying distinct material requirements and procurement dynamics. This analysis highlights how different product types, applications, end-user industries, and forms shape the competitive landscape and drive material innovation across the value chain.
Product Type:
The product type dimension delineates the fundamental chemical compositions providing distinct performance characteristics for wire and cable applications.
- Cross-linked Polyethylene:Cross-linked Polyethylene (XLPE) compounds offer superior thermal stability and dielectric strength, making them essential for demanding power transmission applications. Demand for XLPE concentrates in high-voltage grids across Europe and North America, driven by infrastructure upgrades and renewable energy integration.
- Thermoplastic Elastomers:Thermoplastic Elastomers (TPEs) combine the flexibility of rubber with the processability of thermoplastics, suitable for intricate designs. The automotive wiring segment, particularly in Germany and Japan, drives TPE adoption for flexible EV battery cables and internal harnesses.
- Polyvinyl Chloride:Polyvinyl Chloride compounds provide cost-effective insulation and jacketing for general construction and low-voltage applications.
- Ethylene Propylene Rubber:Ethylene Propylene Rubber offers excellent ozone and UV resistance, often used in medium-voltage underground cables.
- Silicone Rubber:Silicone Rubber compounds deliver high-temperature resistance and flexibility, critical for specialized industrial and medical wires.
Polyvinyl Chloride holds installed capacity. Thermoplastic Elastomers is rotating up the share rankings.
Application:
The application segment categorizes compounds based on their specific end-use environments, dictating performance requirements.
- Power Transmission:Wire compounds for power transmission require high dielectric strength and long-term thermal stability to ensure safe and efficient electricity delivery. Global demand for these compounds is robust in China's expanding grid infrastructure and India's growing industrial power networks.
- Automotive Wiring:Automotive wiring compounds must withstand extreme temperatures, vibrations, and chemical exposure, crucial for vehicle reliability. The transition to electric vehicles in the US and Europe significantly boosts demand for high-performance, lightweight automotive compounds.
- Telecommunications:Telecommunications applications demand low-loss compounds for signal integrity, essential for 5G network buildouts.
- Consumer Electronics:Consumer electronics cables require flexible and durable compounds, often meeting specific regulatory standards like RoHS for hazardous substances.
- Aerospace:Aerospace applications utilize lightweight, flame-retardant compounds with extreme temperature resistance for aircraft systems.
Power Transmission represents the highest volume segment. Automotive Wiring exhibits the steepest expansion trajectory.
End User Industry:
Customer type segmentation highlights the primary purchasers of wire and cable compounds, reflecting distinct procurement patterns.
- Vehicle Manufacturers:Vehicle manufacturers procure specialized compounds for complex wiring harnesses, emphasizing durability, weight reduction, and thermal performance. This sector's demand profile is heavily influenced by electric vehicle production targets in Germany, the US, and China.
- Utilities:Utilities purchase large volumes of compounds for power grids, prioritizing reliability, long service life, and compliance with national electrical codes. Investment in smart grid technologies and renewable energy integration across India and Australia drives compound consumption by utilities.
- Telecom Operators:Telecom operators require compounds for data and communication cables, focusing on signal integrity and outdoor durability.
- Electronics Manufacturers:Electronics manufacturers source compounds for internal wiring and external cables, driven by consumer product cycles and regulatory compliance.
- Aviation Sector:The aviation sector demands ultra-reliable, flame-retardant, and lightweight compounds for critical aircraft systems.
Utilities command the largest purchasing power. Vehicle Manufacturers are gaining share fastest due to EV production.
Form:
The form in which wire and cable compounds are supplied influences handling, processing, and application suitability for manufacturers.
- Pellets:Pellets are the most common form, offering excellent flow properties and consistent dosing for extrusion processes in cable manufacturing. Their widespread use spans general construction wiring to specialized automotive cables, particularly in manufacturing hubs like Mexico and Vietnam.
- Granules:Granules provide a balance of flowability and particle size, often preferred for specific compounding or molding applications requiring particular surface finishes. Demand for granular forms is significant in emerging industrial applications across Brazil and Indonesia, where specialized machinery is prevalent.
- Sheets:Sheets of compounds are used in niche applications such as insulation tapes or specific laminates requiring pre-formed material.
- Liquid:Liquid compounds find use in specialized coatings, potting, or encapsulating applications where flow into intricate spaces is required.
- Powder:Powdered compounds are utilized in certain specialty applications, including dry blending for specific additive packages or surface treatments.
Pellets dominate the supply volume. Granules are expanding most quickly in custom compounding operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power asymmetry exists between raw material-rich production zones and high-demand, highly regulated markets. China's concentrated polymer production centers influence global supply, while European and North American markets drive demand for advanced, compliant formulations. This dynamic shapes investment and innovation across the wire and cable compound value chain.
China
China's expanding grid infrastructure and 5G network build-out stimulate demand for power transmission and telecommunications compounds. The national GB standards mandate specific flame retardant performance and restrict hazardous substances, forcing material reformulation. Manufacturing hubs like the Pearl River Delta are adapting compound production to meet these stringent domestic requirements.
India
India's automotive corridors and growing industrial power networks drive consumption of specialized wire and cable compounds. The Production-Linked Incentive (PLI) scheme is attracting electronics and automotive manufacturing, boosting local demand. Investment in smart grid technologies across Indian states increases the need for reliable, long-service-life compounds by utilities.
Germany
Germany's robust automotive sector, particularly electric vehicle production, fuels demand for high-performance thermoplastic elastomers and XLPE compounds. Compliance with Europe's REACH and RoHS directives is a primary driver for material innovation in the country. Automotive suppliers in Bavaria and Baden-Württemberg are co-developing advanced compounds with polymer specialists.
United States
The United States' transition to electric mobility requires advanced compounds for battery packs and charging systems. US EPA oversight under the Toxic Substances Control Act (TSCA) influences permissible polymer additives and formulations. Demand for high-dielectric-strength compounds for power transmission is strong in states undergoing grid modernization.
Wire Compound and Cable Compound Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the wire and cable compound market. The competitive landscape is tiered, with large-scale polymer producers at the base and specialized compounders offering custom formulations. Strategic archetypes include commodity volume players, high-performance solution providers, and niche material innovators. Dominant competitive moves involve capacity expansion in key growth segments and strategic partnerships for co-development.
Companies with diverse material portfolios, such as Dow Inc., leverage their vast polyethylene production scale to influence raw material costs and supply dynamics. Borealis AG exemplifies specialization through its proprietary Borlink technology, targeting demanding high-voltage applications. Teknor Apex occupies a focused position by providing custom thermoplastic elastomer formulations for specific industrial and medical device clients.
| Leading Market Players |
|---|
| Avient Corporation |
| SCG Chemicals |
| Borealis AG |
| ExxonMobil Corporation |
| Teknor Apex |
| Dow Inc. |
| Solvay |
| Sumitomo Electric Industries |
| Nexans SA |
| Others |
Cost & Logistics Intelligence
China's Pearl River Delta, a major polymer production hub, directly influences raw material costs, thereby shaping global wire and cable compound pricing dynamics for downstream manufacturers.
Pricing Analysis
Configured-to-order formulations command a premium over standard, high-volume compounds in the wire and cable market. Price differentiation stems from customization level for specific applications and the performance tier, such as XLPE for high-voltage versus PVC for general construction. Pricing pressure stems from raw material volatility and competition from lower-spec alternatives in cost-sensitive segments. Residential construction applications exhibit the highest price sensitivity, while automotive and aerospace demand prioritizes performance over cost.
Supply Chain Analysis
Polymer and additive production capacity is heavily concentrated in specific geographic zones, particularly within Asia. The wire and cable compound market draws from key raw materials like polyethylene, plasticizers, and specialized flame retardant additives. Supply chain risk arises from localized logistical disruptions or policy changes in these concentrated production areas, as well as commodity price volatility. Distribution typically involves direct sales from compounders to large cable manufacturers, supplemented by specialized distributors for niche or technically demanding materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wire and cable compound market is poised for a cyclical recovery, primarily driven by renewed global infrastructure spending and the accelerating electric vehicle transition.
For Market Incumbents: Insulate core market share by deepening backward integration into critical polymer precursors to mitigate raw material volatility. Pursue strategic partnerships with major automotive OEMs in Germany and the US for co-development of advanced EV compounds. Invest in R&D for compliant, halogen-free flame retardant formulations to address evolving regulations like Europe's REACH directive. Expand production capacity in emerging automotive corridors, such as India, to capitalize on local demand.
For New Entrants and Emerging Players: Establish a beachhead in specialized, high-performance segments requiring novel material properties, such as biocompatible compounds for medical devices. Target flexible thermoplastic elastomers for electric vehicle battery cables, where rapid innovation is still occurring. A focused go-to-market angle should emphasize custom formulation capabilities and rapid certification for stringent international standards. Explore opportunities in circular economy formulations to meet future European Union mandates for recyclability.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized compounders with proprietary formulations and strong R&D capabilities in areas like high-dielectric XLPE or advanced TPEs. Long-term viability rests on sustained demand from electrification, digitalization, and infrastructure modernization projects. Acquisition targets should possess strong intellectual property in compliant, high-performance materials. Quarterly review of EV production targets and 5G deployment schedules is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Supports local automotive and electronics manufacturing under the PLI scheme. |
| Green Manufacturing Transition | Develops circular economy formulations for easier disassembly and recycling. |
| Long-term Supply Agreement with OEMs | Secures stable demand for high-performance automotive wiring compounds. |
| Joint Venture for Advanced R&D | Accelerates innovation in next-generation compliant polymer formulations. |
| Certification Investment for HFFR | Ensures market access for halogen-free flame retardant compounds in regulated markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase of this study. Interviews were conducted with R&D directors at major compounders, procurement leads at large cable manufacturers, regulatory compliance officers, and automotive design engineers. These primary insights were cross-referenced with secondary data from industry reports, regulatory filings (e.g., REACH, RoHS, China's GB standards documentation), and company financial statements. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
Forecast calibration involved a rigorous process, integrating historical market performance with projected future indicators across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user industry, form, and regional regulatory landscape. Compound Annual Growth Rates were derived from volume and value projections, cross-validated with industry expert consensus. Key industry-specific forecast inputs included electric vehicle production forecasts and 5G network deployment schedules.
Macroeconomic conditions sit as an overlay; deviation in global industrial output or energy prices would shift the trajectory of compound demand. Forecasts reflect assumptions based on current market dynamics and anticipated technological advancements. Geopolitical instability or significant shifts in raw material supply represent specific risk factors that could revise projections. Quarterly review of EV production targets and infrastructure spending is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Metalworking Treating Fluid Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Global Plating on Plastics Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Metal Forming Fluids Market