
 Butadiene Extraction Market | 2026-2036
Butadiene Extraction Market Size, Share, and Industry Trends Forecast 2026-2036
Butadiene Extraction Market Analysis
Bio-based butadiene from ethanol dehydration is decoupling from traditional naphtha-cracked supply chains. Shell leverages its integrated steam cracking complexes across the US Gulf Coast to sustain cost-advantaged C4 feedstock access. Sinopec anchors Asia-Pacific supply through state-backed refinery-petrochemical integration. LyondellBasell Industries Holdings B.V. differentiates via proprietary extractive distillation technology that improves butadiene recovery rates from mixed C4 streams.
Butadiene extraction isolates 1,3-butadiene from crude C4 hydrocarbon fractions using selective solvents such as acetonitrile or N-methylpyrrolidone at temperatures between 40°C and 60°C, yielding polymerization-grade purity above 99.5% for synthetic rubber and ABS resin production. Extractive distillation dominates process-type economics due to mature solvent recovery systems and lower capital intensity versus oxidative dehydrogenation. Automotive tires command the largest application share, though adhesive suppliers represent a faster-growing demand pocket as solvent-based bonding formulations expand in construction and footwear.
EPA emissions standards under the Clean Air Act constrain flaring and venting from US butadiene extraction units, pushing operators toward closed-loop solvent systems. REACH registration requirements in Europe mandate toxicity documentation for C4-derived intermediates, raising compliance costs for exporters. China's MEE enforces stricter volatile organic compound limits around petrochemical clusters. Stakeholders must monitor feedstock substitution economics between naphtha and bio-ethanol routes while assessing regional carbon border adjustments that could restructure trade flows in butadiene derivatives.
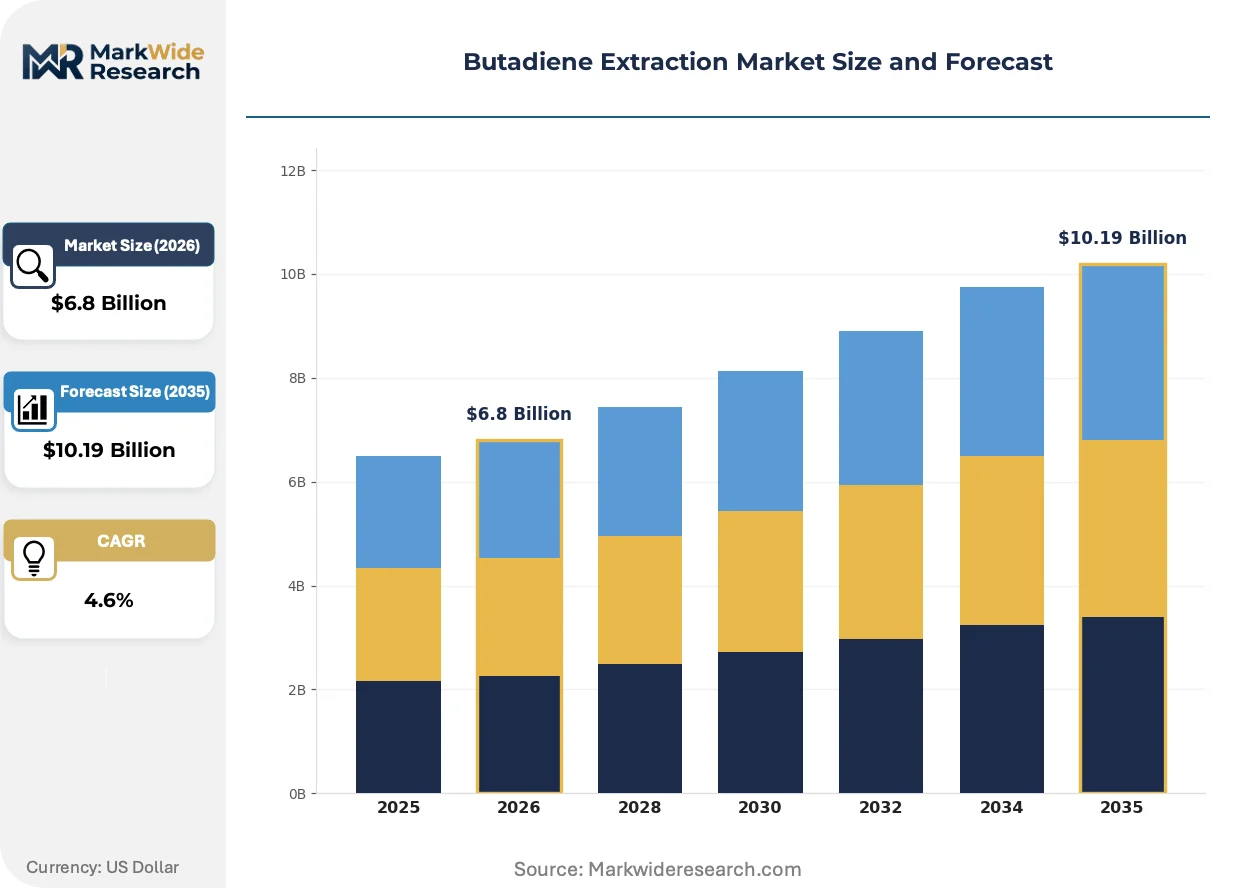
Market Dynamics
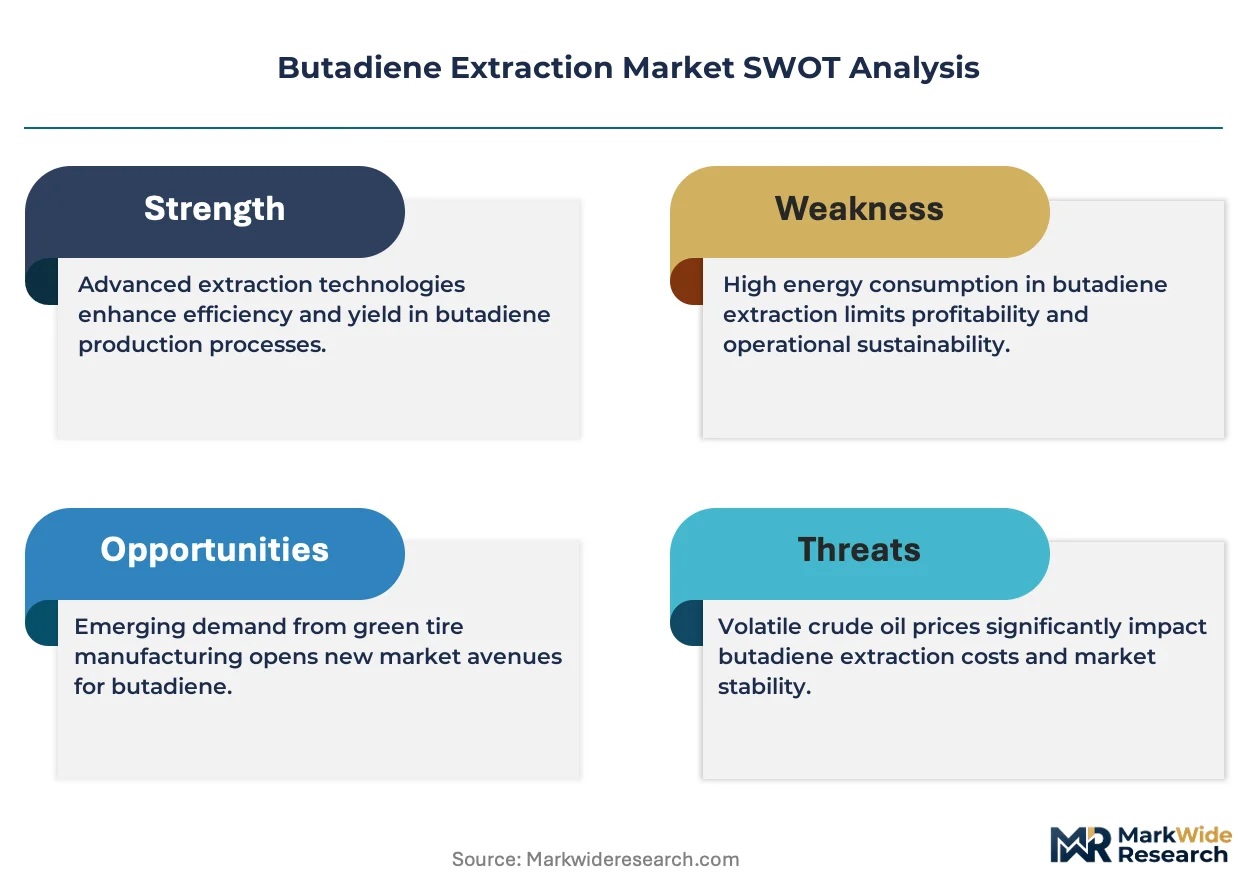
Extractive distillation economics are tightening as naphtha feedstock volatility and bio-ethanol route maturation force operators to reconfigure solvent recovery systems and carbon intensity profiles simultaneously.
Growth Catalysts
- Synthetic rubber tire demand:Automotive OEMs in China and India are expanding radial tire production capacity, pulling polymerization-grade butadiene through long-term offtake contracts with extraction unit operators.
- EPA Clean Air Act enforcement:Stricter emissions standards for volatile organic compounds from C4 processing facilities are accelerating capital deployment into closed-loop solvent systems that reduce venting losses.
- Acetonitrile solvent efficiency gains:Process licensors have improved recovery rates above 99.5% purity thresholds, lowering energy intensity per ton of butadiene extracted from mixed C4 streams.
Market Restraints
- Naphtha price volatility:Steam cracker feedstock costs swing with crude oil benchmarks, compressing butadiene extraction margins when naphtha cracks at premium differentials to ethane.
- Asia-Pacific supply concentration:State-backed refinery-petrochemical integration in China controls upstream C4 fraction availability, limiting independent extractor feedstock security elsewhere in the region.
- REACH registration burden:ECHA documentation requirements for C4-derived intermediates raise compliance costs for European extraction unit exports to derivative markets.
Strategic Opportunities
- Bio-ethanol dehydration routes:Renewable butadiene from agricultural feedstocks qualifies for EU Green Deal carbon border adjustment exemptions, creating premium positioning against naphtha-derived material.
- Adhesive formulation growth:Solvent-based bonding applications in footwear and construction are expanding faster than tire demand, offering extraction operators higher-margin specialty grade outlets.
- India petrochemical corridor development:Gujarat and Maharashtra state governments are licensing greenfield integrated complexes where butadiene extraction units anchor downstream synthetic rubber clusters.
Industry Challenges
- Extractive distillation engineering talent scarcity:Solvent system design and heat integration optimization require specialized chemical engineering expertise that competes with battery materials and hydrogen project hiring.
- Legacy unit retrofit complexity:Older naphtha crackers require simultaneous furnace and separation train upgrades to handle heavier C4 fractions without yield degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butadiene Extraction Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Steam Cracking, Extractive Distillation, Dehydrogenation, C4 Fractionation Application: Automotive Tires, Synthetic Rubber, Plastics, Adhesives Technology: Hydrocarbon Processing, Catalytic Processes, Thermal Processes, Separation Technologies End User: Chemical Manufacturers, Tire Producers, Plastic Fabricators, Adhesive Suppliers |
| Companies Covered | LyondellBasell Industries Holdings B.V., Shell, BASF SE, ExxonMobil, Sinopec, CNPC, INEOS, SABIC, TPC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butadiene Extraction Market Emerging Trajectories
Process intensification and feedstock diversification are converging to redefine extraction unit economics, with solvent chemistry advances and regulatory carbon accounting creating divergent technology adoption curves across geographies.
Membrane-assisted extractive distillation is absorbing incremental investment from operators seeking to reduce solvent circulation rates and energy consumption in C4 separation trains. Synthetic rubber producers in South Korea and Thailand are piloting hybrid configurations that combine selective membranes with conventional acetonitrile columns. This convergence is compressing the capital cost gap between greenfield extraction units and oxidative dehydrogenation alternatives.
REACH authorization timelines for N-methylpyrrolidone are forcing European extraction operators to evaluate alternative selective solvents including N-formylmorpholine and dimethylformamide. The substitution pressure is accelerating process license negotiations with technology holders holding patents on next-generation solvent systems. German and Dutch petrochemical clusters are most exposed given their reliance on NMP-based extraction trains commissioned in prior decades.
Long-term offtake contracting is displacing spot market exposure as tire manufacturers seek supply security amid feedstock route uncertainty. Procurement teams at major synthetic rubber consumers are negotiating five to seven year supply agreements with built-in price corridors tied to naphtha and ethanol benchmarks. This shift is most visible in China where state-owned tire producers are consolidating supplier relationships around integrated refinery-petrochemical operators with captive C4 supply.
Butadiene Extraction Market Segmentation
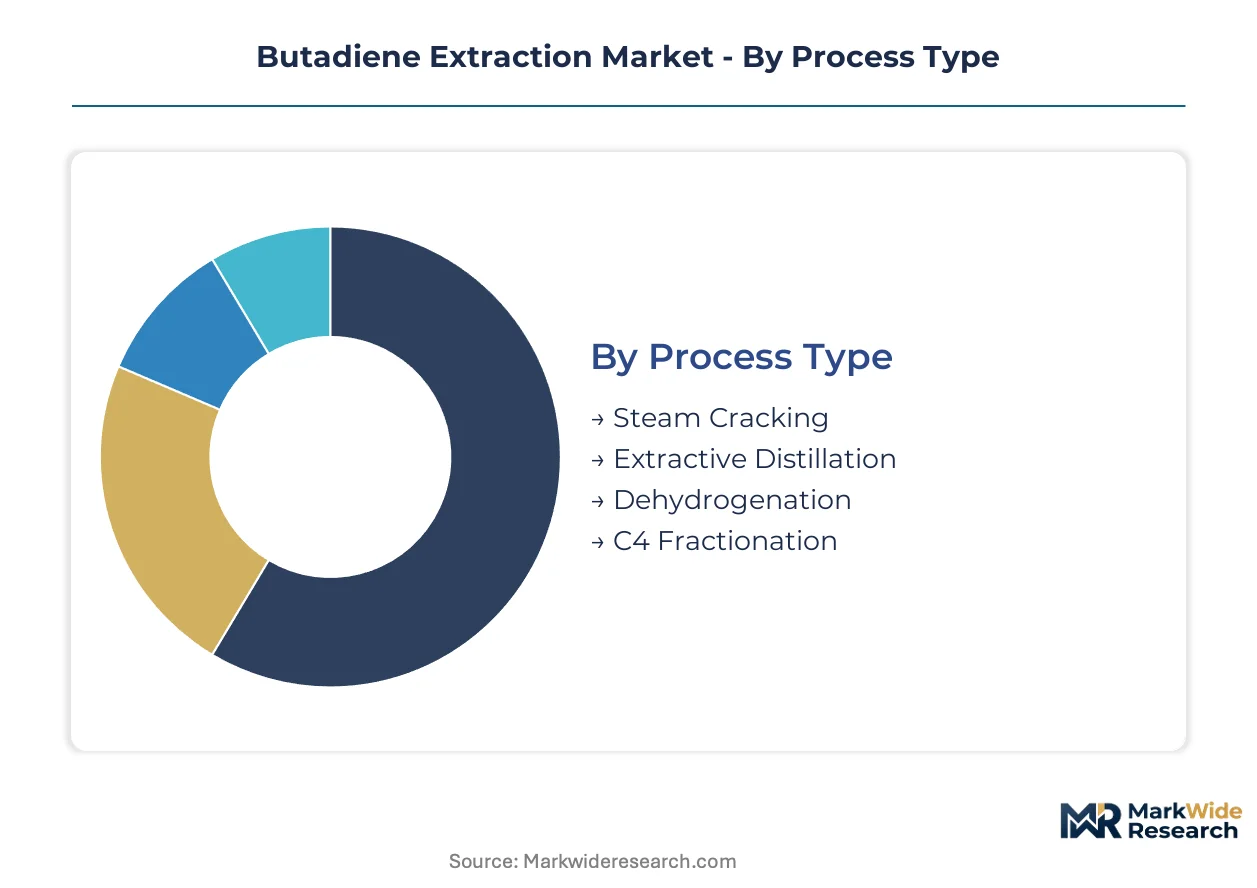
Butadiene extraction economics fragment sharply across process configurations and end-use specifications. Solvent selection, feedstock route, and polymerization-grade purity requirements create divergent margin profiles that reshape competitive positioning in each segment.
Process Type:
Supply concentration in naphtha-integrated steam cracking complexes determines feedstock security for each extraction route.
- Extractive Distillation:Acetonitrile or N-methylpyrrolidone solvents selectively separate 1,3-butadiene from mixed C4 streams at 40-60°C, achieving 99.5% polymerization-grade purity. Sinopec's state-backed refinery-petrochemical integration in China anchors capacity expansion, though REACH NMP authorization timelines in Europe force solvent substitution toward N-formylmorpholine.
- Steam Cracking:Integrated naphtha crackers generate crude C4 fractions as ethylene co-products, with butadiene recovery rates tied to furnace severity and feedstock slate. Shell's US Gulf Coast complexes leverage ethane-naphtha flexibility to sustain C4 output amid volatile feedstock differentials.
- Dehydrogenation:Catalytic conversion of n-butane or butene feeds via oxidative or non-oxidative routes, requiring higher capital intensity than extractive alternatives. Pilot deployments in South Korea target bio-ethanol dehydration integration for renewable butadiene qualification.
- C4 Fractionation:Physical separation of crude C4 streams using distillation trains without selective solvents, limited to regions with concentrated refinery-petrochemical infrastructure. Indian greenfield complexes in Gujarat are evaluating fractionation-light extraction hybrid configurations.
Today's leader: Extractive Distillation. Tomorrow's challenger: Dehydrogenation.
Application:
Cost tier separation between commodity tire rubber and specialty adhesive grades drives technology selection and solvent system investment.
- Automotive Tires:Radial tire production in China and India consumes polymerization-grade butadiene through long-term offtake contracts with integrated extraction operators. Procurement teams at state-owned tire manufacturers are consolidating supplier relationships around captive C4 supply from refinery-petrochemical complexes.
- Adhesives:Solvent-based bonding formulations in footwear and construction command premium pricing for specialty-grade butadiene with controlled oligomer content. This segment is expanding most quickly as construction activity accelerates in Southeast Asian manufacturing hubs.
- Synthetic Rubber:Styrene-butadiene and polybutadiene rubber production for industrial belting and footwear applications. Thai and South Korean producers are piloting membrane-assisted extraction to reduce solvent circulation rates.
- Plastics:Acrylonitrile-butadiene-styrene resin production for automotive interiors and consumer electronics. ABS fabricators in Japan prioritize consistent monomer quality over feedstock route flexibility.
Volume concentrates in Automotive Tires. Margin migrates toward Adhesives.
Technology:
Customer type differentiation separates integrated chemical manufacturers from standalone extraction operators with varying captive feedstock access.
- Separation Technologies:Extractive distillation columns, membrane-assisted hybrid systems, and solvent recovery trains dominate capital deployment. LyondellBasell's proprietary acetonitrile-based technology improves recovery rates above 99.5% thresholds.
- Hydrocarbon Processing:Crude C4 stream pretreatment and fractionation upstream of selective extraction. US Gulf Coast operators face EPA Clean Air Act constraints on flaring and venting from pretreatment units.
- Catalytic Processes:Dehydrogenation and dehydration catalysts for bio-ethanol and n-butane conversion routes. EU Green Deal carbon border adjustments create premium positioning for renewable feedstock qualification.
- Thermal Processes:Steam cracking furnace operation and quench systems generating C4-rich streams. Legacy unit retrofit complexity limits yield improvements at older naphtha crackers without simultaneous separation train upgrades.
Maturity favors Separation Technologies. Innovation pressure targets Catalytic Processes.
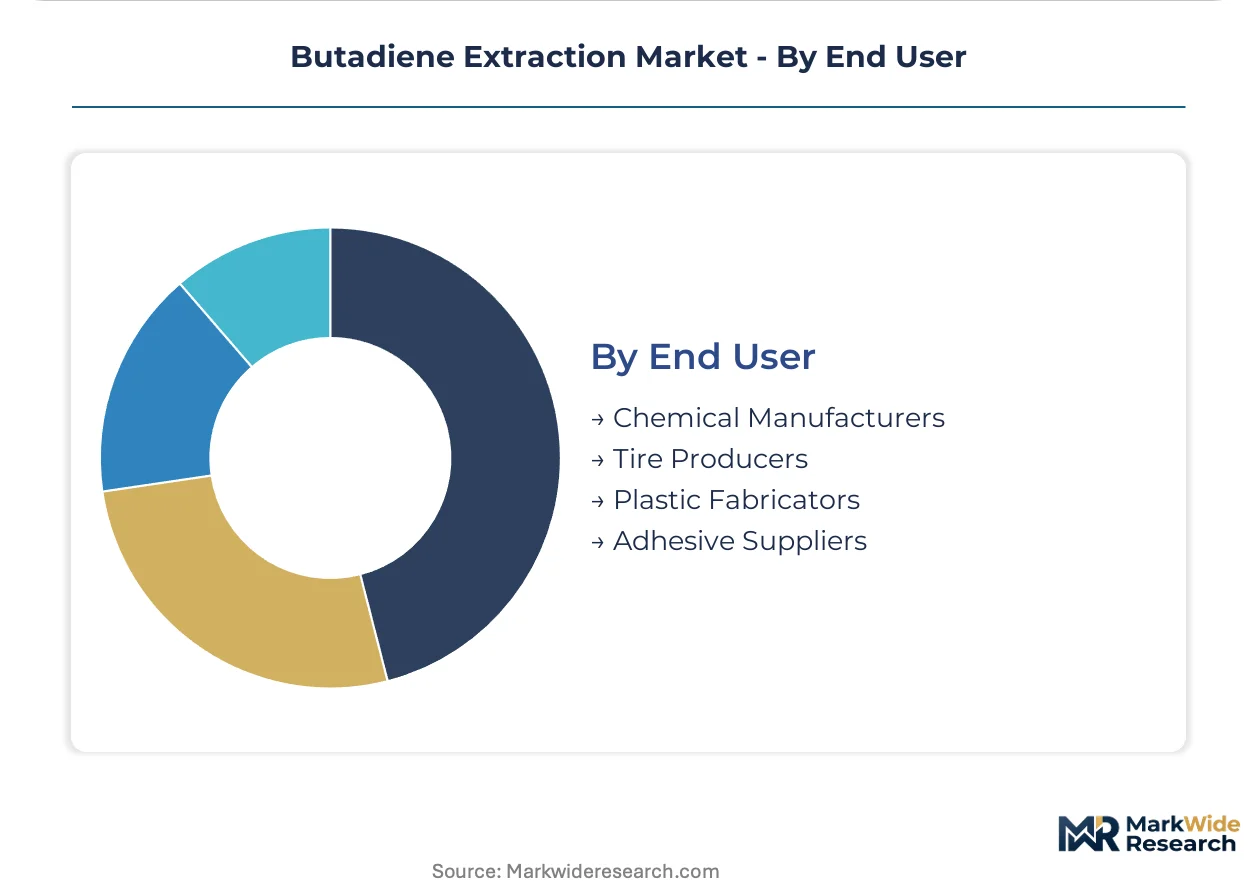
End User:
Geography of demand shapes feedstock security requirements and contract structuring across regional manufacturing clusters.
- Chemical Manufacturers:Integrated petrochemical operators with captive extraction capacity and derivative production. China's MEE volatile organic compound enforcement around clusters tightens emissions compliance for integrated sites.
- Tire Producers:Radial tire OEMs negotiating five to seven year supply agreements with built-in price corridors tied to naphtha and ethanol benchmarks. Procurement consolidation favors operators with refinery-petrochemical integration.
- Adhesive Suppliers:Specialty chemical formulators requiring consistent monomer quality for solvent-based bonding applications. Smaller volume offtakers face feedstock security challenges in Asia-Pacific's concentrated supply environment.
- Plastic Fabricators:ABS and impact modifier producers with stringent polymerization-grade specifications. Japanese fabricators source predominantly through long-term contracts with domestic extraction operators.
Contract power rests with Chemical Manufacturers. Growth velocity sits with Adhesive Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta petrochemical corridor concentrates the highest butadiene extraction capacity globally, with state-backed refinery integration securing captive C4 feedstock for derivative synthetic rubber production.
China
Radial tire manufacturers in Shandong and Jiangsu provinces drive polymerization-grade butadiene consumption through consolidated procurement from Sinopec's integrated complexes. MEE volatile organic compound enforcement around Ningbo and Shanghai clusters tightens emissions compliance for extraction operators. The Zhenhai and Jinshan petrochemical zones anchor capacity expansion with downstream styrene-butadiene rubber plants.
United States
Shell's US Gulf Coast steam cracking complexes sustain C4 output through ethane-naphtha feedstock flexibility, supplying tire plants in South Carolina and Ohio. EPA Clean Air Act constraints on flaring from C4 processing units accelerate capital deployment into closed-loop solvent recovery systems. The Houston Ship Channel and Lake Charles industrial corridors concentrate extraction capacity serving domestic synthetic rubber producers.
Germany
REACH authorization timelines for N-methylpyrrolidone force BASF and INEOS to evaluate N-formylmorpholine solvent substitutions in extraction trains at Ludwigshafen and Cologne sites. ECHA documentation requirements for C4-derived intermediates raise compliance costs for exports to derivative markets. The Rhine-Ruhr chemical corridor hosts Europe's densest concentration of butadiene extraction and downstream ABS resin production.
India
Gujarat and Maharashtra state governments license greenfield integrated complexes where extraction units anchor downstream synthetic rubber clusters for footwear and industrial belting. BIS quality standards for polymerization-grade butadiene tighten import specifications for adhesive formulators. The Dahej and Nagothane manufacturing zones attract investment from tire OEMs seeking captive monomer supply.
South Korea
Yeosu and Ulsan petrochemical complexes pilot membrane-assisted extractive distillation to reduce solvent circulation rates in C4 separation trains. MFDS chemical registration requirements for imported feedstock intermediates add documentation burdens for non-integrated operators. The Yeosu National Industrial Complex hosts the highest butadiene extraction density per square kilometer globally.
Butadiene Extraction Market Vendor Landscape
Global majors compete with regional champions across feedstock integration depth, with state-backed petrochemical groups controlling upstream C4 supply in Asia while independent extractors in North America and Europe rely on merchant feedstock markets. The vendor base organizes around three archetypes: integrated refinery-petrochemical operators with captive steam cracking, technology licensors holding proprietary solvent system patents, and standalone extraction specialists serving spot and contract markets. Dominant competitive moves include backward integration into naphtha cracking capacity and strategic partnerships with tire manufacturers for long-term offtake security.
Within the integrated operator tier, Sinopec and Shell exemplify divergent geographic strategies—Sinopec anchoring Asia-Pacific supply through state-backed refinery-petrochemical integration, Shell leveraging US Gulf Coast ethane-naphtha flexibility. LyondellBasell occupies a position as a technology-anchored specialist, with its proprietary extractive distillation systems representing the process efficiency benchmark for acetonitrile-based separation.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| Shell |
| BASF SE |
| ExxonMobil |
| Sinopec |
| CNPC |
| INEOS |
| SABIC |
| TPC Group |
| Others |
Supply Flow & Price Mechanics
Polymerization-grade purity certification at 99.5% separates specialty adhesive contracts from commodity tire offtake agreements, with this quality bifurcation embedding acetonitrile solvent recovery costs into premium pricing while naphtha feedstock volatility compresses margins at standard grades across integrated and standalone extraction configurations alike.
Pricing Analysis
Naphtha benchmark pass-through dominates contract structuring, with long-term offtake agreements to tire manufacturers incorporating price corridors tied to regional cracking economics. Price differentiation hinges on solvent system efficiency and REACH compliance documentation tiers. Cost compression in standard-grade tire rubber intensifies as bio-ethanol routes achieve scale. Tire OEMs exhibit highest price sensitivity, while adhesive formulators absorb premiums for controlled oligomer content.
Supply Chain Analysis
REACH registration and BIS quality certification gate European and Indian market access respectively, filtering feedstock intermediates through compliance documentation layers. Supply concentrates in China, the United States, and Germany, with crude C4 fractions, acetonitrile solvents, and catalytic dehydrogenation units forming critical input dependencies. Single-source vulnerability runs through Asia-Pacific's state-backed refinery integration. Distribution feeds from integrated petrochemical complexes through long-term contracts to downstream synthetic rubber clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The butadiene extraction market functions as a stable compounder, with automotive tire demand providing steady volume baselines even as bio-based feedstock economics reshape marginal supply growth.
For Market Incumbents: To counter bio-ethanol route displacement in European premium segments, Sinopec and Shell should deepen captive C4 integration through refinery-petrochemical complex expansion in Ningbo and Lake Charles respectively, while accelerating N-formylmorpholine solvent substitution ahead of REACH NMP authorization deadlines to preserve Ludwigshafen and Cologne asset viability. For New Entrants and Emerging Players: Begin with adhesive specialty-grade positioning in Gujarat's Dahej manufacturing zone, where BIS import specifications create qualification barriers for established exporters and membrane-assisted extractive distillation pilots offer technology differentiation against legacy acetonitrile systems serving commodity tire contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone extraction operators lack captive steam cracking capacity and face naphtha price volatility without long-term offtake coverage. Five-to-ten year viability favors integrated operators with ethane-naphtha feedstock flexibility. The signal to watch is tire manufacturer procurement consolidation around state-backed petrochemical groups in China and India.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Cracking | Shell's US Gulf Coast ethane flexibility secures C4 supply amid volatile feedstock differentials. |
| Green Manufacturing Transition | Bio-ethanol dehydration routes qualify for EU Green Deal carbon border adjustment exemptions. |
| Long-term Supply Agreement | State-owned tire producers in Shandong consolidate five-to-seven year offtake with Sinopec. |
| Joint Venture | Gujarat state licenses greenfield complexes anchoring synthetic rubber clusters for footwear. |
| Technology Licensing | LyondellBasell's proprietary acetonitrile systems set 99.5% recovery rate benchmarks globally. |
Methodological Framework
Multiple input streams — extraction unit operators, tire manufacturer procurement leads, solvent technology licensors, and regulatory compliance officers — were reconciled against customs trade data, SEC petrochemical division filings, ECHA REACH registration databases, and ACC industry capacity reports. Bottom-up capacity modeling across naphtha-integrated and standalone configurations was cross-validated through top-down demand aggregation from synthetic rubber and ABS resin production forecasts.
Data-stream reconciliation anchored volume projections across the analysis window, with segmentation modeling across process type, application grade, and regional production hub clusters. CAGRs were derived from weighted feedstock substitution scenarios and regulatory timeline assumptions. Industry-specific inputs included MEE volatile organic compound enforcement trajectories and EU Green Deal carbon border adjustment implementation pacing.
Several conditions sit outside the modeled scope, including unannounced refinery-petrochemical complex shutdowns, breakthrough catalytic dehydrogenation yield improvements, and abrupt REACH solvent authorization reversals. Forecasts assume documented naphtha-to-ethanol feedstock economics and regional emissions compliance trajectories. A model refresh is warranted upon material change in China's dual carbon policy enforcement or bio-ethanol route cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Global Silicone Fluid Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Adblue Market
Industrial Chemicals
FCCL Coating Machine Market