
 Enzymatically Hydrolyzed Carboxymethyl Cellulose Market | 2026-2036
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market Analysis
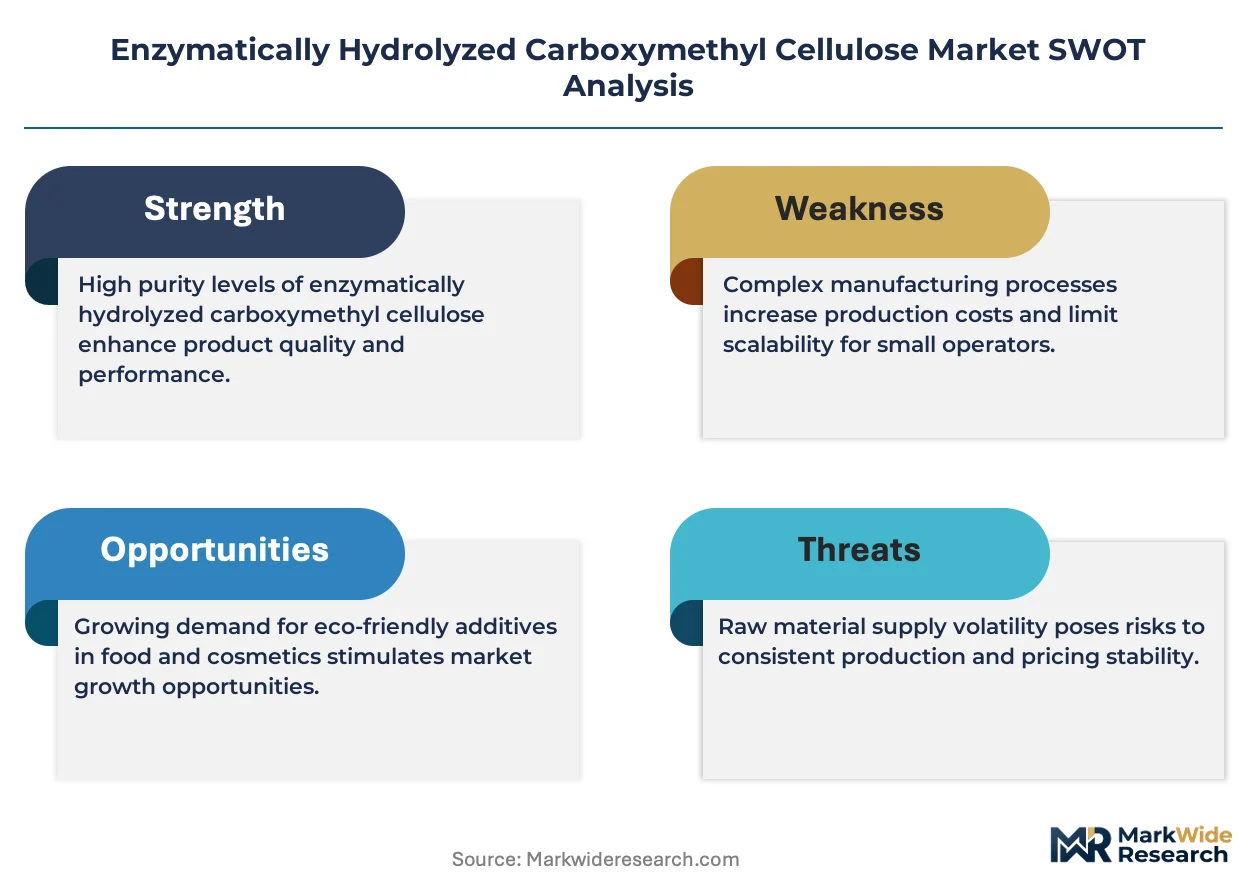
Capital-intensity divergence between integrated cellulose producers and specialty enzyme houses is bifurcating competitive dynamics. Nouryon leverages backward integration into sustainable forestry feedstocks to secure cost-advantaged raw material positions. Ashland Inc. anchors its position through pharmaceutical-grade certification depth across multiple regulatory jurisdictions. CP Kelco differentiates via microbial fermentation expertise that tightens molecular-weight distribution in finished grades.
Enzymatically hydrolyzed carboxymethyl cellulose denotes a water-soluble anionic polysaccharide derived from cellulose ether subjected to controlled enzymatic depolymerization, typically achieving degrees of substitution between 0.7 and 1.5 and viscosity ranges from 10 to 5,000 mPa·s depending on chain-length targets. The material functions primarily as a rheology modifier, stabilizer, and controlled-release matrix across formulated products. Sodium carboxymethyl cellulose commands the dominant product position due to its compatibility with aqueous systems and established pharmacopeial monographs. Food industry applications represent the fastest-expanding demand pool as clean-label thickeners displace synthetic alternatives. Direct sales channels capture premium-margin transactions where technical service integration determines specification adherence.
FDA excipient guidance, REACH substance registration requirements, and EMA quality guidelines collectively elevate purity and documentation thresholds for enzymatically modified cellulose entrants. These frameworks compel manufacturers to invest in GMP-certified enzymatic processing infrastructure rather than conventional chemical hydrolysis assets. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF and EP monographs as specification divergence threatens formulation transferability across Atlantic supply chains.
Market Dynamics
Pharmaceutical-grade enzymatic processing certification is bifurcating supply capabilities, separating GMP-certified producers from commodity cellulose houses unable to absorb validation costs.
Growth Catalysts
- Clean-label food mandates:EU EFSA guidance on additive labeling is accelerating enzymatic hydrolysis adoption over chemically modified alternatives in European processed foods.
- REACH substance registration thresholds:ECHA's tightened documentation requirements for modified cellulose derivatives are consolidating supply toward established enzymatic processors with existing dossiers.
- Controlled-release pharmaceutical demand:Oral solid dosage form manufacturers are specifying narrow-viscosity-range enzymatic grades for matrix tablet formulations.
Market Restraints
- Specialty enzyme input volatility:Cellulase procurement from microbial fermentation suppliers concentrates in Danish and Dutch biotech clusters, exposing processors to single-source risk.
- Pharmacopeial harmonization gaps:Divergent USP-NF and EP monograph specifications for degree of substitution create formulation transfer barriers across Atlantic supply chains.
- Native starch substitute pressure:Cold-water-soluble modified starches from tropical agriculture are capturing thickening applications in cost-sensitive food segments.
Strategic Opportunities
- Indian pharmaceutical excipient qualification:CDSCO's accelerating ANDA review timelines are opening formulation partnerships with domestic drug manufacturers seeking USP-grade supply security.
- Personalized medicine dosage formats:3D-printed pharmaceutical tablets require precisely tuned rheology modifiers that enzymatic processing can deliver through molecular-weight control.
- Bio-based packaging films:Edible and water-soluble film applications for unit-dose pharmaceuticals represent an emerging specification channel with premium pricing potential.
Industry Challenges
- GMP enzymatic facility commissioning:Validated clean-room fermentation and downstream processing infrastructure requires 18-24 month qualification timelines that strain working capital.
- Analytical method transfer:Degree-of-substitution and molecular-weight distribution testing protocols lack standardization across contract laboratories, delaying customer qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enzymatically Hydrolyzed Carboxymethyl Cellulose Market |
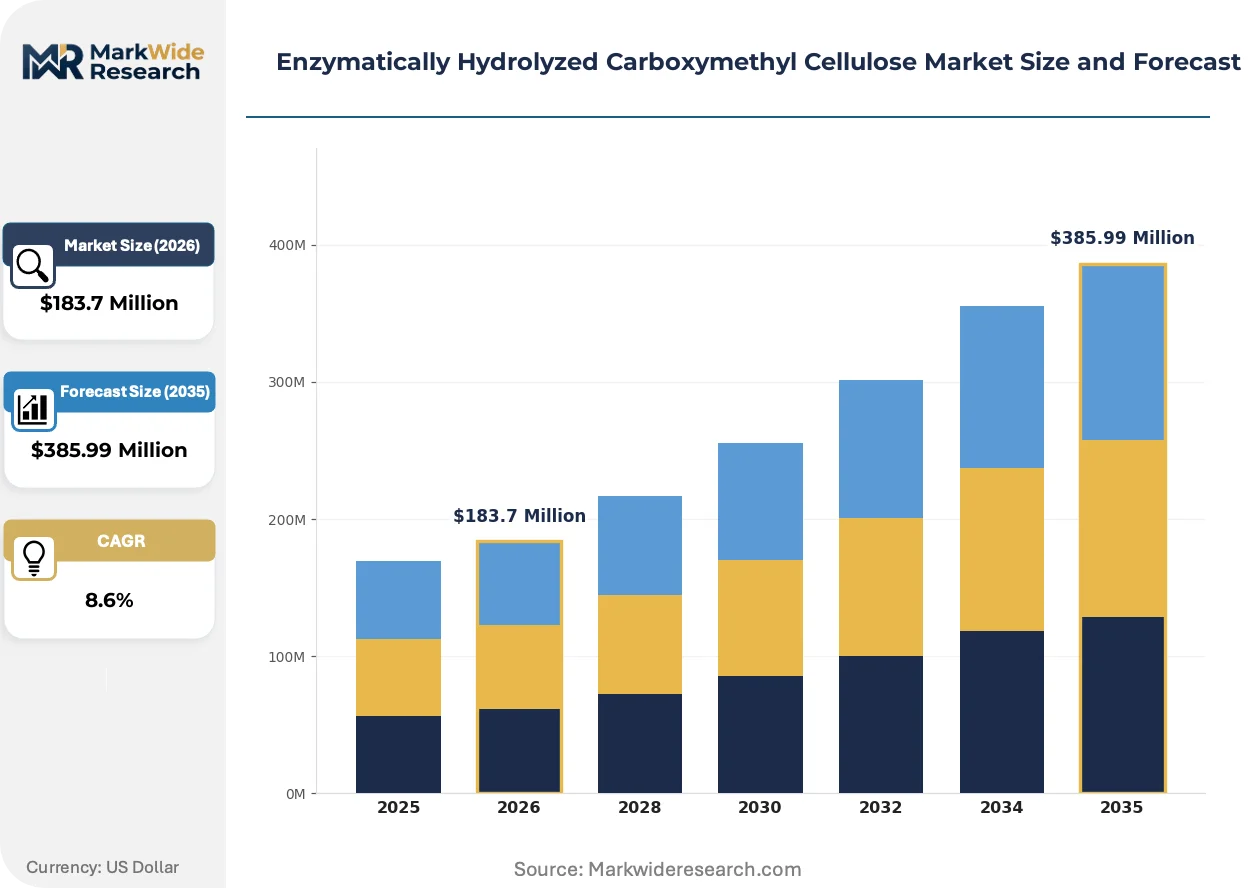
| Market Size in 2026 | $183.7 Million |
| Market Size in 2035 | $385.99 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Carboxymethyl Cellulose, Calcium Carboxymethyl Cellulose, Hydroxypropyl Methylcellulose, Modified Starch Application: Food Industry, Pharmaceuticals, Personal Care, Oil & Gas End User: Food Manufacturers, Cosmetic Companies, Biomedical Firms, Chemical Suppliers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Nouryon, Ashland Inc., Akzo Nobel N.V., CP Kelco, The Dow Chemical Company, J.M. Huber Corporation, Anqiu Eagle Cellulose Co., Ltd., Quimica Amtex, Lamberti S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market Emerging Trajectories
Enzymatic specificity is displacing chemical hydrolysis as the dominant processing paradigm, reshaping capital deployment and technical service requirements across value chain tiers.
Continuous enzymatic flow reactors with immobilized cellulase systems are supplanting batch stirred-tank processing in new capacity investments. European specialty chemical houses are piloting these systems to tighten viscosity specification windows for pharmaceutical customers. The shift is compressing batch-to-batch variability and enabling real-time release testing protocols that chemical hydrolysis cannot match.
EMA's revised excipient risk assessment guidelines now mandate supply chain documentation for enzymatically modified cellulose grades used in parenteral formulations. The framework compels manufacturers to trace enzyme source organisms and fermentation media components through qualified suppliers. Parenteral drug sponsors in Germany and Switzerland are requiring this documentation upstream in specification development.
Direct technical service engagement is replacing distributor-mediated procurement for pharmaceutical-grade volumes. Formulation scientists at mid-size drug developers now expect on-site rheology support and co-development partnerships. The pattern concentrates in the Research Triangle and Boston-Cambridge clusters where biotech formulation activity clusters.
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market Segmentation
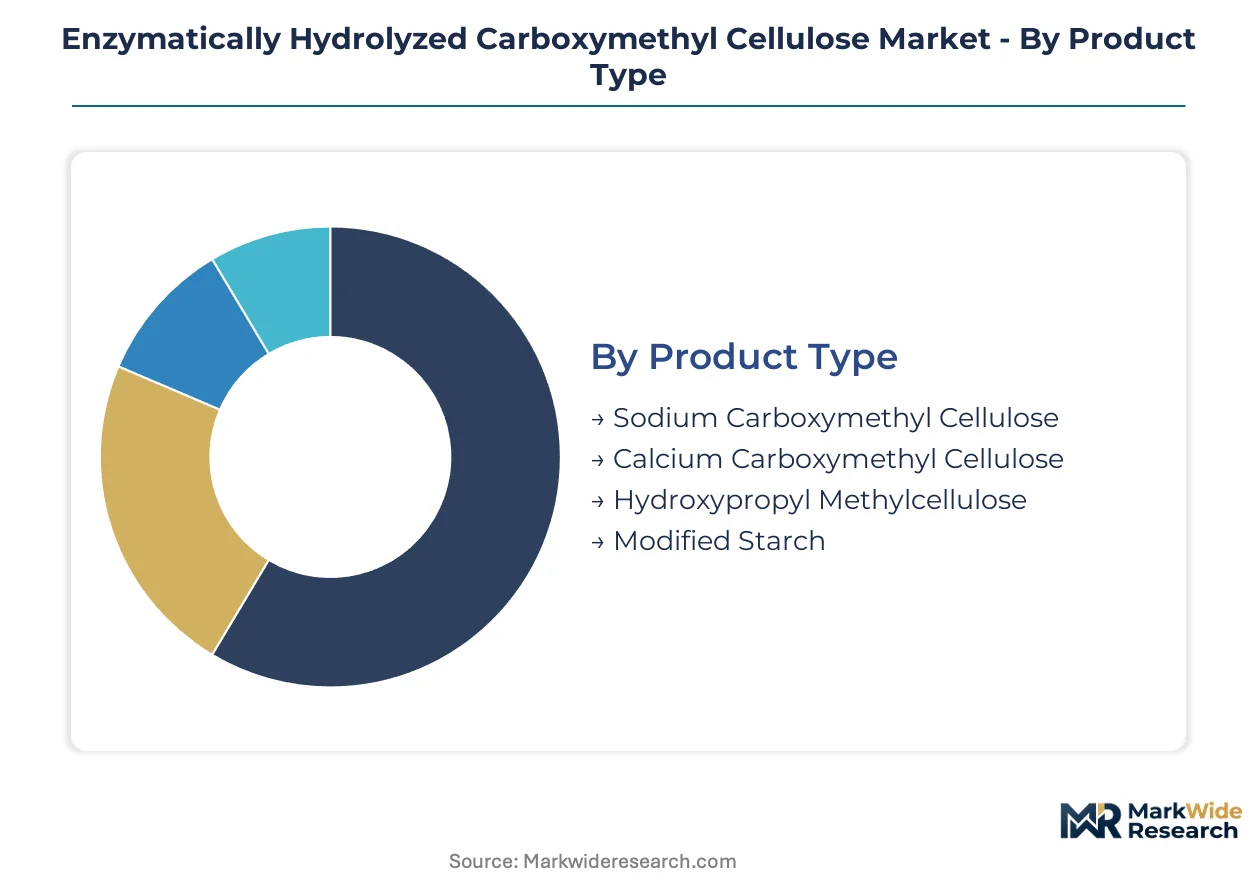
Segmentation in enzymatically hydrolyzed carboxymethyl cellulose reveals how specification intensity and regulatory burden fragment procurement patterns. Pharmaceutical-grade sodium salts command premium direct sales channels, while food-grade volumes flow through distributor networks serving reformulation mandates.
Product Type:
Channel-mix divergence separates pharmaceutical-grade sodium salts flowing through direct technical service relationships from food-grade alternatives distributed through bulk chemical wholesalers.
- Sodium Carboxymethyl Cellulose:Anionic water-soluble polysaccharide with degree of substitution typically 0.7-1.5 and viscosity ranges 10-5,000 mPa·s. German drug manufacturers specify narrow-viscosity enzymatic grades for oral solid dosage matrix formulations under EMA quality guidelines. Direct sales channels with integrated rheology support capture premium-margin transactions.
- Calcium Carboxymethyl Cellulose:Divalent cation salt offering modified gelation profiles and reduced sodium content for specialized dietary applications. Calcium grades concentrate in personal care emulsion stabilization where electrolyte tolerance requirements diverge from pharmaceutical monographs. REACH registration dossiers for calcium salts lag sodium counterparts, consolidating supply toward established processors.
- Hydroxypropyl Methylcellulose:Cellulose ether with thermogelation properties distinct from carboxymethyl chemistries.
- Modified Starch:Cold-water-soluble tropical agriculture derivative competing on cost in thickening applications.
Sodium Carboxymethyl Cellulose dominates installed base. Food Industry applications are where expansion concentrates fastest.
Application:
Cost-tier stratification separates parenteral-grade pharmaceutical specifications from commodity food thickening, with personal care occupying a mid-tier certification position.
- Food Industry:Clean-label thickening and stabilizing in processed foods where EU EFSA additive labeling guidance accelerates enzymatic hydrolysis adoption over chemically modified alternatives. Bakery and dairy reformulation in Germany and France drives specification volume through distributor channels serving mid-size processors.
- Pharmaceuticals:Controlled-release matrix tablets, ophthalmic solutions, and parenteral formulations demanding GMP-certified enzymatic processing with documented enzyme source organisms. CDSCO's accelerating ANDA review timelines in India open formulation partnerships requiring USP-grade supply security.
- Personal Care:Emulsion stabilization and rheology modification in topical formulations with moderate purity thresholds.
- Oil & Gas:Drilling fluid viscosity control and filtration reduction in exploration applications.
Pharmaceuticals dominates installed base. Food Industry is where expansion concentrates.
End User:
Customer-type concentration shapes service intensity, with biomedical firms demanding co-development partnerships while chemical suppliers negotiate commodity tonnage contracts.
- Food Manufacturers:Processed food and beverage producers reformulating under clean-label mandates, procuring through regional distributors with technical service limitations.
- Cosmetic Companies:Personal care formulators seeking emulsion stability with moderate documentation requirements.
- Biomedical Firms:Drug developers and medical device manufacturers requiring pharmacopeial-grade supply with batch-specific certificates of analysis. Boston-Cambridge and Research Triangle biotech clusters specify on-site rheology support and real-time release testing protocols.
- Chemical Suppliers:Intermediary processors and toll manufacturers purchasing bulk grades for downstream modification.
Biomedical Firms dominate installed base. Food Manufacturers are where expansion concentrates.
Distribution Channel:
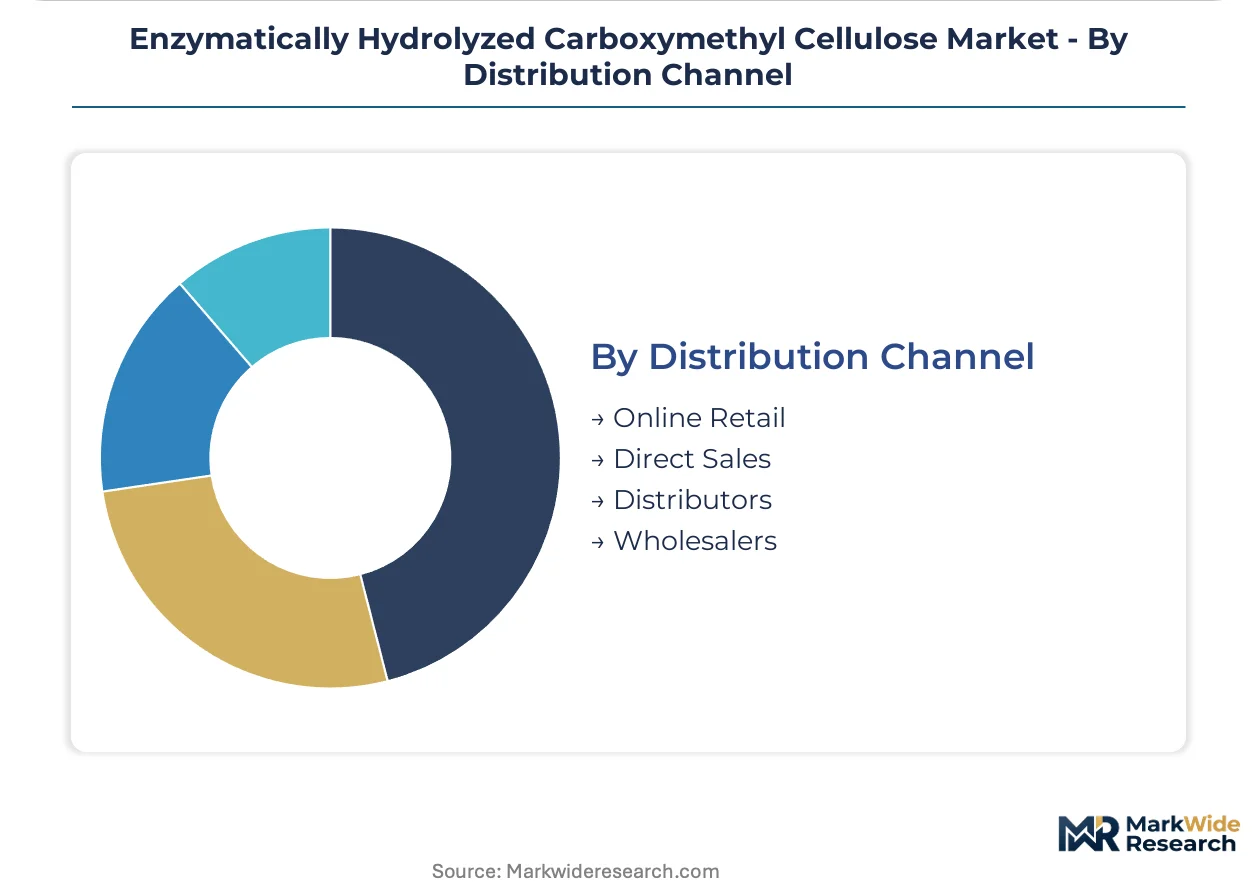
Volume-maturity divergence concentrates pharmaceutical-grade transactions in direct channels while food-grade tonnage flows through established wholesale networks.
- Direct Sales:Technical service-integrated procurement for pharmaceutical and biomedical customers requiring specification adherence support. European specialty chemical houses and integrated cellulose producers deploy formulation scientists to customer sites for rheology troubleshooting.
- Distributors:Regional chemical distributors serving food and personal care manufacturers with standardized grades and limited technical support.
- Online Retail:Small-volume procurement for research and development laboratories.
- Wholesalers:Bulk tonnage aggregation for cost-sensitive industrial applications.
Direct Sales dominates installed base. Distributors are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German pharmaceutical manufacturers specify narrow-viscosity enzymatic grades for oral solid dosage forms, while Indian drug developers prioritize USP-grade supply security for ANDA submissions. Food industry reformulation in France and clean-label mandates in the United States reshape demand composition.
Germany
Specialty chemical clusters in North Rhine-Westphalia anchor enzymatic processing capacity for pharmaceutical-grade output. REACH substance registration requirements under ECHA tighten documentation thresholds for modified cellulose derivatives. The Cologne-Düsseldorf corridor houses GMP-certified fermentation infrastructure serving parenteral formulation sponsors.
United States
FDA excipient guidance on modified cellulose drives specification adherence for controlled-release matrix tablets. Boston-Cambridge and Research Triangle biotech clusters demand on-site rheology support and real-time release testing protocols. Direct technical service engagement replaces distributor-mediated procurement for premium-grade volumes.
India
CDSCO's accelerating ANDA review timelines open formulation partnerships requiring pharmacopeial-grade supply security. Maharashtra and Gujarat host domestic drug manufacturers seeking backward integration into excipient sourcing. Mumbai-Pune pharmaceutical corridors drive specification volume for oral solid dosage applications.
France
EU EFSA guidance on additive labeling accelerates enzymatic hydrolysis adoption over chemically modified alternatives in processed foods. Bakery and dairy reformulation in the Île-de-France and Auvergne-Rhône-Alpes regions concentrates demand through distributor channels. Lyon-based food processors specify clean-label thickeners for European export markets.
Switzerland
Swissmedic quality guidelines elevate purity thresholds for enzymatically modified cellulose in parenteral formulations. Basel-Zurich pharmaceutical corridors require documented enzyme source organisms and fermentation media traceability. Specialty chemical houses serve drug sponsors with integrated supply chain documentation.
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in enzymatically hydrolyzed carboxymethyl cellulose supply. Tier-one positions consolidate around backward integration into sustainable forestry feedstocks and GMP-certified enzymatic processing infrastructure. Three archetypes dominate: integrated cellulose producers with captive raw material positions, specialty enzyme houses with microbial fermentation expertise, and pharmaceutical-grade certification specialists with multi-jurisdictional monograph depth. Competitive moves concentrate on capacity expansion in GMP-certified facilities and strategic partnerships for enzyme procurement security.
Within the integrated producer tier, Nouryon and Ashland Inc. exemplify divergent strategic positions. Nouryon anchors European supply through forestry-linked raw material control. Ashland Inc. occupies a certification-focused position spanning multiple pharmacopeial jurisdictions. CP Kelco represents the fermentation-specialist archetype, with microbial processing expertise tightening molecular-weight distribution. These three companies illustrate how capital-intensity divergence separates integrated leaders from commodity cellulose houses unable to absorb validation costs.
| Leading Market Players |
|---|
| Nouryon |
| Ashland Inc. |
| Akzo Nobel N.V. |
| CP Kelco |
| The Dow Chemical Company |
| J.M. Huber Corporation |
| Anqiu Eagle Cellulose Co., Ltd. |
| Quimica Amtex |
| Lamberti S.p.A. |
| Others |
Supply Flow & Price Mechanics
REACH substance registration thresholds under ECHA simultaneously gate supply qualification and stratify price differentiation, forcing pharmaceutical-grade enzymatic processors to absorb validation costs that commodity cellulose houses cannot bear while commanding corresponding premium capture.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical-grade transactions where GMP-certified enzymatic processors secure volume commitments from oral solid dosage form manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates parenteral-grade sodium salts with documented enzyme source organisms from food-grade alternatives distributed through wholesale channels. Pricing pressure stems from native starch substitutes capturing thickening applications in cost-sensitive European bakery and dairy segments. Food manufacturers exhibit highest price sensitivity, while biomedical firms prioritize supply security and batch-specific certificates of analysis over unit cost.
Supply Chain Analysis
Germany and the Netherlands anchor enzymatic processing capacity for pharmaceutical-grade output, with Danish biotech clusters supplying cellulase enzymes from microbial fermentation. Supply chains draw from sustainable forestry feedstocks in Nordic regions and specialty enzyme inputs concentrated in single-source fermentation facilities. Single-source vulnerability in cellulase procurement exposes processors to supply interruption from Danish and Dutch biotech clusters. Distribution runs through direct technical service relationships for pharmaceutical grades and regional chemical distributors for food and personal care volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated clean-room fermentation infrastructure represents the critical capability gap separating qualified suppliers from commodity cellulose houses, with 18-24 month GMP qualification timelines creating defendable moats for incumbent processors.
For Market Incumbents: Consolidate backward integration into sustainable forestry feedstocks to secure cost-advantaged raw material positions against emerging Asian cellulose producers. Expand GMP-certified enzymatic processing capacity in the Cologne-Düsseldorf corridor to capture parenteral formulation demand from Swiss and German drug sponsors requiring documented enzyme source organisms and fermentation media traceability. For New Entrants and Emerging Players: Differentiate on microbial fermentation expertise that tightens molecular-weight distribution for 3D-printed pharmaceutical tablet applications requiring precisely tuned rheology modifiers. Target Indian pharmaceutical excipient qualification partnerships with domestic drug manufacturers in Maharashtra and Gujarat seeking USP-grade supply security for CDSCO ANDA submissions, deploying direct technical service engagement to bypass established distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated chemical conglomerates with underutilized GMP-certified enzymatic processing assets lacking pharmaceutical-grade certification depth across multiple regulatory jurisdictions. Long-term viability hinges on pharmacopeial harmonization between USP-NF and EP monographs enabling formulation transferability across Atlantic supply chains. Watch EMA's revised excipient risk assessment guidelines for parenteral formulations as the inflection indicator for documentation-intensive supply chain investments.| Strategic Initiative | Industry Significance |
|---|---|
| GMP-Certified Capacity Expansion | Validates clean-room fermentation infrastructure serving parenteral drug sponsors under EMA quality guidelines. |
| Backward Integration into Forestry Feedstocks | Secures cost-advantaged raw material positions against commodity cellulose competitors in Nordic regions. |
| Continuous Flow Reactor Investment | Immobilized cellulase systems compress batch-to-batch variability for real-time release testing protocols. |
| Indian Formulation Partnerships | CDSCO's accelerating ANDA review timelines open excipient supply security agreements with domestic manufacturers. |
| Pharmacopeial Harmonization Advocacy | Alignment between USP-NF and EP monographs reduces formulation transfer barriers across Atlantic supply chains. |
Methodological Framework
A spread of perspectives from pharmaceutical formulation scientists, enzymatic processing plant managers, CDSCO regulatory affairs leads, and specialty enzyme procurement directors converged on the working assumptions shaping demand trajectories. Primary fieldwork combined structured interviews with downstream OEM procurement teams and distribution channel partners serving food and personal care manufacturers. Secondary validation drew from EMA quality guidelines, FDA excipient guidance documents, REACH substance registration dossiers, and SEC filings of integrated cellulose producers. Bottom-up segment sizing triangulated against top-down market envelope checks.
Segmentation dimensions modeled include product type grade tier, application industry, end-user customer type, and distribution channel structure across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating pharmaceutical pipeline progression rates and food industry reformulation mandates. Forecast inputs incorporated EFSA clean-label guidance adoption curves and CDSCO ANDA review timeline acceleration patterns.
Decision-makers should treat outputs as directional under sustained REACH compliance costs and stable cellulase fermentation supply; material deviation in pharmacopeial harmonization or enzyme input concentration would warrant model refresh. Recalibration cycles align with material shifts in EMA excipient risk assessment frameworks and FDA guidance revisions on modified cellulose derivatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Soap Noodles Market