
 1,4-Dioxane Market | 2026-2036
1,4-Dioxane Market Size, Share, and Industry Trends Forecast 2026-2036
1,4-Dioxane Market Analytics
The gap between pharmaceutical-grade and industrial-grade 1,4-dioxane is broadening as purity specifications diverge sharply between regulated life-science applications and commodity solvent markets. Dow Chemical leverages its integrated petrochemical network to sustain cost leadership in bulk industrial solvent output. BASF differentiates through controlled impurity profiles that meet European pharmaceutical excipient standards. Jiangsu Senxuan Pharmaceutical anchors high-purity production for healthcare end users across East Asia.
1,4-Dioxane is a cyclic ether with the molecular formula C4H8O2, manufactured primarily through acid-catalyzed dehydration of ethylene glycol or catalytic hydrogenation of diethylene glycol, serving as a polar aprotic solvent and reaction intermediate in specialty chemical synthesis. The industrial solvent segment dominates volume consumption in paints and adhesives manufacturing, though margin pools concentrate in the chemical reagent category where pharmaceutical and laboratory certification commands premium pricing. Aerospace fluid applications represent a smaller but technically demanding niche with stringent moisture and particulate specifications.
The EPA regulates 1,4-dioxane under the Toxic Substances Control Act and Safe Drinking Water Act, pushing U.S. manufacturers toward closed-loop recovery systems and lower-emission purification technologies. REACH restrictions in Europe limit residual 1,4-dioxane concentrations in imported personal care and detergent formulations, directly affecting export-oriented Chinese producers. China's MEE enforces wastewater discharge standards that raise compliance costs for Jiangsu and Shandong chemical clusters. Stakeholders must monitor tightening purity thresholds and regional regulatory divergence when allocating capital across production sites and customer segments.
Market Dynamics
The EPA's carcinogen classification under the Safe Drinking Water Act is fragmenting supplier tiers, forcing capital reallocation toward closed-loop purification systems and pharmaceutical-grade certification while industrial solvent volumes face residual concentration scrutiny.
Growth Catalysts
- Pharmaceutical intermediate synthesis:Specialty chemical manufacturers in the United States are expanding high-purity grade purchases for active pharmaceutical ingredient manufacturing, tightening supplier qualification protocols.
- REACH residual limits:European import restrictions on personal care formulations are redirecting Chinese export capacity toward certified pharmaceutical and laboratory reagent channels.
- Jiangsu chemical cluster expansion:Concentrated production infrastructure in China's Jiangsu province is capturing Asia-Pacific industrial solvent demand through integrated ethylene glycol feedstock access.
Market Restraints
- Ethylene glycol feedstock volatility:Acid-catalyzed dehydration routes expose producers to petrochemical price swings, compressing margin stability for non-integrated manufacturers.
- Chinese supply concentration:Jiangsu and Shandong provinces control disproportionate global export capacity, creating single-point vulnerability for international pharmaceutical formulators.
- Substitution by tetrahydrofuran:Alternative cyclic ethers are displacing 1,4-dioxane in select polar aprotic solvent applications where regulatory scrutiny is lower.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO-aligned excipient certification programs are opening import pathways for high-purity producers targeting generic drug synthesis hubs.
- Aerospace fluid specifications:Stringent moisture and particulate standards for hydraulic and de-icing formulations command technical premiums beyond commodity solvent pricing.
- Closed-loop recovery mandates:EPA enforcement of lower-emission purification technologies is creating first-mover advantage for capital-intensive recovery system adopters.
Industry Challenges
- Pharmaceutical-grade certification timelines:Excipient qualification protocols under IPEC-PQG standards extend customer onboarding cycles, straining working capital for mid-scale producers.
- Wastewater compliance retrofit costs:China's MEE discharge standards require Jiangsu cluster facilities to reconfigure effluent treatment infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1,4-Dioxane Market |
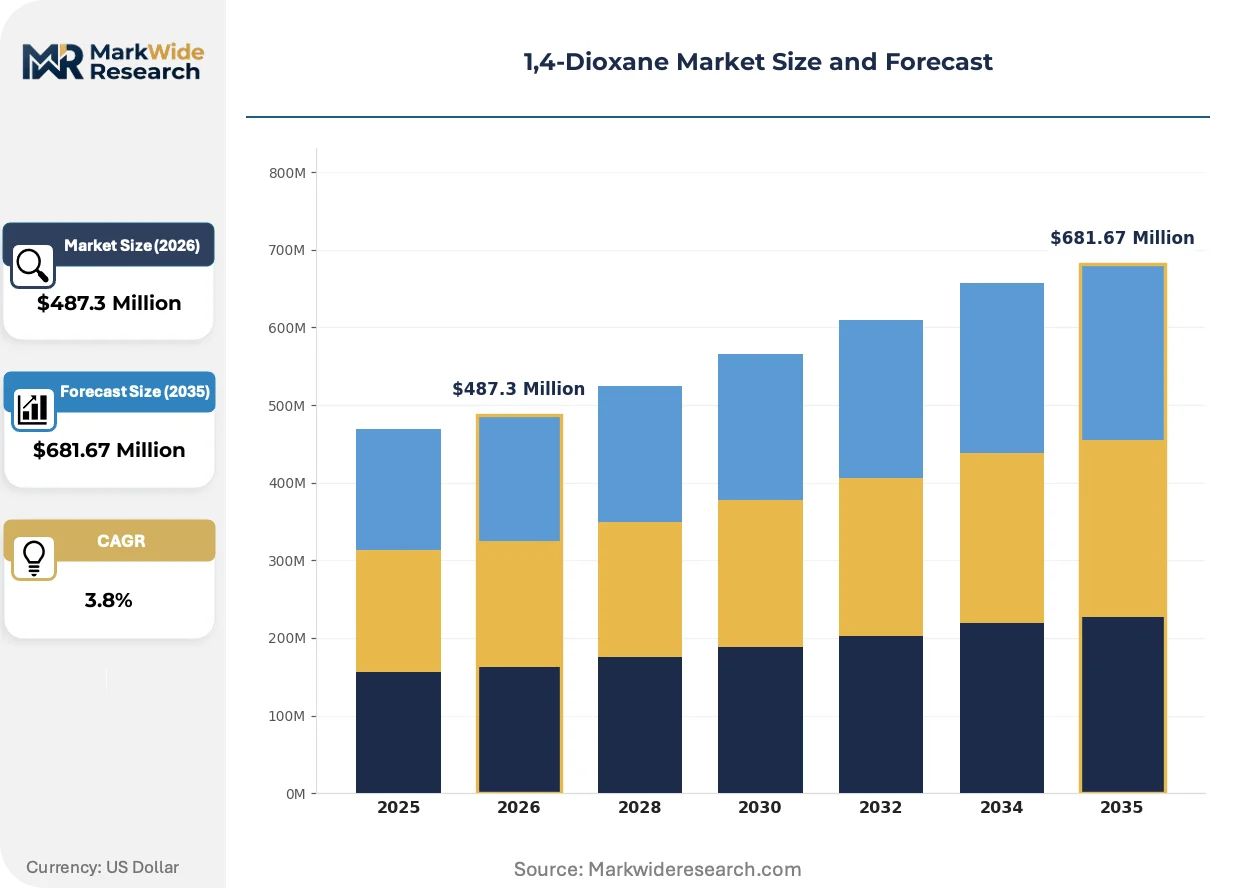
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Solvent, Intermediate, Aerospace Fluid, Chemical Reagent Application: Detergents, Paints, Adhesives, Personal Care End User: Manufacturing, Healthcare, Automotive, Construction Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Dow Chemical, BASF, TCI, HBCChem, CarboMer, Apollo Scientific, AccuStandard, Jiangsu Senxuan Pharmaceutical Co. Ltd., Jiangsu Lianrun Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1,4-Dioxane Market Evolving Landscape
Membrane-based purification technologies are displacing traditional distillation sequences, while regulatory divergence between EPA and REACH frameworks is forcing dual-track compliance architectures. Procurement patterns are compressing toward certified single-source relationships.
Membrane separation technology for residual impurity removal is consolidating market share among pharmaceutical-grade producers. BASF and Dow Chemical have adopted nanofiltration sequences for diethylene glycol hydrogenation feedstock pretreatment. This consolidation is compressing the viable supplier base for excipient-grade certification, marginalizing batch-distillation-dependent facilities.
REACH restrictions on residual 1,4-dioxane in imported detergent and personal care formulations are redirecting Chinese export flows. Export-oriented producers in Jiangsu province are diverting capacity toward pharmaceutical and laboratory reagent channels. Personal care formulation exports to Europe are declining as a demand segment, while chemical reagent certification programs are expanding.
Certification-driven procurement is concentrating buyer relationships around qualified single-source suppliers. Pharmaceutical formulators in the United States are reducing approved vendor lists to three or fewer certified producers per manufacturing site. This concentration is visible most acutely in East Asia, where Jiangsu Senxuan Pharmaceutical and analogous certified producers are capturing multi-year supply agreements.
1,4-Dioxane Market Segmentation
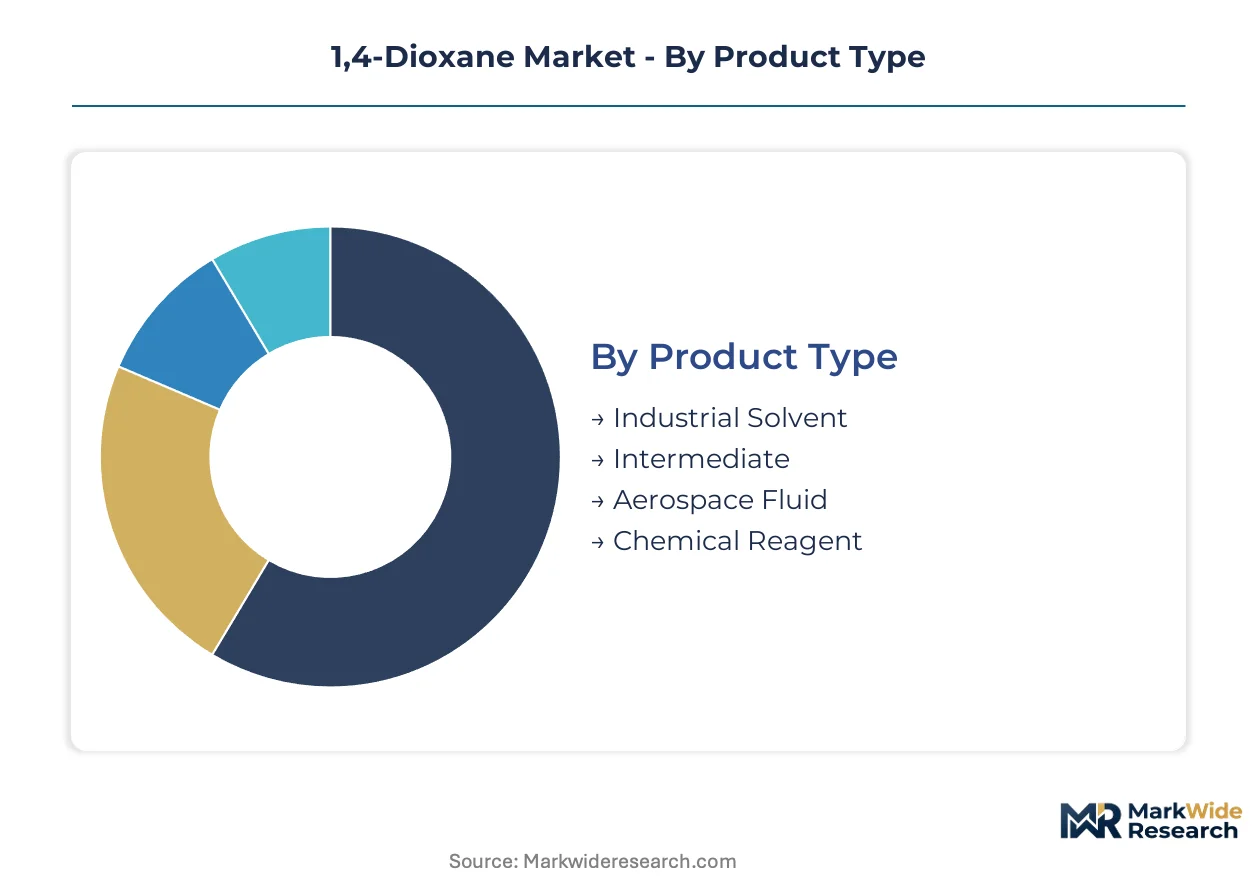
Segmentation in the 1,4-dioxane market reflects divergent purity requirements and regulatory exposure across end-use channels. Pharmaceutical and industrial buyers operate under fundamentally different qualification protocols, forcing suppliers to choose between capital-intensive certification or commodity volume strategies.
Product Type:
Cost tiers separate buyers in this category, with certification burden and margin structure determining supplier viability.
- Industrial Solvent:Standard-grade material with 99% minimum purity serves paints and adhesives manufacturing. Demand concentrates in China's Jiangsu province chemical clusters, where integrated ethylene glycol feedstock access sustains cost leadership against non-integrated competitors.
- Chemical Reagent:Laboratory-certified grades meeting ACS or pharmacopeia specifications command premium pricing through excipient qualification protocols. Procurement is concentrating around three or fewer approved vendors per pharmaceutical manufacturing site in the United States as FDA scrutiny tightens.
- Intermediate:Purified grades for active pharmaceutical ingredient synthesis bridge industrial and pharmaceutical specifications.
- Aerospace Fluid:Stringent moisture and particulate standards for hydraulic and de-icing applications create technical entry barriers.
Volume sits with Industrial Solvent; growth tilts toward Chemical Reagent.
Application:
Regulatory geography determines accessible demand pools, with REACH restrictions fragmenting export-oriented supply chains.
- Personal Care:Residual concentration limits under REACH have collapsed European import demand for this segment. Jiangsu province exporters are diverting capacity toward pharmaceutical channels as personal care formulation shipments to Europe decline.
- Paints:Polar aprotic solvent properties support high-solids coating formulations in automotive and industrial maintenance applications.
- Adhesives:Solvent-based adhesive manufacturing in Asia-Pacific consumes volume grades where EPA-style carcinogen classification has not yet propagated.
- Detergents:REACH residual limits have eliminated this as a viable export segment for Chinese producers.
Volume sits with Paints; regulatory displacement is steepest in Personal Care.
End User:
Customer type determines specification stringency, with healthcare procurement operating under excipient-grade protocols that exclude industrial-grade suppliers.
- Healthcare:Pharmaceutical manufacturers require IPEC-PQG aligned certification extending customer onboarding cycles. CDSCO-aligned programs in India are opening import pathways for high-purity producers targeting generic drug synthesis hubs.
- Manufacturing:Specialty chemical producers consume intermediate grades for active pharmaceutical ingredient synthesis in the United States.
- Construction:Paints and adhesives applications drive industrial solvent consumption with lower purity thresholds.
- Automotive:Coating formulations and sealant applications consume volume grades through distributor channels.
Volume sits with Manufacturing; margin expansion concentrates in Healthcare.
Distribution Channel:
Supply chain configuration determines certification traceability, with pharmaceutical channels requiring documented chain-of-custody that excludes fragmented retail pathways.
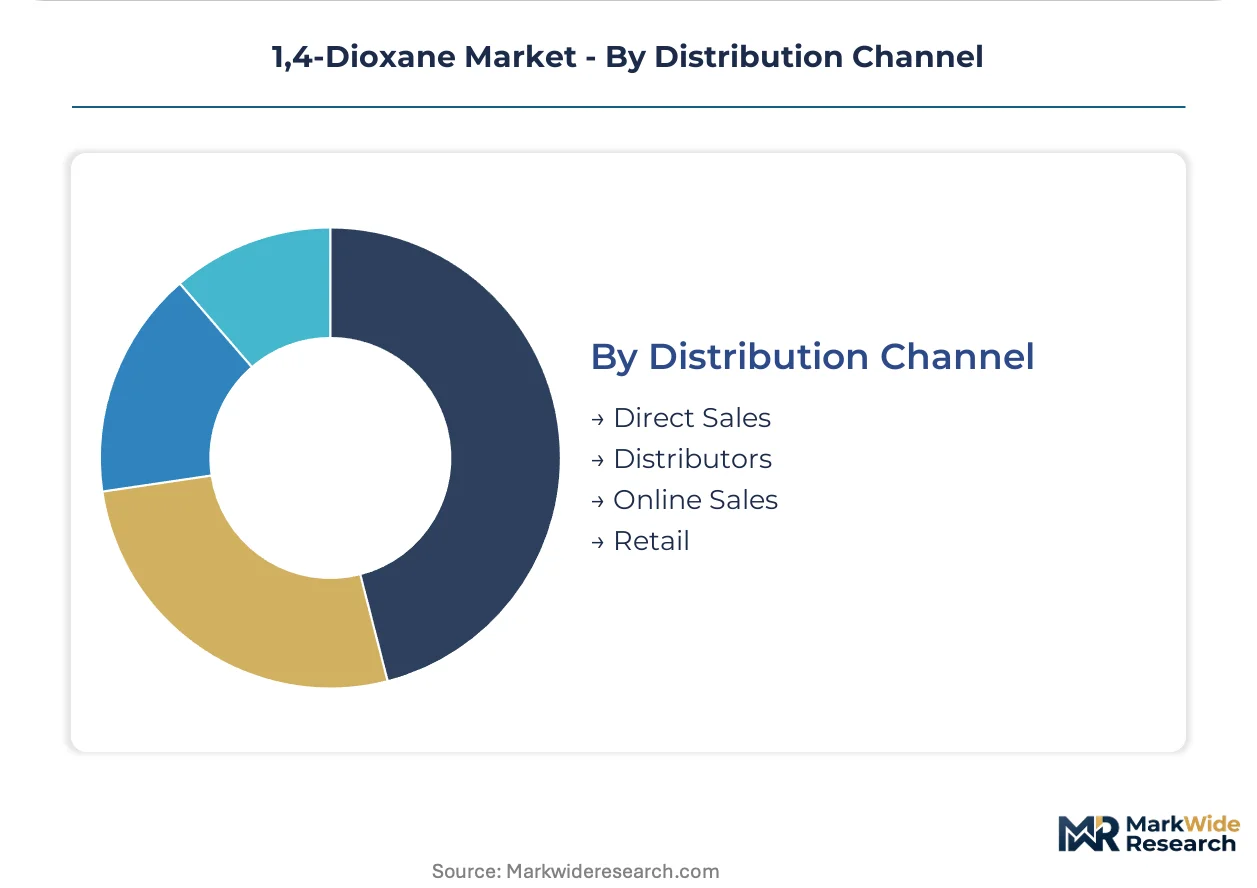
- Direct Sales:Multi-year supply agreements dominate pharmaceutical-grade procurement, with Jiangsu Senxuan Pharmaceutical and analogous certified producers capturing concentrated buyer relationships.
- Distributors:Industrial solvent volumes flow through regional chemical distributors serving paints and adhesives manufacturers.
- Online Sales:Laboratory reagent grades for research institutions move through specialized chemical supply platforms.
- Retail:Minimal penetration given hazardous material handling requirements and bulk packaging economics.
Volume sits with Distributors; contract value concentrates in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province's chemical corridor anchors global 1,4-dioxane production capacity, with concentrated ethylene glycol feedstock access and integrated purification infrastructure serving both domestic demand and export flows across pharmaceutical and industrial channels.
United States
Specialty chemical manufacturers in the United States are expanding high-purity grade purchases for pharmaceutical intermediate synthesis. The EPA's carcinogen classification under the Safe Drinking Water Act is tightening purity standards and reshaping supplier qualification protocols. Manufacturing activity concentrates along the Gulf Coast petrochemical belt, where integrated producers leverage captive ethylene glycol supply.
Germany
BASF anchors European pharmaceutical-grade production through controlled impurity profiles meeting excipient standards. ECHA's REACH restrictions on residual concentrations in imported formulations limit personal care export channels from Asian suppliers. The Ludwigshafen chemical complex maintains specialized purification capacity for laboratory reagent and aerospace fluid specifications.
China
Jiangsu province's chemical cluster dominates both production volume and export capacity for Asia-Pacific industrial solvent applications. The MEE enforces wastewater discharge standards that raise compliance costs for Jiangsu and Shandong facilities. Export-oriented producers are diverting capacity toward pharmaceutical and laboratory reagent channels as personal care shipments to Europe decline.
India
CDSCO-aligned excipient certification programs are opening import pathways for high-purity producers targeting generic drug synthesis hubs. Domestic pharmaceutical manufacturing expansion is driving demand for certified chemical reagent grades. Gujarat and Maharashtra chemical corridors are emerging as consumption centers for intermediate-grade material in active pharmaceutical ingredient production.
Japan
PMDA oversight of pharmaceutical raw materials maintains stringent impurity profiling requirements for imported 1,4-dioxane. Aerospace fluid applications with moisture and particulate specifications command technical premiums in domestic procurement. The Chubu region's specialty chemical infrastructure supports high-purity solvent demand from precision manufacturing sectors.
1,4-Dioxane Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across tiered certification requirements. The market structure concentrates around three supplier tiers: integrated petrochemical majors with captive feedstock, regional specialists with pharmaceutical-grade certification, and commodity distributors serving industrial solvent channels. Dominant competitive moves include backward integration into ethylene glycol supply and multi-year supply agreement capture with pharmaceutical formulators.
Within the integrated petrochemical tier, Dow Chemical and BASF occupy positions defined by scale and geographic reach. Jiangsu Senxuan Pharmaceutical Co. Ltd. exemplifies the certified specialist archetype, anchoring high-purity production for healthcare end users across East Asia through concentrated buyer relationships and excipient-grade qualification protocols.
| Leading Market Players |
|---|
| Dow Chemical |
| BASF |
| TCI |
| HBCChem |
| CarboMer |
| Apollo Scientific |
| AccuStandard |
| Jiangsu Senxuan Pharmaceutical Co. Ltd. |
| Jiangsu Lianrun Chemical Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Ethylene glycol spot price movements cascade through 1,4-dioxane production economics, compressing margin pools for non-integrated manufacturers while amplifying pricing power for Jiangsu province's captive-feedstock chemical clusters. The acid-catalyzed dehydration route's feedstock intensity creates three distinct pricing tiers that separate pharmaceutical-grade excipient certification from commodity industrial solvent volumes.
Pricing Analysis
Yield-based pricing anchors pharmaceutical-grade contracts, where batch consistency and impurity profile control command premiums tied to downstream API synthesis success rates. Certification grade and volume scale differentiate tiers, with IPEC-PQG aligned producers capturing multi-year agreements while spot-market industrial grades face cost compression from tetrahydrofuran substitution. Margins are tightening in standard solvent channels as REACH residual limits redirect Chinese export capacity toward certified reagent markets. Manufacturing buyers in paints and adhesives exhibit highest price sensitivity, whereas healthcare procurement prioritizes qualification stability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from U.S. pharmaceutical formulators are fragmenting supplier relationships, forcing qualification of secondary producers beyond Jiangsu and Shandong province concentrations. Ethylene glycol, diethylene glycol, and specialized hydrogenation catalysts constitute critical input dependencies. Single-source vulnerability concentrates in China's chemical corridor, where MEE wastewater compliance retrofits threaten near-term export reliability. Distribution runs through direct sales channels for pharmaceutical grades and regional chemical distributors for industrial solvent volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into ethylene glycol supply defines competitive positioning in this market, with players racing to secure captive feedstock access ahead of margin compression in non-integrated tiers.
For Market Incumbents: Extend certification coverage into CDSCO-aligned Indian pharmaceutical markets before generic drug synthesis hubs consolidate supplier relationships. BASF and Dow Chemical should deepen membrane purification technology deployment to defend excipient-grade positioning against Jiangsu Senxuan Pharmaceutical's East Asia concentration. Tetrahydrofuran substitution pressure in polar aprotic applications demands accelerated aerospace fluid specification capture where technical barriers exclude commodity entrants. For New Entrants and Emerging Players: Membrane-based purification technology offers entry leverage into pharmaceutical-grade segments where batch-distillation facilities face marginalization. India's CDSCO certification gap presents the most penetrable white space, with Gujarat and Maharashtra chemical corridors driving intermediate-grade consumption for API synthesis. Target laboratory reagent channels through specialized chemical supply platforms as an initial go-to-market pathway. For Investors and Strategic Acquirers: Distressed-cycle entries favor certified mid-scale producers in Jiangsu province facing MEE compliance retrofit costs but holding excipient-grade qualification protocols. Long-term viability hinges on regulatory divergence between EPA and REACH frameworks sustaining dual-track compliance infrastructure investment. Watch for EPA enforcement intensity around closed-loop recovery mandates as the inflection signal for first-mover advantage valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Glycol | Jiangsu province clusters secure margin stability against petrochemical price volatility through captive feedstock. |
| Membrane Purification Technology Deployment | BASF and Dow Chemical consolidate pharmaceutical-grade market share by displacing batch-distillation competitors. |
| CDSCO Certification Investment | High-purity producers unlock Indian generic drug synthesis demand through aligned excipient qualification programs. |
| Closed-loop Recovery System Adoption | EPA enforcement creates first-mover advantage for capital-intensive lower-emission purification technology adopters. |
| Long-term Supply Agreement Capture | Jiangsu Senxuan Pharmaceutical locks in concentrated buyer relationships across East Asia healthcare procurement. |
Research Methodology
SEC 10-K filings, customs and trade databases, and ACC industry reports formed the secondary backbone, cross-referenced with primary interviews involving plant managers at ethylene glycol dehydration facilities, procurement leads at downstream pharmaceutical manufacturers, and technical R&D directors overseeing membrane purification implementation. Bottom-up capacity assessments across Jiangsu and Shandong province chemical clusters were triangulated against top-down demand modeling from end-use sector consumption patterns.
Historical trendline analysis of ethylene glycol price volatility and grade-specific margin evolution informed the projection framework across the analysis window. Segmentation dimensions included purity tier, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH restriction impact on Chinese export flows and EPA carcinogen classification effects on U.S. qualification protocols. Aerospace fluid specification premiums and pharmaceutical excipient certification timelines served as industry-specific forecast modifiers.
Several conditions sit outside the modeled scope, including unannounced MEE enforcement actions, sudden tetrahydrofuran substitution acceleration, and geopolitical trade barrier imposition. Forecasts reflect documented assumptions about feedstock price stability and certification protocol harmonization. Deviation in EPA or REACH regulatory intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Industrial Closures Market
Industrial Chemicals
Dipropylene Glycol (DPG) Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Heat Transfer Fluids Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Fabric Starch Market