
 Fluorine-Based Plasma Surface Treatment Machine for Leather Market | 2026-2036
Fluorine-Based Plasma Surface Treatment Machine for Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorine-Based Plasma Surface Treatment Machine for Leather Market Analysis
Market Context
The Fluorine-Based Plasma Surface Treatment Machine for Leather Market is recalibrating as automated systems command premium pricing while portable units compete on accessibility for small tanneries. Tantec leverages its European installed base to sustain service revenue across aging equipment fleets. Henniker Plasma anchors UK demand through specialized contract treatment services that reduce capital barriers for mid-size footwear manufacturers. Nordson Corporation dominates North American automotive supplier channels with integrated plasma-coating lines.
Technical Definition and Segment Structure
Fluorine-based plasma surface treatment machines for leather generate fluorocarbon-rich plasma discharges that graft perfluorinated functional groups onto collagen fiber surfaces, achieving water contact angles exceeding 120 degrees without wet chemistry baths. Automated systems capture the dominant share of capital expenditure as upholstery companies and automotive suppliers prioritize throughput consistency over unit flexibility. Atmospheric plasma technology leads growth among footwear manufacturers seeking inline integration with existing finishing lines, while low-pressure plasma retains margin concentration in high-end stain resistance applications for luxury leather goods.
Regulatory Frame and Outlook
REACH restrictions on perfluorinated substances and EPA oversight of fluorinated gas emissions shape equipment specifications and process validation requirements across European and North American installations. China's MEE enforces dual carbon goals that accelerate plasma adoption as a water-saving alternative to chrome tanning and solvent-based coating in Zhejiang province tanneries. Stakeholders must monitor evolving fluoropolymer substance restrictions that could redefine permissible chemistries in plasma feedstock gases.
Market Dynamics
REACH restrictions on perfluorinated substances and China's dual carbon mandates are forcing tanneries across Europe and East Asia to abandon solvent-based finishing, creating urgent demand for dry plasma surface modification systems that graft hydrophobic functional groups without wet chemistry baths.
Growth Catalysts
- Automotive Upholstery Specifications:Tier-1 suppliers to German and US vehicle manufacturers now mandate fluorine plasma finishing for seat leather to achieve stain resistance ratings exceeding 120-degree water contact angles.
- REACH Chemical Phase-Outs:ECHA restrictions on long-chain perfluorinated substances eliminate competing wet-chemical alternatives, channeling leather finishers toward plasma-based dry processes.
- Atmospheric Plasma Maturation:Inline atmospheric systems now integrate with existing conveyor finishing lines, allowing footwear manufacturers in China's Guangdong province to retrofit without production halts.
Market Restraints
- Feedstock Gas Cost Volatility:Tetrafluoromethane and hexafluoroethane pricing fluctuates with semiconductor industry demand cycles, compressing plasma operator margins during supply crunches.
- Equipment Supply Concentration:Precision vacuum chamber fabrication concentrates among German and Japanese metalworking specialists, creating 14-18 month lead times for low-pressure system delivery.
- Technical Throughput Limits:Batch low-pressure plasma processes max out at 2-3 square meters per cycle, constraining adoption by high-volume automotive cut-and-sew operations.
Strategic Opportunities
- India Leather Export Corridors:Tamil Nadu and Uttar Pradesh tanneries serving Italian luxury goods houses remain underpenetrated by plasma finishing, presenting first-mover equipment placement potential.
- Regulatory Tailwind from China's MEE:Provincial carbon intensity targets in Zhejiang explicitly subsidize water-free surface treatment, accelerating payback calculations for plasma capital expenditure.
- Convergence with Digital Print Systems:Combined plasma pretreatment and inkjet finishing lines enable on-demand color customization for sneaker manufacturers, collapsing traditional batch-dyeing economics.
Industry Challenges
- Plasma Process Engineering Talent Scarcity:Fewer than 200 specialists globally possess combined expertise in fluorocarbon discharge physics and collagen substrate chemistry, inflating commissioning costs.
- Legacy Chrome Tanning Integration:Plasma systems must interface with existing chromium-saturated leather stocks without triggering hexavalent chromium surface reactions, complicating process validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorine-Based Plasma Surface Treatment Machine for Leather Market |
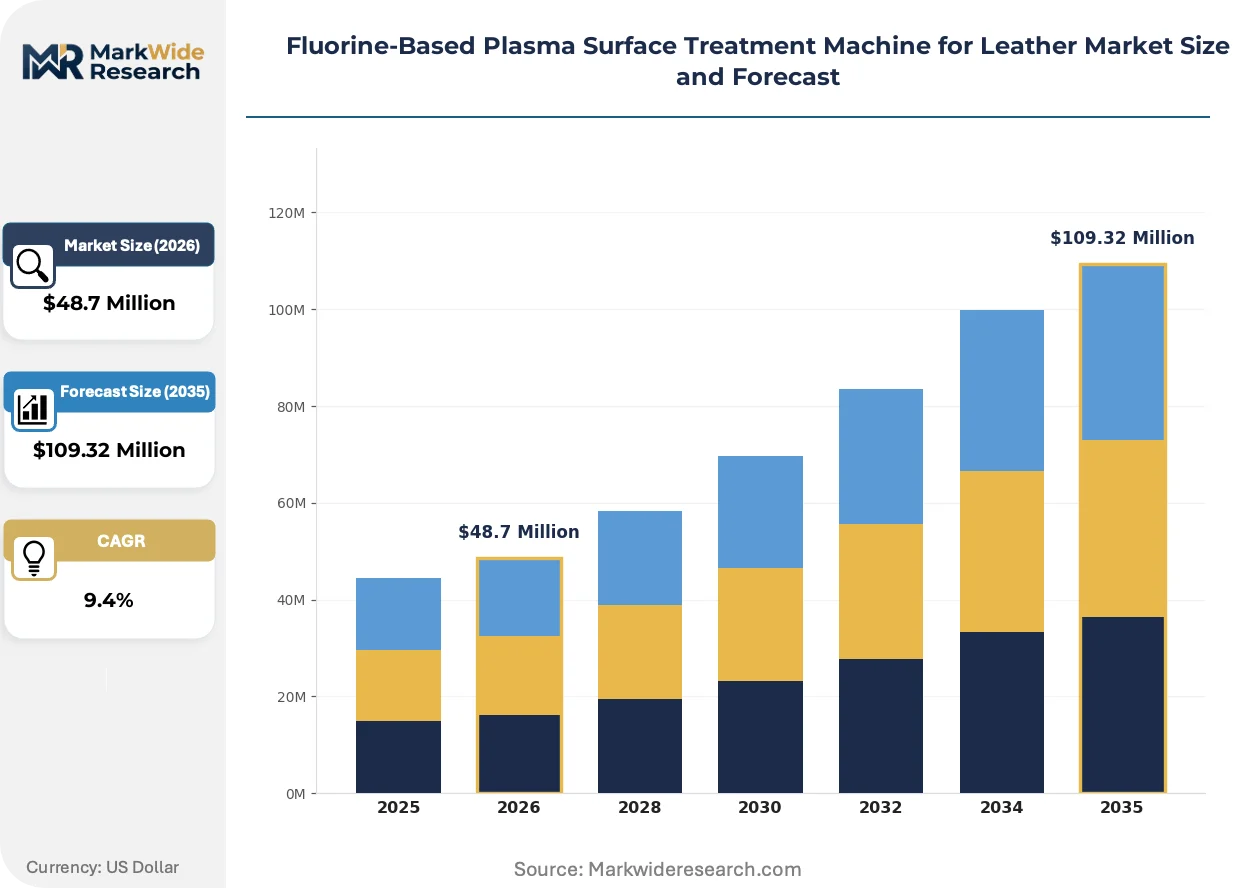
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $109.32 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Machines, Large Machines, Portable Units, Automated Systems Application: Leather Finishing, Stain Resistance, Surface Modification, Coating Enhancement Technology: Direct Plasma, Atmospheric Plasma, Low-Pressure Plasma, Hi-Performance Plasma End User: Footwear Manufacturers, Textile Producers, Automotive Suppliers, Upholstery Companies |
| Companies Covered | Tantec, Henniker Plasma, Nordson Corporation, PVA TePla America, Advanced Plasma Solutions, Plasmatreat, Plasma Etch, Surfx Technologies, Diener Electronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorine-Based Plasma Surface Treatment Machine for Leather Market Emerging Trajectories
Equipment architecture is bifurcating between atmospheric inline systems for footwear throughput and vacuum batch chambers for luxury goods precision, while regulatory chemistry restrictions continuously redefine permissible feedstock gases.
Atmospheric plasma technology is overtaking low-pressure systems in footwear manufacturing. Roll-to-roll atmospheric treatment heads graft fluorinated groups onto split leather at 15 meters per minute, matching conveyor speeds in Portuguese and Brazilian sneaker factories. This speed compression is overtaking vacuum batch economics for all but the highest-end full-grain applications.
Europe's F-Gas Regulation is tightening allowable global warming potential thresholds for industrial fluorinated gases. Plasma equipment manufacturers now qualify sulfur hexafluoride alternatives and perfluoropropane blends to maintain process efficacy while meeting 2027 phase-down targets. Automotive leather finishers in Italy and Germany face the steepest compliance recalibration.
Service-based equipment access is displacing outright purchase among mid-tier tanneries. Contract surface treatment providers in the UK and Netherlands now operate mobile plasma units, charging per-square-meter fees that eliminate capital barriers for footwear brands with seasonal volume spikes. This model concentrates most visibly among Dutch contract finishers serving fragmented Benelux leather goods startups.
Fluorine-Based Plasma Surface Treatment Machine for Leather Market Segmentation
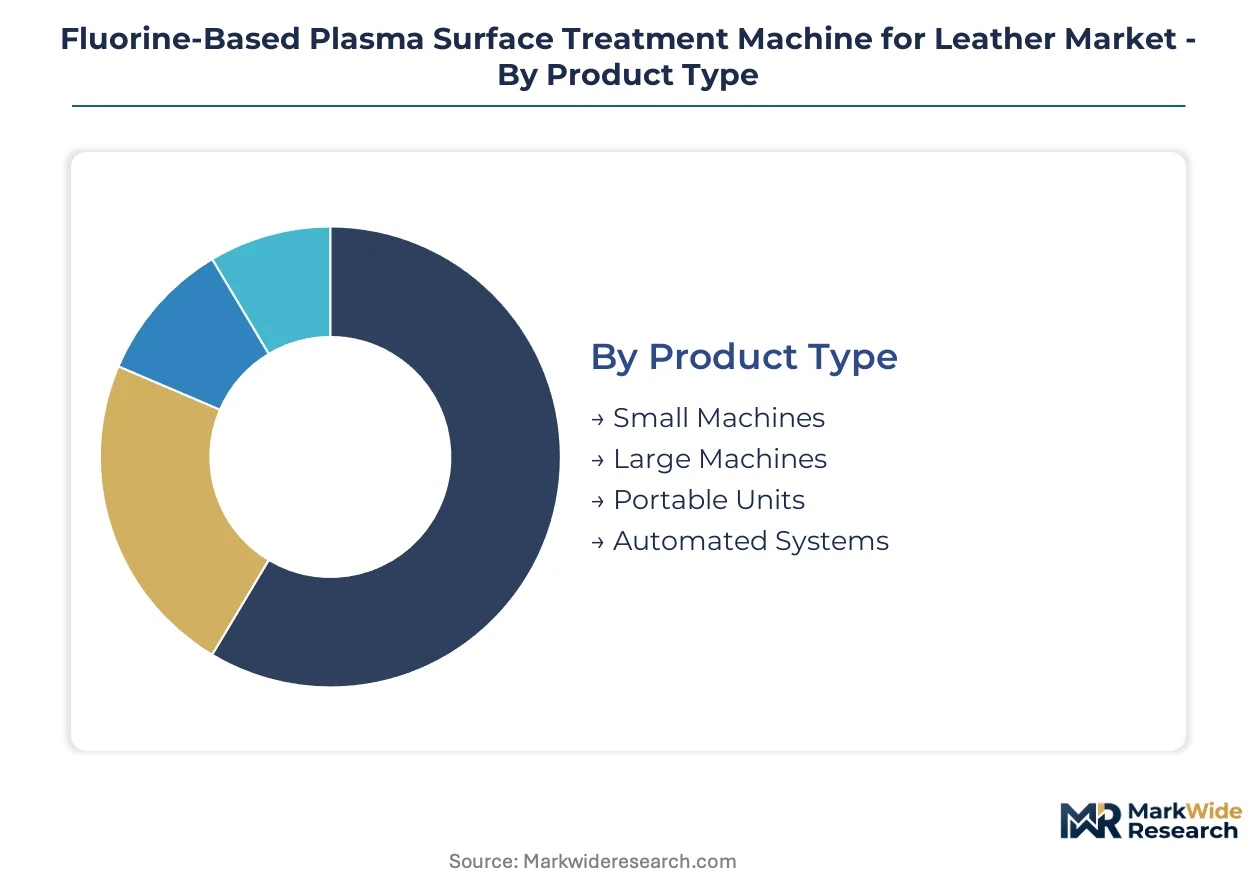
Segmentation in fluorine plasma equipment tracks divergent capital cycles across tannery scales, from automated automotive lines to portable units serving seasonal footwear batches. Understanding these divisions exposes where upgrade urgency concentrates and where replacement demand lags.
Product Type:
Replacement cycles vary sharply by equipment scale, with large automated systems commanding decade-long depreciation schedules while portable units turn over every 3-5 years.
- Automated Systems:Continuous inline architecture integrates fluorocarbon discharge heads with conveyor finishing lines at 15+ meters per minute throughput. Tier-1 automotive suppliers in Germany and the US specify these for seat leather programs requiring 120-degree water contact angles across million-unit annual volumes.
- Large Machines:Batch vacuum chamber systems with 2-3 square meter processing capacity per cycle dominate luxury goods applications where stain resistance precision outweighs speed. Italian tanneries serving French luxury houses maintain these for full-grain calf leather finishing.
- Portable Units:Compact atmospheric plasma wands enable mobile contract treatment services.
- Small Machines:Entry-level benchtop systems serve prototype development and quality control labs.
Automated Systems sit at the top of the volume ranking, with Portable Units climbing the fastest as contract service models expand.
Application:
Application demand splits between regulatory-mandated replacements and performance-specification upgrades, with coating enhancement emerging from digital print convergence.
- Stain Resistance:Perfluorinated functional group grafting achieves 120+ degree water contact angles without wet chemistry baths. REACH restrictions on long-chain perfluorinated substances have eliminated competing fluorocarbon spray alternatives, channeling all premium automotive and luxury goods volume into plasma-based dry processes.
- Leather Finishing:Final surface preparation before color coating or embossing operations. Guangdong province footwear clusters deploy inline atmospheric systems to retrofit existing conveyor lines without production halts.
- Surface Modification:Controlled oxidation and crosslinking of collagen fiber surfaces.
- Coating Enhancement:Plasma pretreatment before inkjet or spray coating application.
Stain Resistance commands the dominant revenue share, while Coating Enhancement gains share fastest from sneaker customization trends.
Technology:
Technology selection tracks the tension between throughput economics and process control precision, with atmospheric systems displacing vacuum batch methods in mid-market applications.
- Atmospheric Plasma:Open-air discharge systems operating at ambient pressure integrate directly with existing production lines. Roll-to-roll treatment heads process split leather at conveyor speeds, matching Portuguese and Brazilian sneaker factory throughputs while eliminating vacuum pump capital and cycle time.
- Low-Pressure Plasma:Vacuum chamber systems below 100 mbar pressure enable precise control of fluorocarbon radical density and penetration depth. High-end Italian and German automotive leather finishers retain these for luxury-grade full-grain applications where batch consistency outweighs unit economics.
- Direct Plasma:Electrode configurations generating discharge without intermediate gas barriers.
- Hi-Performance Plasma:Pulsed power delivery systems with enhanced radical generation efficiency.
Atmospheric Plasma leads installed base volume, with Low-Pressure Plasma holding the steepest margin concentration.
End User:
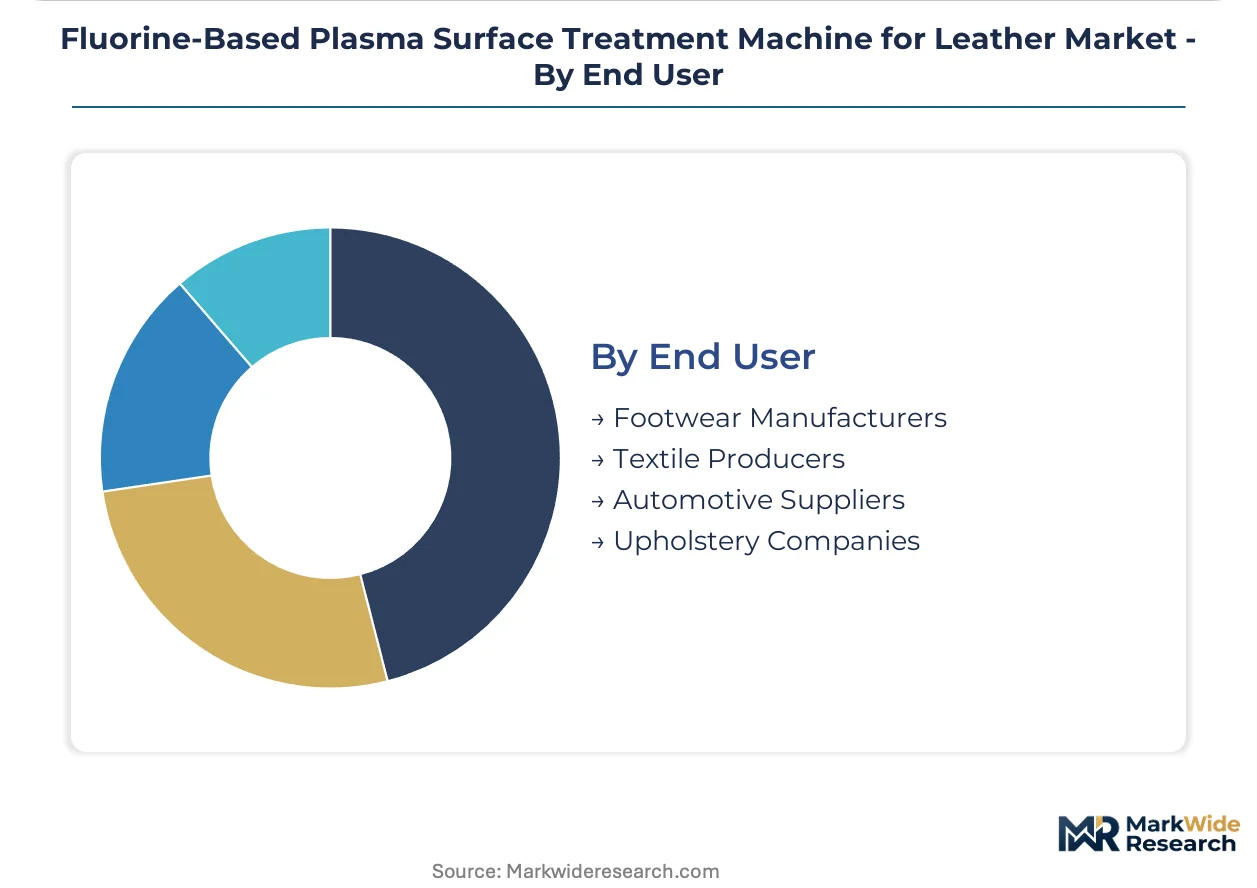
End user structure reflects divergent procurement authority, with automotive suppliers mandating specifications that cascade through Tier-2 and Tier-3 tanneries.
- Automotive Suppliers:Tier-1 seating manufacturers specify fluorine plasma finishing in supplier quality agreements. German and US vehicle manufacturers now mandate 120-degree water contact angle ratings for all seat leather, forcing capital deployment across cut-and-sew operations.
- Footwear Manufacturers:Seasonal volume spikes and style fragmentation favor flexible equipment access over ownership. Dutch contract finishers now operate mobile plasma units charging per-square-meter fees, eliminating capital barriers for Benelux leather goods startups.
- Upholstery Companies:Residential and commercial furniture leather finishers.
- Textile Producers:Synthetic leather and coated fabric manufacturers.
Automotive Suppliers anchor capital expenditure volume, with Footwear Manufacturers expanding most quickly through service-based access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma process engineering talent concentrates in German industrial regions, Italian tannery districts, and China's eastern manufacturing belts, anchoring equipment deployment patterns across three continents.
China
Zhejiang and Guangdong province leather clusters drive atmospheric plasma adoption for inline footwear finishing. MEE dual carbon targets subsidize water-free surface treatment, compressing payback periods for automated systems. Wenzhou tanneries retrofit existing conveyor lines with roll-to-roll plasma heads processing split leather at 15 meters per minute.
Germany
Tier-1 automotive seating suppliers mandate fluorine plasma finishing for 120-degree water contact angle specifications. ECHA REACH restrictions on long-chain perfluorinated substances eliminate wet-chemical alternatives, channeling finishers toward dry plasma processes. Bavarian equipment fabricators supply precision vacuum chambers with 14-18 month lead times.
Italy
Luxury goods tanneries in Tuscany and Veneto retain low-pressure batch systems for full-grain calf leather stain resistance. F-Gas Regulation tightening global warming potential thresholds forces feedstock gas recalibration by 2027. Arzignano leather cluster operators qualify sulfur hexafluoride alternatives to maintain process efficacy.
United States
EPA oversight of fluorinated gas emissions shapes equipment specifications across Michigan and Ohio automotive cut-and-sew operations. Nordson Corporation dominates supplier channels with integrated plasma-coating lines. Detroit-area Tier-1 seating manufacturers deploy continuous inline architecture for million-unit annual volumes.
India
Tamil Nadu and Uttar Pradesh tanneries serving Italian luxury goods houses remain underpenetrated by plasma finishing technology. BIS standards for leather chemical safety create regulatory runway for dry process adoption. Kanpur leather cluster operators evaluate contract treatment models to bypass capital barriers.
Fluorine-Based Plasma Surface Treatment Machine for Leather Market Vendor Landscape
Capital-heavy chamber fabricators compete with asset-light plasma system designers for positioning across automotive and footwear end markets. The vendor base splits between European precision metalworking specialists and North American integrated coating line suppliers. Three archetypes dominate: vacuum chamber specialists, atmospheric plasma integrators, and contract treatment service operators. Strategic moves concentrate on geographic expansion into Indian tannery corridors and technology licensing partnerships with Chinese conveyor manufacturers.
Among European plasma equipment fabricators, Tantec leverages its Danish installed base to sustain service revenue across aging equipment fleets, while Henniker Plasma anchors UK demand through specialized contract treatment services. Nordson Corporation occupies a position among North American integrated system suppliers, dominating automotive supplier channels with coating line integration capabilities. These three exemplify the geographic specialization and service-model differentiation defining competitive positioning.
| Leading Market Players |
|---|
| Tantec |
| Henniker Plasma |
| Nordson Corporation |
| PVA TePla America |
| Advanced Plasma Solutions |
| Plasmatreat |
| Plasma Etch |
| Surfx Technologies |
| Diener Electronic |
| Others |
Supply Flow & Price Mechanics
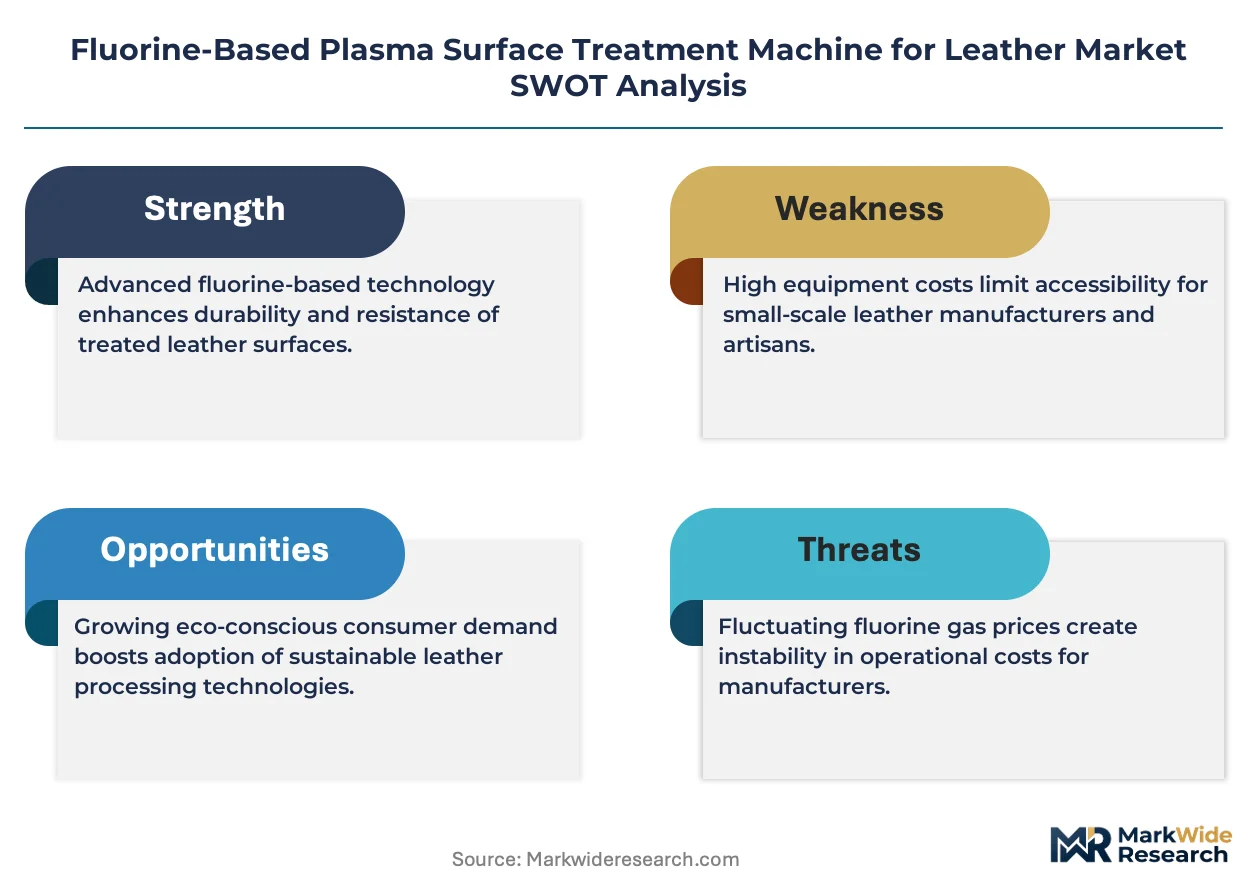
Tetrafluoromethane and hexafluoroethane feedstock costs cascade from semiconductor industry demand cycles through plasma equipment operating economics, compressing margins for tanneries running batch vacuum systems while automated inline operators absorb volatility through volume scale.
Pricing Analysis
Bundled equipment-service contracts dominate Tier-1 automotive supplier relationships, while unbundled capital sales concentrate among mid-tier footwear manufacturers. Three-tier pricing structure across premium automated systems, standard batch chambers, and economy portable units tracks throughput specifications and after-sales support intensity. Pricing pressure stems from fluorinated gas cost volatility during semiconductor supply crunches. Small tanneries and seasonal footwear producers exhibit highest price sensitivity, whereas German and US automotive seating manufacturers prioritize specification compliance over unit economics.
Supply Chain Analysis
Precision vacuum chamber fabrication rests on German and Japanese metalworking specialists, with atmospheric plasma components drawing from Chinese conveyor integration partners. Critical inputs include fluorinated feedstock gases, stainless steel vacuum vessels, and pulsed power electronics. Single-source vulnerability concentrates in specialty gas purification equipment. Distribution runs through direct OEM sales for automotive accounts and regional distributor networks serving fragmented footwear clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH restrictions on long-chain perfluorinated substances eliminate wet-chemical alternatives and force capital deployment into dry plasma finishing systems.
For Market Incumbents: Lock in automotive supplier specifications through integrated coating line partnerships that embed switching costs. Defend against atmospheric plasma commoditization by certifying proprietary feedstock gas blends under tightening F-Gas Regulation thresholds. Prioritize backward integration into vacuum chamber fabrication to compress 14-18 month lead times and capture margin concentration in luxury goods applications. For New Entrants and Emerging Players: REACH restrictions in Europe open a window for contract surface treatment services that eliminate capital barriers for mid-tier tanneries. Target Tamil Nadu and Uttar Pradesh leather clusters serving Italian luxury goods houses where plasma penetration remains minimal. Lead with mobile atmospheric plasma units charging per-square-meter fees to capture seasonal footwear volume spikes without fixed asset deployment. For Investors and Strategic Acquirers: Consolidation pressure builds where plasma process engineering talent scarcity inflates commissioning costs and extends customer acquisition timelines. Five-to-ten year viability favors equipment manufacturers with installed base service revenue and geographic diversification across European automotive corridors and Chinese footwear clusters. Monitor ECHA feedstock gas restriction announcements as inflection indicators for chemistry pivot requirements and equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Gas Chemistry Pivot | Qualification of sulfur hexafluoride alternatives maintains process efficacy under F-Gas Regulation phase-down timelines. |
| Contract Treatment Service Expansion | Mobile plasma units charging per-square-meter fees eliminate capital barriers for Benelux leather goods startups. |
| Atmospheric Plasma Retrofit Integration | Roll-to-roll treatment heads graft fluorinated groups onto split leather at 15 meters per minute matching conveyor speeds. |
| Indian Market First-Mover Placement | Tamil Nadu tanneries serving Italian luxury houses remain underpenetrated by plasma finishing technology. |
| Digital Print System Convergence | Combined plasma pretreatment and inkjet finishing lines enable on-demand sneaker customization collapsing batch-dyeing economics. |
Methodological Framework
Coverage spans European automotive leather corridors, Chinese footwear manufacturing belts, and Indian export tannery clusters, with primary inputs from each. The analysis combines interviews with plasma equipment engineering directors, tannery operations managers, automotive Tier-1 procurement leads, and fluorinated gas supply specialists with secondary validation from ECHA regulatory filings, customs trade data on plasma equipment imports, SEC disclosures from integrated coating line suppliers, and MEE provincial carbon intensity target documents. Bottom-up equipment shipment tallies and top-down tannery capital expenditure surveys were triangulated to anchor market sizing.
Granularity-level modeling tracked automated systems, large batch machines, portable units, and small benchtop systems separately across stain resistance, leather finishing, surface modification, and coating enhancement applications. Atmospheric and low-pressure plasma technologies were modeled with distinct feedstock gas cost assumptions and throughput parameters. CAGRs were derived from segment-level growth trajectory analysis across the projection horizon, incorporating automotive upholstery specification mandates, REACH chemical phase-out timelines, and Chinese dual carbon subsidy eligibility criteria as industry-specific forecast inputs.
Revisions become necessary when fluoropolymer substance restrictions expand beyond current feedstock gas formulations, semiconductor industry demand spikes disrupt fluorinated gas pricing stability, or Indian BIS standards accelerate dry process adoption timelines. A small set of named triggers warrants ongoing watch: ECHA restriction announcements, MEE provincial subsidy adjustments, and Tier-1 automotive supplier specification changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
India Acetic Acid Market