
 Spain Anti Caking Market | 2026-2036
Spain Anti Caking Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Anti Caking Market Analytics
Buyer concentration among Spain's fertilizer cooperatives is recalibrating procurement leverage across the anti-caking supply base. Evonik Industries AG leverages its silica technology leadership to sustain premium positioning in powder flow applications. BASF SE anchors its presence through specialized calcium silicate formulations tailored to Iberian humidity conditions. Cargill Incorporated competes by extending its food-grade mineral portfolio into seasonings and coatings channels.
Anti-caking agents are hygroscopic or hydrophobic substances, typically composed of silicates, carbonates, or bicarbonates, applied at concentrations between 0.5% and 5.0% to maintain free-flowing properties in powdered and granulated materials. Their primary purpose is to prevent crystalline bridge formation during storage and transport in moisture-variable climates. Minerals dominate product type revenue due to established supply chains and lower unit costs, while calcium silicate captures expanding margin pools in pharmaceutical-grade specifications. Among end users, the food industry leads absolute volume, though animal feed applications are registering faster growth as compound feed mills modernize handling infrastructure.
Spain's national food safety agency enforces EU Regulation 231/2012 on food additives, while REACH compliance through ECHA governs chemical-grade anti-caking substances placed on the Spanish market. These frameworks shape formulation choices, testing protocols, and import documentation requirements for both domestic producers and foreign suppliers. Stakeholders must monitor evolving EU Green Deal criteria for sustainable mineral sourcing and anticipate how tightened purity standards will filter through veterinary and pharmaceutical applications.
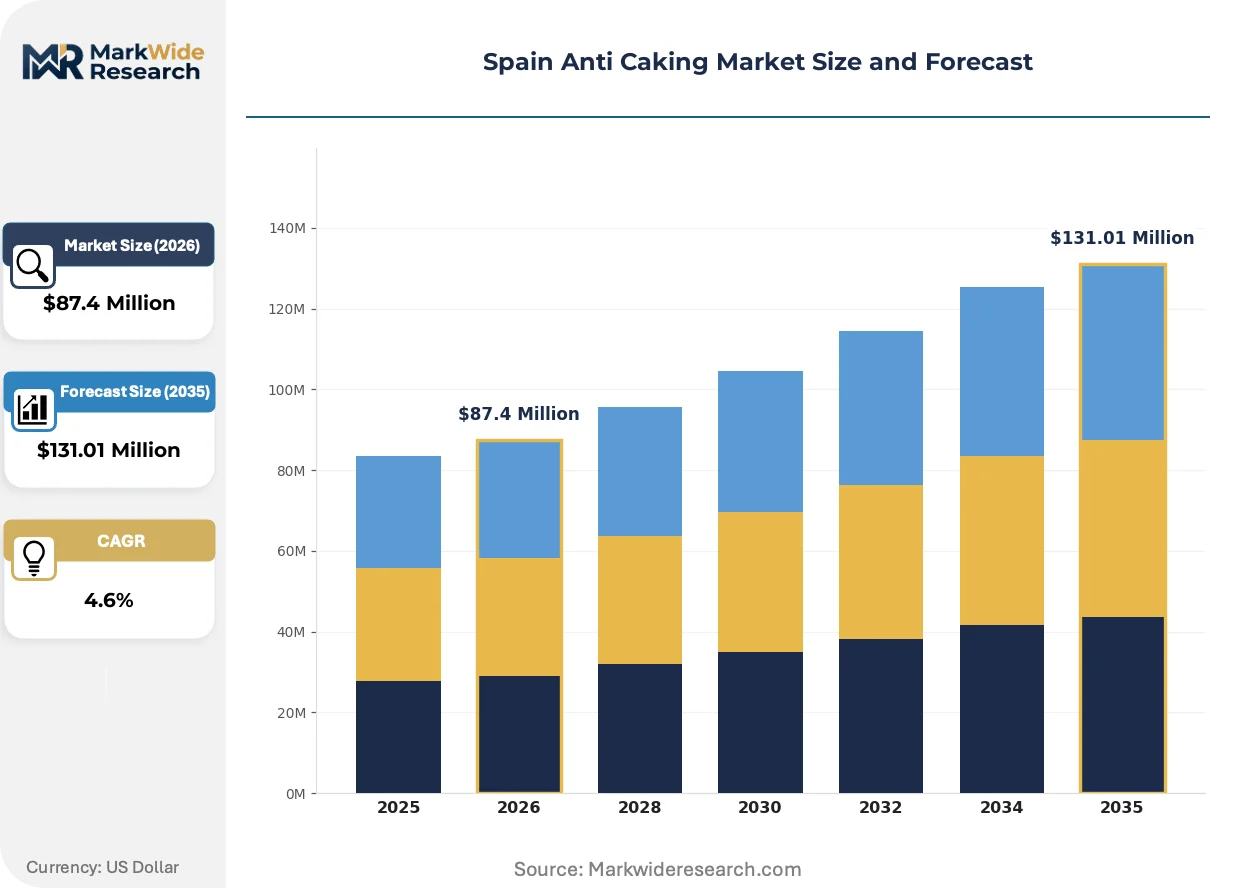
Market Dynamics
Fertilizer cooperatives across Andalusia and Catalonia are consolidating procurement volumes, compressing supplier margins while amplifying technical specification requirements for humidity-resistant formulations.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is redirecting investment toward mineral-based anti-caking alternatives that bypass synthetic coating restrictions.
- Compound feed modernization:Animal feed mills in Aragon and Castile-La Mancha are retrofitting handling infrastructure, generating fresh demand for flow-control agents in protein concentrate storage.
- REACH compliance through ECHA:Registration requirements for chemical-grade substances are filtering out non-compliant imports, creating protected market space for verified domestic and EU-registered suppliers.
Market Restraints
- Silica feedstock volatility:Precipitated silica prices fluctuate with energy costs at European production sites, squeezing margin stability for coating formulators.
- Single-source dependency:High-purity calcium silicate for pharmaceutical-grade applications concentrates among a limited set of EU-registered producers, creating supply vulnerability.
- Technical ceiling in biodegradable options:Starch-based alternatives fail to match mineral performance in high-humidity fertilizer storage above 75% relative humidity.
Strategic Opportunities
- Basque Country food manufacturing corridor:Underpenetrated seasoning and convenience food producers present expansion targets for tailored anti-caking mineral blends.
- EU Green Deal sustainable sourcing criteria:Early alignment with emerging traceability mandates for mined minerals creates preferential positioning in public procurement channels.
- Precision agriculture integration:Coating technologies that enable controlled nutrient release are converging with anti-caking functions, opening premium product tiers.
Industry Challenges
- Formulation chemistry expertise:Shortages of specialists combining mineralogy with food safety compliance slow product development cycles at mid-tier suppliers.
- Dual-use certification complexity:Substances crossing food-grade and industrial-grade applications face divergent testing protocols under EFSA and ECHA, extending approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Anti Caking Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $131.01 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minerals, Sodium Bicarbonate, Calcium Silicate, Magnesium Carbonate End User: Food Industry, Animal Feed, Pharmaceuticals, Chemicals Application: Powdered Products, Granulated Products, Seasonings, Coatings Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Evonik Industries AG, Huber Engineered Materials, Cargill Incorporated, BASF SE, Solvay SA, PPG Industries, Kao Corporation, Merck KGaA, PQ Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Anti Caking Market Evolving Landscape
Mineral coating technologies are fragmenting into performance-tiered offerings as humidity-specific formulations displace generic products, while regulatory pressure accelerates substitution away from synthetic additives.
Surface-modified precipitated silica is overtaking standard uncoated grades in high-value fertilizer applications. Manufacturers in Valencia's chemical cluster are adopting these engineered particles for their superior moisture barrier properties under Iberian coastal humidity. The technology is overtaking conventional calcium carbonate in premium compound fertilizer lines, compressing commodity-grade mineral margins while expanding addressable value pools.
REACH authorization timelines for synthetic anti-caking substances are lengthening as ECHA scrutinizes persistence and bioaccumulation profiles. Industrial chemical suppliers face reformulation mandates or withdrawal decisions for legacy coating chemistries. Fertilizer processors in Extremadura are accelerating mineral alternative qualification to preempt supply disruption.
Buyers are bundling anti-caking procurement with broader flow-aid and dust-suppression contracts, unbundling historical single-product relationships. Distributors serving Castile and León's grain handling sector are consolidating supplier panels and demanding volume-tiered pricing transparency. This pattern concentrates most visibly among agricultural cooperatives with centralized purchasing functions.
Spain Anti Caking Market Segmentation
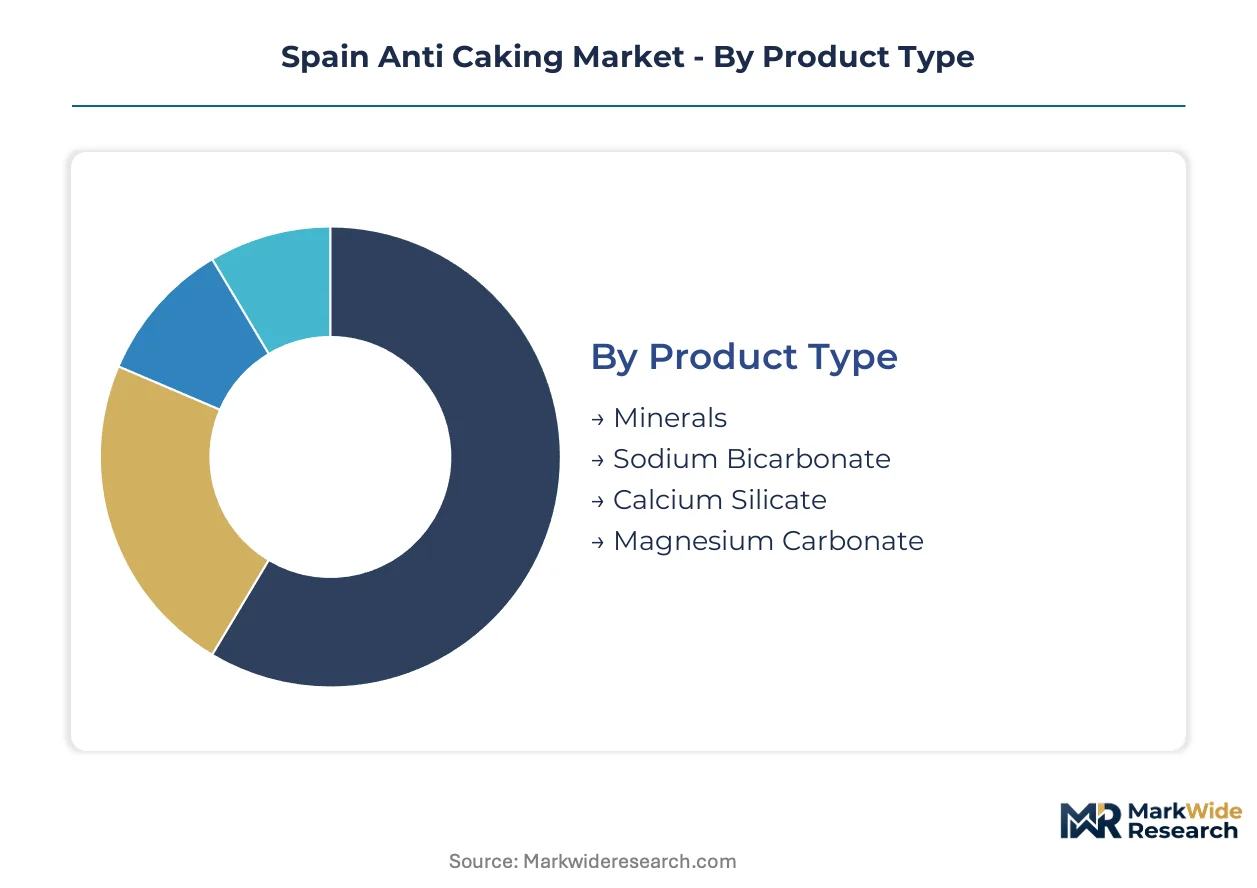
Anti-caking procurement in Spain fragments across performance tiers, regulatory grades, and moisture-resistance specifications. Buyers in Andalusia's fertilizer corridor and Catalonia's food belt apply divergent selection criteria, reshaping supplier portfolio priorities.
Product Type:
Cost tier determines specification depth, with mineral-based formulations dominating volume procurement and engineered silicates capturing premium margin pools.
- Minerals:Silicates, carbonates, and bicarbonates constitute the foundational tier, applied at 0.5-5.0% concentration to prevent crystalline bridge formation. Andalusian fertilizer cooperatives source these in bulk for phosphate and urea storage, prioritizing unit economics over performance differentiation in ambient humidity below 65%.
- Calcium Silicate:Engineered particles with superior moisture barrier properties command premium positioning in pharmaceutical-grade specifications. Valencia's chemical cluster is adopting surface-modified grades for high-value fertilizer lines, displacing commodity minerals in applications exceeding 75% relative humidity.
- Sodium Bicarbonate:Food-grade specifications serve seasoning manufacturers in the Basque Country corridor, where EU Regulation 231/2012 compliance is mandatory.
- Magnesium Carbonate:Niche applications in sports nutrition and specialty food processing, with limited penetration in Iberian industrial markets.
Minerals lead on scale; calcium silicate leads on momentum.
End User:
Application maturity separates established food safety compliance from emerging infrastructure modernization cycles.
- Food Industry:Seasoning, convenience food, and bakery segments drive absolute volume demand. Catalonia's manufacturing belt requires EU F-Gas Regulation-aligned mineral alternatives as synthetic coatings face phasedown.
- Animal Feed:Compound feed mills in Aragon and Castile-La Mancha are retrofitting handling infrastructure, generating fresh demand for flow-control agents in protein concentrate storage.
- Pharmaceuticals:High-purity calcium silicate for tablet and powder formulations concentrates among ECHA-registered suppliers, creating protected procurement channels.
- Chemicals:Industrial-grade applications in Extremadura's fertilizer processing corridor favor REACH-compliant mineral coatings over legacy synthetic chemistries.
Food industry leads on scale; animal feed leads on momentum.
Application:
Physical form dictates coating mechanism and humidity-resistance specification.
- Powdered Products:Fine particle systems require hydrophobic surface treatments to maintain dispersibility. Pharmaceutical and food-grade specifications dominate value capture.
- Granulated Products:Fertilizer processors in Andalusia apply anti-caking coatings to urea and NPK blends, with humidity-specific formulations displacing generic products.
- Seasonings:Salt and spice blends in Catalonia and the Basque Country require food-additive compliance under EFSA frameworks.
- Coatings:Convergence with controlled-release nutrient technologies opens premium tiers in precision agriculture segments.
Granulated products lead on scale; coatings lead on momentum.
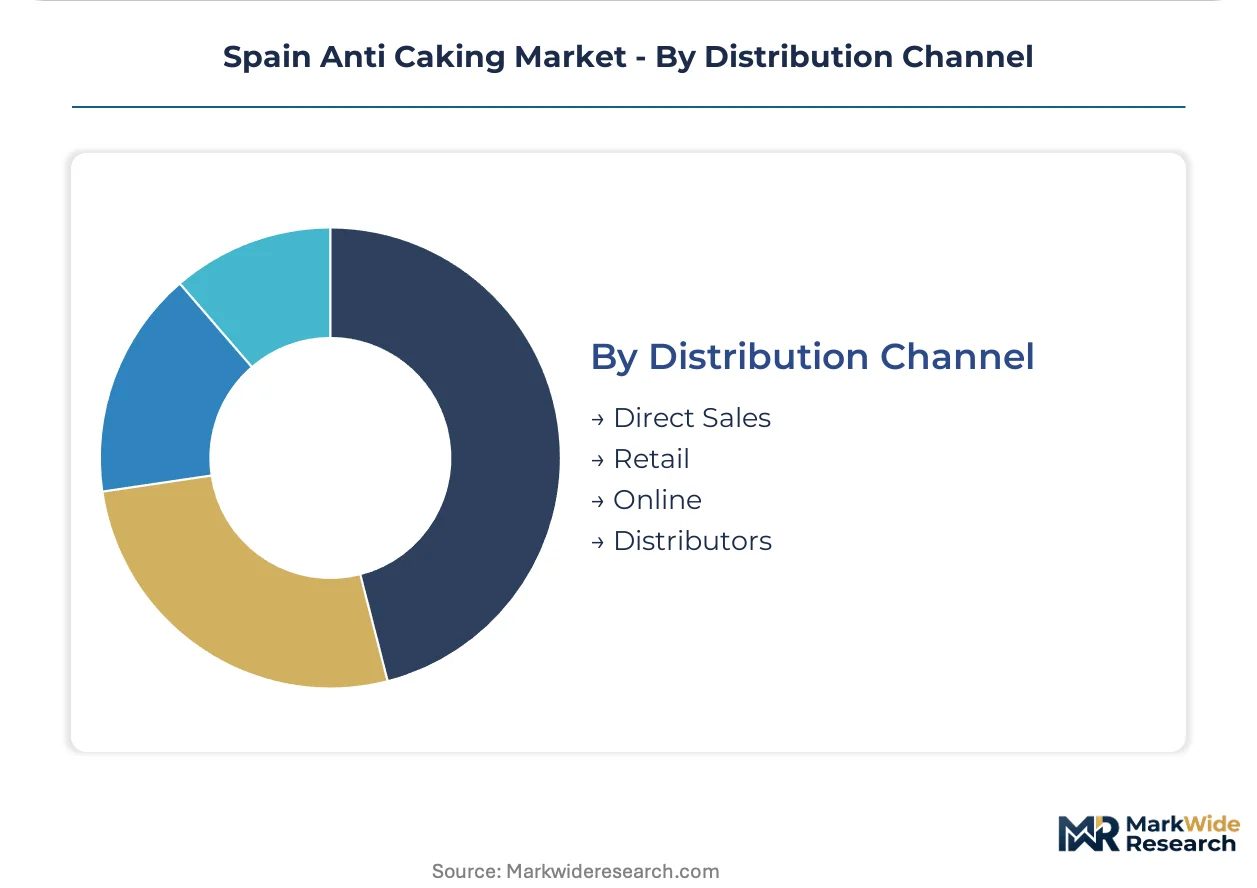
Distribution Channel:
Customer scale and technical service requirements determine channel selection.
- Direct Sales:Large fertilizer cooperatives in Andalusia negotiate centralized procurement with volume-tiered pricing transparency.
- Distributors:Serve Castile and León's grain handling sector with bundled flow-aid and dust-suppression contracts.
- Retail:Small-scale food processors and specialty chemical buyers access standard-grade minerals through regional chemical suppliers.
- Online:Emerging channel for technical documentation and sample procurement, with limited transaction scale in industrial-grade categories.
Direct sales lead on scale; distributors lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and mineral processing engineers concentrate in Spain's eastern chemical corridor, anchoring technical service capabilities for humidity-specific anti-caking development.
Andalusia
Fertilizer cooperatives in Córdoba and Seville provinces drive bulk mineral procurement for phosphate and urea storage. EU F-Gas Regulation compliance deadlines accelerate substitution toward mineral-based coatings. The Guadalquivir Valley processing corridor hosts expanding qualification programs for humidity-resistant formulations exceeding 75% relative humidity.
Catalonia
Seasoning manufacturers and convenience food processors in Barcelona province generate concentrated food-grade demand. EFSA frameworks under EU Regulation 231/2012 mandate additive purity documentation. The Penedès food manufacturing belt is retrofitting handling lines to accommodate reformulated mineral alternatives.
Valencia
Surface-modified precipitated silica adoption is accelerating among high-value fertilizer coating operations. REACH registration requirements through ECHA filter non-compliant import channels. Valencia's chemical cluster is displacing commodity calcium carbonate with engineered particle systems for coastal humidity applications.
Basque Country
Underpenetrated seasoning producers in Gipuzkoa and Bizkaia provinces present expansion targets for tailored mineral blends. EU Green Deal traceability mandates are reshaping sourcing documentation requirements. The Bilbao metropolitan area is developing specialized distribution infrastructure for bundled flow-aid contracts.
Aragon
Compound feed mills in Zaragoza province are modernizing protein concentrate handling infrastructure. ECHA compliance protocols govern chemical-grade substance placement. The Ebro Valley grain corridor is generating fresh demand for dust-suppression and flow-control agent integration.
Spain Anti Caking Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered performance segments. The supplier base organizes around mineral extraction capabilities, chemical modification expertise, and food safety certification depth. Three archetypes dominate: integrated mining-chemical conglomerates, specialized silica technology houses, and agricultural-input distributors with captive formulation capacity. Capacity expansion and strategic portfolio diversification into pharmaceutical-grade specifications represent the dominant competitive vectors.
Among Germany-based chemical conglomerates, Evonik Industries AG and BASF SE exemplify the integrated technology-leader archetype, anchoring premium positioning through specialized mineral formulations. Cargill Incorporated represents the agricultural-input distributor model, extending food-grade mineral portfolios into seasoning and coating channels. These three companies occupy distinct competitive positions based on vertical scope and end-market specialization.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Huber Engineered Materials |
| Cargill Incorporated |
| BASF SE |
| Solvay SA |
| PPG Industries |
| Kao Corporation |
| Merck KGaA |
| PQ Corporation |
| Others |
Value Network & Pricing Analysis
Surface-modified precipitated silica adoption is simultaneously compressing commodity mineral margins and concentrating supply leverage among European chemical clusters with proprietary particle engineering capabilities. This technology transition rewards suppliers with captive R&D infrastructure while penalizing traders dependent on standard-grade mineral sourcing.
Pricing Analysis
Bundled flow-aid and dust-suppression contracts are displacing single-product relationships across Andalusian fertilizer cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade calcium silicate from food-grade minerals and industrial bulk formulations. Cost compression in commodity minerals is intensifying because centralized procurement functions extract volume-tiered transparency. Animal feed mills exhibit highest price sensitivity; pharmaceutical manufacturers accept premium positioning for ECHA-registered purity documentation.
Supply Chain Analysis
Single-source vulnerability sits with high-purity calcium silicate production concentrated among limited EU-registered chemical manufacturers. Precipitated silica supply draws from Germany, Belgium, and Spain's Valencia chemical cluster. Raw material dependencies rest on sodium silicate feedstock, energy-intensive calcination processes, and specialized milling equipment. Tariff exposure on non-EU mineral imports creates protected market space for domestic producers. Distribution runs through agricultural cooperatives with centralized purchasing and regional chemical distributors serving fragmented food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's anti-caking market reads as a late-cycle quality story, with fertilizer cooperatives and pharmaceutical formulators both migrating toward humidity-specific engineered specifications that command sustainable margin premiums.
For Market Incumbents: Deepen backward integration into precipitated silica manufacturing to secure feedstock cost control against energy price volatility. Expand Valencia cluster capacity for surface-modified particle production, as REACH authorization timelines for synthetic alternatives extend approval risk for non-compliant imports. Cement ECHA registration depth as a competitive moat against emerging mineral traders. For New Entrants and Emerging Players: Agricultural cooperatives with unconsolidated procurement functions represent the most penetrable channel archetype, particularly in Castile and León's grain handling corridor. Target bundled service contracts combining anti-caking, flow-aid, and dust-suppression to displace single-product incumbents. Basque Country seasoning manufacturers offer white-space expansion with tailored mineral blend formulations. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier mineral traders lacking ECHA registration depth or proprietary particle engineering capabilities. Five-to-ten year viability favors suppliers with dual food-grade and pharmaceutical-grade certification infrastructure. Watch for EU Green Deal traceability mandate implementation as an inflection signal for sustainable sourcing premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Feedstock | Captive sodium silicate supply insulates margin stability from European energy cost volatility. |
| Surface-Modified Particle Capacity Expansion | Valencia chemical cluster adoption accelerates displacement of commodity calcium carbonate in coastal humidity applications. |
| ECHA Registration Investment | REACH compliance depth filters non-compliant imports and creates protected procurement channels for verified suppliers. |
| EU Green Deal Traceability Alignment | Sustainable mineral sourcing documentation opens preferential positioning in public procurement and cooperative purchasing. |
| Bundled Service Contract Development | Flow-aid and dust-suppression integration captures volume consolidation trends among centralized agricultural cooperatives. |
Research Methodology
Direct dialogue with fertilizer cooperative procurement directors, food manufacturing plant managers, chemical distribution channel partners, and ECHA regulatory consultants grounded qualitative findings in operational reality. Secondary validation drew from Spanish customs trade data, EU F-Gas Regulation implementation reports, SEC filings of listed chemical conglomerates, and ECHA registration databases. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down supply-side capacity assessments.
Bottom-up modeling segmented demand across mineral type, purity grade, and end-use application, while top-down analysis tracked supplier capacity and import penetration rates across the analysis window. Segmentation dimensions included product performance tier, regulatory compliance grade, moisture-resistance specification, and regional buyer concentration. CAGRs were derived from trend extrapolation of historical volume patterns adjusted for regulatory phaseout timelines and infrastructure modernization cycles. Key inputs incorporated fertilizer cooperative procurement consolidation rates and pharmaceutical-grade specification adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal traceability mandate timing and precipitated silica energy cost volatility. Forecasts reflect documented assumptions about regulatory implementation schedules and cooperative purchasing centralization trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Creasing Agent Market
Additives
Cetane Improver Additives Market
Additives
Global PVC Additives Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
North America Fuel Additives Market
Additives
Inorganic Filler Market
Additives
Sorbitan Oleate Market
Additives
Citrate Ester Market
Additives
Canada Anti-Caking Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Isobutyl Acetate Market
Additives
Disodium Guanylate Market
Additives
Global Synthetic Tackifier Market
Additives
Choline Chloride Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Caprylyl Glycol Market