
 Sodium Stannate Market | 2026-2036
Sodium Stannate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Stannate Market Analytics
Electroplating chemistry is rewriting how tin-based surface finishes replace lead in printed circuit board manufacturing. Showa leverages its Japanese manufacturing heritage to supply high-purity grades for semiconductor packaging. Yunnan Tin anchors upstream tin supply through captive mining and smelting operations in southwestern China. Reaxis differentiates via specialty organotin and inorganic tin catalyst formulations for North American industrial customers.
Sodium stannate is an inorganic tin compound, typically Na₂SnO₃·3H₂O, manufactured through alkaline fusion of tin oxide with sodium carbonate or direct electrochemical oxidation of metallic tin in caustic soda. The compound functions primarily as a mordant in textile dyeing, a stabilizer in peroxide bleaching, and a precursor for electroplating baths depositing tin and tin-alloy coatings. Crystalline sodium stannate leads product type revenue due to superior storage stability and precise dosing in automated plating lines, while liquid sodium stannate posts faster growth from just-in-time delivery contracts with electronics assemblers. Flame retardant applications command premium pricing as halogen-free formulations gain regulatory preference in consumer electronics housings.
REACH registration requirements and RoHS substance restrictions in Europe compel reformulation of legacy tin-plating processes, while China's MEE enforces wastewater discharge limits on stannate-containing effluents from plating facilities. Japan's METI chemical substance classification shapes import documentation burdens for regional traders. Stakeholders must monitor evolving battery-grade tin specifications, as sodium stannate purification pathways may converge with emerging tin-anode supply chains for lithium-ion alternatives.
Market Dynamics
Electroplating bath chemistry is pivoting toward tin-based formulations as REACH and RoHS restrictions eliminate lead from printed circuit board surface finishes, forcing reformulation investments across electronics supply chains.
Growth Catalysts
- Halogen-free flame retardant mandates:EU F-Gas Regulation and consumer electronics safety standards are accelerating sodium stannate adoption in polymer stabilization for device housings.
- Electronics manufacturing relocation:Printed circuit board fabricators in Vietnam and Mexico are installing tin-plating capacity that specifies high-purity sodium stannate feedstock.
- China's dual carbon goals:MEE wastewater discharge limits on plating effluents are pushing facilities toward closed-loop stannate recovery systems that favor concentrated crystalline product forms.
Market Restraints
- Tin price volatility:London Metal Exchange tin pricing swings directly compress sodium stannate producer margins and destabilize contract negotiations with electroplating customers.
- Upstream concentration:Captive tin smelting capacity in Indonesia and Myanmar creates supply vulnerability for non-integrated sodium stannate manufacturers dependent on spot tin oxide purchases.
- Alkaline plating substitution:Methane sulfonic acid tin plating baths are displacing traditional stannate chemistry in some high-speed reel-to-reel connector applications.
Strategic Opportunities
- Battery-grade tin purification:Sodium stannate production lines can retrofit to serve emerging tin-anode specifications for lithium-ion alternatives, with purification protocols converging across electroplating and energy storage grades.
- Just-in-time liquid delivery:Electronics assemblers in Guadalajara and Penang are contracting regional blending facilities for bulk liquid sodium stannate to reduce inventory carrying costs.
- India PLI scheme for electronics:Production-linked incentives for semiconductor and PCB manufacturing are creating first-mover advantages for stannate suppliers establishing local technical service presence.
Industry Challenges
- REACH registration documentation:European Chemicals Agency substance data requirements for tin compounds demand specialized toxicology and exposure assessments that smaller traders cannot self-generate.
- Electrochemical oxidation scale-up:Transitioning from batch alkaline fusion to continuous electrochemical tin oxidation requires capital-intensive cell engineering and process control expertise concentrated among Japanese equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Stannate Market |
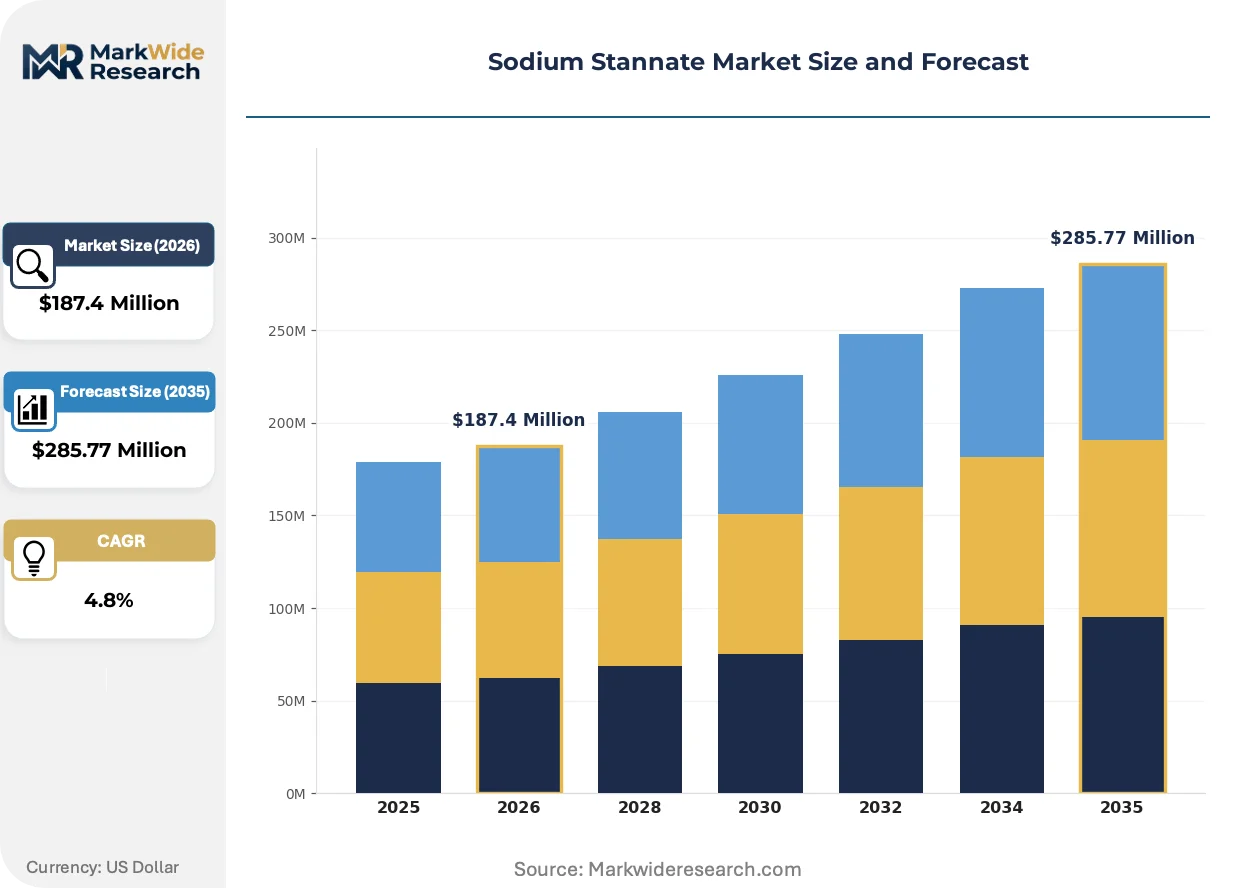
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Sodium Stannate, Liquid Sodium Stannate, Powdered Sodium Stannate, Soda-Lime Sodium Stannate End Use Industry: Textiles, Electronics, Chemical Manufacturing, Water Treatment Application: Flame Retardants, Catalyst, Pigments, Stabilizers Distribution Channel: Direct Sales, Wholesale, Online Retail, Distributors |
| Companies Covered | Showa, Binshun Chemical, Yunnan Tin, Noah Chemicals, NKS, China-Tin Group, Wuhan Kemi-Works, Haviland Enterprises, Reaxis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Stannate Market Evolving Landscape
Digital plating bath monitoring and predictive chemistry management are compressing the traditional supplier-customer relationship toward real-time specification adjustments and automated replenishment contracts.
Continuous electrochemical oxidation of metallic tin in caustic soda is virtualizing the conventional batch manufacturing footprint. Korean and Taiwanese electronics chemical suppliers are adopting this cell-based production for on-site generation at customer facilities. The technology is virtualizing regional distribution networks by eliminating crystalline product packaging, warehousing, and long-haul transport from the value chain.
REACH authorization requirements for tin compounds are forcing electroplaters to document substitution analysis and socioeconomic justifications for continued stannate use. German surface finishing trade associations are coordinating pooled registration consortia to share data costs. Semiconductor packaging facilities in Dresden and Leuven are responding by qualifying alternative tin sources ahead of potential sunset date pressures.
Electronics assemblers are consolidating sodium stannate purchasing through integrated chemical management contracts that bundle plating chemistry, analytical services, and waste treatment. Foxconn and Jabil procurement teams are replacing discrete spot buying with multi-year sole-source agreements. This concentration is most visible in Shenzhen and Ho Chi Minh City, where plating line operators now delegate specification compliance entirely to chemical suppliers.
Sodium Stannate Market Segmentation
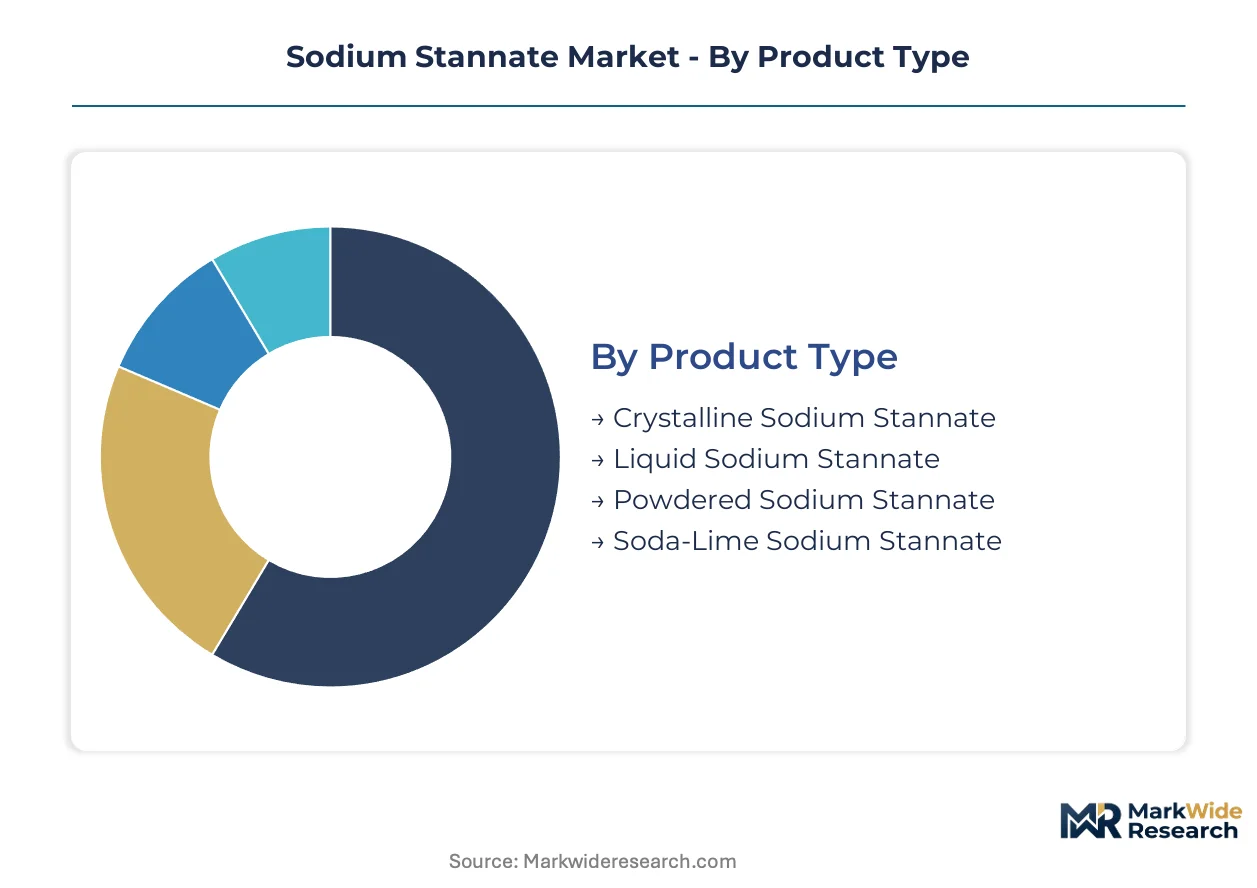
Sodium stannate specifications diverge sharply across electroplating baths, textile mordants, and polymer stabilization. Cycle times for crystalline grades stretch to months while liquid formulations turn weekly, reshaping inventory strategies across the supply base.
Product Type:
Crystalline sodium stannate locks capital longest in warehouse and transit, while liquid variants rotate fastest through just-in-time contracts with Mexican and Vietnamese electronics assemblers.
- Crystalline Sodium Stannate:Na₂SnO₃·3H₂O in granular or prilled form delivers precise dosing control for automated PCB plating lines. Demand clusters in China's Jiangsu province where closed-loop recovery systems comply with MEE wastewater discharge mandates.
- Liquid Sodium Stannate:Concentrated aqueous solutions eliminate dissolution steps and packaging waste for high-volume reel-to-reel connector manufacturers. Guadalajara and Penang electronics parks are contracting regional blending facilities to cut inventory carrying costs.
- Powdered Sodium Stannate:Fine-ground material serves legacy textile dyeing operations in India's Surat cluster where manual bath preparation persists.
- Soda-Lime Sodium Stannate:Modified alkaline matrix for specialized glass and ceramic applications requiring controlled tin release kinetics.
Crystalline sodium stannate dominates installed base. Liquid sodium stannate is where expansion concentrates.
End Use Industry:
Electronics plating commands premium pricing and technical service intensity, while textile applications run on thinner margins with longer contract tenures.
- Electronics:PCB surface finishing and semiconductor packaging drive high-purity specifications. REACH and RoHS restrictions on lead are forcing tin-plating bath conversions across Dresden and Leuven packaging facilities.
- Textiles:Mordant applications in peroxide bleaching and dye fixation. Surat and Tiruppur processing clusters in India maintain steady offtake for standard-grade crystalline product.
- Chemical Manufacturing:Intermediate for organotin catalysts and tin-based stabilizers serving polymer producers.
- Water Treatment:Coagulant and corrosion inhibitor applications in industrial cooling systems.
Electronics generates the steepest expansion trajectory. Textiles anchor volume stability through cyclical downturns.
Application:
Flame retardant formulations extract maximum value per kilogram through halogen-free polymer stabilization, while catalyst applications compete on throughput efficiency.
- Flame Retardants:Halogen-free tin-based stabilization for consumer electronics housings meeting EU F-Gas Regulation and safety standards. Device manufacturers in South Korea and Taiwan specify certified grades for premium product lines.
- Catalyst:Esterification and transesterification acceleration in polymer and biofuel production. Reaxis and specialty chemical suppliers formulate proprietary organotin derivatives from sodium stannate precursors.
- Pigments:Ceramic colorants and opacifiers requiring controlled particle size distribution.
- Stabilizers:Peroxide decomposition control in textile bleaching and pulp processing.
Flame retardants command margin leadership. Catalyst volumes scale most rapidly with biofuel capacity additions.
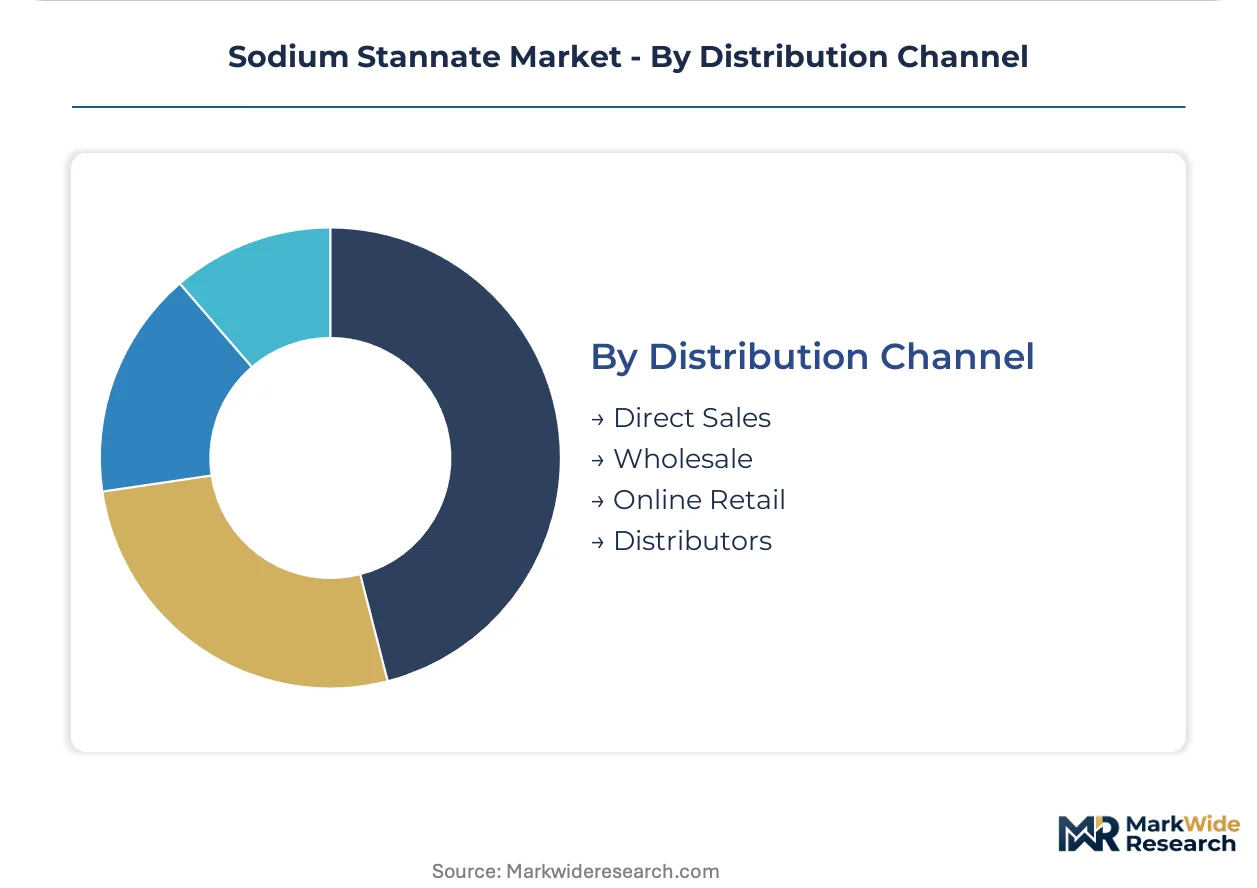
Distribution Channel:
Direct sales relationships absorb the technical service burden for electroplating chemistry, while distributor networks handle fragmented textile and water treatment accounts.
- Direct Sales:Foxconn and Jabil procurement teams are consolidating multi-year sole-source agreements that bundle plating chemistry, analytical services, and waste treatment. Shenzhen and Ho Chi Minh City concentration is most visible here.
- Distributors:Regional chemical distributors serve smaller PCB fabricators and textile processors with standardized crystalline grades.
- Wholesale:Bulk liquid delivery contracts for high-volume plating operations with dedicated storage infrastructure.
- Online Retail:Limited to laboratory quantities and specialty reagent grades for research applications.
Direct sales locks in specification compliance. Distributor channels capture geographic whitespace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electroplating chemical buyers cluster in electronics manufacturing corridors where REACH compliance and RoHS conversion timelines dictate procurement urgency. Sodium stannate demand concentrates in jurisdictions with dense PCB fabrication and semiconductor packaging infrastructure.
China
Jiangsu and Shandong provinces host tin chemical processing clusters serving domestic PCB manufacturers. MEE wastewater discharge limits on plating effluents are accelerating closed-loop stannate recovery system installations. Yunnan Tin anchors upstream supply through captive mining and smelting operations in southwestern China.
Germany
Dresden semiconductor packaging facilities are qualifying alternative tin sources ahead of potential REACH sunset date pressures. ECHA substance data requirements for tin compounds demand specialized toxicology assessments that reformulation investments must address. German surface finishing trade associations coordinate pooled registration consortia to share compliance costs.
Japan
METI chemical substance classification shapes import documentation burdens for regional traders handling high-purity grades. Showa leverages domestic manufacturing heritage to supply semiconductor packaging applications. Tokyo-based electronics chemical suppliers are adopting electrochemical oxidation cell technology for on-site generation at customer facilities.
United States
Reaxis formulates specialty organotin and inorganic tin catalyst formulations for North American industrial customers. EPA oversight of tin compound handling complements state-level environmental regulations for plating facility operations. Midwestern automotive electronics suppliers are converting lead-free surface finishes under RoHS-aligned customer mandates.
Vietnam
Ho Chi Minh City electronics parks are installing tin-plating capacity that specifies high-purity sodium stannate feedstock. Foxconn and Jabil procurement teams are consolidating multi-year sole-source agreements with regional chemical suppliers. Vietnamese PCB fabricators are contracting bulk liquid delivery to reduce inventory carrying costs.
Sodium Stannate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across differentiated service models. The vendor base organizes around three strategic archetypes: integrated tin miners with downstream chemical conversion, electroplating chemical specialists with formulation expertise, and regional distributors serving fragmented textile and water treatment accounts. Capacity expansion and qualification of battery-grade purification protocols represent the dominant competitive moves as electroplating and energy storage specifications converge.
Within the integrated upstream tier, Yunnan Tin and China-Tin Group exemplify miners controlling captive smelting and chemical conversion capacity. Showa represents Japanese manufacturing heritage in high-purity semiconductor packaging grades. Reaxis occupies the specialty formulation position for North American industrial catalyst applications.
| Leading Market Players |
|---|
| Showa |
| Binshun Chemical |
| Yunnan Tin |
| Noah Chemicals |
| NKS |
| China-Tin Group |
| Wuhan Kemi-Works |
| Haviland Enterprises |
| Reaxis |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam container corridor channels sodium stannate logistics costs into downstream price stratification, amplifying margin pressure for non-integrated European electroplaters while Jiangsu-based producers exploit captive tin oxide supply to defend pricing power across crystalline and liquid grade tiers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange tin indexation dominate long-term electroplating chemical agreements, creating margin volatility when LME pricing swings compress producer spreads. Three-tier pricing structure across battery-grade, semiconductor-grade, and industrial-grade crystalline products reflects purification protocol intensity and REACH documentation burdens. Cost compression in standard-grade liquid formulations is intensifying because Vietnamese and Mexican electronics assemblers are consolidating procurement through integrated chemical management contracts. Textile mordant buyers in India's Surat cluster exhibit highest price sensitivity due to manual bath preparation and thin margin structures, while semiconductor packaging facilities in Dresden and Leuven demonstrate lowest sensitivity given qualification costs and specification lock-in.
Supply Chain Analysis
Export control regimes on electrochemical oxidation cell technology limit Japanese equipment vendor sales to Chinese sodium stannate producers, constraining process upgrade pathways for regional competitors. Geographic supply concentration centers on China, Indonesia, and Myanmar, with captive tin smelting operations in Yunnan and Myanmar's Wa State anchoring upstream oxide feedstock. Raw material dependencies rest on cassiterite concentrate, caustic soda, and sodium carbonate, with energy costs for alkaline fusion representing a secondary input pressure. Single-source vulnerability from Indonesian tin export policy shifts creates structural risk for non-integrated manufacturers dependent on spot oxide purchases. Distribution runs through direct technical service relationships for electronics plating accounts and regional chemical distributors serving fragmented textile processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium stannate procurement is consolidating around service-attach contracts where analytical services, waste treatment, and predictive bath management generate recurring revenue expanding faster than crystalline product sales.
For Market Incumbents: Pre-empt methane sulfonic acid tin plating substitution in high-speed reel-to-reel connector applications by accelerating electrochemical oxidation cell deployment at customer facilities. Secure backward integration into captive tin oxide supply through offtake agreements with Indonesian or Myanmar smelters, reducing LME price exposure that currently destabilizes contract negotiations. Qualify battery-grade purification protocols ahead of tin-anode specification convergence to capture emerging lithium-ion alternative demand. For New Entrants and Emerging Players: Establish a beachhead in India's electronics manufacturing corridors under the PLI scheme for semiconductor and PCB production, where first-mover technical service presence creates procurement lock-in before incumbent qualification. Target liquid sodium stannate blending facilities in Guadalajara and Penang electronics parks, leveraging just-in-time delivery contracts to displace crystalline product inventory carrying costs. Deploy regional analytical service capabilities as the primary go-to-market wedge, bundling plating chemistry management to secure sole-source positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming tin chemical divisions lacking electroplating formulation expertise or REACH registration consortia membership. Long-term viability hinges on convergence between electroplating and battery-grade purification capabilities, positioning integrated producers to serve dual demand pools. Watch for tin-anode pilot production announcements from solid-state battery developers as the inflection signal triggering capacity expansion and qualification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Electrochemical Oxidation Scale-Up | Continuous cell technology eliminates crystalline packaging and warehousing from Japanese supplier value chains. |
| Backward Integration into Tin Oxide | Captive smelting in Yunnan or Myanmar insulates margin compression from LME pricing volatility. |
| Battery-Grade Purification Qualification | Convergence with tin-anode specifications opens lithium-ion alternative supply chain positioning. |
| Regional Liquid Blending Facilities | Guadalajara and Penang installations capture just-in-time delivery demand from electronics assemblers. |
| REACH Registration Consortium Participation | Pooled ECHA data costs protect European market access against sunset date pressures. |
Research Methodology
A standing panel of electroplating chemical plant managers, PCB fabricator procurement leads, tin oxide smelter operations directors, and textile dyeing technical supervisors provided ongoing calibration across primary interview cycles. Secondary validation drew from Chinese customs trade data, Jiangsu and Shandong provincial environmental discharge records, ECHA REACH registration filings, and SEC 10-K disclosures from listed tin chemical producers. Bottom-up demand modeling across end-use industries triangulated against top-down tin consumption forecasts to generate volume and value estimates.
Scenario-bracketing framed optimistic, baseline, and constrained demand pathways across the projection horizon without specifying discrete year markers. Segmentation dimensions modeled included crystalline versus liquid product forms, electronics versus textile versus chemical manufacturing end-use industries, and flame retardant versus catalyst versus stabilizer applications. CAGRs were derived from regression analysis of historical tin chemical consumption patterns adjusted for REACH-driven lead substitution acceleration and China's dual carbon wastewater mandates. Industry-specific forecast inputs incorporated MEE discharge limit compliance timelines and RoHS conversion schedules at European PCB facilities.
Stress conditions across LME tin price volatility bands, Indonesian export policy disruption scenarios, and electrochemical oxidation technology diffusion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained electronics manufacturing relocation to Vietnam and Mexico, continued REACH enforcement intensity, and stable tin-anode development trajectories for energy storage applications. Material shifts in Chinese environmental regulator enforcement posture or solid-state battery commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Furniture Foam Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Calcium Sulphite Market