
 Europe Antifreeze Coolant Market | 2026-2036
Europe Antifreeze Coolant Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Antifreeze Coolant Market Analysis
Aftermarket service revenue is fragmenting across Europe as vehicle electrification alters thermal system maintenance cycles. BASF SE leverages its integrated ethylene oxide supply chain to sustain margin capture in concentrated coolants. Fuchs Petrolub SE anchors its position through specialized industrial formulations for German machine tool builders. Royal Dutch Shell competes via retail channel density and fleet service partnerships across France and the Benelux.
Antifreeze coolant is a heat-transfer fluid comprising ethylene glycol or propylene glycol base stocks with corrosion inhibitor packages, designed to depress the freezing point and elevate the boiling point of engine cooling systems. The formulation typically operates between minus thirty-seven degrees Celsius and one hundred twenty-nine degrees Celsius in pressurized automotive circuits, protecting aluminum, cast iron, and polymer components from cavitation and galvanic degradation. Ethylene glycol formulations still dominate installed volumes across European passenger car parc, though propylene glycol is gaining structural share in food-processing HVAC and marine applications where toxicity regulations restrict ethylene glycol discharge. The aftermarket provider channel carries higher per-liter margins than OEM supply, though OEM contracts lock in multi-year specification adherence and testing validation costs.
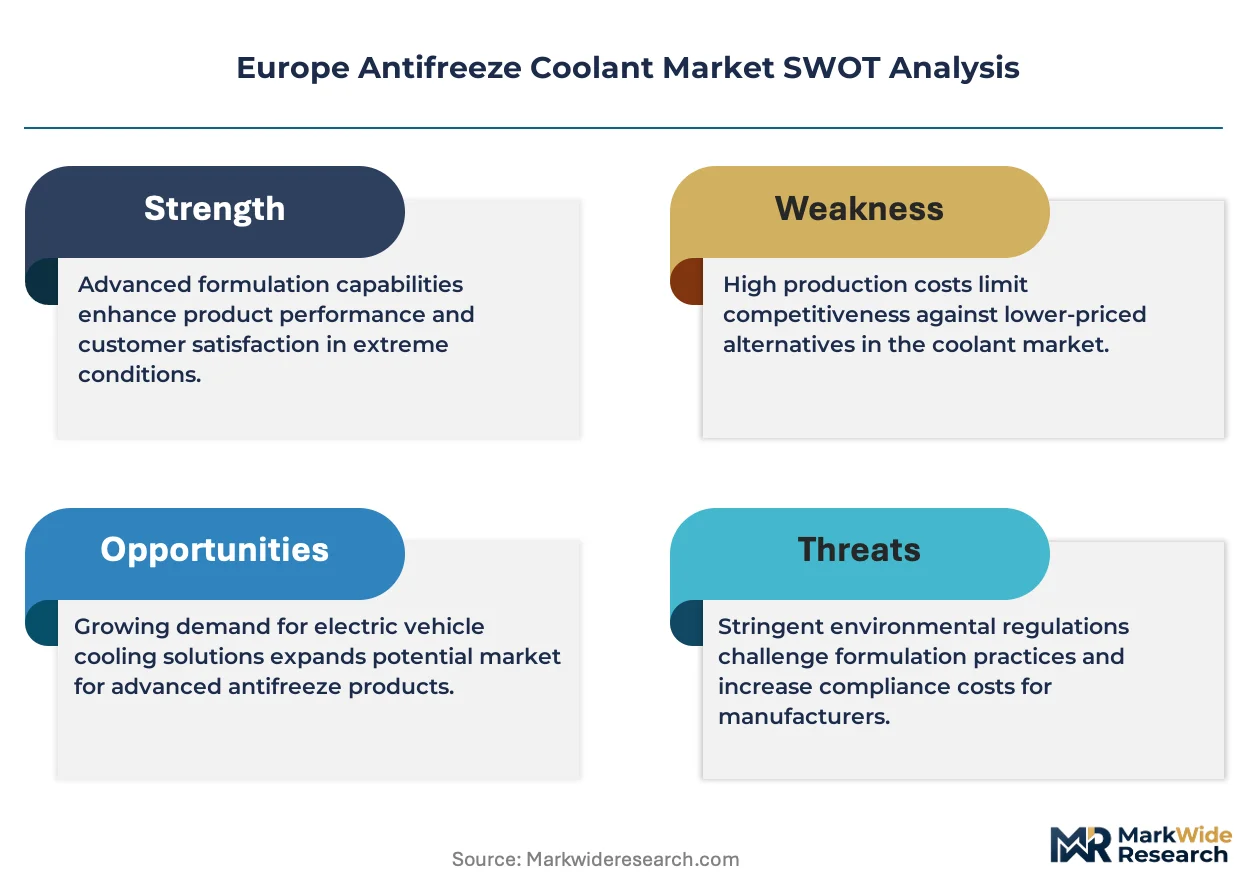
REACH registration requirements and the EU F-Gas Regulation constrain formulation chemistries available to blenders, pushing Arteco NV and Pentosin-Werke GmbH toward phosphate-free and silicate-reduced organic acid technology platforms. ECHA substance evaluation cycles are extending reformulation lead times, forcing smaller compounders to rely on pre-registered additive packages rather than proprietary inhibitor development. Stakeholders must monitor pending MEE classifications for boron and amine derivatives, as these restrictions would force second-generation organic acid technology transitions across the European installed base before current coolant inventories deplete.
Market Dynamics
Electrification of European powertrains is compressing traditional coolant service intervals while expanding thermal management complexity, forcing reformulation investments across the value chain.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are accelerating adoption of low-GWP propylene glycol formulations in commercial vehicle HVAC systems.
- Extended service intervals:German and French automotive OEMs now specify 250,000-kilometer coolant lifecycles, driving demand for organic acid technology packages with enhanced corrosion inhibition.
- Electrification thermal loads:Battery electric vehicle power electronics require dielectric coolant compatibility, opening specification windows for glycol-silicate hybrid chemistries.
Market Restraints
- Ethylene oxide feedstock volatility:BASF and INEOS ethylene glycol producers face margin compression from natural gas price swings tied to European energy security disruptions.
- REACH registration costs:ECHA substance evaluation cycles for novel corrosion inhibitors extend commercialization timelines to 18-24 months, freezing out mid-tier compounders.
- Propylene glycol supply concentration:European bio-based propylene glycol capacity clusters in Netherlands and Belgium, creating single-source risk for food-grade and marine formulation blenders.
Strategic Opportunities
- Poland and Czech Republic aftermarket penetration:Vehicle parc expansion in Central European logistics corridors remains underserved by premium coolant distribution networks.
- Data center liquid cooling:Hyperscale facilities in Frankfurt and Amsterdam are adopting automotive-derived glycol formulations for immersion cooling of AI training clusters.
- EU Green Deal public procurement:Bio-based content mandates for municipal fleet maintenance contracts create preferential bidding windows for renewable feedstock coolant suppliers.
Industry Challenges
- Additive chemistry expertise scarcity:Formulators struggle to recruit tribologists familiar with phosphate-free organic acid technology validation protocols.
- OEM specification lock-in:Volkswagen Group and Stellantis multi-year supply agreements require dedicated testing facilities that smaller blenders cannot finance.
- Legacy fleet compatibility:Second-generation organic acid coolants face warranty void risks when servicing vehicles originally specified for hybrid organic acid technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Antifreeze Coolant Market |
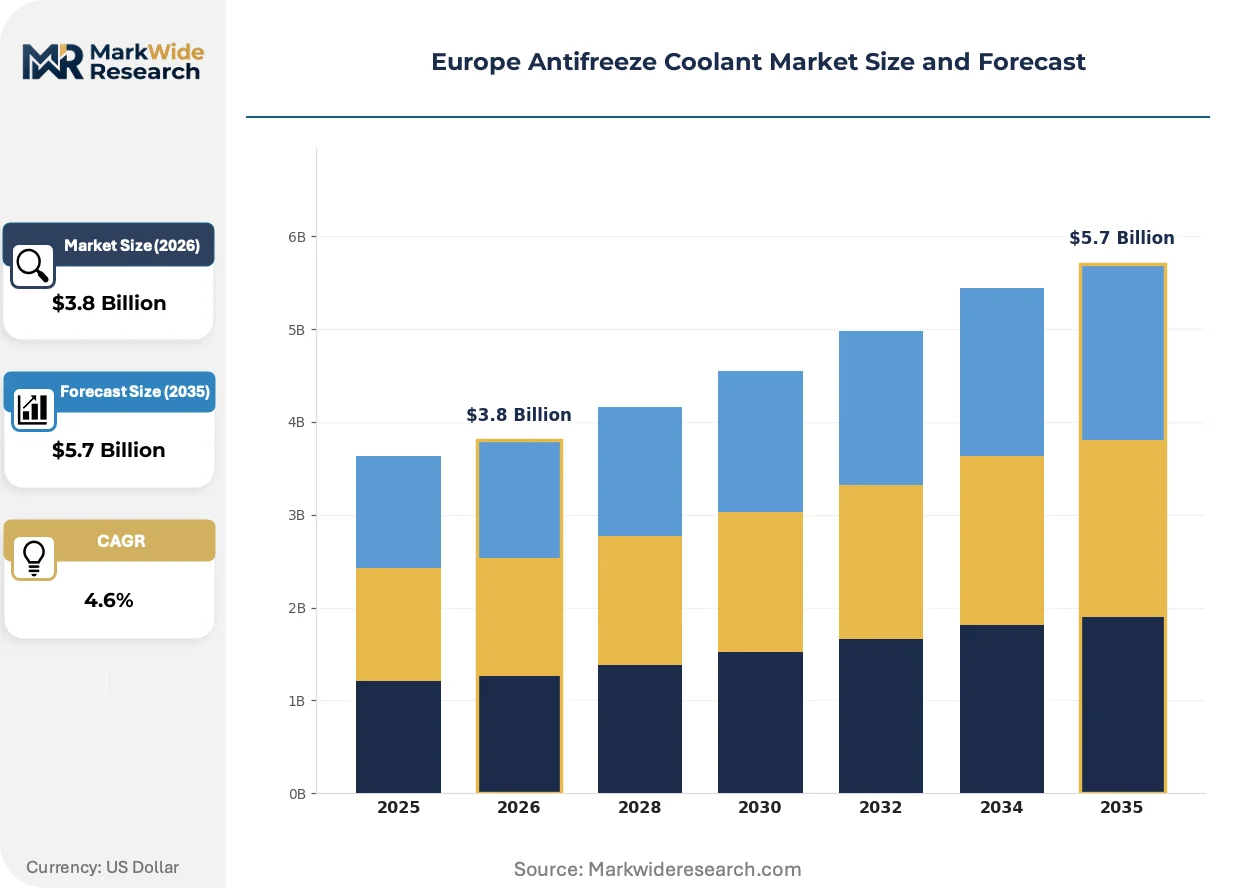
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Glycol, Propylene Glycol, Alcohol-Based, Others Application: Automotive, Industrial, Marine, HVAC End User: OEMs, Aftermarket Providers, Industrial Facilities, Commercial Vehicles Distribution Channel: Online, Retail Stores, Auto Parts Shops, Distributors |
| Companies Covered | Chevron Corporation, Pentosin-Werke GmbH, BASF SE, Comma Oil & Chemicals Ltd., Arteco NV, Royal Dutch Shell, Fuchs Petrolub SE, Arom-Dekor Kemi, TotalEnergies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Antifreeze Coolant Market Emerging Trajectories
Formulation science and regulatory chemistry are converging to redefine acceptable performance thresholds, with toxicity reduction and electrification compatibility emerging as non-negotiable design parameters.
Organic acid technology with silicate-free inhibitor packages is rendering obsolete conventional hybrid formulations across European passenger car parc service. Independent workshops in Germany and France now stock exclusively extended-life coolants to reduce inventory complexity. The shift compresses aftermarket SKU counts by forty percent while elevating per-liter technical support requirements.
REACH substance restriction proposals targeting boron and amine derivatives are forcing preemptive reformulation cycles ahead of regulatory enforcement. ECHA's 2024-2026 evaluation timeline for boric acid derivatives threatens existing coolant inventories across Southern European markets. Blenders are accelerating phosphate-free organic acid technology platform migration to avoid stranded stock positions.
Fleet operators are consolidating procurement through integrated service contracts that bundle coolant with preventive maintenance scheduling. Large logistics providers in the Benelux now source directly from blenders, bypassing traditional distributor markups. The disintermediation concentrates volume with formulation specialists capable of delivering bulk tanker replenishment to centralized depot networks.
Europe Antifreeze Coolant Market Segmentation
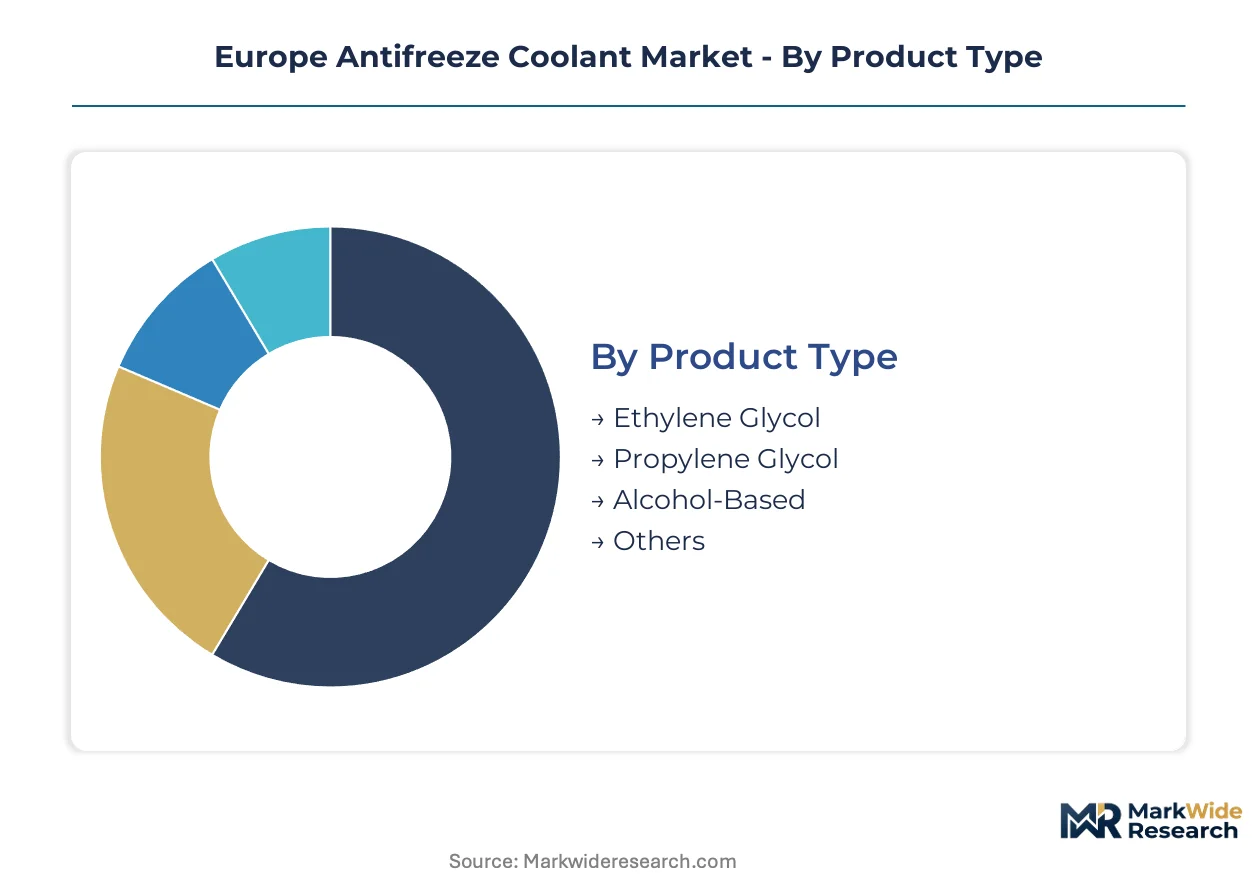
Segmentation in the Europe antifreeze coolant market reveals divergent formulation requirements across thermal management applications. Each dimension—product chemistry, end-use environment, customer procurement mode, and channel structure—carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Use-case spectrum spans toxic industrial formulations to food-safe alternatives, with base stock selection dictated by discharge regulations and thermal performance thresholds.
- Ethylene Glycol:Petroleum-derived diol delivering superior freeze protection and thermal conductivity in pressurized automotive cooling circuits. Demand concentrates in Germany's passenger car manufacturing corridor, where OEMs specify hybrid organic acid technology for 250,000-kilometer service intervals.
- Propylene Glycol:Less toxic alternative with marginally reduced heat transfer efficiency, favored where discharge restrictions apply. Food-processing HVAC installations across France and the Netherlands drive structural share gains as REACH toxicity evaluations tighten.
- Alcohol-Based:Methanol or ethanol formulations for deicing and emergency freeze protection in non-circulating systems. Limited to seasonal applications with shorter duty cycles.
- Others:Glycerin-based and experimental bio-derived fluids for specialized marine and aerospace thermal management.
Established volume favors ethylene glycol; emerging adoption favors propylene glycol.
Application:
Cost tier separation distinguishes commodity automotive volumes from specification-intensive industrial and marine segments.
- Automotive:Passenger car and light truck coolant systems requiring aluminum-compatible corrosion inhibition. Germany's powertrain electrification is compressing traditional service intervals while expanding dielectric coolant specifications for battery thermal management.
- Industrial:Machine tool cooling, metalworking fluid temperature control, and process heat exchange. German manufacturing clusters specify phosphate-free organic acid technology to meet wastewater discharge standards.
- Marine:Seawater-cooled auxiliary systems and engine protection for commercial shipping. Baltic and North Sea routes drive demand for biodegradable formulations under MARPOL discharge protocols.
- HVAC:Commercial building climate control and district heating networks. EU F-Gas Regulation phase-down schedules accelerate propylene glycol adoption as low-GWP heat transfer fluid.
Automotive commands absolute volume; HVAC is climbing the fastest on regulatory displacement of fluorinated refrigerants.
End User:
Customer type determines specification authority, with OEMs locking multi-year formulations versus aftermarket price sensitivity.
- OEMs:Volkswagen Group, Stellantis, and BMW specify proprietary coolant chemistries with dedicated testing validation. Multi-year supply agreements require captive laboratory facilities that exclude mid-tier blenders.
- Aftermarket Providers:Independent workshops and fast-fit chains carrying higher per-liter margins but fragmented across generic and premium private-label offerings. Central European logistics corridors in Poland and Czech Republic remain underserved.
- Industrial Facilities:Steel mills, chemical plants, and power stations procuring bulk coolant for closed-loop cooling towers. Volume concentration favors direct blender relationships over distributor markups.
- Commercial Vehicles:Fleet operators consolidating procurement through integrated service contracts bundling coolant with preventive maintenance scheduling.
OEM contracts anchor formulation R&D aftermarket expansion offers the steepest margin recovery for specialized blenders.
Distribution Channel:
Supply concentration varies by geography, with retail density in mature markets versus distributor-led penetration in developing corridors.
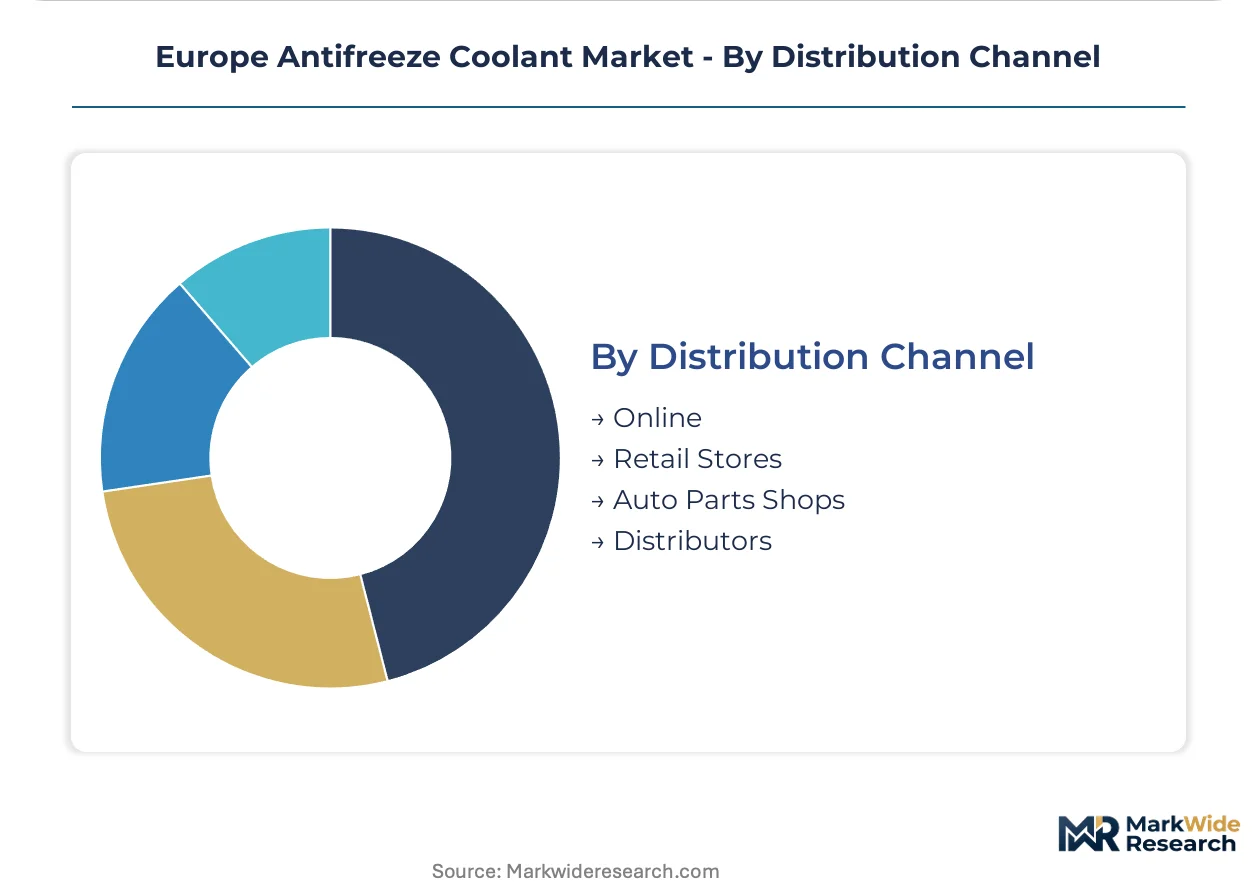
- Online:E-commerce platforms capturing DIY consumer and small fleet procurement. Limited to packaged formats below bulk tanker thresholds.
- Retail Stores:Hypermarkets and automotive specialists stocking pre-mixed and concentrated formats for emergency top-up demand.
- Auto Parts Shops:Specialist chains with technical counter staff capable of specification matching for workshop trade. Germany's workshop density supports premium product placement.
- Distributors:Regional logistics networks delivering bulk replenishment to centralized depot networks. Benelux fleet operators increasingly bypass this tier through direct blender contracts.
Distributors still move the largest absolute volumes; online channels are gaining share fastest among price-transparent small fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across European markets, with Germany prioritizing extended-service automotive formulations while France and the Netherlands accelerate propylene glycol adoption for food-processing and marine discharge compliance.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify 250,000-kilometer coolant lifecycles for powertrain thermal management. The KBA enforces type-approval standards that lock suppliers into multi-year validation protocols. Stuttgart's manufacturing corridor concentrates demand for organic acid technology packages compatible with aluminum engine blocks.
France
Food-processing HVAC installations in the Île-de-France region drive structural demand for low-toxicity propylene glycol formulations. ANSM toxicity evaluations are tightening discharge restrictions for ethylene glycol near agricultural zones. Lyon and Marseille marine terminals specify biodegradable coolant for Baltic and North Sea shipping routes under MARPOL protocols.
Netherlands
Rotterdam's chemical cluster anchors European bio-based propylene glycol capacity for food-grade and marine applications. The EU F-Gas Regulation accelerates adoption of low-GWP heat transfer fluids in commercial vehicle climate systems. Amsterdam data centers are repurposing automotive-derived glycol formulations for AI training cluster immersion cooling.
Poland
Central European logistics corridors expand vehicle parc density without matching aftermarket coolant distribution penetration. Polish waste discharge regulations are converging with REACH substance evaluation timelines for boron derivative restrictions. Warsaw and Krakow fleet operators remain underserved by premium organic acid technology supply networks.
Belgium
Antwerp's petrochemical hub processes ethylene oxide feedstock for concentrated coolant manufacturing serving Benelux industrial markets. ECHA substance evaluation cycles extend reformulation lead times for corrosion inhibitor packages. Ghent's automotive suppliers specify phosphate-free organic acid technology to meet wastewater discharge standards.
Europe Antifreeze Coolant Market Vendor Landscape
Capability concentration sits with specialized formulators possessing captive additive chemistry expertise; scale advantage sits with integrated petrochemical producers controlling upstream ethylene oxide supply. The market structures around three tiers: multinational chemical conglomerates with automotive OEM supply contracts, mid-sized blenders serving industrial aftermarket channels, and regional compounders focused on marine and food-grade niches. Dominant competitive moves include backward integration into ethylene glycol production and strategic partnerships with fleet operators for bulk supply contracts.
Within the integrated chemical tier, BASF SE exemplifies scale-driven positioning through its Ludwigshafen ethylene oxide supply chain. Royal Dutch Shell occupies a position bridging retail channel density with fleet service partnerships across France and the Benelux. Fuchs Petrolub SE anchors the specialized industrial segment through formulations targeting German machine tool builders. Pentosin-Werke GmbH represents the mid-tier blender archetype navigating REACH registration constraints through pre-registered additive packages.
| Leading Market Players |
|---|
| Chevron Corporation |
| Pentosin-Werke GmbH |
| BASF SE |
| Comma Oil & Chemicals Ltd. |
| Arteco NV |
| Royal Dutch Shell |
| Fuchs Petrolub SE |
| Arom-Dekor Kemi |
| TotalEnergies |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Belgian ethylene oxide production is compressing spot prices for concentrated coolant feedstock while simultaneously eroding leverage for contract renegotiations. German blenders facing margin compression are accelerating backward integration into captive glycol production to defend pricing autonomy against Rotterdam spot market volatility.
Pricing Analysis
Long-term offtake agreements between BASF and Volkswagen Group anchor volume pricing for organic acid technology packages, while spot market transactions in Rotterdam and Antwerp set marginal cost benchmarks for smaller compounders. Price differentiation rests on REACH registration tier and OEM validation status, with certified formulations commanding substantial premia over generic aftermarket blends. Pricing pressure stems from natural gas cost volatility feeding ethylene oxide production economics. Fleet operators exhibit highest price sensitivity, whereas OEM procurement teams prioritize specification adherence over unit cost optimization.
Supply Chain Analysis
Upstream ethylene oxide feedstock concentrates in Belgium, Germany, and the Netherlands, with INEOS and BASF controlling European cracking capacity. Raw material dependencies include natural gas for ethylene production, corrosion inhibitor additive packages from specialty chemical suppliers, and phosphate-free organic acid technology licensing. Single-source vulnerability pervades bio-based propylene glycol, where Netherlands-based capacity serves food-grade and marine formulation demand. Distribution runs through regional tanker networks serving centralized depot systems, though Benelux fleet operators increasingly source direct from blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's antifreeze coolant market represents early-cycle expansion as electrification-driven thermal management complexity outpaces traditional service interval compression. Propylene glycol penetration in food-processing HVAC and marine applications is accelerating faster than ethylene glycol displacement in automotive, creating asymmetric growth pockets.
For Market Incumbents: Pre-empt REACH substance restriction enforcement by accelerating phosphate-free organic acid technology platform migration ahead of ECHA's boron derivative evaluation timeline. Secure captive ethylene oxide supply through backward integration or long-term feedstock offtake to insulate margin structures from natural gas volatility. Defend OEM specification lock-in through dedicated testing facility investments that exclude mid-tier blenders from multi-year supply agreement eligibility.
For New Entrants and Emerging Players: Build out distribution infrastructure in Poland and Czech Republic logistics corridors, where vehicle parc expansion has outpaced premium coolant aftermarket penetration. Target data center liquid cooling applications in Frankfurt and Amsterdam, where automotive-derived glycol formulations are repurposing for AI training cluster immersion cooling. Pursue EU Green Deal public procurement channels with bio-based content credentials to bypass entrenched automotive OEM supply relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because REACH substance evaluation cycles and F-Gas Regulation phase-down schedules are structurally elevating barriers to novel formulation entry. Acquisition targets should display captive additive chemistry expertise or pre-registered inhibitor package relationships that circumvent ECHA commercialization delays. Monitor ECHA MEE classification timelines for boron and amine derivatives as the critical inflection signal for second-generation organic acid technology transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | BASF's Ludwigshafen captive supply insulates margin capture from Rotterdam spot volatility. |
| Phosphate-Free Organic Acid Technology Migration | Arteco NV and Pentosin-Werke GmbH preempt REACH boron restrictions ahead of ECHA enforcement. |
| Direct Fleet Supply Contracting | Benelux logistics operators bypass distributor markups through centralized depot tanker replenishment. |
| Bio-Based Propylene Glycol Capacity Expansion | Netherlands chemical cluster serves food-grade HVAC and marine discharge compliance demand. |
| Data Center Liquid Cooling Partnership | Amsterdam hyperscale facilities adopt automotive-derived glycol for AI training cluster thermal management. |
Methodological Framework
A standing panel of coolant formulators, automotive OEM procurement directors, industrial maintenance engineers, and REACH regulatory consultants provided ongoing calibration throughout the study period. Primary interviews with these stakeholders were cross-validated against secondary sources including ECHA substance evaluation databases, EU F-Gas Regulation implementation reports, and customs trade data for ethylene glycol and propylene glycol flows. Bottom-up volume modeling from end-use application segments was triangulated with top-down value estimates derived from producer revenue disclosures.
Scenario bracketing around electrification adoption velocity and REACH substance restriction timing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include base stock chemistry, end-use environment, customer procurement mode, and distribution channel structure. CAGRs were derived from elasticity-adjusted volume projections incorporating OEM specification adherence rates and aftermarket service interval compression factors. Industry-specific inputs encompassed powertrain thermal management content per vehicle and data center liquid cooling adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Middle Eastern petrochemical producers or accelerated bio-based propylene glycol commercialization would shift outcomes materially. Quarterly review of ECHA evaluation timelines, natural gas price benchmarks, and OEM electrification platform rollouts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Anti-Corrosive Agents Market