
 Surface Disinfectant Products Market | 2026-2036
Surface Disinfectant Products Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Disinfectant Products Market Analytics
Asset-light contract manufacturing and private-label leasing arrangements is fragmenting competitive tiers in surface disinfectants, enabling mid-tier brands to challenge incumbents without capital-intensive production infrastructure. Reckitt Benckiser Group PLC leverages its Lysol brand equity and retail pharmacy channel control to sustain premium positioning across North American and European markets. Ecolab anchors its institutional presence through integrated hygiene programs that bundle disinfectant supply with compliance auditing and staff training services.
Surface disinfectant products are chemical or biological formulations engineered to eliminate or inactivate pathogenic microorganisms on non-living surfaces, typically containing active concentrations of quaternary ammonium compounds, hydrogen peroxide, or ethanol at specified log-reduction thresholds validated against EPA or EN test protocols. Their primary commercial purpose spans infection prevention in healthcare environments, food safety assurance in hospitality and food processing, and occupational health compliance in office and industrial settings. Liquid formulations dominate institutional procurement volumes due to cost-per-application efficiency and compatibility with automated dilution systems, while wipes command higher unit margins in clinical point-of-care applications where convenience and single-use compliance reduce cross-contamination risk. Alcohol-based formulations lead in rapid-turnover environments such as emergency departments and food preparation surfaces, whereas hydrogen peroxide-based alternatives are gaining preference in settings with respiratory sensitivity concerns or where residue-free evaporation supports cleanroom protocols.
The EPA regulates surface disinfectant efficacy claims through its Office of Pesticide Programs, requiring substantiated log-reduction data against specified pathogen panels before products can carry kill claims or enter interstate commerce. Healthcare facilities must additionally navigate Joint Commission accreditation standards and OSHA bloodborne pathogen compliance, which mandate documented cleaning frequencies and product rotation protocols that directly shape procurement specifications and inventory management systems. Stakeholders should monitor how evolving EPA guidance on per- and polyfluoroalkyl substance contamination in chemical supply chains will alter raw material sourcing strategies and reformulation timelines across the sector.
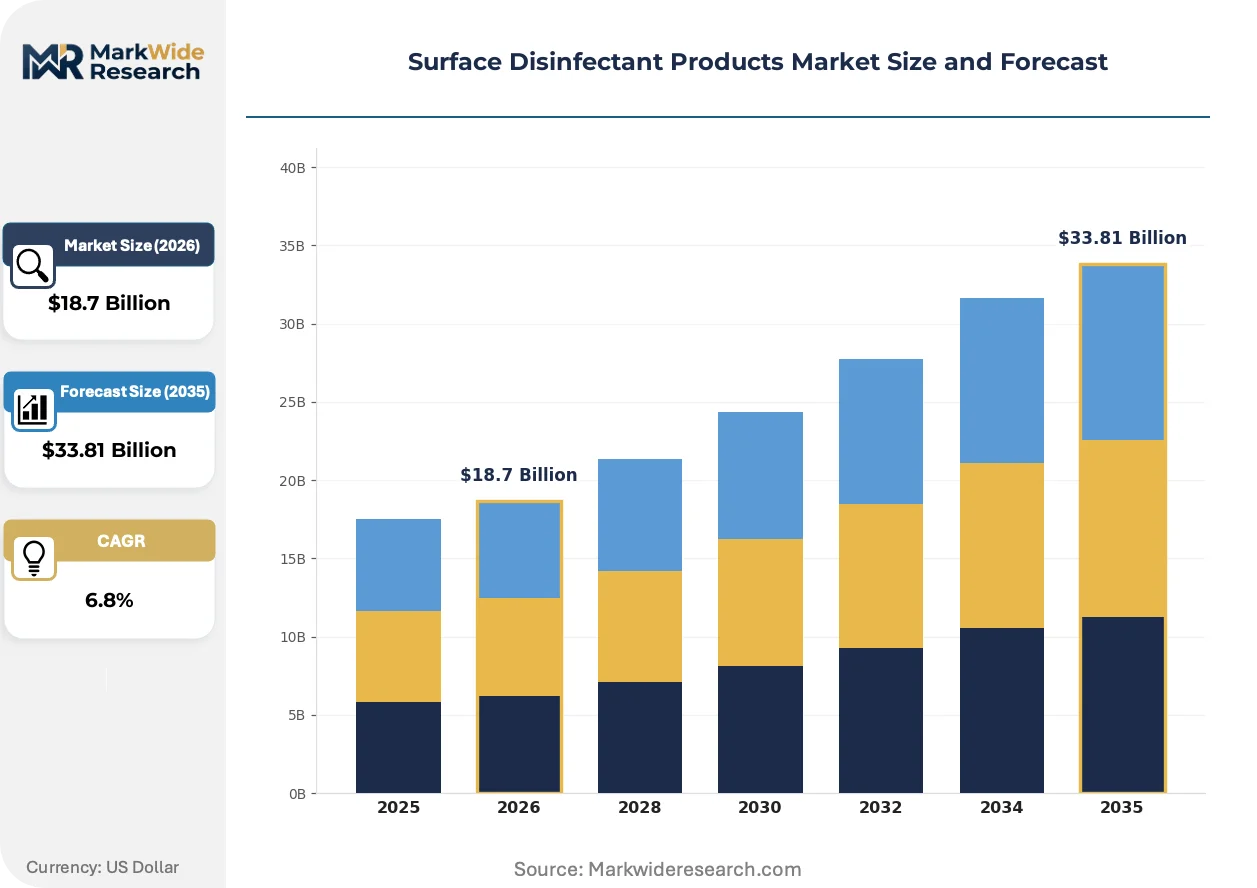
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously demanding bundled service capabilities that smaller manufacturers cannot replicate without operational restructuring.
Growth Catalysts
- Healthcare-associated infection mandates:Joint Commission accreditation standards now require documented disinfection protocols across acute care networks, institutionalizing recurring demand cycles.
- EPA emerging pathogen framework:The framework accelerates product registration timelines for manufacturers with validated efficacy data against novel viral threats.
- Food processing automation:Automated dilution systems in meat and poultry facilities are standardizing chemical delivery infrastructure that locks in volume contracts.
Market Restraints
- Quaternary ammonium compound feedstock volatility:Petrochemical derivative pricing swings directly compress formulation margins for mid-tier suppliers lacking long-term supply agreements.
- EPA registration timeline friction:The Office of Pesticide Programs requires 12-24 month efficacy validation cycles that delay commercialization and freeze R&D capital.
- Electrostatic spray substitution:Non-chemical surface treatment technologies are capturing terminal cleaning applications in aviation and semiconductor cleanrooms.
Strategic Opportunities
- Outpatient surgical center expansion:Ambulatory facility construction in Texas and Florida is outpacing supply of regionally distributed disinfectant portfolios.
- OSHA bloodborne pathogen compliance bundling:Training and documentation services attached to chemical supply create defensible contract renewal rates.
- Electrolyzed water convergence:On-site generation systems combined with IoT monitoring are displacing delivered-chemical models in hospitality chains.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in EPA-compliant antimicrobial chemistry commands premium compensation that strains mid-cap R&D budgets.
- Legacy dilution equipment incompatibility:Healthcare facilities with installed base of 1990s-era proportioning systems resist chemistry changes requiring capital retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Disinfectant Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Wipe, Spray, Foam Application: Healthcare, Commercial, Industrial, Residential Formulation: Alcohol-based, Hydrogen Peroxide-based, Quaternary Ammonium Compounds, Others End User: Hospitals, Offices, Schools, Restaurants |
| Companies Covered | Reckitt Benckiser Group PLC, Procter & Gamble, 3M, Ecolab, The Clorox Company, SC Johnson, GOJO Industries, Inc., STERIS, Diversey Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Disinfectant Products Market Evolving Landscape
Formulation science is converging with digital compliance tools to reshape how facilities document, verify, and audit surface hygiene protocols across regulated environments.
Peracetic acid-hydrogen peroxide blends are hybridizing traditional disinfection with sporicidal claims previously requiring separate glutaraldehyde cycles. Hospital sterile processing departments in the United States are adopting these chemistries to consolidate SKU complexity and reduce storage footprint. The convergence is hybridizing vendor relationships as chemical suppliers acquire software platforms for automated compliance logging.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of surfactant packages used in ready-to-use sprays and wipes. European manufacturers are accelerating substitution timelines ahead of 2025 authorization sunset dates. Food contact surface applications face the steepest technical barriers as replacement chemistries must match residue profiles without altering EPA-registered kill claims.
Bulk concentrate purchasing with third-party dilution service contracts is displacing traditional case-good deliveries in multi-site healthcare systems. Group purchasing organizations are centralizing specification authority and mandating electronic inventory tracking that locks out non-integrated suppliers. The restructuring is most visible in California and New York health systems where labor cost pressures have eliminated on-site housekeeping chemical management roles.
Surface Disinfectant Products Market Segmentation
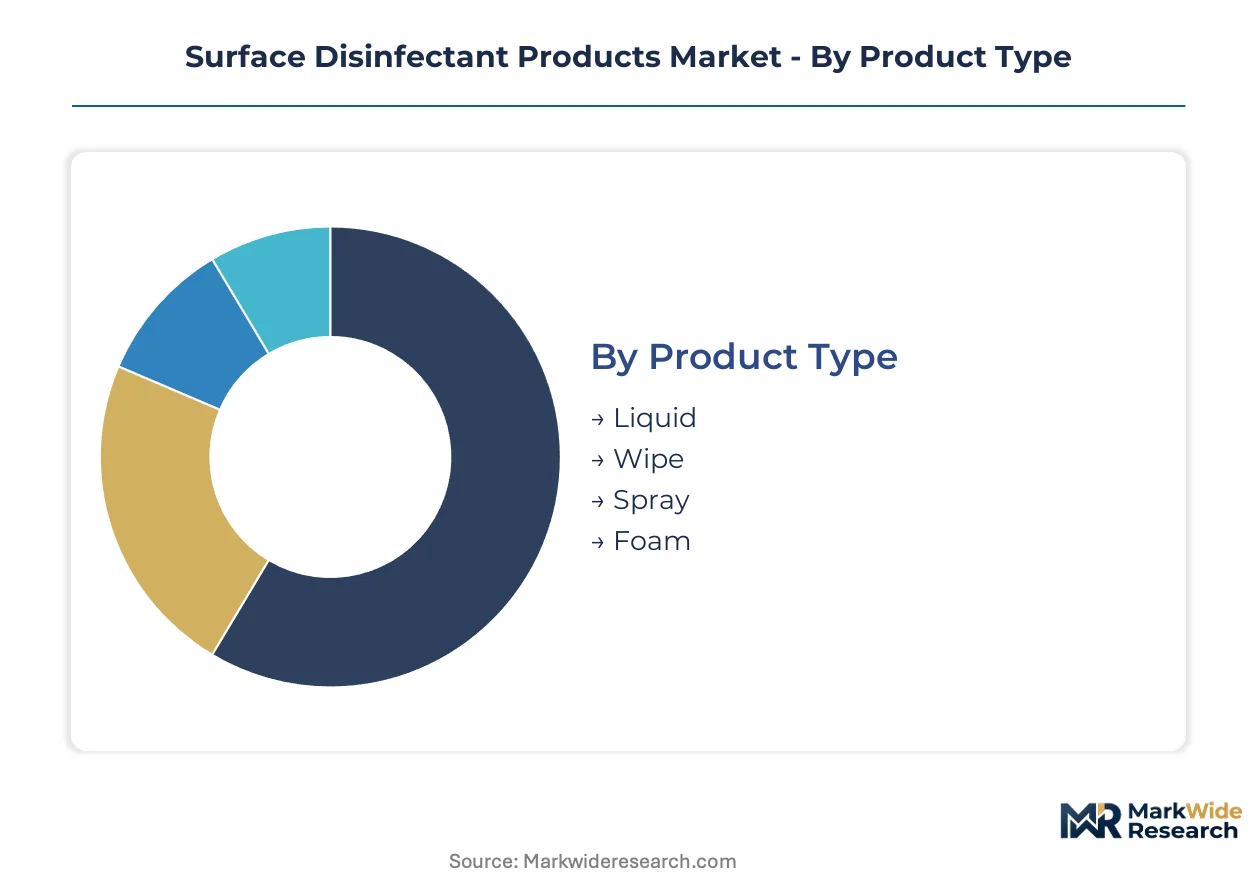
Segmentation in surface disinfectants reveals how procurement specifications diverge across institutional buyers with distinct compliance burdens and application frequencies. Understanding these divides enables suppliers to align formulation investments with the highest-velocity demand corridors.
Product Type:
Mature liquid concentrates anchor institutional procurement volumes while emerging formats reshape point-of-care workflows.
- Liquid:Concentrated chemistries delivered in bulk totes or drums dominate hospital and food processing procurement through automated dilution compatibility. Demand concentrates in acute care networks across the United States where Joint Commission audit trails mandate documented concentration verification at each use point.
- Wipe:Pre-saturated nonwoven substrates eliminate dilution error risk in clinical environments requiring immediate terminal cleaning between patients. Demand is accelerating in ambulatory surgical centers throughout Texas and Florida where staffing ratios limit on-site chemical management capacity.
- Spray:Ready-to-use trigger formulations serve intermittent disinfection needs in commercial and residential settings where equipment investment is uneconomical.
- Foam:Cling-enhanced viscosities extend contact time on vertical surfaces in industrial meat and poultry facilities with USDA inspection protocols.
Liquid retains volume leadership; wipes hold the steepest expansion curve.
Application:
Cost tiers separate regulated institutional environments from price-sensitive consumer and light commercial segments.
- Healthcare:Acute care hospitals, long-term care facilities, and outpatient clinics operate under Joint Commission and OSHA bloodborne pathogen mandates that specify product rotation, documented kill claims, and staff training protocols. EPA registration status and sporicidal efficacy against C. difficile dominate procurement scorecards.
- Commercial:Office buildings, retail spaces, and hospitality properties balance visible cleanliness with labor cost constraints. Electrolyzed water systems and contract dilution services are displacing delivered-chemical models in multi-site hotel chains seeking to eliminate on-site chemical inventory management.
- Industrial:Food processing, pharmaceutical manufacturing, and semiconductor cleanrooms require residue-free formulations compatible with validation protocols and environmental monitoring systems.
- Residential:Consumer households and small businesses purchase through retail channels where brand recognition and convenience positioning override technical specification scrutiny.
Healthcare commands premium pricing per liter; commercial applications are expanding most quickly through service bundling.
Formulation:
Supply concentration in petrochemical feedstocks creates margin volatility that reshapes competitive positioning across chemistry families.
- Alcohol-based:Ethanol and isopropanol formulations deliver rapid evaporation and broad-spectrum efficacy suited to high-turnover environments. Demand concentrates in United States emergency departments and food preparation surfaces where dwell time minimization supports patient flow and production schedules.
- Hydrogen Peroxide-based:Oxygen-release chemistries decompose to water and oxygen without persistent residues, gaining preference in respiratory-sensitive settings and cleanroom protocols. EPA's emerging pathogen framework has accelerated registration timelines for validated hydrogen peroxide blends against novel viral threats.
- Quaternary Ammonium Compounds:QACs dominate surface compatibility and cost efficiency in routine environmental cleaning across commercial and residential applications.
- Others:Peracetic acid blends, sodium hypochlorite, and emerging bio-based alternatives serve specialized sporicidal and sustainability-driven niches.
Quaternary ammonium compounds retain volume leadership; hydrogen peroxide-based alternatives are gaining share fastest through cleanroom and healthcare expansion.
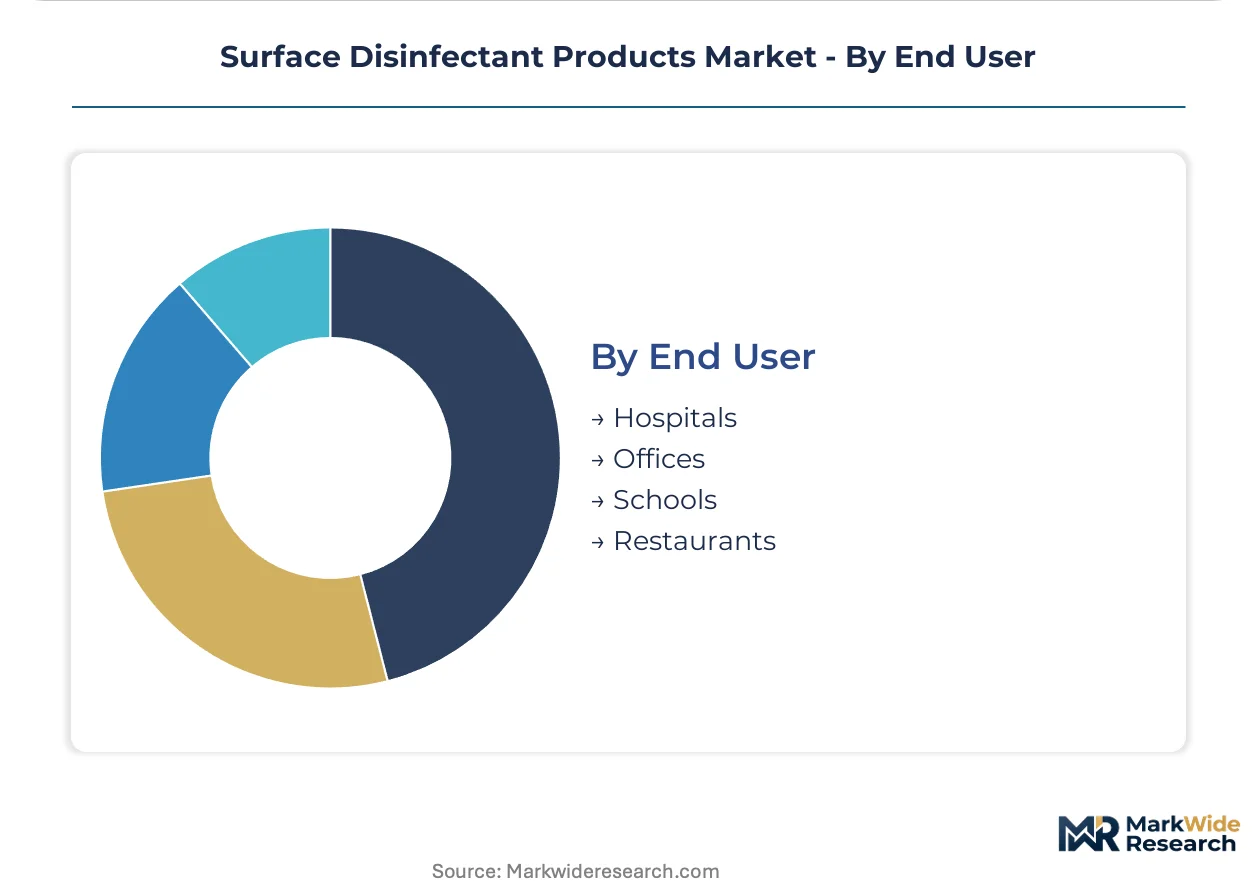
End User:
Customer type determines whether procurement flows through group purchasing organizations, facility management contractors, or retail channels.
- Hospitals:Integrated delivery networks and standalone acute care facilities purchase through GPO-negotiated contracts bundling chemical supply with compliance auditing, staff training, and electronic inventory tracking. California and New York health systems have eliminated on-site housekeeping chemical management roles entirely.
- Offices:Corporate real estate portfolios and facility management contractors prioritize total cost of application over unit chemistry costs, favoring concentrate systems with automated dilution.
- Schools:K-12 districts and higher education institutions balance budget constraints with heightened parental and regulatory scrutiny of chemical exposure in occupied spaces.
- Restaurants:Quick-service chains and independent foodservice operators navigate FDA Food Code compliance with varying technical sophistication, creating segmentation between national accounts with standardized protocols and fragmented independent operators.
Hospitals anchor institutional revenue concentration; outpatient surgical centers in high-growth states are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in surface disinfectants tilt toward domestic production in major healthcare economies, with concentrated manufacturing clusters serving regional demand corridors through integrated distribution networks rather than long-haul international trade.
United States
Joint Commission accreditation mandates and OSHA bloodborne pathogen protocols institutionalize recurring procurement cycles across acute care networks. EPA's Office of Pesticide Programs tightens efficacy documentation requirements through its emerging pathogen claims framework. Hospital procurement consolidation in California and New York health systems has eliminated on-site housekeeping chemical management roles entirely.
Germany
REACH restrictions on per- and polyfluoroalkyl substances accelerate reformulation timelines for surfactant packages ahead of 2025 authorization sunset dates. ECHA compliance burdens concentrate specification authority among manufacturers with dedicated regulatory affairs capabilities. The Baden-Württemberg industrial corridor hosts specialized chemical formulators serving pharmaceutical cleanroom protocols.
China
Domestic healthcare infrastructure expansion and food processing automation standardize chemical delivery infrastructure that locks in volume contracts. SAMR registration requirements for disinfectant efficacy claims create procedural friction for imported formulations. The Yangtze River Delta manufacturing belt concentrates quaternary ammonium compound production for regional supply.
India
Bureau of Indian Standards certification requirements and CDSCO medical device regulations shape import substitution strategies for hospital-grade formulations. Central government procurement through the Health Ministry's rate contracts favors domestic manufacturers with established distribution. Maharashtra's chemical manufacturing cluster around Mumbai supplies concentrate formulations to western and southern hospital networks.
Japan
METI industrial standards and PMDA medical device regulations impose stringent residue and compatibility testing for healthcare applications. Aging demographic pressures expand long-term care facility construction with associated infection prevention protocols. The Kanto region surrounding Tokyo anchors demand concentration for hydrogen peroxide-based alternatives in respiratory-sensitive clinical settings.
Surface Disinfectant Products Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct competitive tiers: multinational chemical conglomerates with integrated hygiene programs, mid-tier specialists leveraging contract manufacturing flexibility, and private-label assemblers competing on procurement cost. Strategic archetypes include the bundled-service anchor, the asset-light challenger, and the retail brand equity holder. Dominant competitive moves encompass M&A activity targeting compliance software platforms and capacity expansion in automated dilution system compatibility.
Within the bundled-service tier, Ecolab anchors institutional presence through integrated hygiene programs, while Reckitt Benckiser Group PLC exemplifies retail brand equity leverage across North American and European pharmacy channels. Diversey Holdings occupies a position among mid-tier specialists with concentrated foodservice and hospitality sector exposure.
| Leading Market Players |
|---|
| Reckitt Benckiser Group PLC |
| Procter & Gamble |
| 3M |
| Ecolab |
| The Clorox Company |
| SC Johnson |
| GOJO Industries, Inc. |
| STERIS |
| Diversey Holdings |
| Others |
Value Network & Pricing Analysis
Quaternary ammonium compound production concentrates in the Yangtze River Delta manufacturing belt and Gulf Coast petrochemical corridors, anchoring margin capture with integrated formulators while forcing mid-tier competitors into toll-manufacturing arrangements with compressed pricing power.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across food processing and healthcare networks. Three-tier pricing structure across premium, standard, and economy levels separates EPA-registered sporicidal formulations from commodity QAC concentrates and private-label alternatives. Cost compression in mid-tier supply is intensifying because hospital procurement consolidation demands bundled compliance services without proportional price tolerance. Quick-service restaurant chains exhibit highest price sensitivity due to thin operating margins, whereas acute care networks prioritize kill-claim validation over unit cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Lonza, Croda, and regional toll blenders serving private-label assemblers and mid-tier brands. Raw material sourcing draws from Chinese petrochemical derivatives, Indian surfactant intermediates, and domestic ethanol production. Single-source vulnerability runs through QAC feedstock suppliers with limited qualified alternatives for EPA-compliant formulations. Distribution runs through group purchasing organization networks and third-party dilution service providers that displace direct chemical delivery in multi-site health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-light manufacturing and private-label leasing fragment competitive tiers, creating entry niches for specialists targeting compliance-bundled service gaps as hospital procurement eliminates on-site chemical management roles.
For Market Incumbents: Harden integrated hygiene programs by acquiring compliance software platforms for automated audit logging and electronic inventory tracking. Deepen backward integration into QAC feedstock production to insulate margins from petrochemical volatility. Electrolyzed water on-site generation systems represent the most pressing substitute technology threat requiring monitoring. For New Entrants and Emerging Players: Ambulatory surgical centers in Texas and Florida represent the most penetrable entry point given construction velocity outpacing regional supply and limited staffing for chemical management. Outpatient clinics in high-growth Sun Belt metros offer secondary white-space with lower compliance documentation burdens than acute care. A go-to-market angle combining EPA-registered formulations with third-party dilution service partnerships bypasses capital-intensive infrastructure requirements. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists with concentrated foodservice and hospitality sector exposure and established contract manufacturing relationships. Long-term viability over the next decade hinges on regulatory affairs capabilities navigating EPA emerging pathogen frameworks and REACH surfactant restrictions. The signal to watch is GPO specification authority centralization accelerating consolidation among non-integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into QAC Feedstock | Captive supply of quaternary ammonium precursors insulates margin compression from petrochemical derivative volatility. |
| Compliance Software Platform Acquisition | Automated audit logging capabilities lock in hospital contract renewal rates through Joint Commission documentation requirements. |
| Electrolyzed Water System Partnership | On-site generation convergence with IoT monitoring displaces delivered-chemical models in hospitality chain accounts. |
| Regional Dilution Service Expansion | Third-party concentrate blending in Texas and Florida captures ambulatory surgical center construction velocity. |
| REACH-Compliant Surfactant Reformulation | Per- and polyfluoroalkyl substance substitution ahead of authorization sunset dates preserves European market access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement directors, EPA regulatory affairs consultants, GPO contracts managers, and food processing plant engineers. Secondary validation incorporated EPA Office of Pesticide Programs registration databases, Joint Commission accreditation standards, customs trade data on QAC imports, and SEC 10-K disclosures from listed chemical manufacturers. Bottom-up volume modeling across product type, application, and formulation segments was triangulated against top-down healthcare expenditure and food processing capacity indicators.
Calibration against historical EPA registration timelines and hospital procurement cycle data informed growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product format, end-use industry, active chemistry family, and regional regulatory cluster. CAGRs were derived from weighted average growth contributions across these segments. Industry-specific inputs incorporated Joint Commission audit frequency standards and automated dilution system installation rates in meat and poultry facilities.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, hospital capital expenditure cycles, or EPA registration timeline friction would shift the trajectory. Quarterly review of GPO contract award announcements, EPA emerging pathogen claim approvals, and ambulatory facility construction permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
Hypochlorite Bleaches Market
Disinfectants and Preservatives
Aerosol Disinfectants Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
Disinfecting Wipes Market
Disinfectants and Preservatives
Global Animal Disinfectants Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
Global Fusidic Acid Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Disinfectant Fogging and Misting Chemicals for Large Facilities Market