
 Fluorine Derivatives Market | 2026-2036
Fluorine Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorine Derivatives Market Foresight
Market Context
The gap between high-purity fluoropolymers for semiconductor etching and commodity hydrofluoric acid for industrial cleaning is shifting from a price spread into a capability chasm. Chemours leverages its vertical integration from fluorspar mining to finished polymer resin to sustain margin capture across the value chain. Arkema differentiates through specialty fluoroelastomer grades that dominate aerospace sealing applications where certification barriers block commodity entrants.
Technical Definition and Segment Structure
Fluorine derivatives encompass organic and inorganic compounds synthesized by substituting hydrogen with fluorine, yielding carbon-fluorine bonds with bond dissociation energies near 485 kJ/mol that confer chemical inertness, thermal stability, and dielectric performance. These properties make them indispensable for plasma-resistant chamber linings, refrigerant working fluids, and crop protection active ingredients. Fluoropolymers anchor the value pool due to their irreplaceability in sub-7 nanometer semiconductor lithography, while fluorochemicals compete on scale in refrigerant and aluminum smelting markets where regulatory phase-downs are accelerating product turnover. Organofluorine compounds occupy the fastest-expanding niche as agrochemical patent cliffs drive generic fluorinated pesticide production in India and China.
Regulatory Frame and Outlook
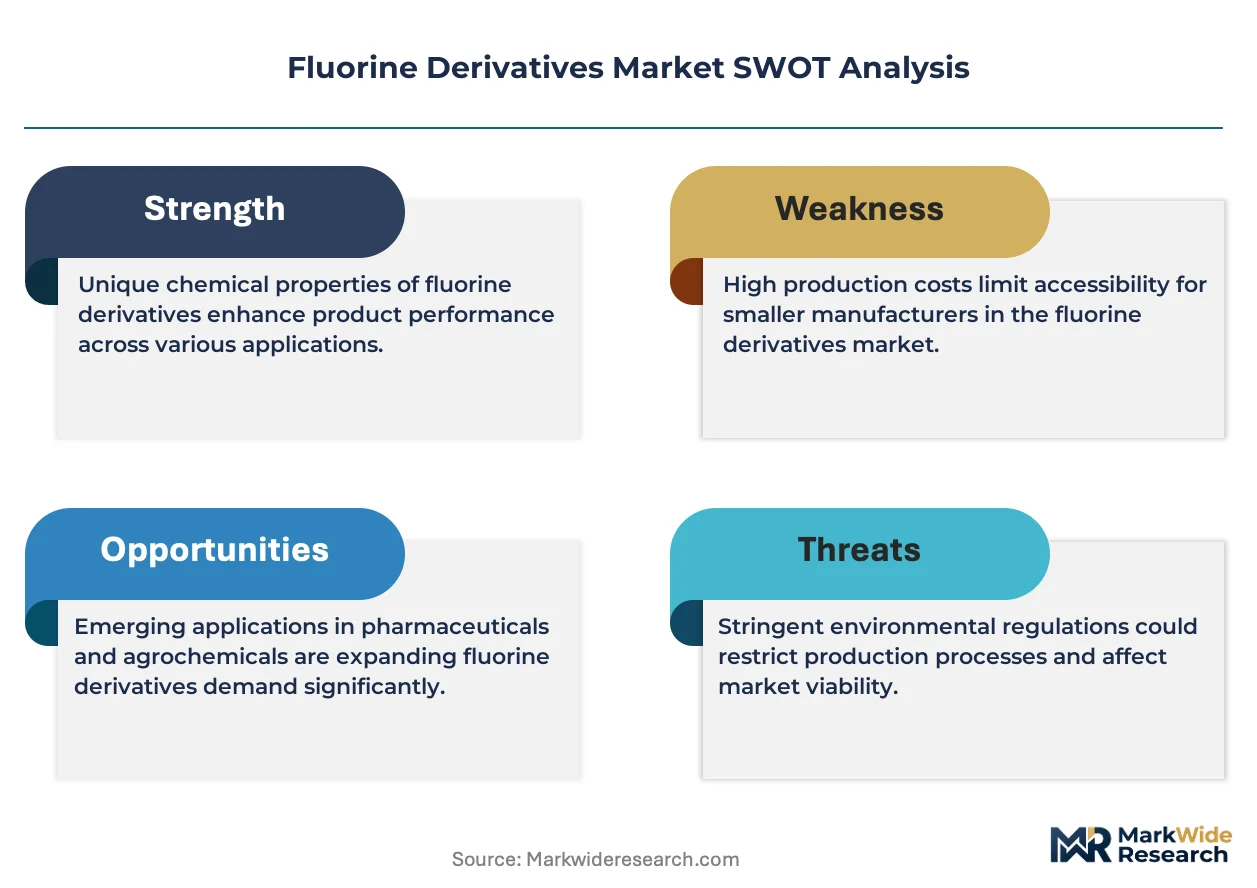
The EPA Significant New Alternatives Policy program and EU F-Gas Regulation are restricting hydrofluorocarbon production quotas, forcing refrigerant manufacturers to reformulate around hydrofluoroolefins and natural alternatives. China's Ministry of Ecology and Environment enforces dual carbon goals that cap perfluorocarbon emissions from aluminum and electronics manufacturing, tightening feedstock availability for derivative producers. Stakeholders must monitor how rapidly evolving national ozone-depleting substance inventories and carbon border adjustment mechanisms will reshape cost-competitive sourcing geography for fluorinated intermediates.
Market Dynamics
Semiconductor fabricators are consuming fluoropolymers at unprecedented purity grades, while refrigerant phase-down mandates simultaneously compress legacy hydrofluorocarbon volumes and redirect capital toward low-GWP molecule development. This dual-track demand structure—irreplaceable high-performance materials alongside regulated commodity turnover—defines competitive positioning.
Growth Catalysts
- Sub-7 nanometer lithography:Chip manufacturers require plasma-resistant fluoropolymer chamber components that withstand aggressive etching chemistries, creating captive demand for ultra-high-purity PTFE and PFA grades.
- EU F-Gas Regulation phase-down:Refrigerant manufacturers must reformulate around hydrofluoroolefins with GWP below 150, accelerating product turnover and equipment replacement cycles.
- China electronics manufacturing concentration:Domestic fluorochemical capacity expansion serves both local semiconductor fabrication and export markets, consolidating supply geography.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar mining concentrates in China, Mexico, and Mongolia, exposing derivative producers to export quota volatility and geopolitical friction.
- Perfluorocarbon emission caps:China's Ministry of Ecology and Environment enforces dual carbon goals that limit feedstock availability for tetrafluoromethane and hexafluoroethane production.
- Process energy intensity:Electrochemical fluorination and Halex reactions require substantial electricity input, compressing margins where carbon border adjustment mechanisms apply.
Strategic Opportunities
- India agrochemical genericization:Patent cliffs on fluorinated fungicides and herbicides drive contract manufacturing demand for trifluoromethyl-substituted active ingredients.
- Fluoroelastomer aerospace certification:FAA and EASA material qualification requirements for sealing applications create multi-year incumbency advantages for approved suppliers.
- Closed-loop refrigerant recovery:Extended producer responsibility frameworks in the EU and California mandate reclamation infrastructure investment, opening service revenue streams.
Industry Challenges
- High-purity polymer processing expertise:Semiconductor-grade fluoropolymer production requires cleanroom extrusion capabilities and metallic contamination control that few compounders possess.
- Multi-jurisdictional substance inventories:Registration requirements under REACH, TSCA, and China's MEE chemical management system impose parallel compliance burdens with divergent data requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorine Derivatives Market |
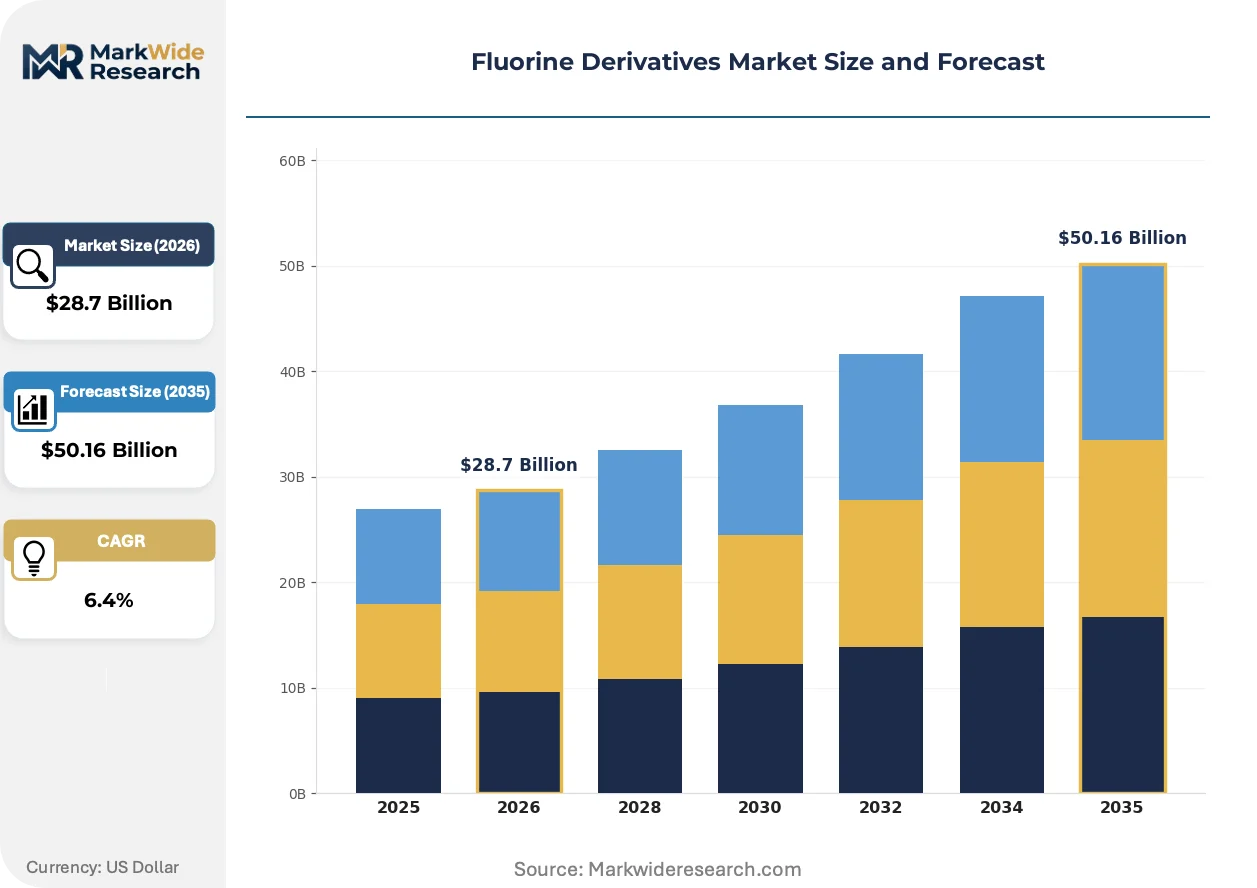
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoropolymers, Fluorochemicals, Fluoroelastomers, Organofluorine Compounds, Inorganic Fluorides Application: Pharmaceuticals, Agrochemicals, Electronics, Refrigerants, Metallurgy End User Industry: Specialty Chemicals Manufacturers, Crop Protection Firms, Semiconductor Fabricators, Pharmaceutical Producers Packaging Type: Drums, Cylinders, Bags, Containers |
| Companies Covered | Chemours, Navin Fluorine International, Arkema, Juhua Group, Dongyue Group, Solvay, Gujarat Fluorochemicals, Honeywell, Daikin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorine Derivatives Market Shifts & Advancements
Fluorine derivative markets are bifurcating between irreplaceable high-performance materials commanding technical premiums and regulated commodity chemistries facing forced substitution timelines. This tension accelerates R&D allocation toward next-generation molecules.
Atomic layer deposition precursors containing fluorinated ligands are rewriting semiconductor equipment specifications. Memory and logic chip fabricators in Taiwan and South Korea specify these chemistries for conformal dielectric films at sub-5 nanometer nodes. The technology is compressing equipment qualification cycles from 18 months to under 9 months as node transitions accelerate.
The EPA Significant New Alternatives Policy program and EU F-Gas Regulation are compressing hydrofluorocarbon production quotas through 2030. Refrigerant blenders must pivot formulation portfolios toward hydrofluoroolefins and natural alternatives with minimal GWP. Stationary air conditioning and commercial refrigeration equipment manufacturers in the US Southeast and Mediterranean Europe face the steepest retrofit and redesign requirements.
After-sales refrigerant recovery and reclamation is unbundling from equipment sales as a standalone service line. HVAC distributors in Germany and California are acquiring reclamation assets to capture recurring revenue from mandatory recovery mandates. This behavioral shift is most visible in commercial rooftop and industrial process cooling segments where refrigerant charge volumes justify dedicated logistics infrastructure.
Fluorine Derivatives Market Segmentation
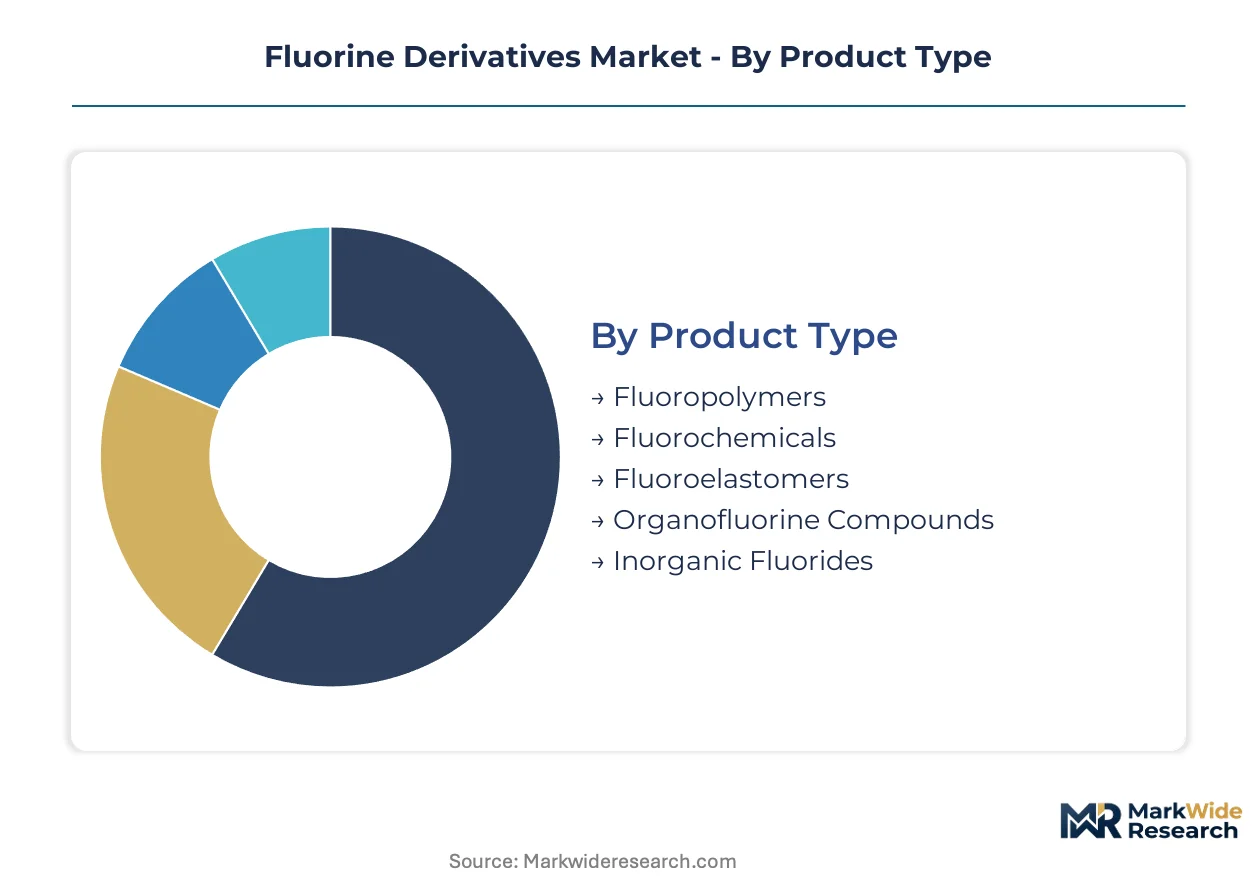
Fluorine derivative markets fragment along technical performance tiers rather than commodity grades. Semiconductor fabricators, agrochemical formulators, and refrigerant blenders each impose distinct purity, regulatory, and handling specifications that reshape supplier economics across every segment.
Product Type:
Replacement cycles for legacy fluorinated materials are accelerating as regulatory phase-downs force equipment turnover and chip lithography advances demand next-generation polymer grades.
- Fluoropolymers:Carbon-fluorine bond dissociation energies near 485 kJ/mol deliver plasma resistance for sub-7 nanometer semiconductor etching chambers. Taiwan and South Korea fabrication facilities specify ultra-high-purity PTFE and PFA grades where metallic contamination tolerances sit below parts-per-billion thresholds.
- Fluorochemicals:Hydrofluorocarbon and hydrofluoroolefin working fluids dominate refrigerant and aluminum smelting applications. The EU F-Gas Regulation compresses production quotas for high-GWP molecules while redirecting capital toward low-GWP alternatives with global warming potential below 150.
- Fluoroelastomers:Aerospace sealing applications require FAA and EASA material qualification that blocks commodity entrants.
- Organofluorine Compounds:Trifluoromethyl-substituted active ingredients serve crop protection patent cliffs in India and China.
- Inorganic Fluorides:Acid-grade fluorspar derivatives supply aluminum electrolysis and industrial cleaning markets.
Volume placements concentrate in fluorochemicals serving refrigerant and metallurgy base demand; the faster expansion belongs to fluoropolymers capturing semiconductor fabrication intensity.
Application:
Cost tier differentiation separates premium-specification electronics and pharmaceutical grades from commodity metallurgy and mass-market refrigerant volumes.
- Electronics:Atomic layer deposition precursors with fluorinated ligands enable conformal dielectric films at sub-5 nanometer nodes. Equipment qualification cycles compress from 18 months to under 9 months as Taiwan and South Korea logic chip fabricators accelerate node transitions.
- Refrigerants:Stationary air conditioning and commercial refrigeration equipment in the US Southeast and Mediterranean Europe face steep retrofit mandates under EPA SNAP and EU F-Gas Regulation phase-down schedules.
- Agrochemicals:Fluorinated fungicide and herbicide generics drive contract manufacturing demand.
- Pharmaceuticals:Fluorine substitution modulates metabolic stability and bioavailability in small-molecule drug candidates.
- Metallurgy:Aluminum smelting consumes inorganic fluorides for electrolytic bath chemistry.
Electronics commands the steepest price premiums; agrochemicals gain share fastest as patent expirations accelerate generic production.
End User Industry:
Customer type determines specification stringency, with semiconductor fabricators imposing metallic contamination controls that few compounders can satisfy.
- Semiconductor Fabricators:Cleanroom extrusion capabilities and parts-per-billion metallic contamination control requirements create multi-year supplier qualification barriers.
- Crop Protection Firms:India and China contract manufacturers scale trifluoromethyl-substituted active ingredient production as proprietary agrochemical patents expire.
- Specialty Chemicals Manufacturers:Refrigerant blenders reformulate portfolios around hydrofluoroolefins to meet EPA SNAP and EU F-Gas Regulation mandates.
- Pharmaceutical Producers:Fluorinated intermediates serve late-stage drug candidate synthesis where fluorine substitution enhances metabolic stability.
Procurement concentration sits with semiconductor fabricators; crop protection firms expand fastest as generic manufacturing migrates to India and China.
Packaging Type:
Handling requirements track hazard classification, with toxic and pressurized fluorinated materials demanding specialized containment that elevates logistics costs above commodity chemical norms.
- Cylinders:Pressurized hydrofluorocarbon and hydrofluoroolefin refrigerants require DOT and ADR-certified pressure vessels for transport and storage.
- Drums:Liquid fluorochemicals and polymer resins ship in standard industrial packaging with corrosion-resistant linings.
- Containers:Bulk inorganic fluorides move in intermediate bulk containers for aluminum smelter feedstock delivery.
- Bags:Powdered fluoropolymer resins package in moisture-barrier flexible containers.
Cylinder utilization dominates refrigerant logistics; bag shipments expand fastest with fluoropolymer compounding scale-up in China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taoyuan City anchors fluoropolymer demand through Taiwan Semiconductor Manufacturing Company's advanced packaging complexes. Hsinchu Science Park fabricators specify ultra-high-purity PTFE grades for sub-7 nanometer etching chambers. This concentration pattern repeats across four additional national manufacturing centers.
United States
Semiconductor fabricators in Arizona and Texas consume plasma-resistant fluoropolymers for advanced logic chip production. The EPA Significant New Alternatives Policy program restricts hydrofluorocarbon refrigerant quotas through 2030. Phoenix and Austin metropolitan clusters host Intel and Samsung expansion projects requiring captive fluorochemical supply.
China
Domestic fluorochemical capacity serves both local electronics manufacturing and export markets. The Ministry of Ecology and Environment enforces dual carbon goals that cap perfluorocarbon emissions from aluminum smelting. Yangtze River Delta chemical parks concentrate PTFE and PFA resin production for semiconductor and battery applications.
Germany
Commercial refrigeration equipment manufacturers face steep retrofit mandates under EU F-Gas Regulation phase-down schedules. ECHA registration requirements impose parallel compliance burdens for fluorinated intermediate imports. Rhineland chemical corridors host refrigerant blending facilities pivoting toward hydrofluoroolefin formulations.
Japan
Memory and logic chip fabricators specify atomic layer deposition precursors with fluorinated ligands for conformal dielectric films. METI industrial policy supports domestic fluoropolymer production for semiconductor equipment supply chains. Kyushu and Hiroshima prefectures concentrate advanced packaging facilities driving specialty fluorochemical consumption.
India
Patent cliffs on fluorinated fungicides and herbicides drive contract manufacturing demand for trifluoromethyl-substituted active ingredients. BIS quality standards regulate agrochemical intermediate imports. Gujarat chemical estates scale generic fluorinated pesticide production for export to African and Southeast Asian markets.
Fluorine Derivatives Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-grade capabilities in fluoropolymer compounding. The vendor base stratifies between integrated miners-to-resin producers, specialty fluoroelastomer compounders, and regional refrigerant blenders. Three archetypes dominate: captive supply chain controllers, certification-anchored aerospace specialists, and scale-driven agrochemical intermediates suppliers. Competitive moves center on backward integration into acid-grade fluorspar mining and cleanroom extrusion capacity expansion for semiconductor-grade resin production.
Among North American integrated producers, Chemours and Honeywell occupy positions spanning mining through finished polymer resin. Arkema exemplifies the specialty fluoroelastomer tier where regulatory certification creates multi-year incumbency barriers. Chinese state-affiliated entities including Juhua Group and Dongyue Group represent scale-driven capacity expansion archetypes serving domestic electronics manufacturing clusters.
| Leading Market Players |
|---|
| Chemours |
| Navin Fluorine International |
| Arkema |
| Juhua Group |
| Dongyue Group |
| Solvay |
| Gujarat Fluorochemicals |
| Honeywell |
| Daikin |
| Others |
Supply & Pricing Matrix
China's dual carbon goals enforced by the Ministry of Ecology and Environment gate both qualified acid-grade fluorspar supply and premium-tier fluoropolymer pricing access, compressing feedstock availability for derivative producers while semiconductor fabricators absorb escalating resin costs for sub-7 nanometer lithography chambers.
Pricing Analysis
Yield-guaranteed uptime pricing anchors semiconductor-grade fluoropolymer contracts, with fabricators in Taiwan and South Korea paying technical premiums for parts-per-billion metallic contamination control. Price differentiation separates cleanroom-extruded PTFE and PFA grades from commodity resin tiers, while certification barriers for aerospace fluoroelastomers sustain incumbent premiums. Pricing pressure stems from carbon border adjustment mechanisms applying to electrochemical fluorination energy inputs. Refrigerant blenders exhibit highest price sensitivity as EU F-Gas Regulation phase-downs compress hydrofluorocarbon margins.
Supply Chain Analysis
Refrigerant recovery and reclamation flows are unbundling from equipment sales as standalone service revenue streams, with HVAC distributors in Germany and California acquiring dedicated logistics infrastructure. Acid-grade fluorspar mining concentrates in China, Mexico, and Mongolia, exposing derivative producers to export quota volatility. Tetrafluoromethane and hexafluoroethane feedstock availability hinges on perfluorocarbon emission caps. Single-source vulnerability concentrates in Chinese state-affiliated fluorspar-to-resin integrated producers. Distribution runs through regional refrigerant blending facilities and semiconductor chemical distribution networks serving fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acid-grade fluorspar export quota volatility from China props fluoropolymer pricing, creating supply-constrained conditions that favor incumbents with captive mining assets and qualified cleanroom extrusion capabilities.
For Market Incumbents: Anchor backward integration into Mongolian and Mexican fluorspar mining concessions to diversify feedstock exposure beyond Chinese export quotas. Expand cleanroom extrusion capacity in Taiwan and Arizona to capture Intel and Samsung expansion projects. Certification investment for FAA and EASA fluoroelastomer qualifications blocks commodity entrants from aerospace sealing markets. For New Entrants and Emerging Players: The mid-tier pricing gap between semiconductor-grade fluoropolymers and commodity refrigerant chemicals offers white-space targeting for India-based contract manufacturers scaling trifluoromethyl-substituted agrochemical intermediates. Gujarat chemical estates provide penetrable geography for generic fluorinated pesticide production serving African and Southeast Asian export markets. Joint venture structures with established refrigerant blenders accelerate hydrofluoroolefin formulation portfolio pivots. For Investors and Strategic Acquirers: Taiwan Semiconductor Manufacturing Company's advanced packaging capacity announcements are the leading indicator that fluoropolymer demand intensity will sustain through sub-5 nanometer node transitions. Acquisition targets should prioritize specialty fluoroelastomer compounders with multi-year FAA and EASA material qualifications that create incumbency barriers. Monitor China's Ministry of Ecology and Environment perfluorocarbon emission enforcement actions for feedstock availability inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Mongolian and Mexican mining concessions reduce Chinese export quota exposure for derivative producers. |
| Cleanroom Extrusion Capacity Expansion | Arizona and Taiwan facilities capture Intel and Samsung semiconductor fabrication cluster demand. |
| Hydrofluoroolefin Formulation Pivot | EU F-Gas Regulation phase-down mandates redirect refrigerant blender portfolios toward sub-150 GWP molecules. |
| Refrigerant Recovery Infrastructure Acquisition | German and California distributors capture mandatory reclamation service revenue under extended producer responsibility frameworks. |
| Aerospace Fluoroelastomer Certification Investment | FAA and EASA material qualifications create multi-year incumbency barriers blocking commodity competitors. |
Research Methodology
Document review covered SEC 10-K filings from fluorochemical producers, EU F-Gas Regulation quota tracking databases, and Chinese Ministry of Ecology and Environment emission disclosure reports, complemented by interviews with semiconductor fabrication plant managers, refrigerant procurement leads at HVAC OEMs, and specialty chemical distribution channel partners. Secondary validation drew from customs trade data, American Chemistry Council sector reports, and Taiwan Semiconductor Industry Association capacity announcements. Bottom-up and top-down triangulation reconciled resin volume estimates with fabrication equipment installation data.
Segment-level value outputs across the projection horizon reflect modeled interactions between purity grade tiers, end-use industry concentration, and regional regulatory cluster stringency. The analytical framework incorporated fluoropolymer grade specifications, refrigerant GWP transition timelines, and agrochemical patent expiration schedules as industry-specific forecast inputs. CAGRs were derived from regression against semiconductor node transition acceleration rates and aluminum smelter perfluorocarbon emission cap trajectories.
Inputs from Chinese customs fluorspar export records and Taiwan fabrication equipment procurement databases were available through the study window; gaps in real-time perfluorocarbon emission verification introduce uncertainty bands around tetrafluoromethane and hexafluoroethane feedstock availability assumptions. Forecasts reflect documented regulatory phase-down schedules and announced capacity expansion timelines. Practitioners should monitor China Ministry of Ecology and Environment enforcement actions and Taiwan Semiconductor Manufacturing Company capital expenditure disclosures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Phosgene Market
Chemicals
Superplasticizer Market
Chemicals
Thiourea Market
Chemicals
Europe Biguanide Market
Chemicals
Bronopol Market
Chemicals
Methanol Market
Chemicals
Etidronic Acid Market
Chemicals
Copper Oxychloride Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
3-Dimethylacrylic Acid Methyl Ester Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
White Phosphorus Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
N-Propanol Market
Chemicals
Chlorosilane Market