
 Detergent Making Machinery Market | 2026-2036
Detergent Making Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Detergent Making Machinery Market Analysis
The gap between mechanical mixing and fully integrated continuous processing is narrowing as detergent makers pursue energy recovery and real-time viscosity control. Jinzong Machinery leverages its reactor-engineering heritage to anchor high-volume spray drying lines for Asian manufacturers. Zhangjiagang Keyuan Machinery specializes in modular batch systems that let mid-tier producers reconfigure lines between liquid and powder formats.
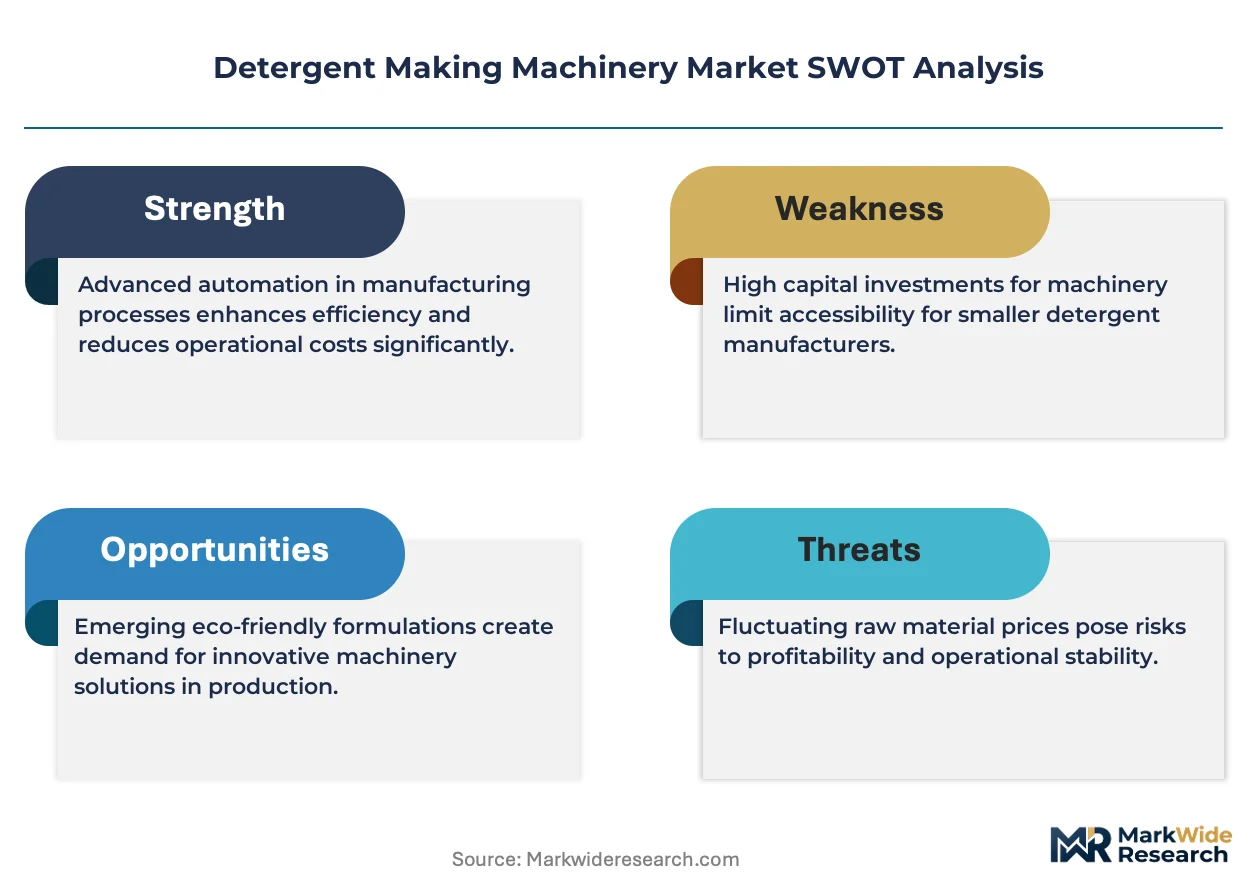
Detergent making machinery encompasses reactors, homogenizers, spray dryers, and filling systems engineered to handle surfactant slurries with viscosities ranging from 500 to 50,000 centipoise, operating at temperatures up to 180°C to drive solvent evaporation and particle formation. Continuous process equipment leads capital deployment among large-scale producers seeking throughput above ten metric tons per hour, while biological technology segments gain traction as enzyme-stable processing becomes essential for cold-water detergent formulations. Mixing equipment occupies the broadest addressable base, serving both artisanal manufacturers and industrial compounders with standardized vessel configurations.
EPA effluent guidelines and REACH chemical restrictions are reshaping equipment specifications, compelling stainless steel construction upgrades and closed-circuit cooling architectures to contain surfactant runoff. FDA oversight of cleaning agents used in food-processing facilities further segments demand toward sanitary-design machinery with clean-in-place capability. Stakeholders must weigh capital intensity against regulatory exposure when selecting between batch flexibility and continuous scale.
Market Dynamics
Equipment manufacturers face mounting pressure to integrate real-time viscosity control with energy recovery systems as detergent formulators pivot from batch to continuous processing architectures.
Growth Catalysts
- REACH chemical restrictions:European formulators are replacing legacy surfactants with biodegradable alternatives, forcing equipment retrofits that handle shear-sensitive enzyme slurries without denaturation.
- India's PLI scheme for chemical manufacturing:Domestic brands and contract manufacturers are scaling local production, creating demand for modular spray drying and filling lines that accommodate both powder and liquid formats.
- Cold-water detergent formulations:Enzyme-stable processing equipment is capturing investment as consumer preference for low-temperature washing spreads across Asian and European markets.
Market Restraints
- Stainless steel price volatility:316L grade construction mandates under EPA effluent guidelines expose fabricators to nickel and molybdenum input cost swings that compress project margins.
- German component supplier concentration:Precision pump and homogenizer subsystems rely on a narrow base of Mittelstand specialists, creating lead time vulnerability for Asian turnkey integrators.
- Closed-loop cooling technical ceiling:Surfactant recovery rates above 98.5 percent remain elusive in pilot installations, capping regulatory compliance premiums for early adopters.
Strategic Opportunities
- Indonesia's underpenetrated SME tier:Artisanal detergent producers in Surabaya and Medan lack access to standardized mixing vessels, creating a channel for skid-mounted batch systems with local language interfaces.
- Food-processing sanitation standards:FDA oversight of cleaning agents used in dairy and meat facilities segments demand toward sanitary-design machinery with clean-in-place capability and 3A certification.
- Hybrid powder-liquid lines:Modular reactor configurations that reconfigure between surfactant slurry and spray-dried granule production are capturing interest from contract manufacturers serving multiple brand portfolios.
Industry Challenges
- Process control engineering talent scarcity:Integration of real-time rheology sensors with programmable logic controllers demands cross-trained automation specialists that machine builders struggle to recruit in Pune and Shanghai industrial zones.
- Legacy DCS migration complexity:Brownfield detergent plants running 1990s-era distributed control systems face protracted validation timelines when retrofitting continuous processing skids that require Ethernet-IP connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Detergent Making Machinery Market |
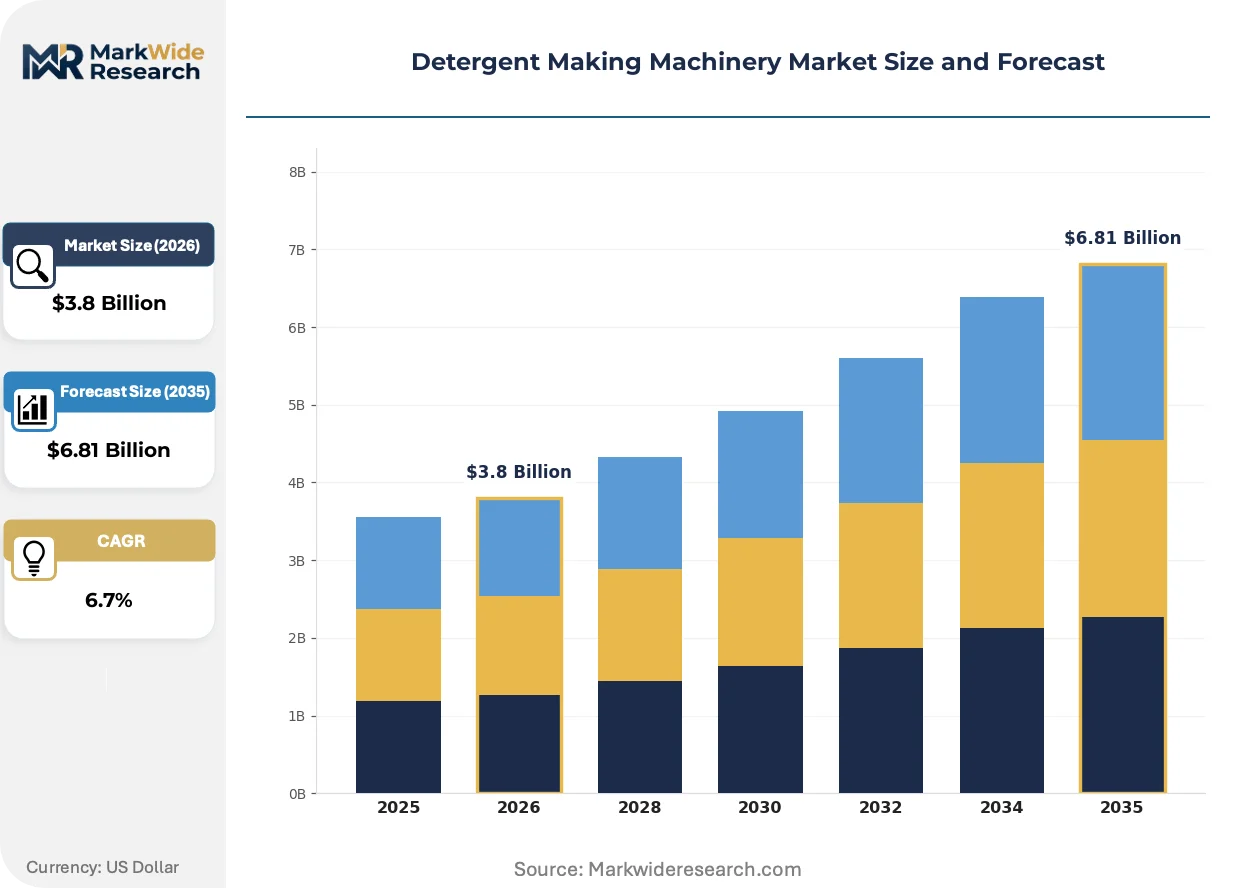
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Process, Continuous Process, Spray Drying, Mixing Equipment Technology: Mechanical, Chemical, Biological, Thermal Application: Household Cleaning, Industrial Cleaning, Institutional Cleaning, Specialty Cleaning End User: Manufacturers, Retailers, Distributors, Wholesalers |
| Companies Covered | Jinzong Machinery, Zhangjiagang Keyuan Machinery, Wuxi Transtek Machinery, Shanghai Genyond Machinery, Guangzhou Jinzong Machinery, Fei Lun Packing Machinery, Angelon Chemistry Machinery, Botou Xianfa, Changzhou Terry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Detergent Making Machinery Market Emerging Trajectories
Active transformation in detergent machinery centers on converging digital process control with materials handling architectures originally developed in adjacent chemical processing sectors.
Continuous spray drying technology is hybridizing with reactor-engineering principles borrowed from pharmaceutical active ingredient production. Large-scale Asian manufacturers are adopting these integrated lines to consolidate solvent evaporation, particle formation, and classification into single-pass architectures. This convergence compresses capital intensity per ton of finished detergent while tightening residence time distribution control.
EPA effluent guidelines and REACH chemical restrictions are mandating stainless steel construction upgrades and closed-circuit cooling architectures. Equipment fabricators must now certify containment performance for surfactant runoff across entire production trains. European formulators are responding fastest, specifying 316L electropolished surfaces and zero-liquid-discharge auxiliary systems that recover process water for reuse.
Buyer preference for concentrated and unit-dose detergent formats is rotating demand toward precision dosing and packaging integration. Brand owners in Germany and Japan are unbundling after-sales service contracts, selecting machinery vendors on throughput flexibility rather than bundled maintenance terms. This procurement pattern shifts margin capture toward spare parts and remote diagnostics subscriptions.
Detergent Making Machinery Market Segmentation
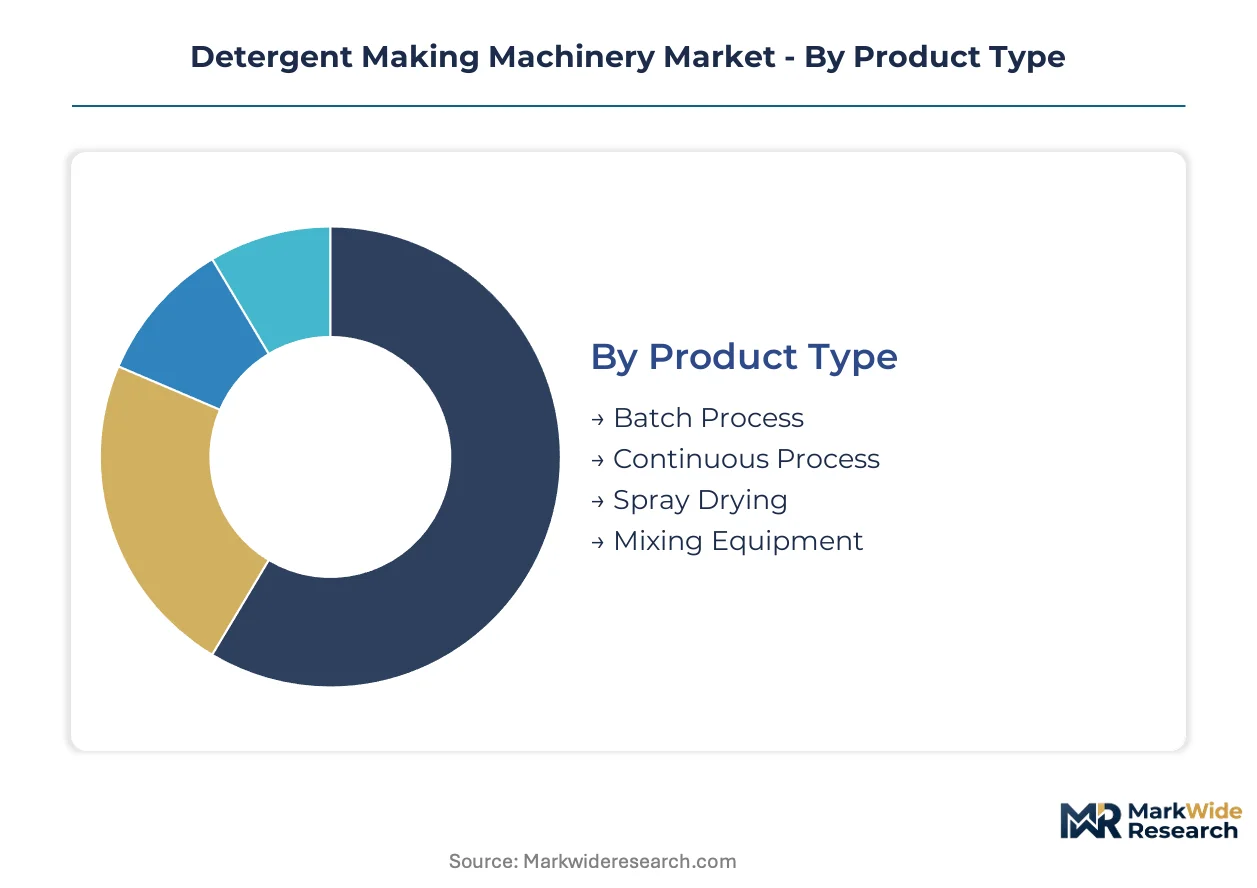
Detergent machinery purchasing cycles vary dramatically by process architecture, with batch systems turning over every 12-15 years while continuous lines demand capital refresh within 7-10 years. Understanding these velocity differences helps suppliers align inventory, service contracts, and upgrade roadmaps to actual replacement timing.
Product Type:
Cycle time separates this category sharply: batch vessels and mixing equipment operate on decade-plus replacement horizons, whereas continuous process lines and spray drying systems compress procurement cycles through faster technology obsolescence and throughput expansion demands.
- Batch Process:Jacketed reactors and agitated vessels handle surfactant slurries in discrete production cycles, accommodating viscosity swings from 500 to 50,000 centipoise. Demand concentrates among Indian SME manufacturers scaling under the PLI scheme for chemical manufacturing, where modular batch lines allow format flexibility between powder and liquid detergents. Equipment margins here face pressure from stainless steel price volatility affecting 316L grade construction mandates.
- Continuous Process:Integrated reactor-dryer-classifier architectures consolidate solvent evaporation and particle formation into single-pass systems operating above ten metric tons per hour. Large-scale Asian manufacturers in Indonesia and Vietnam deploy these lines to compress capital intensity per ton while tightening residence time distribution control for concentrated detergent formats.
- Spray Drying:Tower systems atomize surfactant slurries against heated air streams to produce granular detergents with controlled particle size distribution. These units dominate powder detergent production in established European markets facing REACH chemical restrictions on legacy surfactant formulations.
- Mixing Equipment:Standardized vessel configurations serve artisanal manufacturers and industrial compounders across the broadest addressable base. Surabaya and Medan producers in Indonesia's underpenetrated SME tier represent untapped demand for skid-mounted batch systems with local language interfaces.
Batch Process dominates installed base. Continuous Process is where expansion concentrates.
Technology:
Cost tier stratification shapes procurement patterns: mechanical and thermal systems occupy economy and standard price bands with mature supply chains, while chemical and biological technologies command premium positioning through specialized engineering and enzyme-stability requirements.
- Mechanical:Agitators, homogenizers, and pumps handle physical dispersion and shear without chemical transformation. These systems anchor mid-tier producer budgets across India's domestic brand landscape, where capital constraints favor proven mechanical architectures over advanced process control.
- Chemical:Reactor systems drive surfactant synthesis through controlled temperature and pressure regimes up to 180°C. European formulators under ECHA REACH mandates specify these units for biodegradable surfactant production requiring precise reaction endpoint control.
- Biological:Enzyme-stable processing equipment maintains protease and lipase activity through low-shear mixing and temperature-controlled residence. Cold-water detergent formulations spreading across Japanese and German consumer markets are accelerating investment in biological technology segments.
- Thermal:Evaporators and dryers remove solvent content through heat transfer systems with energy recovery integration. These units face technical ceiling constraints as closed-loop cooling architectures struggle to achieve surfactant recovery rates above 98.5 percent in pilot installations.
Mechanical systems anchor volume shipments. Biological technology is climbing the fastest as enzyme formulation demand spreads.
Application:
Customer type fragmentation creates divergent specification requirements: household and institutional buyers prioritize throughput flexibility and format conversion speed, while industrial and specialty applications demand contamination control and validated cleaning protocols.
- Household Cleaning:Equipment serves powder, liquid, and unit-dose detergent production for consumer markets. German and Japanese brand owners here are unbundling after-sales service contracts, selecting vendors on throughput flexibility rather than bundled maintenance terms.
- Industrial Cleaning:Heavy-duty degreaser and solvent-based detergent systems require corrosion-resistant construction for aggressive chemical environments. These applications concentrate among automotive and metalworking clusters where EPA effluent guidelines mandate closed-circuit cooling architectures.
- Institutional Cleaning:Hospitals, schools, and hospitality facilities demand concentrated formulations with precise dosing equipment. The segment pushes machinery specifications toward modular reactor configurations that reconfigure between surfactant slurry and spray-dried granule production.
- Specialty Cleaning:FDA-regulated cleaning agents for dairy and meat processing facilities require sanitary-design machinery with clean-in-place capability and 3A certification. This application commands premium pricing through validation documentation and material traceability requirements.
Household Cleaning anchors equipment shipments. Specialty Cleaning is gaining share fastest through food-processing sanitation standard upgrades.
End User:
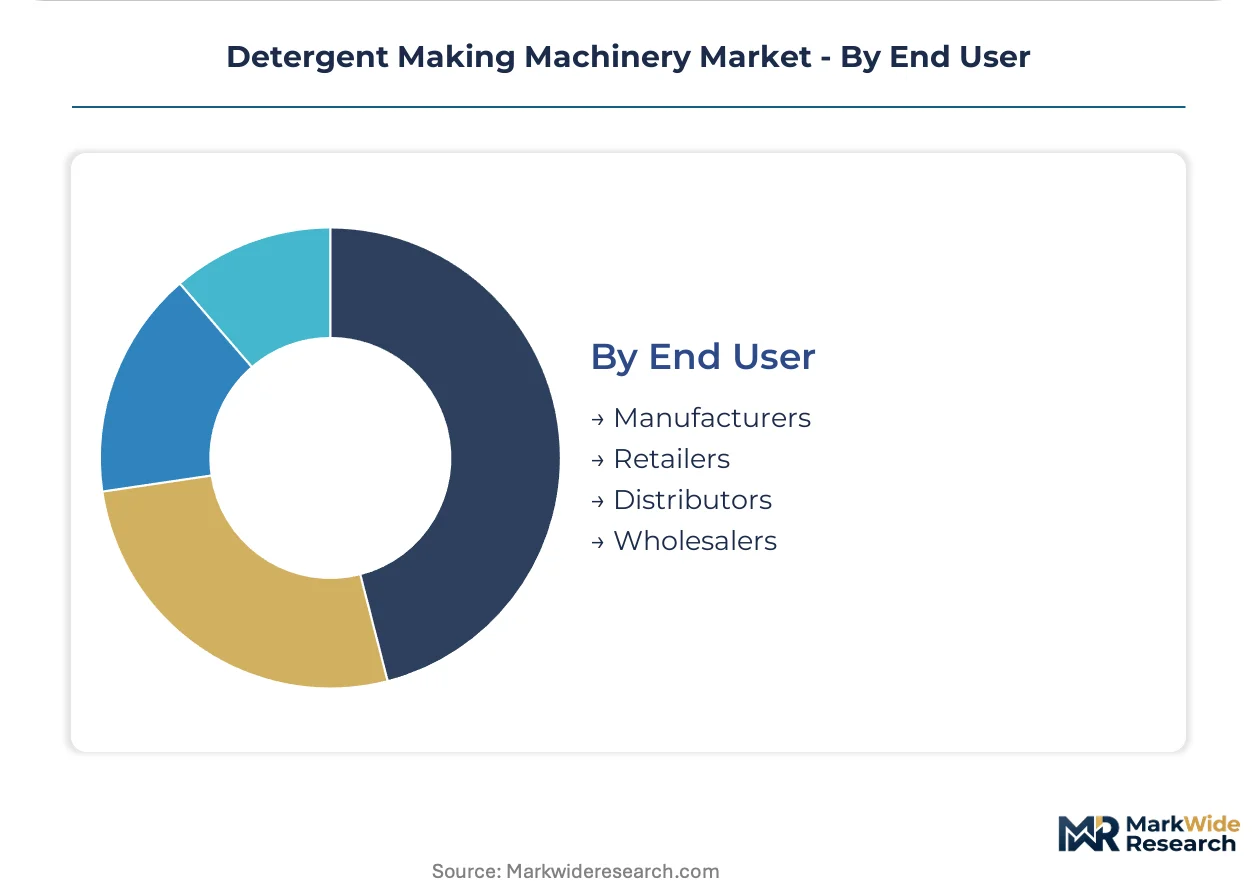
Supply chain position determines technical sophistication requirements: manufacturers demand integrated process control, while downstream intermediaries prioritize packaging integration and logistics compatibility over production technology depth.
- Manufacturers:Integrated producers specify complete production trains from raw material handling through finished goods palletization. These buyers drive demand for real-time viscosity control systems and energy recovery integration as they pivot from batch to continuous processing architectures.
- Retailers:Private-label detergent programs require contract manufacturing partnerships with rapid format-switching capability. Equipment specifications here emphasize modular batch systems that accommodate seasonal volume swings and SKU proliferation without dedicated line investment.
- Distributors:Regional logistics players rarely own production assets, instead influencing machinery selection through packaging and palletization requirements that affect warehouse handling efficiency.
- Wholesalers:Bulk commodity traders participate marginally in equipment procurement, primarily specifying bulk bag filling and intermediate bulk container handling systems for toll manufacturing arrangements.
Manufacturers dominate capital deployment. Retailers are where procurement pattern shifts concentrate as private-label programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision component suppliers ship homogenizer subsystems to turnkey integrators in Pune and Shanghai, while Indian equipment fabricators export modular batch lines to Southeast Asian detergent producers scaling under national chemical manufacturing incentives.
United States
EPA effluent guidelines are compelling stainless steel construction upgrades among household cleaning product manufacturers. FDA oversight of food-processing sanitation agents segments demand toward machinery with clean-in-place capability. Equipment procurement concentrates in Midwest industrial clusters where automotive and meatpacking facilities drive heavy-duty detergent consumption.
Germany
ECHA REACH chemical restrictions are forcing equipment retrofits for biodegradable surfactant handling. Mittelstand specialists dominate precision pump and homogenizer subsystem supply, creating lead time vulnerability for Asian integrators. Machinery specification in North Rhine-Westphalia emphasizes 316L electropolished surfaces and zero-liquid-discharge auxiliary systems.
India
PLI scheme incentives for chemical manufacturing are accelerating domestic production scaling among SME detergent brands and contract manufacturers. Modular spray drying and filling lines accommodate both powder and liquid formats. Maharashtra and Gujarat industrial corridors host the fastest equipment deployment for concentrated and eco-formulated detergent output.
China
Dual carbon goals and tightening MEE standards are pushing equipment upgrades toward energy recovery integration and closed-loop processing architectures. Yangtze River Delta manufacturers are adopting continuous reactor-dryer-classifier lines operating above ten metric tons per hour. Zhejiang and Jiangsu provinces anchor spray drying technology adoption for granular detergent exports.
Indonesia
Artisanal detergent producers in Surabaya and Medan lack access to standardized mixing vessels, creating demand for skid-mounted batch systems with local language interfaces. Contract manufacturers serving multiple brand portfolios are evaluating hybrid powder-liquid line configurations. Java-based equipment procurement remains price-sensitive amid nickel and molybdenum input cost volatility.
Detergent Making Machinery Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single fabricator holds dominant share. The market structures around three tiers: large-scale turnkey integrators bundling complete production trains, mid-cap modular system builders offering format flexibility, and component specialists supplying precision subsystems to multiple OEMs. M&A activity concentrates on acquiring automation engineering capabilities, while capacity expansion targets Southeast Asian assembly facilities to reduce lead times for Indian and Indonesian end users.
Among Chinese fabricators, Jinzong Machinery and Zhangjiagang Keyuan Machinery occupy positions reflecting distinct strategic archetypes. Jinzong Machinery exemplifies the reactor-engineering heritage segment, leveraging process equipment expertise to anchor high-volume production lines. Zhangjiagang Keyuan Machinery represents the modular batch system specialization, serving mid-tier producers requiring reconfiguration capability between liquid and powder formats. Both sit within the broader tier of Asia-Pacific equipment builders competing on throughput flexibility and local service presence rather than bundled maintenance terms.
| Leading Market Players |
|---|
| Jinzong Machinery |
| Zhangjiagang Keyuan Machinery |
| Wuxi Transtek Machinery |
| Shanghai Genyond Machinery |
| Guangzhou Jinzong Machinery |
| Fei Lun Packing Machinery |
| Angelon Chemistry Machinery |
| Botou Xianfa |
| Changzhou Terry |
| Others |
Supply Flow & Price Mechanics
Shanghai-Piraeus container freight corridors transmit 316L stainless steel price volatility from European mills to Asian equipment fabricators, amplifying cost compression in batch vessel manufacturing while widening the premium that continuous process lines command over legacy mechanical mixing systems.
Pricing Analysis
Current-generation continuous reactor-dryer-classifier lines command substantial premiums over prior-generation batch vessels, while next-gen enzyme-stable biological processing equipment sits at the apex of the pricing hierarchy. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation depth and energy recovery integration, with German Mittelstand component sourcing driving differentiation at the top tier. Pricing pressure stems from nickel and molybdenum input cost swings compressing margins on 316L construction mandates. SME detergent producers in India's PLI scheme expansion zones exhibit highest price sensitivity, whereas large-scale Asian manufacturers prioritize throughput flexibility over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk architecture for precision pump and homogenizer subsystems. Component sourcing concentrates in Germany, China, and India, with Mittelstand specialists anchoring high-shear equipment and Yangtze River Delta fabricators supplying thermal processing units. Raw material flows draw from Indonesian nickel laterite, South African ferrochrome, and Brazilian iron ore feeds. Single-source vulnerability pervades precision metering pump supply. Distribution runs through turnkey integrators in Pune and Shanghai who bundle complete production trains for end-user deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detergent machinery purchasing cycles track capital expenditure waves in consumer goods manufacturing, with the current upswing reflecting post-pandemic automation backlogs and regulatory-driven equipment refresh mandates across European and Asian production bases.
For Market Incumbents: Harden defensive positions by deepening backward integration into 316L stainless steel processing capabilities to offset raw material price volatility, while accelerating certification investment for FDA-compliant sanitary-design machinery to capture food-processing sanitation upgrade cycles. Channel control through long-term service contracts with Indian PLI scheme beneficiaries provides stickiness against modular system competitors. For New Entrants and Emerging Players: Indonesia's underpenetrated SME tier in Surabaya and Medan offers immediate white-space access for skid-mounted batch systems with Bahasa Indonesia interfaces and localized payment terms. Hybrid powder-liquid modular configurations targeting contract manufacturers serving multiple brand portfolios represent the most penetrable equipment segment. Go-to-market execution should prioritize equipment-as-a-service financing to overcome capital constraints among artisanal producers. For Investors and Strategic Acquirers: EPA effluent guideline enforcement reshapes the acquisition landscape toward equipment fabricators with proven closed-loop cooling architectures and surfactant recovery capabilities above 98 percent. Long-term viability centers on automation engineering talent density and Southeast Asian assembly footprint scale. Monitor REACH chemical restriction expansion timelines as the signal for biodegradable surfactant handling equipment demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Processing | Captive 316L supply insulates margins from nickel price volatility affecting construction mandates. |
| Enzyme-Stable Processing Equipment Launch | Cold-water detergent formulation demand in Japan and Germany drives biological technology segment premiums. |
| Joint Venture with Indian PLI Beneficiaries | Local assembly presence in Maharashtra and Gujarat reduces lead times for domestic brand scaling. |
| Zero-Liquid-Discharge System Certification | REACH compliance positions fabricators for European formulator equipment retrofit cycles. |
| Remote Diagnostics Platform Integration | Subscription revenue capture aligns with German and Japanese buyer preference for unbundled service terms. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with equipment fabricators, plant engineers at detergent manufacturers, procurement leads at contract manufacturers, and aftermarket service heads; alongside secondary validation through customs trade data, chemical industry association reports, SEC filings of publicly listed machinery companies, and regulatory documentation from EPA and ECHA. Bottom-up equipment shipment tallies triangulated against top-down capital expenditure surveys across the analysis window.
Forecast inputs considered process architecture segmentation, technology tier stratification, application-specific specification requirements, and end-user supply chain position across the projection horizon. Modeled dimensions spanned batch versus continuous process type, mechanical through biological technology tiers, household through specialty cleaning applications, and manufacturer versus retailer procurement patterns. CAGRs derived from equipment replacement cycle velocity, regulatory compliance deadline clustering, and regional production scaling incentives.
Practitioners should monitor stainless steel price index movements, REACH chemical restriction expansion scope, and PLI scheme beneficiary qualification thresholds for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Oilfield Biocides and Bio-Solvents Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Asia-Pacific Bio Transformer Oil Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Explosion Venting Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market