
 Reconditioned Drums Market | 2026-2036
Reconditioned Drums Market Size, Share, and Industry Trends Forecast 2026-2036
Reconditioned Drums Market Analytics
Market Dynamics
Drum refurbishment subscriptions and predictive maintenance overlays are restructuring how industrial buyers procure container lifecycles. Greif Inc. leverages its North American collection network to secure feedstock for reconditioning operations. Mauser Packaging Solutions anchors European demand through closed-loop pooling systems that integrate tracking software. SCHOTT AG specializes in high-barrier pharmaceutical drum restoration that meets stringent cleanliness protocols.
Product Landscape
Reconditioned drums are industrial containers restored to performance standards through cleaning, dent removal, lining replacement, and pressure testing for reuse in chemical, food, and pharmaceutical logistics. Steel drums dominate refurbishment volume due to structural durability and compatibility with high-temperature reconditioning processes, while plastic drum reconditioning is expanding fastest as food-grade resin recycling technologies mature. Fiber drums occupy a narrower niche where lightweight, one-way export applications limit reuse economics.
Regulatory Environment
EPA RCRA hazardous waste container rules, EU REACH chemical registration requirements, and BIS certification standards in India collectively shape reconditioning quality thresholds and market access conditions. These frameworks elevate compliance costs for uncertified operators while creating protected demand channels for accredited refurbishers. Stakeholders must monitor evolving extended producer responsibility mandates that could shift financial liability for end-of-life drum management toward original manufacturers.
Market Dynamics
Closed-loop pooling systems and predictive maintenance overlays are compressing procurement cycles for industrial container lifecycles. Chemical processors now track drum utilization through embedded RFID tags, triggering reconditioning orders before failure rather than after decommissioning.
Growth Catalysts
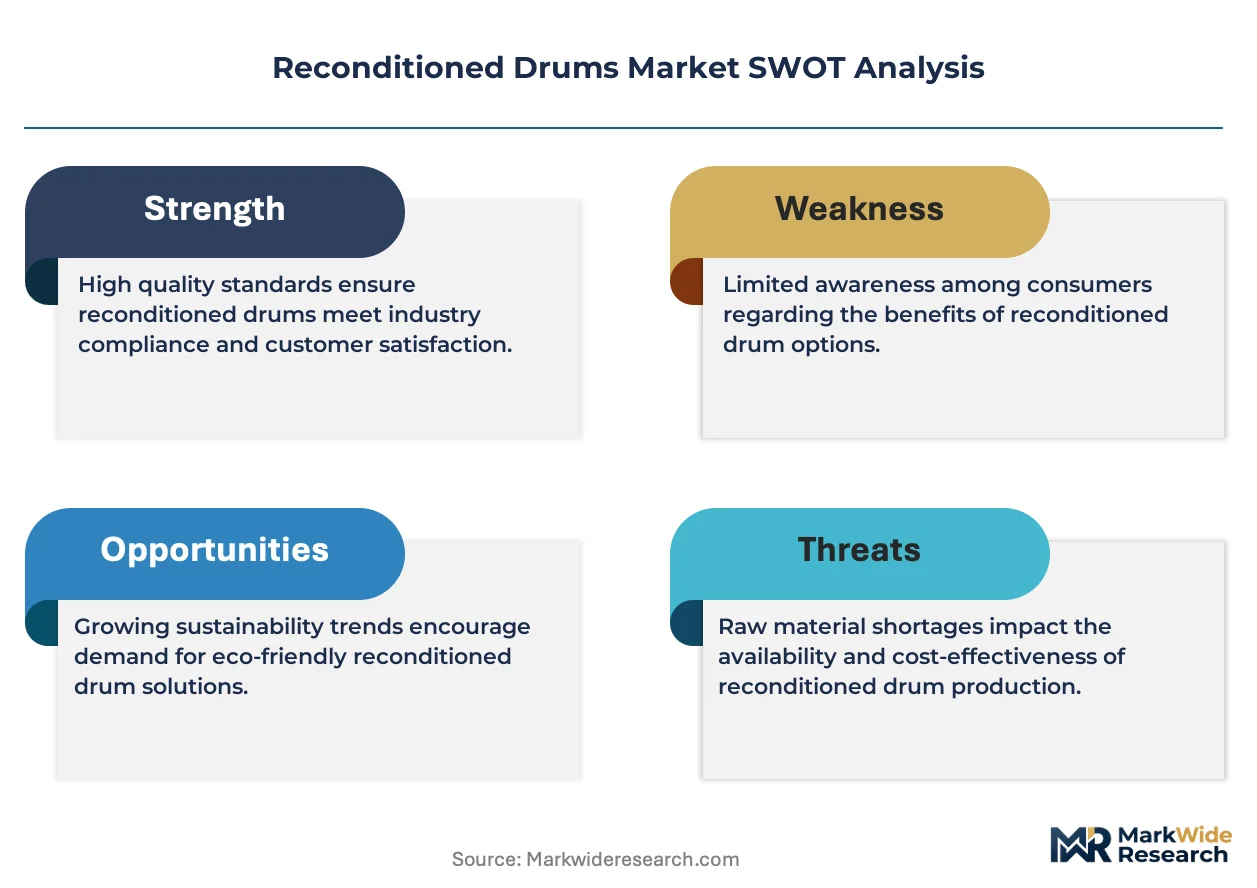
- EU REACH compliance protocols:Chemical registration requirements in Europe mandate documented container traceability. Reconditioned drums with certified cleaning histories satisfy audit trails that single-use alternatives cannot match.
- Steel drum structural durability:High-temperature reconditioning processes restore steel containers to original pressure ratings. Food-grade and pharmaceutical logistics operators favor this material for multi-cycle reuse programs.
- India BIS certification requirements:The Plastic Waste Management Rules push manufacturers toward certified reconditioning facilities. Domestic reconditioners with Bureau of Indian Standards accreditation capture protected demand channels.
Market Restraints
- Resin price volatility:Virgin polyethylene and polypropylene feedstock fluctuations compress margins for plastic drum reconditioners. Operators cannot fully pass through material cost swings to contracted industrial buyers.
- Collection network concentration:Feedstock availability clusters around established logistics corridors in Germany and the United States. New market entrants face prohibitive costs to replicate dense collection infrastructure.
- Fiber drum reuse economics:Lightweight construction limits reconditioning cycles to one or two rotations. Export-oriented shippers discard fiber containers after single use, capping addressable market volume.
Strategic Opportunities
- Pharmaceutical high-barrier restoration:SCHOTT AG's cleanliness protocols for pharmaceutical drum reconditioning create premium service tiers. Specialized liners and vacuum-sealing technologies command price multiples over standard chemical containers.
- Tracking software integration:IoT-enabled drum pooling systems merge physical asset management with digital inventory visibility. Chemical processors in the United States pilot subscription models linking container availability to production schedules.
- Extended producer responsibility mandates:Evolving regulations in the European Union may shift end-of-life drum liability toward original manufacturers. Accredited reconditioners position as compliance partners for brand owners facing new financial obligations.
Industry Challenges
- Pressure testing technician certification:Qualified inspectors for hydrostatic and pneumatic validation remain scarce. Reconditioning facilities compete for talent against broader industrial inspection services.
- Lining replacement capex cycles:Automated spray-coating equipment for food-grade epoxy linings requires substantial capital deployment. Mid-scale operators struggle to justify equipment upgrades against uncertain contract volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reconditioned Drums Market |
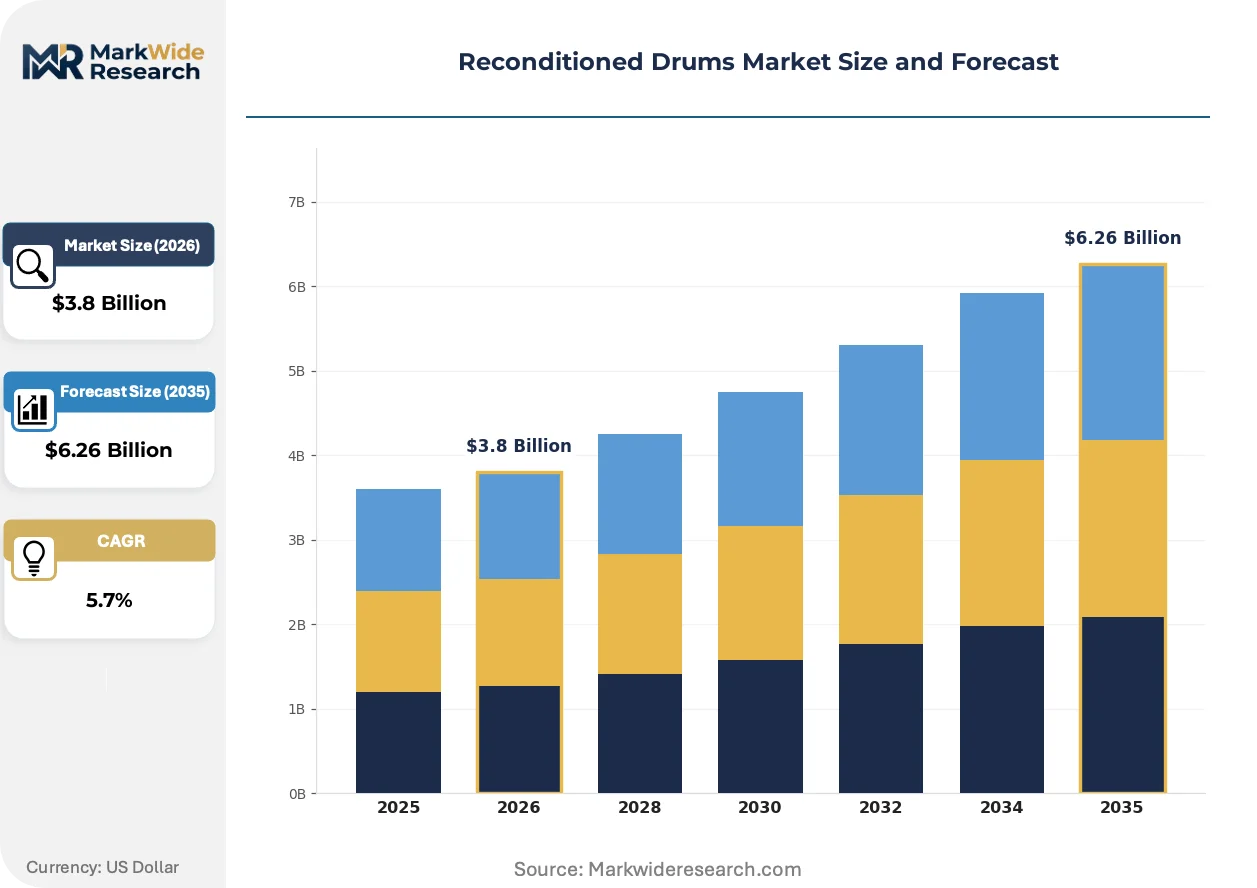
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Drums, Plastic Drums, Fiber Drums, Composites End User: Food Industry, Chemical Industry, Pharmaceutical, Oil & Gas Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers Usage: Storage, Transportation, Waste Management, Recycling |
| Companies Covered | SCHOTT AG, North Coast Container, Greif Inc., Crown Steel Drum, Recon Industries, Mauser Packaging Solutions, Berry Global, Moll Container, Industrial Container Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reconditioned Drums Market Evolving Landscape
Digitalization of asset tracking and automation of cleaning processes are restructuring operational economics for drum reconditioners. Technology investments now separate scalable operators from manual-dependent competitors.
Automated high-pressure cleaning systems with computer-vision defect detection are converging with legacy reconditioning workflows. Chemical processors in Germany adopt these installations to reduce turnaround times for container reuse. The technology is converging with predictive maintenance platforms, enabling reconditioners to forecast drum retirement and pre-position replacement inventory.
EPA RCRA hazardous waste container rules now require documented chain-of-custody for containers holding listed wastes. Reconditioners serving petrochemical and agrochemical sectors invest in barcode-based tracking systems to satisfy audit requirements. Small operators lacking compliance infrastructure face exclusion from contracted waste management programs.
Subscription-based container lifecycle management displaces traditional spot-market drum purchases among large chemical processors. Mauser Packaging Solutions and Greif Inc. structure multi-year agreements bundling collection, reconditioning, and redelivery. This model concentrates most visibly in North America, where integrated logistics networks support predictable rotation schedules.
Reconditioned Drums Market Segmentation
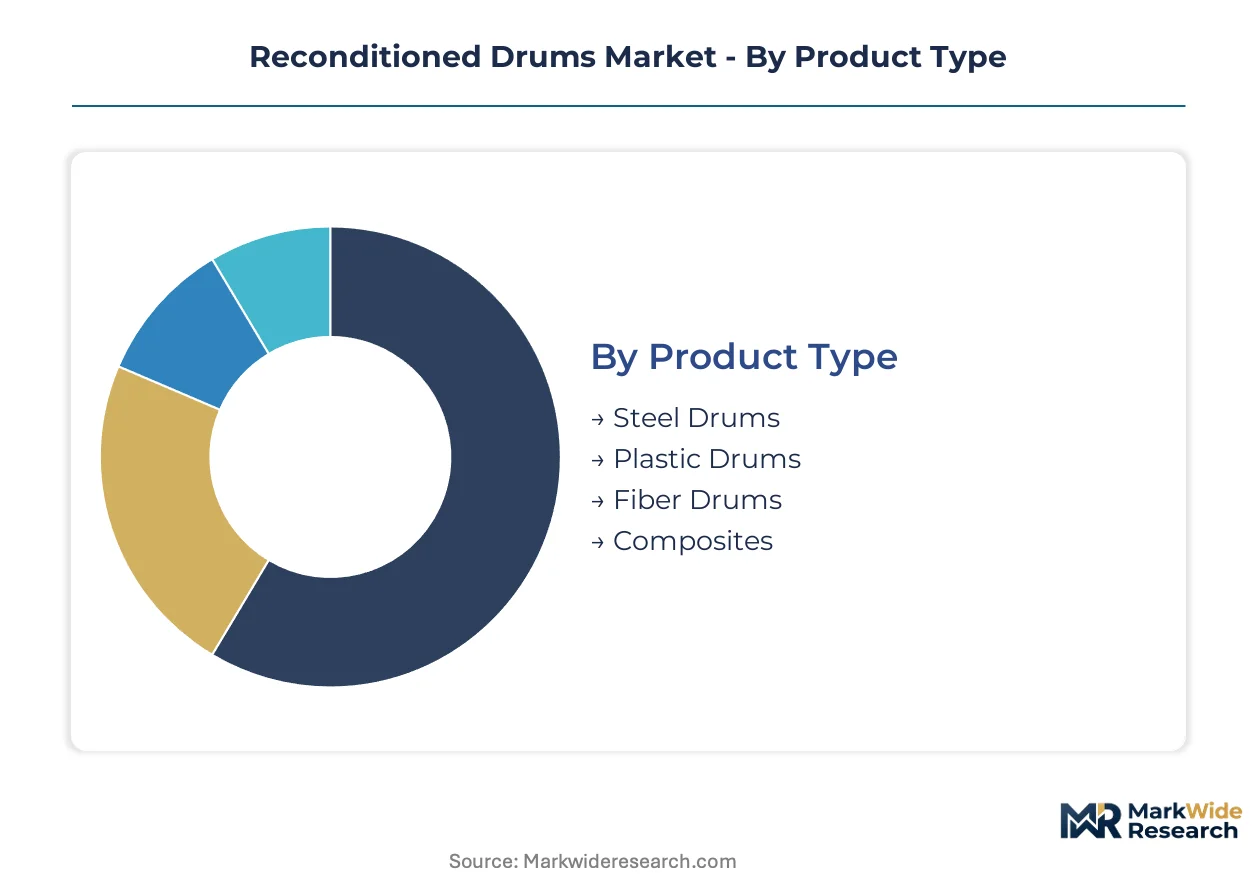
Reconditioned drum procurement varies sharply by container material, end-use compliance requirements, and channel economics. Understanding these fault lines helps suppliers align refurbishment capacity with buyer willingness to pay for certification tiers.
Product Type:
Cost tier separates buyers most cleanly in this category.
- Steel Drums:Carbon and stainless steel containers withstand high-temperature cleaning and hydrostatic pressure testing to original DOT specifications. Chemical processors in Germany favor steel reconditioning for multi-cycle solvent handling under EU REACH traceability mandates.
- Plastic Drums:High-density polyethylene containers require specialized resin recycling and food-grade lining replacement to meet FDA and BIS standards. India's Plastic Waste Management Rules are accelerating certified HDPE reconditioning as manufacturers abandon single-use alternatives.
- Fiber Drums:Lightweight kraft construction limits reconditioning to one or two rotations before structural degradation.
- Composites:Multi-material drums combining steel and plastic layers serve niche pharmaceutical barrier applications.
Steel drums lead volumes today; plastic drums are gaining share fastest.
End User:
Application-specific compliance thresholds reshape reconditioning specifications.
- Chemical Industry:Petrochemical and agrochemical handlers require documented chain-of-custody under EPA RCRA rules. Reconditioners invest in barcode tracking systems to satisfy hazardous waste audit trails that uncertified operators cannot match.
- Pharmaceutical:SCHOTT AG's vacuum-sealing and specialized liner protocols command premium pricing for high-barrier restoration. Parenteral drug manufacturers in the United States demand validated cleanliness exceeding standard chemical grades.
- Food Industry:Processors need FDA-compliant epoxy linings and automated spray-coating verification for edible oil and syrup containment.
- Oil & Gas:Lubricant and drilling fluid handlers prioritize structural integrity over cosmetic refurbishment.
Chemical industry demand anchors current volumes; pharmaceutical represents the steepest expansion trajectory.
Distribution Channel:
Customer type determines service bundling and contract structure.
- Direct Sales:Greif Inc. and Mauser Packaging Solutions structure multi-year subscription agreements bundling collection, reconditioning, and redelivery. Large chemical processors in the United States prefer this model for production-schedule alignment.
- Distributors:Regional logistics firms aggregate drum pools across smaller chemical handlers, capturing economies of scale that individual buyers cannot achieve.
- Online Retail:Spot-market platforms serve intermittent buyers with standardized specifications and limited certification requirements.
- Wholesalers:Inventory-heavy intermediaries stock pre-refurbished drums for immediate availability in fragmented industrial corridors.
Direct sales channels dominate contract value; distributor networks are expanding most quickly.
Usage:
Maturity of circular infrastructure varies by functional application.
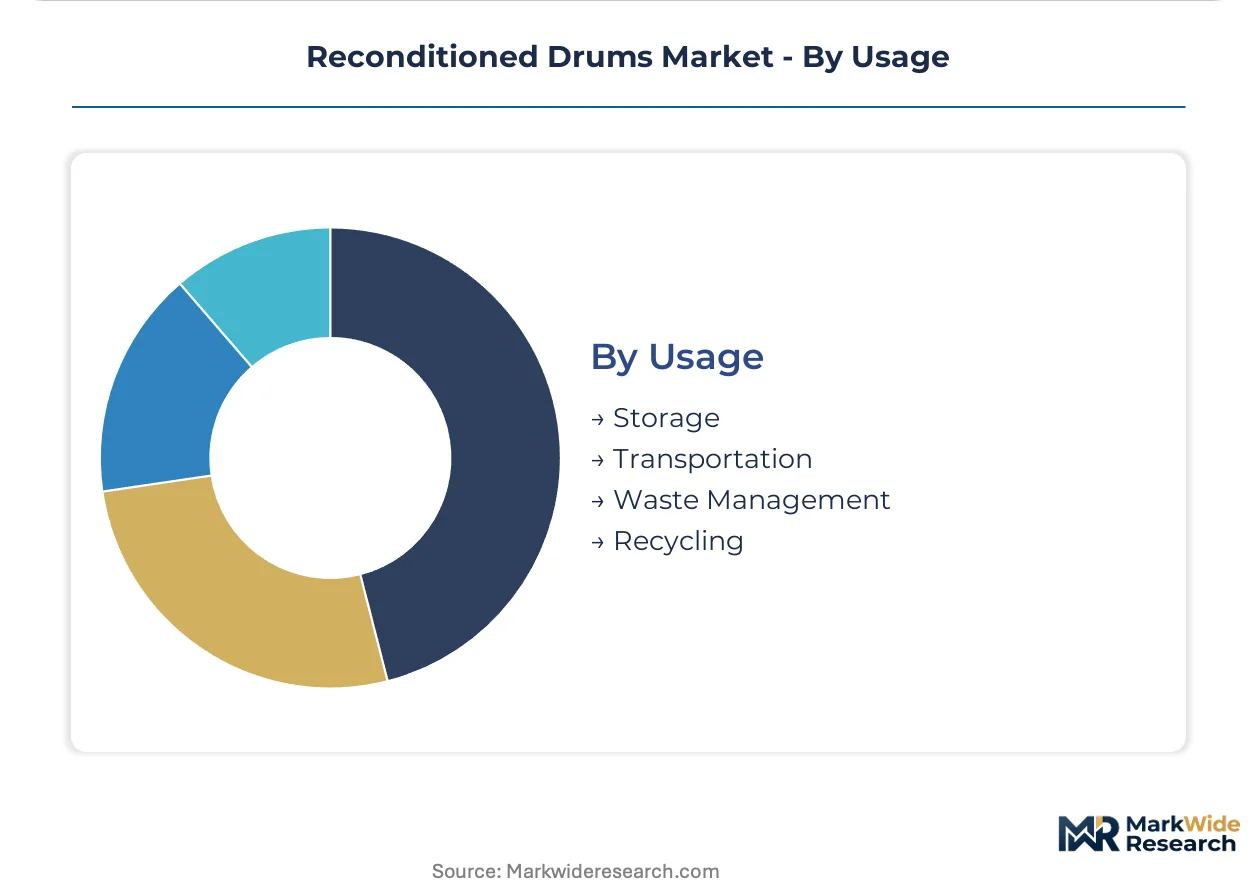
- Transportation:Multi-modal logistics operators demand UN-certified reconditioning for cross-border chemical shipments. German chemical exporters rely on closed-loop pooling systems with embedded RFID tracking.
- Storage:In-plant containment applications tolerate longer turnaround times, allowing reconditioners to batch-process drums during seasonal demand lulls.
- Waste Management:Hazardous waste handlers face EPA RCRA container rules requiring documented custody transfer. Small operators lacking compliance infrastructure face exclusion from contracted programs.
- Recycling:Material recovery facilities feed shredded drum content into secondary steel and resin markets when reconditioning economics fail.
Transportation applications generate the highest refurbishment frequency; waste management is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical corridor sustains denser drum reconditioning infrastructure than India's emerging certification hubs, yet both markets are tightening regulatory compliance thresholds for container reuse programs.
United States
Petrochemical refiners along the Gulf Coast generate substantial steel drum feedstock for refurbishment cycles. EPA RCRA hazardous waste container rules mandate documented chain-of-custody systems that accredited reconditioners satisfy through barcode tracking investments. Houston-area processing clusters host the densest concentration of pressure-testing facilities serving agrochemical and solvent handlers.
Germany
Ruhr Valley chemical processors operate closed-loop pooling systems with embedded RFID tracking for multi-cycle container utilization. EU REACH chemical registration requirements enforce documented traceability that certified reconditioned drums provide. BASF and Bayer supplier networks around Ludwigshafen anchor European demand for high-barrier steel refurbishment.
India
Food-grade resin reconditioning accelerates as manufacturers abandon single-use HDPE alternatives under cost pressures. BIS certification requirements and Plastic Waste Management Rules create protected demand channels for accredited domestic refurbishers. Gujarat's chemical manufacturing belt around Vadodara and Ahmedabad concentrates new reconditioning capacity investments.
China
Industrial solvent handlers in the Yangtze River Delta sustain steel drum refurbishment volumes despite virgin container price competition. The country's national environmental regulator enforces hazardous waste container standards that elevate compliance costs for uncertified operators. Shanghai-Ningbo port logistics corridors generate cross-border container pooling demand for chemical exporters.
Brazil
Agricultural chemical distributors in São Paulo state drive drum reuse programs for pesticide and fertilizer containment. The country's national environmental regulator oversees hazardous material packaging standards that reconditioners must satisfy for market access. Campinas industrial clusters host the primary concentration of pressure-testing infrastructure serving Latin American chemical logistics.
Reconditioned Drums Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pooling operators commanding premium contract terms while independent refurbishers compete on spot-market turnaround speed. Market structure tilts toward consolidation among container lifecycle managers with captive collection networks. Three archetypes dominate: closed-loop pooling specialists with tracking software integration, pharmaceutical-grade restoration experts with vacuum-sealing protocols, and regional independents focused on chemical industry spot demand. Competitive moves concentrate on geographic network densification and certification tier expansion.
Among North American integrated operators, Greif Inc. and Mauser Packaging Solutions exemplify the closed-loop pooling archetype through subscription-based lifecycle management. SCHOTT AG occupies a position representing pharmaceutical-grade restoration specialists with premium service tiers. These three companies anchor the competitive landscape across distinct certification and end-use segments.
| Leading Market Players |
|---|
| SCHOTT AG |
| North Coast Container |
| Greif Inc. |
| Crown Steel Drum |
| Recon Industries |
| Mauser Packaging Solutions |
| Berry Global |
| Moll Container |
| Industrial Container Services |
| Others |
Value Network & Pricing Analysis
Certified pressure-testing technician pools in Germany and the United States create labor-cost differentials that widen pricing-tier spreads between premium pharmaceutical-grade restoration and standard chemical-container refurbishment. BIS-accredited facilities in India capture mid-tier demand as wage arbitrage compresses margins for uncertified operators serving spot-market buyers.
Pricing Analysis
Capacity additions in Gujarat and Texas are reshaping price floors for food-grade HDPE reconditioning as automated spray-coating investments diffuse across mid-scale operators. Three-tier pricing structure across premium, standard, and economy levels separates SCHOTT AG's vacuum-sealed pharmaceutical protocols from BIS-certified chemical handlers and uncertified regional independents. Pricing pressure stems from virgin polyethylene feedstock volatility that reconditioners cannot fully pass through to contracted industrial buyers. Small chemical processors exhibit highest price sensitivity; parenteral drug manufacturers show least elasticity due to validated cleanliness requirements.
Supply Chain Analysis
Regional distribution centers around Houston, Ludwigshafen, and Vadodara anchor hub-and-spoke patterns that feed reconditioning facilities with used drum feedstock. Germany, the United States, and India concentrate supply for steel and plastic drum refurbishment; China sustains secondary volumes for solvent-handler demand. Raw material inputs draw from carbon steel coil, high-density polyethylene resin, and food-grade epoxy lining formulations. Single-source vulnerability clusters around specialized liner suppliers serving pharmaceutical restoration tiers. Distribution runs through closed-loop pooling systems with embedded RFID tracking for large chemical processors, while spot-market buyers rely on wholesaler inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA RCRA hazardous waste container rules and EU REACH traceability mandates continuously elevate compliance thresholds that accredited operators alone can satisfy.
For Market Incumbents: To counter resin price volatility compressing plastic drum margins, backward integration into captive HDPE collection networks secures feedstock cost predictability. Certification tier expansion into BIS-accredited operations in India captures protected demand channels created by Plastic Waste Management Rules enforcement.
For New Entrants and Emerging Players: Launch via distributor-aggregated drum pools serving fragmented chemical handlers in Brazil and Southeast Asia where collection infrastructure remains underdeveloped. Pharmaceutical high-barrier restoration offers the most penetrable premium tier given specialized cleanliness protocol scarcity. Target food-grade lining automation as the go-to-market angle for mid-scale contract manufacturers.
For Investors and Strategic Acquirers: Container lifecycle managers with integrated pooling software are the most active acquirer in this space, consolidating regional independents to densify network coverage. Long-term viability hinges on extended producer responsibility mandate expansion shifting end-of-life liability toward original manufacturers. Watch EU regulatory proposals on producer financing obligations as the inflection signal for compliance-partner valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Greif Inc.'s North American feedstock control insulates margin pressure from spot-market drum scarcity. |
| RFID-Enabled Pooling System Deployment | Mauser Packaging Solutions' tracking software merges physical asset management with digital inventory visibility for chemical processors. |
| Pharmaceutical Certification Tier Expansion | SCHOTT AG's vacuum-sealing protocols command price multiples over standard chemical container restoration. |
| Automated Spray-Coating Equipment Investment | Food-grade epoxy lining automation reduces turnaround times for FDA-compliant edible oil containment. |
| BIS Accreditation Pursuit in India | Domestic reconditioners with Bureau of Indian Standards certification capture protected demand under Plastic Waste Management Rules. |
Research Methodology
Bottom-up chemical processor demand modeling reconciled against top-down reconditioning capacity tracking forms the analytical core of this study. Primary interviews with plant managers at petrochemical refiners, procurement leads at agrochemical distributors, drum pool logistics coordinators, and EPA compliance officers combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and BIS certification registries. Triangulation across these sources reconciles facility-level utilization rates with macro-level container flow estimates.
Input-output matrices map drum retirement rates, reconditioning cycle frequencies, and end-use certification requirements across material type, application compliance tier, and channel structure throughout the forecast period. CAGRs derive from segment-level growth rate blending weighted by base-year value shares. Forecast inputs incorporate EU REACH enforcement trajectory, EPA RCRA audit intensity, and BIS accreditation expansion timelines for Indian facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden resin price spikes or accelerated extended producer responsibility mandate implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Bulk Explosives Market
Industrial Chemicals
CDU Heat Exchanger Antifoulants Market
Industrial Chemicals
Mold Powders and Casting Fluxes Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Hydrofluoric Acid (HF) for Semiconductor Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Babassu Oil Market