
 Phenol Derivatives Market | 2026-2036
Phenol Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Phenol Derivatives Market Analysis
REACH is shifting the cost-of-entry calculus for European phenol derivative producers, forcing reformulation investments and third-party certification costs that favor well-capitalized incumbents. BASF SE leverages its integrated Ludwigshafen complex to sustain margin capture across phenolic resins and caprolactam chains. INEOS Phenol anchors its position through captive cumene supply and Rotterdam-Antwerp logistics dominance. LG Chem competes on scale from its Yeosu petrochemical hub, while Mitsui Chemicals differentiates through specialty-grade catechol and hydroquinone purity leadership.
Phenol derivatives encompass organic compounds synthesized from phenol feedstock, including bisphenol A produced via acid-catalyzed condensation of phenol and acetone, phenolic resins formed through formaldehyde reaction under alkaline or acidic conditions, and dihydroxybenzenes such as catechol and hydroquinone with defined melting points above 104°C. These materials serve as essential intermediates for polycarbonate plastics, epoxy adhesives, antioxidants, and pharmaceutical precursors. Phenolic resins command the largest volume share due to sustained demand from brake linings and insulating laminates, while bisphenol A faces structural pressure from polycarbonate substitution in baby bottles and food-contact applications under EFSA scrutiny. Catechol and hydroquinone occupy narrower but higher-margin positions in agrochemical and photographic chemical value chains.
EPA oversight of formaldehyde emissions from composite wood products directly constrains phenolic resin formulation standards in the United States, while ECHA REACH restrictions on phenol classification and labeling reshape import requirements across EU member states. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks for cumene-to-phenol crackers in Shandong and Zhejiang provinces. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned capital deployment.
Market Dynamics
REACH compliance costs in Europe are restructuring competitive economics, forcing reformulation investments that favor integrated producers with captive cumene supply and in-house certification capabilities over merchant compounders.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in China, India, and South Korea are expanding phenolic resin consumption for brake linings and composite structural components to meet fuel-efficiency standards.
- REACH-driven formulation upgrades:ECHA restrictions on phenol classification are accelerating demand for lower-emission phenolic resin derivatives in EU member states.
- Caprolactam chain integration:Phenol-to-caprolactam producers in Ludwigshafen and Rotterdam-Antwerp corridors are capturing margin through backward integration into nylon-6 feedstocks.
Market Restraints
- Acetone price volatility:Bisphenol A producers face margin compression when acetone feedstock costs spike due to refinery operating rate fluctuations.
- Shandong-Zhejiang supply concentration:China's dual carbon goals under MEE enforcement are tightening energy intensity benchmarks for cumene-to-phenol crackers, constraining new capacity.
- Polycarbonate substitution pressure:EFSA scrutiny of bisphenol A in food-contact applications is accelerating migration to polypropylene and Tritan copolyester alternatives.
Strategic Opportunities
- India PLI scheme alignment:Electronics manufacturing incentives are creating demand for high-purity catechol in printed circuit board antioxidants.
- EU Green Deal chemistry:Bio-based phenol pilot projects in Antwerp and Rotterdam qualify for circular economy funding and green procurement preferences.
- Specialty hydroquinone purity:Agrochemical and photographic chemical value chains in Japan and South Korea reward Mitsui-grade purity leadership with price premiums.
Industry Challenges
- Formaldehyde emission certification:EPA composite wood product standards require third-party testing that extends phenolic resin qualification timelines by 8-12 months.
- Process safety engineering scarcity:Cumene oxidation unit operators face recruitment gaps for peroxide handling specialists in Shandong and Zhejiang provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenol Derivatives Market |
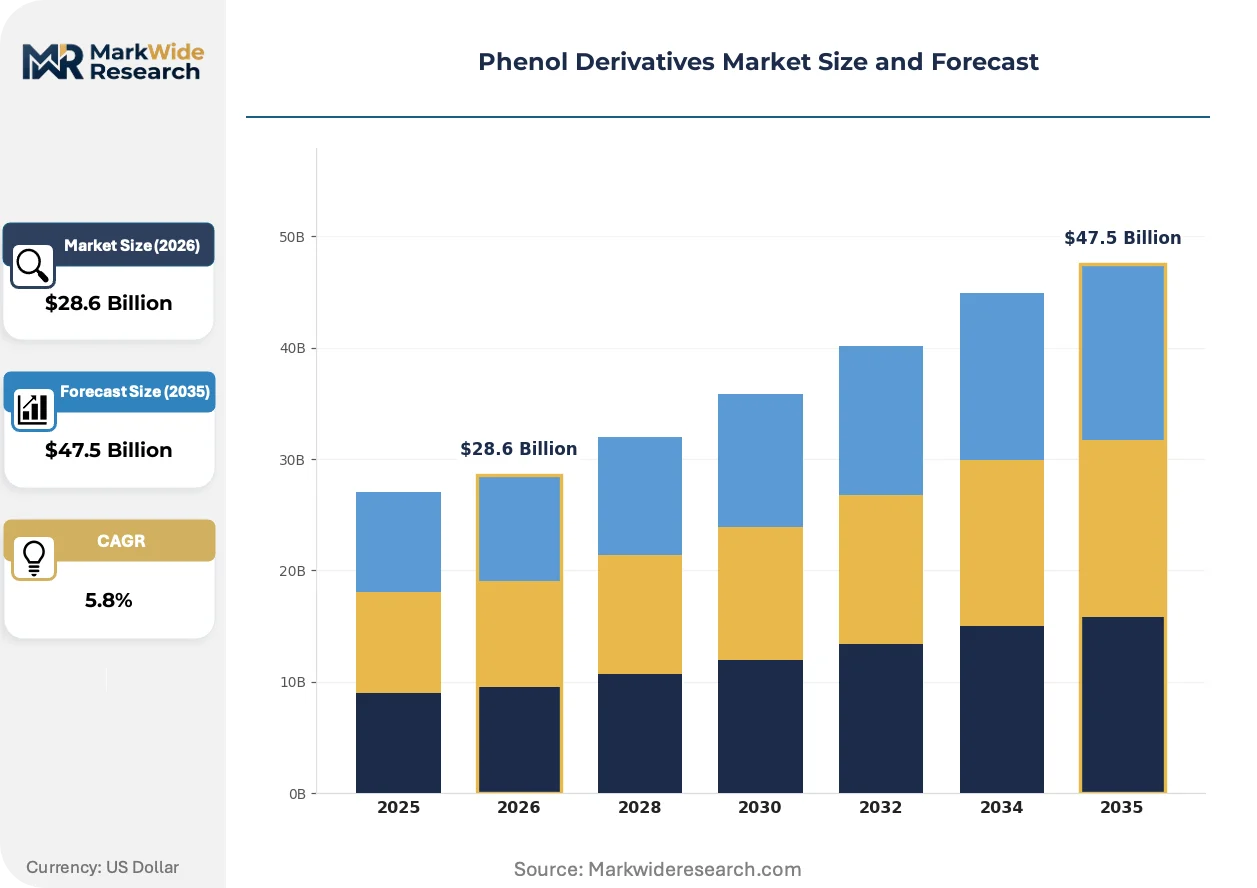
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenolic Resins, Bisphenol A, Catechol, Hydroquinone Application: Automotive, Construction, Electronics, Coatings End User: Chemical Industry, Pharmaceuticals, Consumer Goods, Manufacturing Grade: Technical Grade, Analytical Grade, Industrial Grade, Food Grade |
| Companies Covered | BASF SE, Dow Chemical Company, Mitsui Chemicals Inc., INEOS Phenol, Mitsubishi Chemical Corporation, LG Chem, Shell, Honeywell International Inc., Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenol Derivatives Market Emerging Trajectories
Process intensification and regulatory chemistry are compressing traditional batch operations while digital traceability systems reshape how derivative purity is verified across pharmaceutical and agrochemical value chains.
Continuous-flow phenol alkylation technology is modularizing production economics for mid-scale bisphenol A units. Automotive tier-one suppliers in South Korea are piloting these systems for just-in-time resin delivery. The technology is modularizing capital deployment, enabling 40% smaller footprint plants without sacrificing yield parity with world-scale facilities.
EPA formaldehyde emission standards for composite wood products are tightening phenolic resin cure chemistry requirements. Panel producers must reformulate with lower free-formaldehyde resins or install emission capture systems. North American oriented strand board manufacturers are absorbing compliance costs through specification-grade pricing tiers.
Specification-driven procurement is consolidating phenol derivative purchasing around certified purity tiers. Agrochemical formulators in India and Brazil now require ISO-documented catechol impurity profiles rather than commodity grades. This shift is most visible in contract manufacturing agreements where pharmaceutical precursors demand batch-level chromatographic traceability.
Phenol Derivatives Market Segmentation
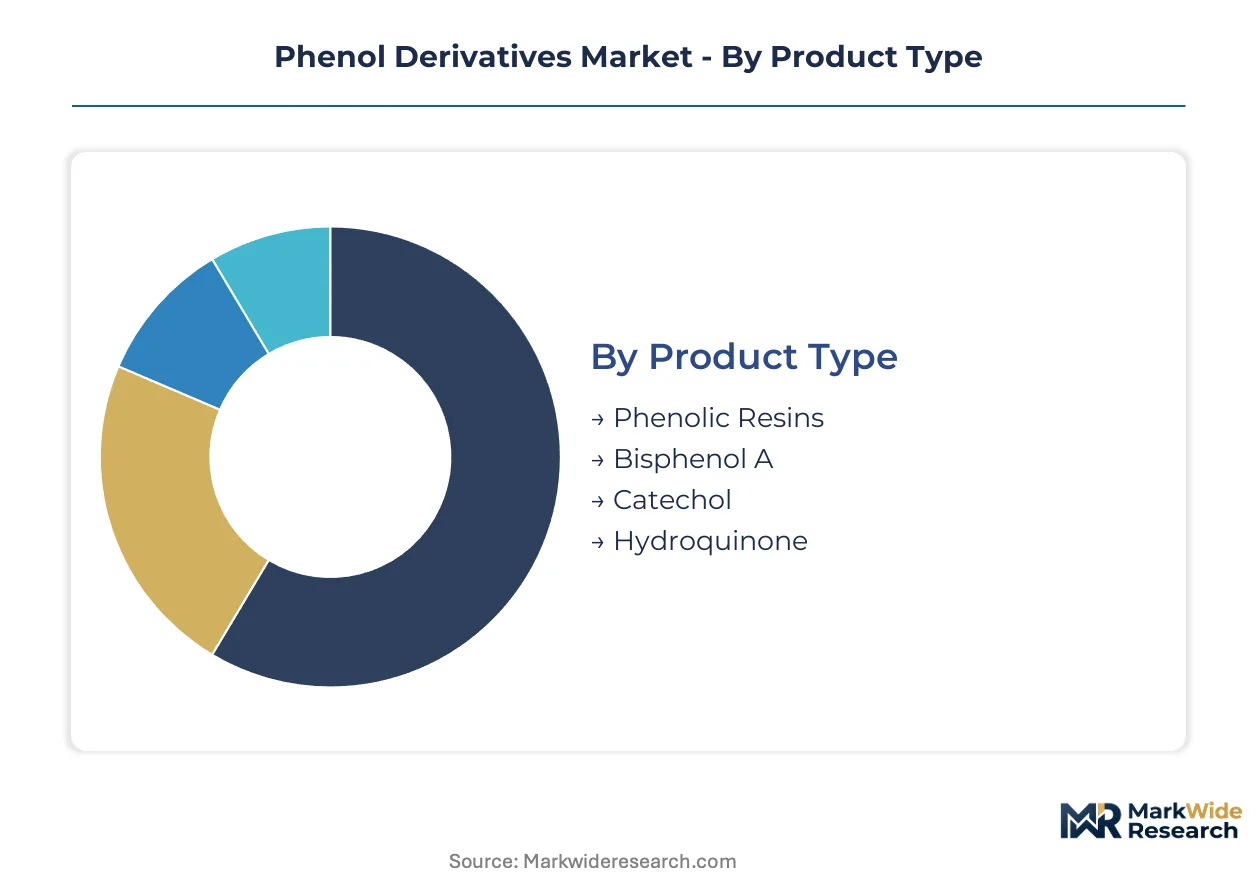
Phenol derivative buyers prioritize distinct performance attributes across applications. Automotive OEMs demand thermal stability for brake linings. Electronics manufacturers require ultra-low impurity profiles for circuit board antioxidants.
Product Type:
Cost tier separates commodity-scale buyers from specialty purchasers willing to pay purity premiums.
- Phenolic Resins:Thermoset polymers formed through formaldehyde condensation under alkaline or acidic catalysis. Automotive brake linings and electrical laminates in China and India absorb the majority of volume as OEMs pursue lightweighting mandates under fuel-efficiency regulations.
- Bisphenol A:Diphenolic compound synthesized via acid-catalyzed condensation of phenol and acetone. Polycarbonate manufacturers in South Korea and Germany face formulation pressure from EFSA scrutiny of food-contact applications, accelerating migration to alternative feedstocks.
- Catechol:Ortho-dihydroxybenzene with melting point above 104°C serving agrochemical and pharmaceutical precursor markets.
- Hydroquinone:Para-dihydroxybenzene commanding price premiums in photographic chemical and polymerization inhibitor applications.
Volume sits with Phenolic Resins; growth tilts toward Catechol.
Application:
Application maturity determines whether buyers accept commodity grades or demand certified purity tiers.
- Automotive:Phenolic resin consumption concentrates in brake friction materials and composite structural components. China's MIIT fuel-efficiency standards and India's CAFE regulations are expanding resin offtake for under-hood applications and body panel substrates.
- Construction:Phenolic resins bind oriented strand board and medium-density fiberboard facing EPA formaldehyde emission caps. North American panel producers absorb compliance costs through specification-grade pricing tiers tied to third-party certification.
- Electronics:High-purity catechol and hydroquinone serve printed circuit board antioxidants and photoresist developers. India's PLI scheme for electronics manufacturing is creating demand for ISO-documented impurity profiles rather than commodity grades.
- Coatings:Epoxy formulations derived from bisphenol A face substitution pressure as architectural specifiers pivot to waterborne alternatives.
Automotive commands current volume; electronics represents the steepest expansion trajectory.
End User:
Customer type dictates procurement rigor from spot-market purchasing to batch-level traceability requirements.
- Chemical Industry:Integrated nylon-6 producers and epoxy formulators purchase phenol derivatives as chain intermediates. Caprolactam manufacturers in Ludwigshafen and Rotterdam-Antwerp corridors capture margin through backward integration into captive cumene supply.
- Pharmaceuticals:API manufacturers require chromatographic traceability and documented impurity profiles for catechol-derived precursors. Contract manufacturing agreements now mandate ISO-certified batch documentation rather than commodity certificates of analysis.
- Consumer Goods:Polycarbonate molders for food-contact applications face EFSA-driven substitution to polypropylene and Tritan copolyesters.
- Manufacturing:Composite fabricators and insulation producers specify technical-grade phenolic resins with controlled cure chemistry.
Chemical Industry anchors volume; pharmaceuticals is gaining share fastest.
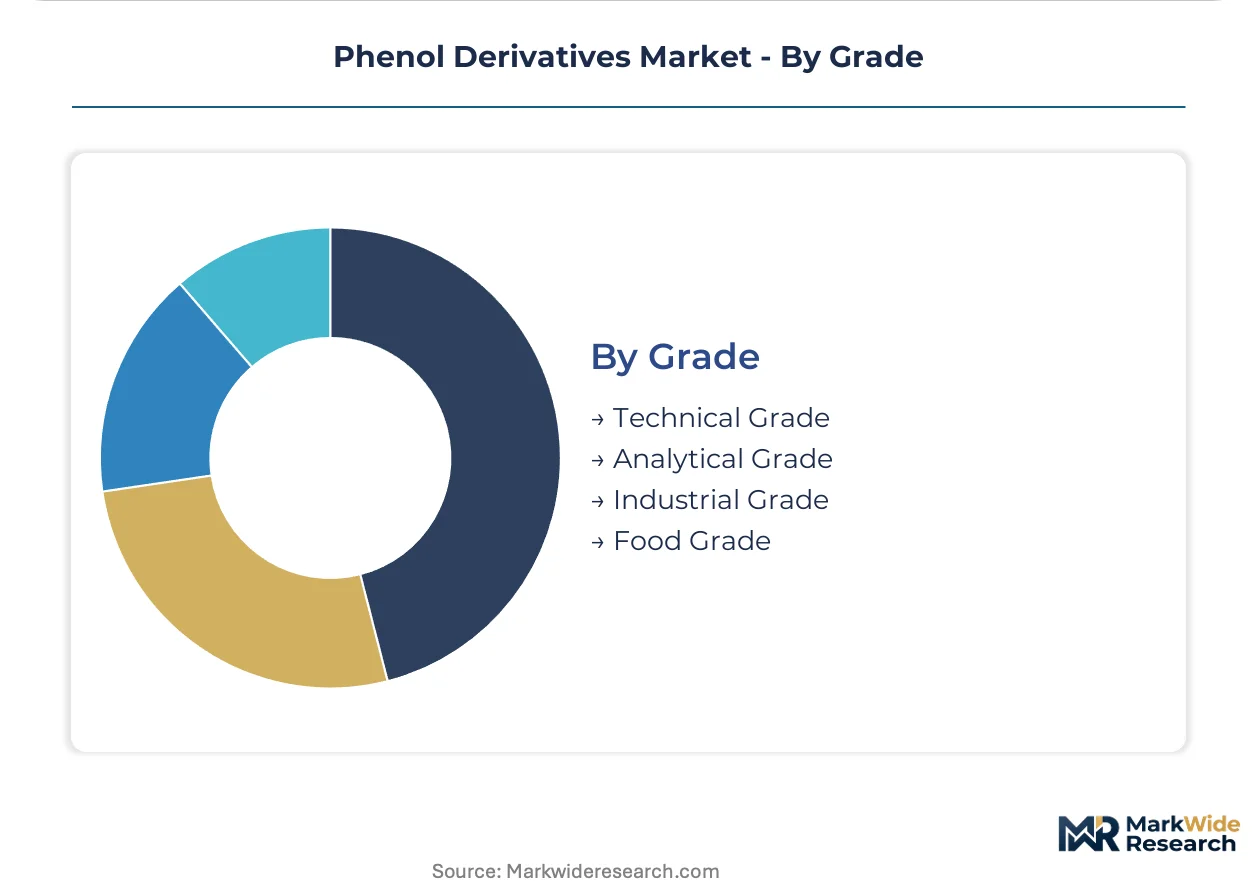
Grade:
Margin structure separates specification-driven premiums from bulk commodity pricing.
- Technical Grade:Standardized purity for industrial phenolic resin production and general chemical synthesis.
- Analytical Grade:Ultra-low impurity specifications for pharmaceutical precursor and reference standard applications. Agrochemical formulators in India and Brazil now require documented chromatographic profiles for catechol purchases.
- Industrial Grade:Bulk phenol derivatives for construction panel binders and mass-market epoxy formulations.
- Food Grade:Bisphenol A faces structural decline under EFSA restrictions; remaining applications concentrate in non-contact polymer additives.
Industrial Grade dominates volume; analytical grade climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Zhejiang provinces host China's densest concentration of cumene-to-phenol crackers, where MEE dual carbon enforcement is tightening energy intensity benchmarks and constraining new capacity additions.
China
Automotive OEMs in Shanghai and Guangzhou are expanding phenolic resin offtake for brake linings and composite structural components under MIIT fuel-efficiency mandates. MEE enforcement of dual carbon goals is tightening energy intensity benchmarks for cumene-to-phenol crackers in Shandong and Zhejiang provinces. Yeosu-based LG Chem anchors regional supply through its integrated petrochemical hub.
Germany
Caprolactam manufacturers in Ludwigshafen capture margin through backward integration into captive cumene supply and nylon-6 feedstocks. ECHA REACH restrictions on phenol classification are accelerating demand for lower-emission phenolic resin derivatives across EU member states. The Ludwigshafen chemical complex sustains integrated production across phenolic resins and caprolactam chains.
United States
North American oriented strand board manufacturers absorb EPA formaldehyde emission compliance costs through specification-grade pricing tiers tied to third-party certification. EPA oversight of composite wood products directly constrains phenolic resin formulation standards and extends qualification timelines. Gulf Coast petrochemical corridors maintain cumene oxidation capacity serving derivative producers.
South Korea
Automotive tier-one suppliers are piloting continuous-flow phenol alkylation systems for just-in-time resin delivery to meet lightweighting mandates. MFDS pharmaceutical regulations shape import requirements for high-purity catechol and hydroquinone destined for API manufacturing. The Yeosu petrochemical hub concentrates phenol derivative production at scale.
India
Electronics manufacturing incentives under the PLI scheme are creating demand for high-purity catechol in printed circuit board antioxidants with ISO-documented impurity profiles. BIS certification requirements are reshaping procurement standards for agrochemical formulators in Maharashtra and Gujarat. Mumbai-Pune industrial corridors concentrate specialty chemical demand from pharmaceutical and electronics sectors.
Phenol Derivatives Market Vendor Landscape
German producers anchor one tier through integrated Ludwigshafen complexes; South Korean specialists hold scale positions through Yeosu hub concentration. The market structures around three archetypes: integrated petrochemical majors with captive cumene supply, regional specialists commanding purity premiums in catechol and hydroquinone, and merchant compounders dependent on spot feedstock procurement. Competitive moves concentrate on backward integration into cumene supply and third-party certification investments for REACH compliance.
Within the integrated major tier, BASF SE and INEOS Phenol exemplify archetypes of backward integration and logistics dominance respectively. Mitsui Chemicals occupies a position representing specialty-grade purity leadership in dihydroxybenzenes. These three anchors illustrate how geographic concentration and regulatory compliance capabilities separate margin capture from commodity pressure.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Mitsui Chemicals Inc. |
| INEOS Phenol |
| Mitsubishi Chemical Corporation |
| LG Chem |
| Shell |
| Honeywell International Inc. |
| Covestro AG |
| Others |
Supply Flow & Price Mechanics
Cumene feedstock costs cascade through phenol derivative pricing tiers from Ludwigshafen and Rotterdam-Antwerp corridors to automotive OEMs in Asia-Pacific, with REACH compliance investments stratifying quotation structures across European and Asian supply bases.
Pricing Analysis
Short lead-time premiums for certified low-emission phenolic resins command pricing separation from spot-market technical grades in Europe. Contract-based long-term offtake dominates automotive supply agreements, while acetone price volatility compresses margins for merchant bisphenol A producers lacking captive cumene supply. ISO-documented impurity profiles in catechol attract specification-grade premiums from agrochemical formulators in India and Brazil. Construction panel producers show highest price sensitivity due to formaldehyde compliance cost absorption, whereas pharmaceutical API manufacturers accept purity premiums for batch-level traceability.
Supply Chain Analysis
Reverse-logistics flows for phenol derivative packaging and spent catalyst recovery concentrate around Yeosu, Ludwigshafen, and Shandong-Zhejiang production clusters. Raw material sourcing draws from Saudi and Korean cumene supply, European acetone refining, and Chinese coal-to-chemicals feedstock. Single-source vulnerability sits with Shandong-Zhejiang crackers under MEE dual carbon enforcement. Distribution runs through Rotterdam-Antwerp liquid bulk terminals and Asia-Pacific chemical tanker corridors to downstream automotive and electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH compliance capabilities and captive cumene supply, with ECHA reformulation deadlines forcing undercapitalized merchant compounders toward exit or acquisition.
For Market Incumbents: Anticipate acetone price volatility by securing long-term cumene supply agreements or backward integration into crackers in Shandong or Rotterdam-Antwerp corridors. Defend margin position through third-party REACH certification investments that extend qualification timelines for smaller competitors. Prioritize specialty-grade catechol and hydroquinone capacity to capture agrochemical and pharmaceutical purity premiums. For New Entrants and Emerging Players: Electronics manufacturers under India's PLI scheme represent the most penetrable buyer archetype for high-purity catechol with ISO-documented impurity profiles. Target contract manufacturing agreements for pharmaceutical precursors requiring batch-level chromatographic traceability. Enter through continuous-flow phenol alkylation pilot systems offering 40% smaller footprints for just-in-time automotive resin delivery. For Investors and Strategic Acquirers: ECHA's tightening phenol classification restrictions are the leading indicator that integrated producers with captive cumene supply and in-house certification capabilities will outcompete merchant compounders. Over the projection horizon, vertically integrated mid-cap specialists in dihydroxybenzenes present acquisition targets. Monitor MEE enforcement intensity in Shandong-Zhejiang provinces for early signals of capacity rationalization and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cumene Supply | Captive feedstock secures margin capture against acetone price volatility for bisphenol A producers. |
| REACH Compliance Certification Investment | Third-party validation extends qualification timelines and raises rival's cost-of-entry in European markets. |
| Continuous-Flow Phenol Alkylation Deployment | Modular 40% smaller footprint plants enable just-in-time resin delivery to automotive tier-one suppliers. |
| Specialty-Grade Purity Capacity Expansion | Mitsui-grade catechol and hydroquinone specifications command price premiums in agrochemical value chains. |
| Long-Term Supply Agreement with Automotive OEMs | Fuel-efficiency mandates in China and India lock in phenolic resin offtake for brake friction materials. |
Methodological Framework
Document review covered SEC 10-K filings, customs and trade data from ACC and Cefic, and ECHA regulatory submissions, complemented by interviews with plant managers at cumene-to-phenol crackers, procurement leads at automotive OEMs, and technical R&D directors in specialty chemical divisions. Bottom-up triangulation across production capacity databases and top-down validation against downstream demand estimates informed volume and value outputs.
Cross-referencing historical pricing patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, end-use industry application, grade certification level, and regional production hub concentration. CAGRs derived from regression analysis of capacity utilization rates, feedstock cost trajectories, and regulatory implementation timelines.
Revisions become necessary when MEE dual carbon enforcement intensifies beyond modeled benchmarks or EFSA restrictions accelerate polycarbonate substitution beyond anticipated rates. Practitioners should monitor Shandong-Zhejiang operating rate disclosures and ECHA substance evaluation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Droppers Market
Solvents
Potassium Formate Market
Solvents
Dimethyl Ether (DME) Market
Solvents
2-Butanone Market
Solvents
Diethanolamine (DEA) Market
Solvents
Global Glycol Market
Solvents
Acetone Market
Solvents
Hexylene Glycol Market
Solvents
Isoamylene Market
Solvents
Piperylene Market
Solvents
Phenylacetonitrile Market
Solvents
Trichloroacetyl Chloride Market
Solvents
Hydrosol Market
Solvents
Nitromethane Market
Solvents
N-Pentyl Chloride Market
Solvents
India High Purity Solvents Market