
 Cumene Market | 2026-2036
Cumene Market Size, Share, and Industry Trends Forecast 2026-2036
Cumene Market Intelligence
Catalytic alkylation process intensification is rewriting cumene production economics across integrated petrochemical complexes. Shell plc leverages its Middle Eastern feedstock access to sustain cost-advantaged positions in Asian derivative markets. INEOS Group Limited anchors European supply through its Rotterdam and Lavéra manufacturing nodes. Chevron Phillips Chemical Company LLC competes on Gulf Coast shale-gas economics, dominating North American merchant cumene flows.
Cumene is an aromatic hydrocarbon produced via acid-catalyzed alkylation of benzene with propylene, typically yielding polymer-grade purity exceeding 99.5 weight percent for downstream phenol manufacture. The compound serves primarily as a chemical intermediate, with over 95 percent of global output converted to phenol and its co-product acetone for plastics, resins, and adhesive formulations. Phenol derivative demand leads the product type dimension, reflecting entrenched bisphenol A and phenolic resin consumption in construction and electronics end users. Acetone co-product flows are accelerating fastest within the application layer, driven by solvent demand in pharmaceutical and coatings sectors where direct sales channels capture premium pricing from qualified chemical industry buyers.
EPA air quality standards under the Clean Air Act constrain US refinery alkylation emissions, while REACH registration requirements in Europe mandate toxicological dossiers for cumene import and manufacture above one-tonne thresholds. China's MEE enforces dual carbon goals that elevate energy-efficiency benchmarks for naphtha crackers supplying propylene feedstock. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustments and chemical safety reclassifications reshape cost structures and trade routing decisions.
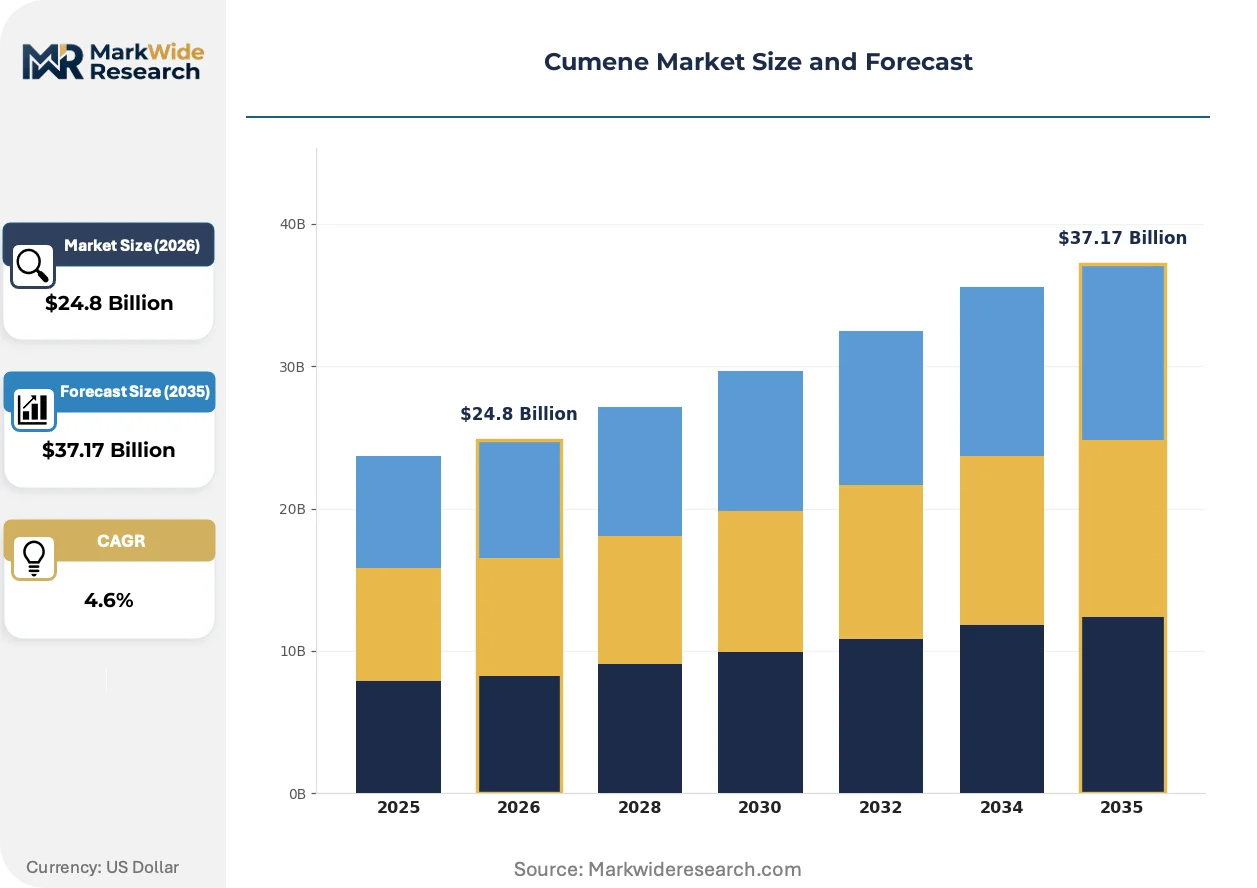
Market Dynamics
Catalytic alkylation process intensification is compressing unit capital costs and energy intensity across cumene manufacturing, redistributing competitive advantage toward integrated petrochemical complexes with captive benzene and propylene supply.
Growth Catalysts
- Phenol-to-bisphenol A supply chains:Electronics and construction sectors in China are absorbing cumene-derived phenol at accelerating rates for polycarbonate and epoxy resin production.
- REACH compliance premiums:European registrants with complete toxicological dossiers capture preferential supply relationships from risk-averse derivative manufacturers.
- Automotive lightweighting mandates:Germany and South Korea are specifying phenolic composite materials for interior and structural components, tightening specification tolerances for feedstock purity.
Market Restraints
- Propylene feedstock volatility:Naphtha cracker operating rates and PDH unit economics in the Middle East and Asia transmit price instability directly to cumene conversion margins.
- Acetone market absorption limits:Co-product offtake constraints in pharmaceutical and coatings sectors periodically force production curtailments at phenol-cumene integrated sites.
- EPA Clean Air Act alkylation emissions:US refiners face escalating compliance costs for benzene fugitive emissions and catalytic regeneration particulate controls.
Strategic Opportunities
- Bio-based benzene pathways:Pyrolysis oil upgrading and biomass gasification routes offer defossilized feedstock positioning for European green chemistry procurement tenders.
- Dual carbon goals alignment:China's MEE energy-efficiency benchmarks for crackers create first-mover advantage for producers with carbon capture integration at manufacturing nodes.
- Specialty acetone derivatives:High-purity solvent demand from pharmaceutical API manufacturing is opening direct sales channels bypassing traditional merchant distribution.
Industry Challenges
- Alkylation catalyst expertise scarcity:Operating knowledge for solid acid and zeolite systems is concentrated among retiring engineering cohorts at legacy facilities.
- Co-product balancing complexity:Phenol-acetone demand mismatches require continuous production scheduling optimization across multi-derivative integrated complexes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cumene Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cumene, Phenol, Acetone, Others Application: Plastics, Resins, Adhesives, Coatings End User: Chemical Industry, Automotive, Construction, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | BASF SE, Sumitomo Chemical Company, Limited, Shell plc, Saudi Basic Industries Corporation (SABIC), TotalEnergies SE, ExxonMobil Corporation, INEOS Group Limited, Chevron Phillips Chemical Company LLC, BP plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cumene Market Strategic Shifts & Innovations
Process analytical technology and advanced control systems are penetrating cumene manufacturing, enabling real-time optimization that was previously inaccessible to mid-scale producers.
Digital twin implementations are digitizing reactor performance prediction and catalyst lifecycle management across European and Asian cumene units. Operators at integrated phenol complexes are deploying these systems to compress unplanned shutdown intervals and extend catalyst replacement cycles. The technology is digitizing maintenance scheduling from calendar-based to condition-based protocols, reallocating engineering resources toward yield optimization.
REACH registration requirements are tightening substance identity specifications for cumene import and manufacture above one-tonne thresholds, mandating enhanced analytical characterization and supply chain transparency. ECHA's dossier evaluation program is elevating compliance costs for non-integrated traders and toll manufacturers. Specialty chemical distributors serving electronics-grade phenol markets are consolidating supplier bases to reduce registration duplication exposure.
Specification-driven procurement is displacing spot-market purchasing for electronics and pharmaceutical-grade phenol derivatives. Major polycarbonate manufacturers in East Asia are implementing supplier qualification programs with eighteen-month onboarding timelines. This pattern concentrates volume commitments toward backward-integrated producers with certified quality management systems and captive cumene supply.
Cumene Market Segmentation
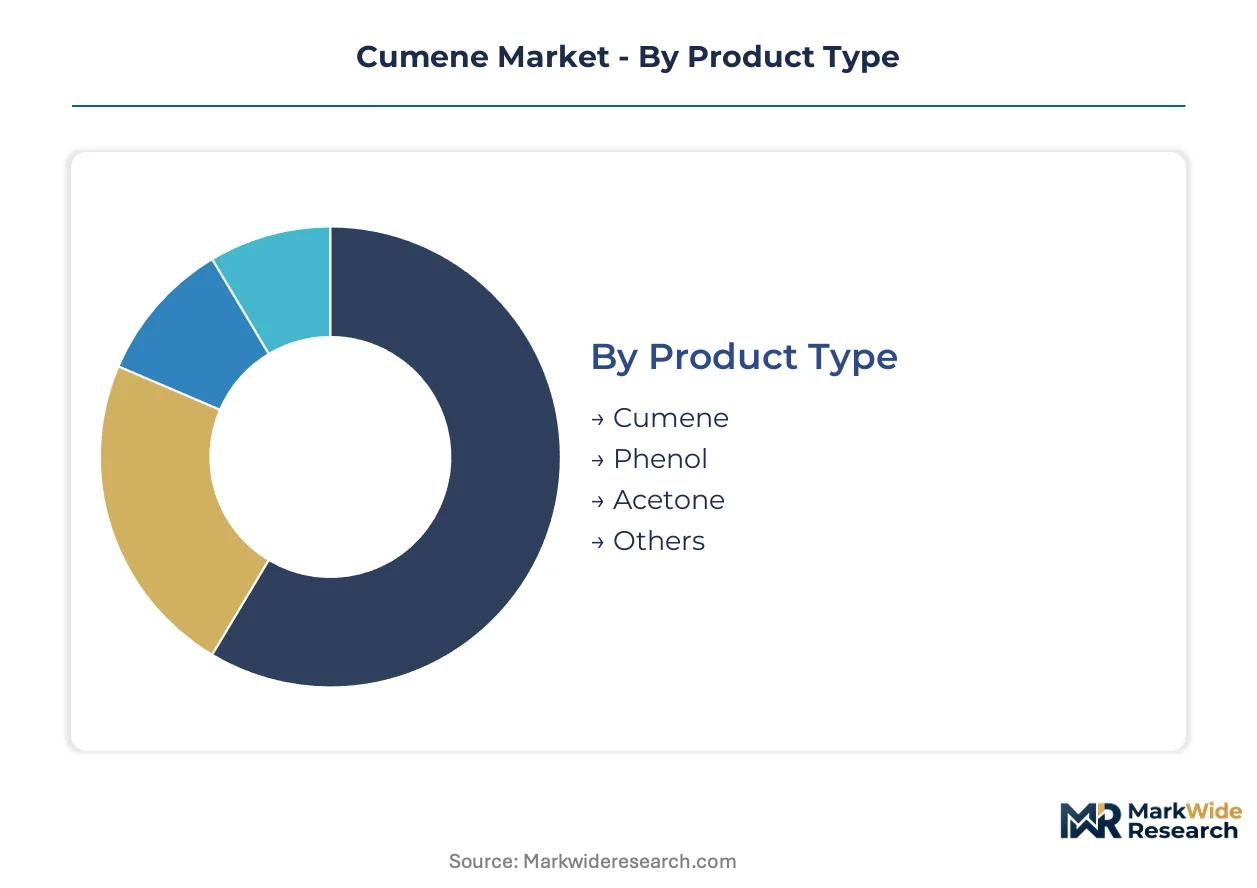
Cumene market segmentation reveals how derivative chemistry and procurement channels fragment value capture across integrated phenol complexes and merchant distribution networks. Understanding these dimensions exposes where specification premiums concentrate and where volume commoditization pressures margins.
Product Type:
Product type segmentation tracks purity grades and derivative positioning from refinery alkylation output through downstream chemical conversion.
- Cumene:Polymer-grade aromatic hydrocarbon exceeding 99.5 weight percent purity, produced via acid-catalyzed benzene alkylation with propylene. Refinery-integrated producers in the US Gulf Coast and Rotterdam cluster capture specification premiums through captive feedstock access and ISO-certified quality systems for electronics-grade phenol manufacturers.
- Phenol:Primary oxidation derivative serving bisphenol A and phenolic resin supply chains. Demand concentrates in China's polycarbonate and epoxy resin sectors where construction and electronics end users enforce eighteen-month supplier qualification timelines that favor backward-integrated producers with REACH-compliant dossiers.
- Acetone:Co-product from cumene oxidation with accelerating solvent demand in pharmaceutical API manufacturing and coatings formulation. Direct sales channels to qualified chemical buyers are bypassing traditional merchant distribution for high-purity grades.
- Others:Minor cumene derivatives including cumene hydroperoxide intermediates and specialty solvent formulations for niche industrial applications.
Cumene commands the established base. The steepest expansion runs through acetone.
Application:
Application segmentation maps how cumene-derived molecules enter distinct formulation chemistry with varying specification tolerances and pricing power.
- Plastics:Polycarbonate and epoxy resin production from bisphenol A consumes the dominant phenol derivative share. China's electronics manufacturing clusters and Germany's automotive lightweighting programs are tightening purity specifications for feedstock cumene.
- Resins:Phenolic resins for construction composites and foundry binders represent mature demand with volume contracting tied to housing cycle sensitivity in North America and Europe.
- Adhesives:Formaldehyde-phenol formulations for plywood and engineered wood products. South Korean construction sector procurement is specifying low-emission grades that propagate upstream to cumene purity requirements.
- Coatings:Epoxy and phenolic coating systems for marine and industrial protection. Solvent demand from pharmaceutical-grade coatings is opening premium direct sales channels for acetone co-product flows.
Plastics anchors volume concentration. Coatings is gaining share fastest through specification-driven procurement.
End User:
End user segmentation exposes how sector-specific regulatory exposure and integration economics reshape cumene offtake patterns.
- Chemical Industry:Integrated phenol-acetone producers and merchant derivative manufacturers constitute the primary demand channel. REACH registration requirements above one-tonne thresholds are consolidating supplier bases toward dossier-complete registrants.
- Automotive:Phenolic composite interior and structural components from Germany's KBA-mandated lightweighting programs and South Korean EV supply chains. Specification tolerances for feedstock purity are tightening beyond standard merchant grades.
- Construction:Bisphenol A for polycarbonate glazing and phenolic resins for insulation. China's property sector volatility is transmitting demand instability to cumene conversion scheduling.
- Electronics:Polycarbonate for consumer device housings and epoxy resins for printed circuit boards. East Asian manufacturers are implementing supplier qualification programs that concentrate volume toward certified quality management systems.
Chemical Industry commands the established base. Electronics is climbing the fastest through qualification-driven procurement consolidation.
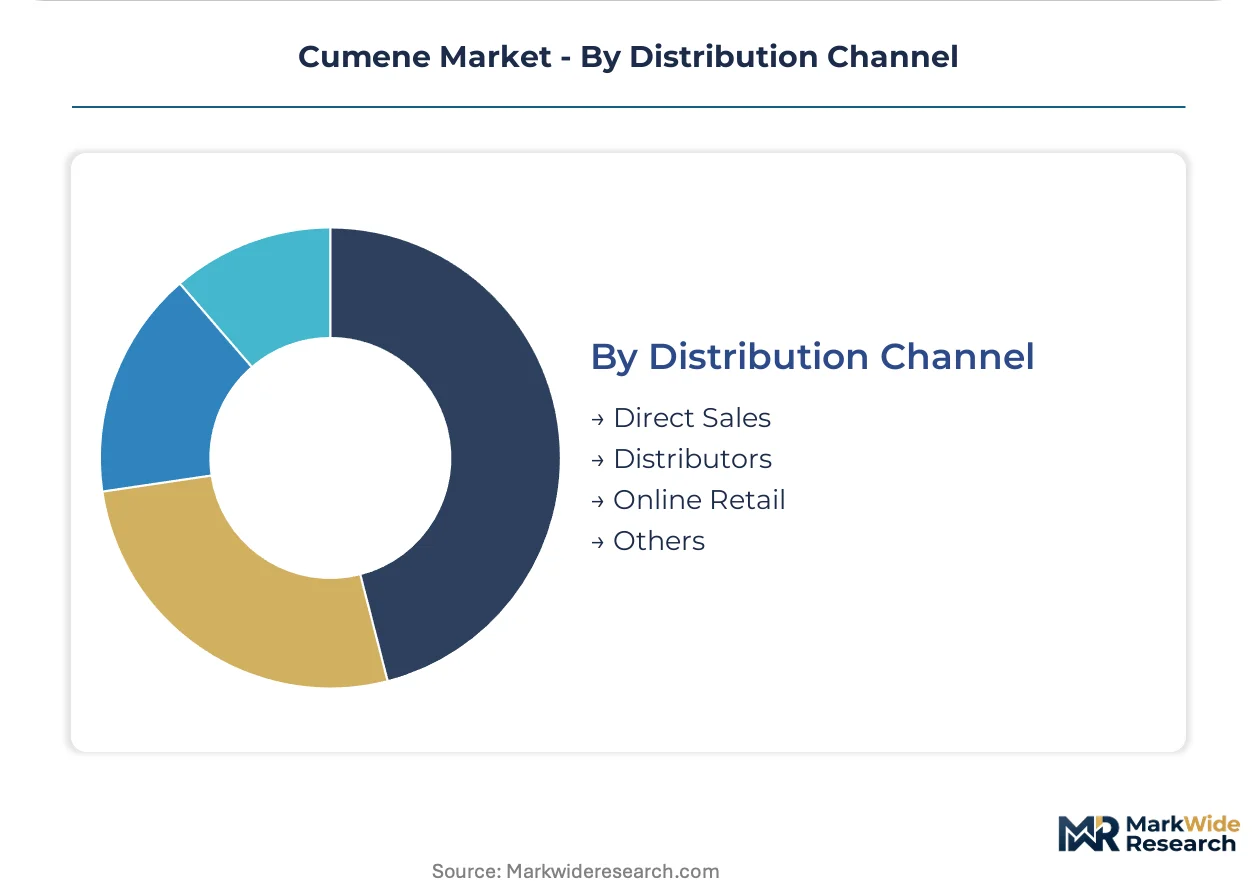
Distribution Channel:
Distribution channel segmentation tracks how custody transfer economics and regulatory liability allocate between producer-direct and intermediated flows.
- Direct Sales:Producer-to-manufacturer contracts for high-volume phenol and acetone offtake. Electronics-grade and pharmaceutical-grade specifications are concentrating here due to eighteen-month qualification timelines and REACH dossier requirements.
- Distributors:Specialty chemical distributors serving mid-scale derivative manufacturers and regional formulators. ECHA's dossier evaluation program is forcing consolidation as registration duplication costs escalate.
- Online Retail:E-procurement platforms for laboratory-scale and specialty solvent grades with expedited fulfillment requirements.
- Others:Toll manufacturing arrangements and terminal-to-terminal bulk transfers for integrated complex optimization.
Direct Sales commands the established base. Distributors face the steepest margin compression from registration cost escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics-grade phenol buyers in East Asia and automotive lightweighting programs in Germany concentrate cumene derivative demand. REACH dossier requirements and China's dual carbon goals are redistributing supplier advantage toward integrated producers with certified quality systems.
China
Polycarbonate manufacturing for consumer electronics and construction glazing absorbs the dominant phenol derivative share. MEE enforces dual carbon goals that elevate energy-efficiency benchmarks for naphtha crackers supplying propylene. The Yangtze River Delta clustering concentrates phenol-to-bisphenol A conversion capacity serving Samsung and BOE supply chains.
Germany
KBA-mandated automotive lightweighting programs specify phenolic composite materials for EV structural components. ECHA's REACH registration requirements mandate complete toxicological dossiers for cumene import above one-tonne thresholds. The Ludwigshafen industrial complex anchors European phenol derivative supply with backward-integrated cumene production.
United States
Gulf Coast shale-gas economics sustain cost-advantaged propylene feedstock for merchant cumene flows. EPA Clean Air Act standards constrain refinery alkylation emissions and benzene fugitive release limits. Houston and Port Arthur petrochemical corridors dominate North American phenol-acetone integrated manufacturing.
South Korea
EV battery enclosure and interior component programs drive phenolic resin specification tightening. MFDS pharmaceutical-grade solvent standards propagate upstream to acetone co-product purity requirements. The Ulsan petrochemical complex concentrates cumene oxidation capacity serving domestic automotive and electronics clusters.
Saudi Arabia
Middle Eastern feedstock access supports cost-competitive cumene export positioning into Asian derivative markets. The national industrial regulator enforces environmental compliance benchmarks for aromatics complex expansion. Jubail Industrial City hosts integrated phenol manufacturing nodes with captive benzene and propylene supply.
Cumene Market Key Industry Players
Channel-controlling players compete with product-specialist players across integrated phenol complexes and merchant distribution networks. The market structure consolidates around backward-integrated petrochemical majors with captive feedstock access and ISO-certified quality systems. Two strategic archetypes dominate: Gulf Coast shale-advantaged producers and Rotterdam-anchored European registrants with REACH-complete dossiers. Capacity expansion and strategic partnerships represent the primary competitive moves, with carbon capture integration emerging as a differentiation mechanism.
Within the integrated petrochemical tier, Shell plc and INEOS Group Limited exemplify divergent geographic anchoring strategies. Shell leverages Middle Eastern feedstock access to sustain Asian derivative market positioning, while INEOS occupies a dossier-complete registrant role across European supply chains. Chevron Phillips Chemical Company LLC represents Gulf Coast shale-gas economics in North American merchant cumene flows.
| Leading Market Players |
|---|
| BASF SE |
| Sumitomo Chemical Company, Limited |
| Shell plc |
| Saudi Basic Industries Corporation (SABIC) |
| TotalEnergies SE |
| ExxonMobil Corporation |
| INEOS Group Limited |
| Chevron Phillips Chemical Company LLC |
| BP plc |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp barge freight corridors transmit propylene feedstock cost volatility directly into cumene conversion margins, concentrating pricing power among integrated phenol producers with captive benzene supply while forcing merchant operators to absorb basis risk through formula-indexed contracts.
Pricing Analysis
Cost-plus contracts indexed to ICIS propylene and benzene spot assessments dominate cumene offtake agreements, with electronics-grade specifications commanding purity premiums over standard merchant grades. Price differentiation rests on REACH dossier completeness and ISO-certified quality systems rather than volume scale. Pricing pressure intensifies from acetone co-product absorption limits in pharmaceutical solvents, squeezing integrated complex economics. Mid-scale derivative manufacturers exhibit highest price sensitivity, while polycarbonate producers with eighteen-month qualification timelines accept specification premiums.
Supply Chain Analysis
Tariff exposure between US Gulf Coast exporters and Chinese phenol derivative manufacturers dominates supply chain risk calculus for merchant cumene flows. Manufacturing concentrates in the United States, Saudi Arabia, and South Korea, each leveraging shale-gas economics, Middle Eastern feedstock access, or EV supply chain proximity respectively. Raw material dependencies center on refinery-grade benzene, polymer-grade propylene, and solid acid alkylation catalysts. Distribution runs through long-term offtake contracts with direct producer-to-manufacturer custody transfer, bypassing intermediaries for high-purity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among backward-integrated polycarbonate manufacturers with eighteen-month supplier qualification programs, fragmenting merchant offtake channels and forcing supply consolidation toward dossier-complete registrants.
For Market Incumbents: Harden defensibility through carbon capture integration at Rotterdam and Gulf Coast manufacturing nodes before China's MEE energy-efficiency benchmarks propagate into trade barrier structures. Deepen captive propylene supply through PDH unit economics alignment. Lock electronics-grade qualification pipelines with East Asian polycarbonate producers to forestall merchant market commoditization.
For New Entrants and Emerging Players: India's underpenetrated pharmaceutical-grade acetone solvent market offers white-space entry with MFDS-equivalent purity positioning. Target toll manufacturing arrangements with European distributors facing REACH registration cost escalation. Pursue bio-based benzene pathway partnerships with pyrolysis oil upgrading technology providers to capture green chemistry procurement tenders.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core cumene oxidation assets lacking backward benzene integration. Five-to-ten year viability favors producers with dual carbon goals alignment and carbon capture deployment. Watch for acetone market absorption inflections forcing phenol-cumene integrated site curtailments as distressed entry signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | PDH unit economics at Gulf Coast and Jubail sites compress feedstock cost volatility for phenol-acetone complexes. |
| Carbon Capture Integration | China's MEE dual carbon benchmarks create first-mover advantage for Rotterdam and Antwerp manufacturing nodes. |
| Long-term Supply Agreement with Electronics Manufacturers | Samsung and BOE supply chains in Yangtze River Delta enforce eighteen-month qualification timelines concentrating volume. |
| Green Manufacturing Transition | Pyrolysis oil upgrading routes position European producers for defossilized benzene procurement tenders. |
| Joint Venture in Underpenetrated Markets | Indian pharmaceutical solvent demand opens toll manufacturing partnerships bypassing REACH registration duplication costs. |
Research Approach
Initial hypotheses were tested against primary input from phenol complex plant managers, procurement leads at polycarbonate OEMs, specialty chemical distribution channel partners, and technical R&D directors at alkylation catalyst suppliers, then refined through customs trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical majors, and EPA Clean Air Act compliance disclosures. Bottom-up capacity modeling and top-down derivative demand estimation were triangulated to validate volume outputs.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning purity grade tier, end-use industry concentration in plastics versus coatings, packaging format for acetone solvent grades, and regional production hub clustering. CAGRs were derived from derivative demand elasticity modeling and feedstock cost pass-through coefficients, incorporating naphtha cracker operating rate assumptions and PDH unit economics as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive carbon capture deployment by Gulf Coast shale-advantaged producers or accelerated bio-based benzene commercialization by European registrants would shift outcomes from baseline trajectories. Material shifts in China's property sector polycarbonate absorption or REACH substance identity reclassifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Linear Mercaptans Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Coagulant Market
Chemicals
India Ethoxylates Market
Chemicals
Chemical As a Service Market
Chemicals
Ethylenediaminetetraacetic Acid Market
Chemicals
Methanol Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Household Insecticides Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
P-Ethylphenol Market
Chemicals
Whitening Ingredients Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
Hexachloroethane Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Europe Calcium Peroxide Market