
 Europe Starch Derivatives Market | 2026-2036
Europe Starch Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Starch Derivatives Market Foresight
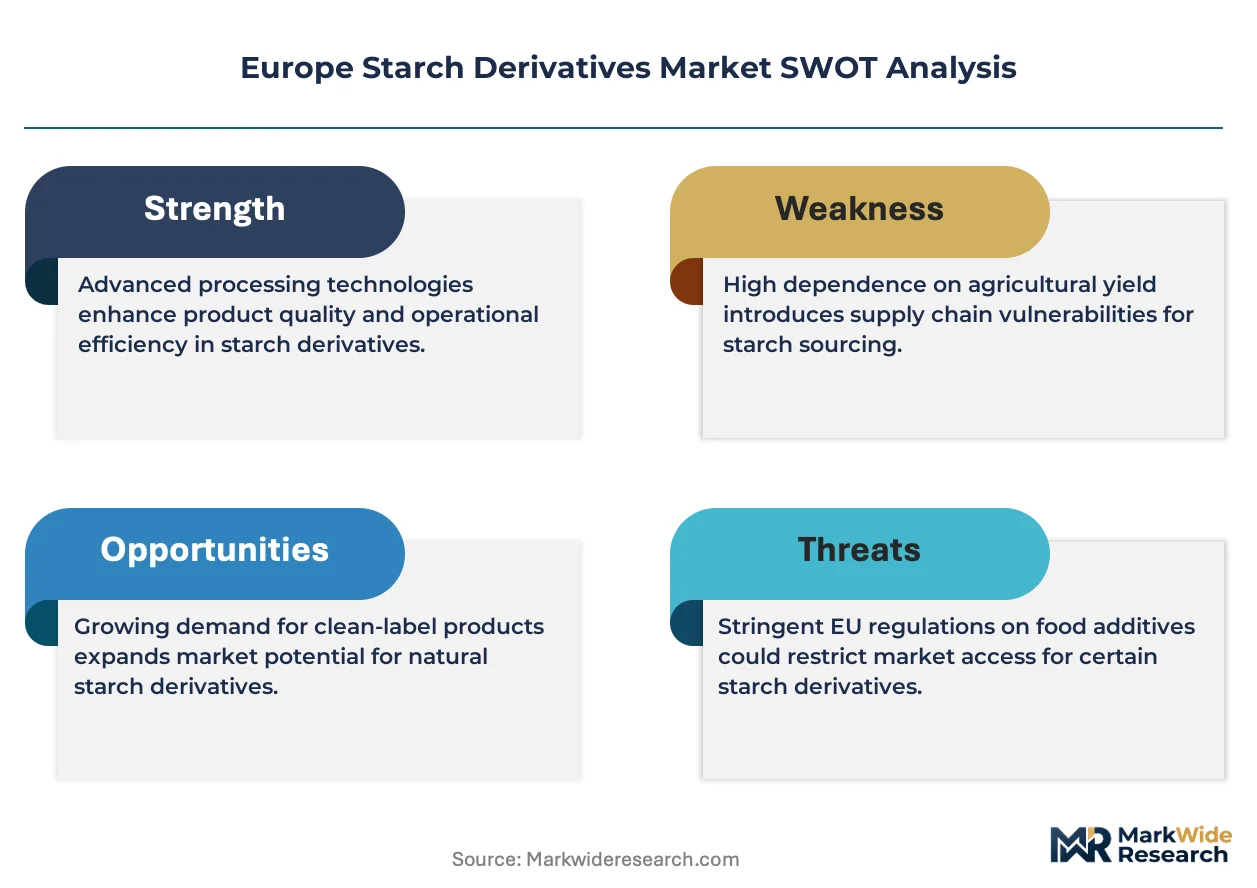
Ingredient formulation services is reconfiguring margin pools across the European starch derivatives value chain. Cargill, Incorporated leverages its integrated European grain supply network to dominate modified starch production for food manufacturers. Roquette Frères sustains technology leadership in pea-derived starch alternatives, while Coöperatie AVEBE U.A. anchors potato starch derivative output from its Dutch cooperative base.
Starch derivatives encompass chemically, physically, or enzymatically altered starch molecules with modified gelatinization temperatures, viscosity profiles, or digestibility characteristics, produced through acid hydrolysis, oxidation, or etherification processes for binding, thickening, and stabilizing applications across food, pharmaceutical, and industrial sectors. Modified starch commands the largest value share among product types due to its versatility in processed food texture modification. Liquid starch competes aggressively in textile sizing applications where European textile producers seek biodegradable alternatives to petrochemical binders.
EFSA maintains stringent purity standards for food-grade starch derivatives under EU food additive regulations, while REACH governs chemical modification processes and environmental release thresholds for industrial starch applications. The EU Green Deal bioeconomy framework incentivizes enzymatic conversion pathways that reduce processing energy intensity. Stakeholders must monitor evolving ECHA classification reviews for oxidized starch derivatives that could trigger new handling requirements across pharmaceutical and personal care supply chains.
Market Dynamics
Enzymatic processing technologies are compressing energy intensity thresholds across European starch derivative facilities, redirecting capital expenditure away from acid hydrolysis infrastructure toward bioeconomy-compliant conversion pathways.
Growth Catalysts
- EU Green Deal bioeconomy targets:Enzymatic conversion pathways receive preferential financing through circular economy funds, accelerating plant retrofits in the Netherlands and Germany.
- Clean-label bakery demand:Food manufacturers in France and Belgium substitute modified starches for synthetic emulsifiers to meet retailer clean-label mandates.
- Textile sector biodegradability requirements:European textile producers replace petrochemical sizing agents with liquid starch derivatives to satisfy industrial wastewater discharge standards.
Market Restraints
- Potato supply concentration:Dutch and German cooperative processing networks control raw material flows, creating input bottlenecks during seasonal harvest volatility.
- REACH chemical modification compliance:Oxidized starch derivative classifications under ECHA review threaten new handling protocols for pharmaceutical and personal care applications.
- Native starch price arbitrage:Wheat and maize input cost swings compress margin stability for modified starch producers serving commodity food accounts.
Strategic Opportunities
- Pea-derived starch alternatives:Roquette Frères' protein-starch fractionation technology opens formulation white space in plant-based meat and dairy analogues across Northern Europe.
- Pharmaceutical excipient certification:EMA quality guidelines for starch-based tablet binders create premium pricing tiers for GMP-certified producers.
- Industrial biotechnology convergence:Precision fermentation partnerships between enzyme suppliers and derivative manufacturers reduce conversion yield variability.
Industry Challenges
- Specialized enzymology talent scarcity:European facilities compete for protein engineers capable of optimizing amylase performance under continuous processing conditions.
- Legacy acid hydrolysis asset stranding:Plants with sunk capital in chemical modification infrastructure face accelerated depreciation against enzymatic greenfield capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Starch Derivatives Market |
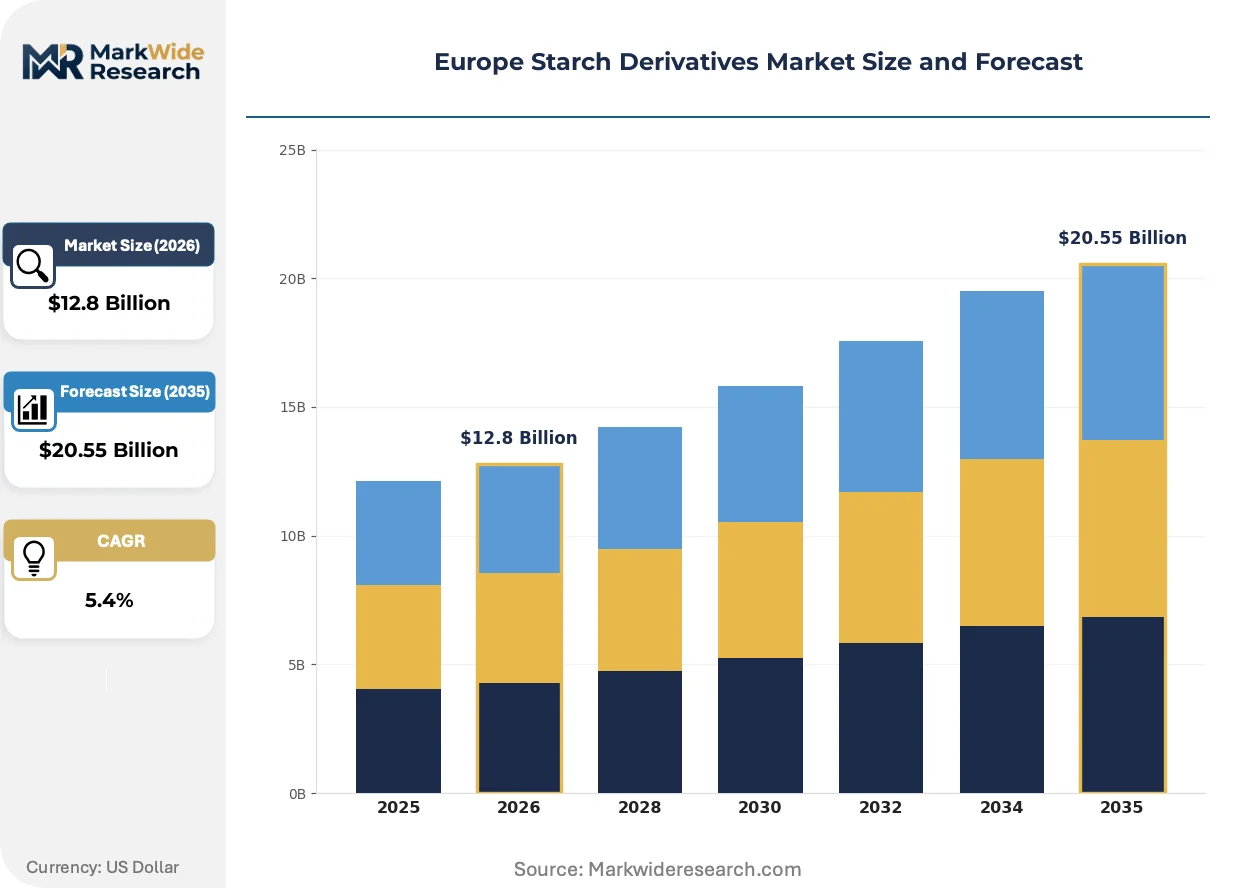
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Starch, Modified Starch, Dextrins, Starch Esters Application: Food Processing, Pharmaceutical, Personal Care, Textile End User: Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Textile Producers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Cargill, Incorporated, Tereos SCA, Ingredion Incorporated, Archer Daniels Midland Company, Coöperatie AVEBE U.A., Roquette Frères, Tate & Lyle PLC, AGRANA Beteiligungs-AG, Emsland Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Starch Derivatives Market Shifts & Advancements
Dual-function starch derivatives that bridge food texture modification with pharmaceutical controlled-release properties are attracting cross-sector R&D investment from ingredient houses with multi-industry formulation expertise.
Enzymatic modification systems is hybridizing acid-thinned and oxidized starch functionalities into single-process outputs. Pharmaceutical excipient buyers in Germany and Switzerland adopt these hybrid grades to reduce supplier qualification burdens. The technology is compressing the traditional separation between food-grade and pharmaceutical-grade production lines.
REACH authorization requirements for oxidized starch derivatives are forcing reformulation timelines across personal care applications. ECHA's substance evaluation roadmap now includes modified starches previously exempt from full registration dossiers. Cosmetic compounders in France and Italy accelerate substitution testing to preempt supply interruptions.
Direct procurement relationships between bakery chains and starch derivative producers are disintermediating traditional ingredient distributors. Large retail-owned bakeries in the Netherlands and Belgium negotiate volume commitments with cooperative processors for clean-label modified starches. This channel shift compresses distributor margins while locking in formulation exclusivity for buyer accounts.
Europe Starch Derivatives Market Segmentation
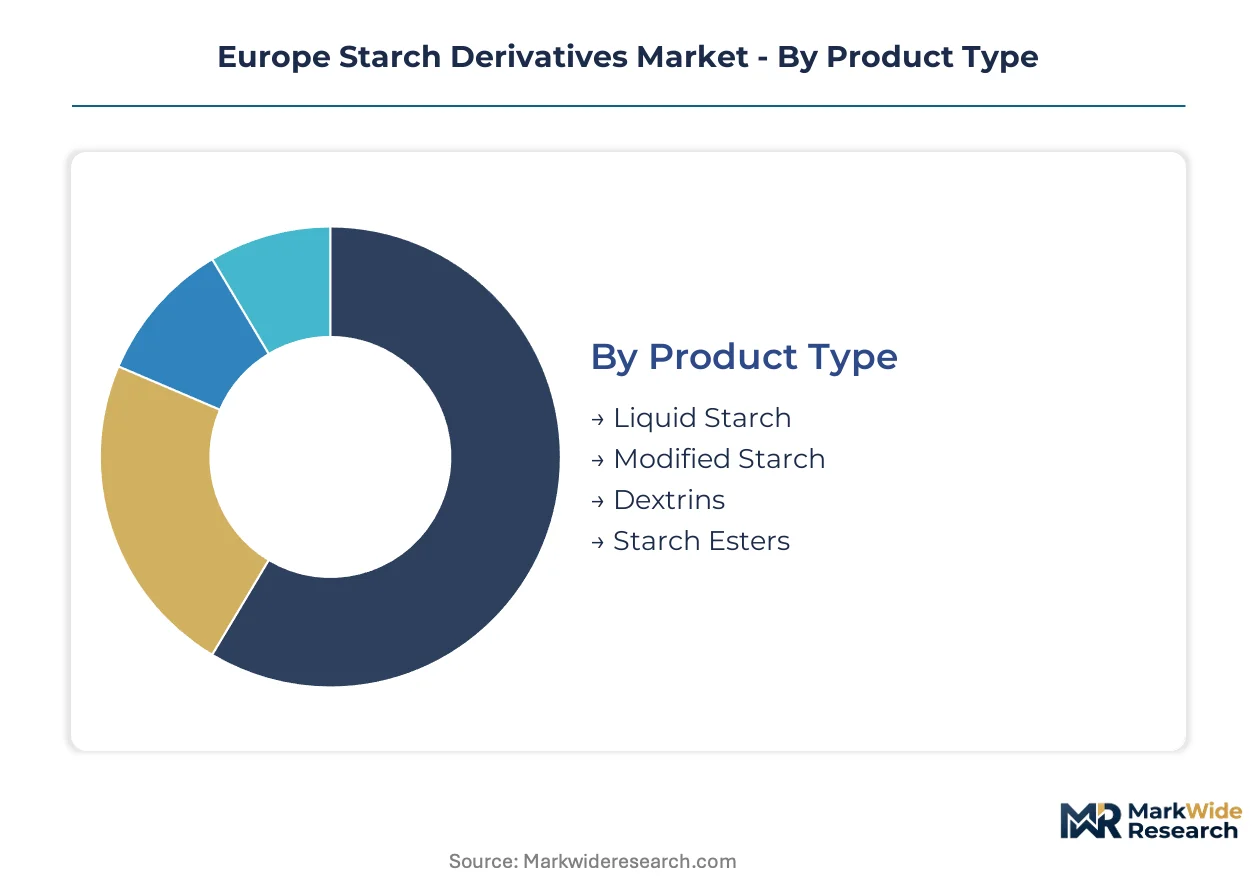
European starch derivative procurement patterns diverge sharply across product categories, with enzymatic modification capabilities and clean-label compliance requirements reshaping buyer segmentation priorities. Application-specific purity standards and REACH classification uncertainties further fragment sourcing strategies across food, pharmaceutical, and industrial end-uses.
Product Type:
Modified starch spans the widest functional spectrum across European food and pharmaceutical applications, from texture modification to controlled-release matrix systems.
- Modified Starch:Chemically, physically, or enzymatically altered starch molecules with customized gelatinization temperatures and viscosity profiles. German and French food processors dominate demand as clean-label bakery applications displace synthetic emulsifiers under retailer mandates.
- Liquid Starch:Pre-gelatinized starch suspensions optimized for industrial sizing and coating operations. European textile producers in Belgium and Italy accelerate adoption to meet industrial wastewater biodegradability standards and replace petrochemical binders.
- Dextrins:Low-molecular-weight starch hydrolysates produced through controlled thermal or acid conversion. Adhesive manufacturers and food coating applications in the Netherlands drive volume.
- Starch Esters:Esterified derivatives with enhanced hydrophobicity and emulsification properties. Pharmaceutical excipient buyers in Switzerland specify these grades for tablet binder applications requiring EMA quality certification.
The dominant share belongs to Modified Starch, while Liquid Starch is closing the gap fastest.
Application:
Cost tier stratification separates commodity food accounts from premium pharmaceutical and personal care specifications.
- Food Processing:Texture modification, stabilization, and clean-label reformulation across bakery, dairy, and convenience food segments. Dutch and Belgian retail-owned bakeries negotiate direct procurement contracts with cooperative processors for modified starch supply security.
- Pharmaceutical:Tablet binders, disintegrants, and controlled-release excipients subject to EMA GMP guidelines. German and Swiss buyers command premium pricing tiers for certified production lines.
- Personal Care:Rheology modifiers and film-forming agents in cosmetics and personal hygiene products. French and Italian compounders face reformulation pressure from ECHA oxidized starch classification reviews.
- Textile:Biodegradable sizing agents replacing polyvinyl alcohol and acrylic binders. European producers prioritize liquid starch derivatives to satisfy discharge permit requirements.
Food Processing retains volume leadership, though Pharmaceutical applications command the steepest margin expansion trajectory.
End User:
Customer type determines specification intensity, with pharmaceutical and cosmetic buyers imposing stricter purity and documentation requirements than commodity food accounts.
- Food Manufacturers:Industrial bakeries, dairy processors, and convenience food producers seeking functional alternatives to synthetic additives. Large Dutch and Belgian chains disintermediate traditional distributors through direct cooperative relationships.
- Pharmaceutical Companies:Dosage form developers requiring excipient certification under EMA quality guidelines. German facilities drive demand for GMP-certified modified and esterified grades.
- Cosmetic Brands:Personal care compounders reformulating around REACH authorization uncertainties for oxidized derivatives. French and Italian markets show highest substitution testing activity.
- Textile Producers:European weaving and finishing operations converting sizing operations to biodegradable starch systems. Belgian and Italian mills lead liquid starch adoption rates.
Food Manufacturers anchor procurement volumes, while Pharmaceutical Companies are expanding specification premiums fastest.
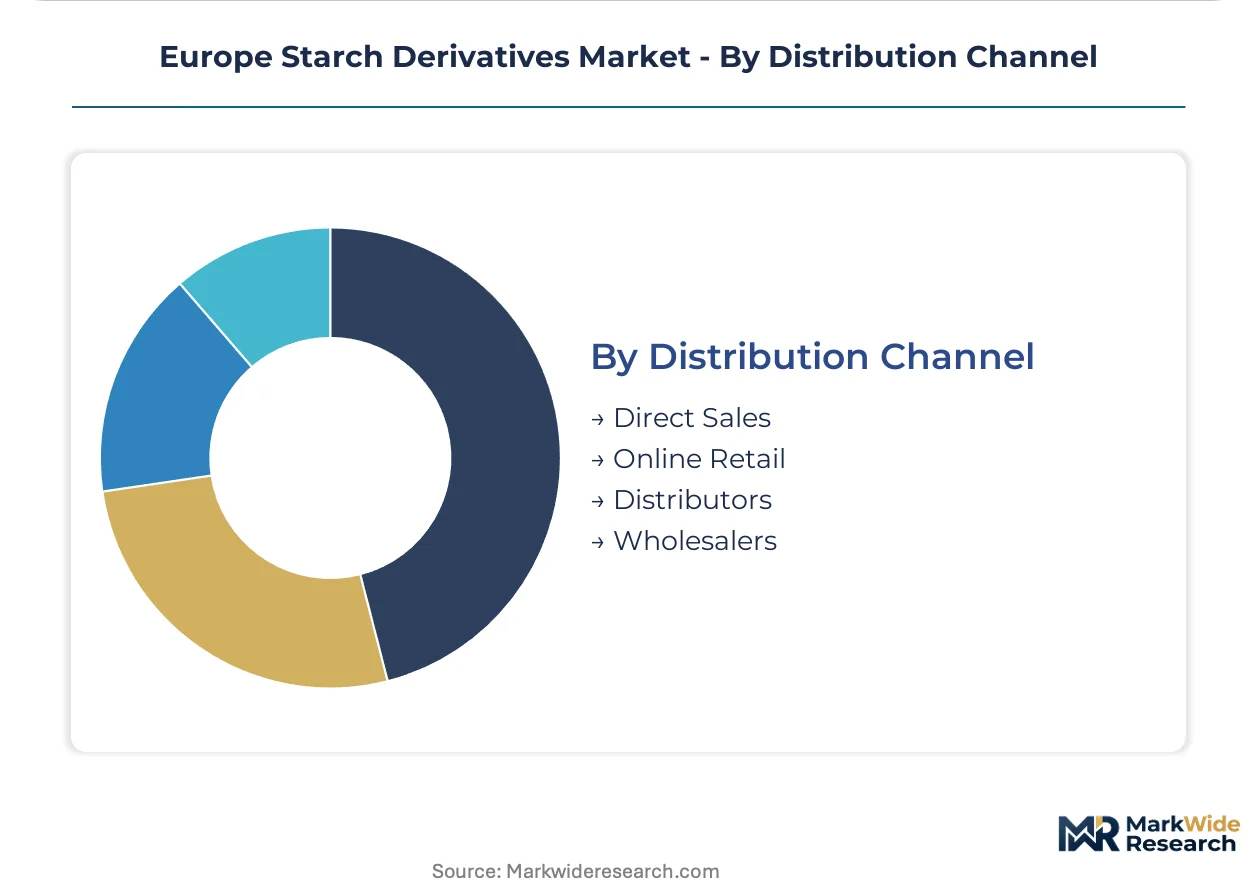
Distribution Channel:
Supply concentration in Dutch and German cooperative processing networks shapes channel power dynamics across the value chain.
- Direct Sales:Volume commitments between starch derivative producers and large food manufacturing accounts. Netherlands and Belgium bakery chains lock in formulation exclusivity through captive supply arrangements.
- Distributors:Traditional ingredient distributors facing margin compression as direct procurement expands. Smaller food processors and regional cosmetic brands remain dependent on this channel.
- Wholesalers:Bulk handling of commodity-grade liquid and modified starches for industrial textile and paper applications. Seasonal harvest volatility creates intermittent supply bottlenecks.
- Online Retail:Emerging channel for specialty and small-volume pharmaceutical and cosmetic grades. Limited penetration due to documentation and certification requirements.
Direct Sales commands the largest value flow, though Distributors retain relevance for fragmented buyer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Europe diverge sharply by application intensity. German pharmaceutical buyers command premium-certified grades, while Dutch and Belgian food processors drive volume through direct cooperative procurement. Southern European textile mills prioritize liquid starch biodegradability to satisfy wastewater discharge mandates.
Germany
Pharmaceutical excipient demand and clean-label bakery reformulation dominate German starch derivative consumption. EMA GMP guidelines for tablet binders create premium pricing tiers that attract certified production investment. The Rhine-Main industrial corridor hosts concentrated pharmaceutical manufacturing that specifies modified and esterified starch grades for controlled-release formulations.
Netherlands
Cooperative potato starch processing and direct retail bakery procurement define Dutch market structure. EU Green Deal bioeconomy funds accelerate enzymatic plant retrofits in the northern agricultural provinces. The Gelderland processing cluster anchors AVEBE's cooperative output, supplying modified starches under captive supply arrangements with Belgian and Dutch retail bakery chains.
France
Pea-derived starch alternatives and cosmetic reformulation pressure shape French demand patterns. ANSM oversight of cosmetic ingredients compounds REACH authorization uncertainties for oxidized derivatives. The Hauts-de-France region concentrates Roquette Frères' protein-starch fractionation capacity, serving plant-based meat analogue developers across Northern Europe.
Belgium
Textile sizing biodegradability requirements and food manufacturing direct procurement drive Belgian starch derivative uptake. Industrial wastewater discharge standards under Flemish environmental regulation accelerate liquid starch substitution for petrochemical binders. The Kortrijk textile cluster leads European adoption of biodegradable sizing agents for weaving operations.
Switzerland
Pharmaceutical excipient certification and precision quality standards concentrate Swiss demand at the premium tier. Swissmedic oversight of drug manufacturing inputs reinforces EMA quality guidelines for starch-based tablet binders. The Basel pharmaceutical hub commands GMP-certified modified starch grades with documentation requirements that exclude commodity suppliers.
Europe Starch Derivatives Market Competitive Landscape
Capability concentration sits with enzymatic technology specialists; scale advantage sits with integrated grain processors with captive raw material access. The European starch derivative sector structures around three archetypes: cooperative potato processors with regional supply lock-in, diversified grain traders with backward integration into modification capacity, and plant-protein fractionation specialists with dual-output starch streams. Dominant competitive moves include direct procurement relationship formation with large food manufacturing accounts and enzymatic processing asset deployment to capture EU Green Deal financing.
Among integrated grain processors, Cargill, Incorporated and Archer Daniels Midland Company occupy positions defined by transcontinental supply network control. Cooperative specialists exemplified by Coöperatie AVEBE U.A. anchor regional potato starch output through member-governed processing infrastructure. Plant-derived ingredient developers represented by Roquette Frères sit within a technology tier where protein-starch coproduction capabilities open formulation white space in alternative protein applications.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tereos SCA |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Coöperatie AVEBE U.A. |
| Roquette Frères |
| Tate & Lyle PLC |
| AGRANA Beteiligungs-AG |
| Emsland Group |
| Others |
Supply & Pricing Matrix
Dutch and German cooperative potato processing networks control upstream raw material flows, concentrating margin capture with member-governed processors while downstream food manufacturers face compressed bargaining power during seasonal harvest volatility.
Pricing Analysis
Long-term offtake contracts between cooperative processors and large retail bakery chains dominate European starch derivative procurement, locking in volume commitments that insulate sellers from spot market wheat and maize price swings. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certifications separates EMA GMP-certified excipients commanding premium tiers from commodity modified starches facing cost compression. Pricing pressure stems from native starch input cost arbitrage as wheat and maize price volatility squeezes margin stability for modified starch producers serving commodity food accounts. Pharmaceutical companies exhibit the lowest price sensitivity due to excipient certification requirements, while textile producers show highest sensitivity as they benchmark liquid starch against petrochemical binder alternatives.
Supply Chain Analysis
Tariff exposure between Ukraine and European Union member states threatens wheat starch input flows, amplifying raw material cost uncertainty for processors dependent on Black Sea grain supplies. Supply concentration spans the Netherlands, Germany, and Belgium, where cooperative and integrated grain processing infrastructure draws from regional potato, wheat, and maize harvests. Key inputs include native starch feedstocks, enzymatic conversion catalysts, and chemical modification reagents. Single-source vulnerability runs through Dutch potato starch cooperatives controlling seasonal output volumes. Distribution runs through direct sales relationships with large food manufacturing accounts, supplemented by traditional ingredient distributors serving fragmented cosmetic and pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European starch derivatives market is cycling through a recovery phase as EU Green Deal bioeconomy financing redirects capital toward enzymatic processing retrofits and clean-label reformulation demand stabilizes input offtake.
For Market Incumbents: Insulate margin pools by deepening captive supply relationships with retail-owned bakery chains through exclusive formulation partnerships, while accelerating enzymatic asset deployment to capture circular economy fund access before legacy acid hydrolysis infrastructure faces accelerated depreciation. Prioritize EMA GMP certification investment for pharmaceutical excipient lines to defend premium pricing tiers against commodity-grade competitors. For New Entrants and Emerging Players: Pea-derived starch alternatives for plant-based meat analogues in Northern Europe represent the most penetrable entry point, given Roquette Frères' technology leadership has not fully saturated formulation white space. Mid-scale enzymatic processing capacity in Belgium and France offers second-mover positioning to serve cosmetic compounders reformulating around REACH authorization uncertainties. A technical service-led go-to-market approach differentiates against commodity traders. For Investors and Strategic Acquirers: Capital is best deployed toward enzymatic technology specialists with demonstrated amylase optimization capabilities and existing EU bioeconomy compliance infrastructure, as these assets command scarcity premiums in a talent-constrained environment. Over the medium-term horizon, acquisition targets should demonstrate dual-output protein-starch fractionation technology or pharmaceutical excipient certification pathways. Monitor ECHA classification decisions for oxidized starch derivatives as the critical inflection signal for personal care segment supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Retrofit | EU Green Deal bioeconomy funds accelerate plant conversions in Dutch and German facilities. |
| Pharmaceutical Excipient Certification | EMA GMP guidelines create premium pricing tiers for certified modified starch producers. |
| Direct Procurement Relationship Formation | Retail-owned bakery chains in Belgium and Netherlands lock in supply security through captive arrangements. |
| Pea-Starch Fractionation Capacity Expansion | Roquette Frères' technology opens formulation white space in alternative protein applications. |
| REACH Compliance Reformulation Partnership | French and Italian cosmetic compounders require substitution testing support for oxidized derivative alternatives. |
Research Methodology
A standing panel of plant operations managers, ingredient procurement leads at food manufacturers, pharmaceutical excipient buyers, and enzymatic technology R&D directors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with cooperative processor executives and downstream formulation scientists, validated against customs trade data, EFSA novel food approval registers, ECHA substance evaluation dossiers, and SEC filings of integrated grain traders. Bottom-up volume modeling across product grades and applications triangulated with top-down macroeconomic demand drivers.
Scenario-bracketing anchored the analytical framework, with demand trajectories tested against EU Green Deal implementation pace and EMA quality guideline enforcement intensity across the projection horizon. Segmentation dimensions modeled included modification technology type, application purity tier, end-use industry, and regional production hub concentration. CAGRs were derived from installed capacity utilization rates and buyer substitution elasticity parameters, incorporating enzymatic conversion yield improvements and clean-label mandate adoption curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in energy cost trajectories and agricultural commodity price volatility would shift the trajectory of processing margin expansion. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Europe Molecular Sieve Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market