
 Gypsum-Free Cement Market | 2026-2036
Gypsum-Free Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Gypsum-Free Cement Market Analytics
Calcined clay is restructuring product economics in binder formulations. Knauf AG leverages vertical integration across raw material sourcing to sustain cost advantages in specialty cement production. Saint-Gobain anchors its position through R&D intensity in alternative binder chemistry. Tarmac competes on manufacturing scale in the rapid-setting segment.
Gypsum-free cement denotes hydraulic binders formulated without calcium sulfate dihydrate, typically employing calcined clay, limestone fines, or pozzolanic supplements to achieve controlled setting and sulfate resistance. These formulations target environments where gypsum contamination risks structural degradation or where reduced embodied carbon meets project specifications. The residential construction application dominates volume flows, while infrastructure development represents the fastest-growing category as public agencies specify lower-carbon alternatives for heavy civil works. Rapid-setting products command premium positioning in repair works where downtime minimization justifies higher unit economics.
The EPA oversees emissions disclosure for cement manufacturing in the United States, while REACH governs chemical safety in European binder formulations and China's MEE enforces dual carbon goals for building material producers. Regulatory pressure on embodied carbon intensifies specification requirements across public procurement channels. Stakeholders must monitor evolving compliance thresholds to align product portfolios with jurisdiction-specific mandates.
Market Dynamics
Calcined clay substitution is compressing raw material costs while China's MEE enforcement on dual carbon goals accelerates specification changes across public procurement channels.
Growth Catalysts
- India's urban corridor mandates:State governments in Maharashtra and Karnataka specify low-carbon binders for metro rail and affordable housing projects, creating volume anchors for specialty cement producers.
- REACH compliance in European infrastructure:Chemical safety disclosures for construction materials favor gypsum-free formulations with cleaner hazard profiles in Dutch and German public tenders.
- Limestone calcination process refinement:Flash calcination technology reduces energy intensity in kaolinitic clay processing, narrowing the cost gap with conventional Portland cement.
Market Restraints
- Kaolin supply concentration:High-purity clay deposits cluster in Brazil and Ukraine, exposing formulators to geopolitical disruption and freight cost volatility.
- Technical limitation in freeze-thaw performance:Calcined clay blends exhibit reduced durability in Nordic climate cycles, restricting specification in Scandinavian bridge and tunnel projects.
- Substitution threat from geopolymers:Alkali-activated binders compete for the same low-carbon infrastructure contracts with faster strength development profiles.
Strategic Opportunities
- Vietnam's industrial zone expansion:Foreign manufacturing investment in Binh Duong and Dong Nai provinces drives warehouse and factory construction demand for rapid-setting repair cements.
- Indonesia's trans-Java toll road program:Public-private partnership structures for coastal highway segments specify sulfate-resistant formulations in saline groundwater zones.
- Technology convergence with carbon capture:Integration of direct air capture systems with calcination kilns enables negative-emission cement claims for premium infrastructure bids.
Industry Challenges
- Materials science talent scarcity:Formulation chemists with combined expertise in clay mineralogy and hydraulic binder kinetics command premium compensation, constraining R&D team scaling.
- Certification timeline compression:EN 197-5 validation for calcined clay cements requires 90-day strength testing protocols that delay product launches by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gypsum-Free Cement Market |
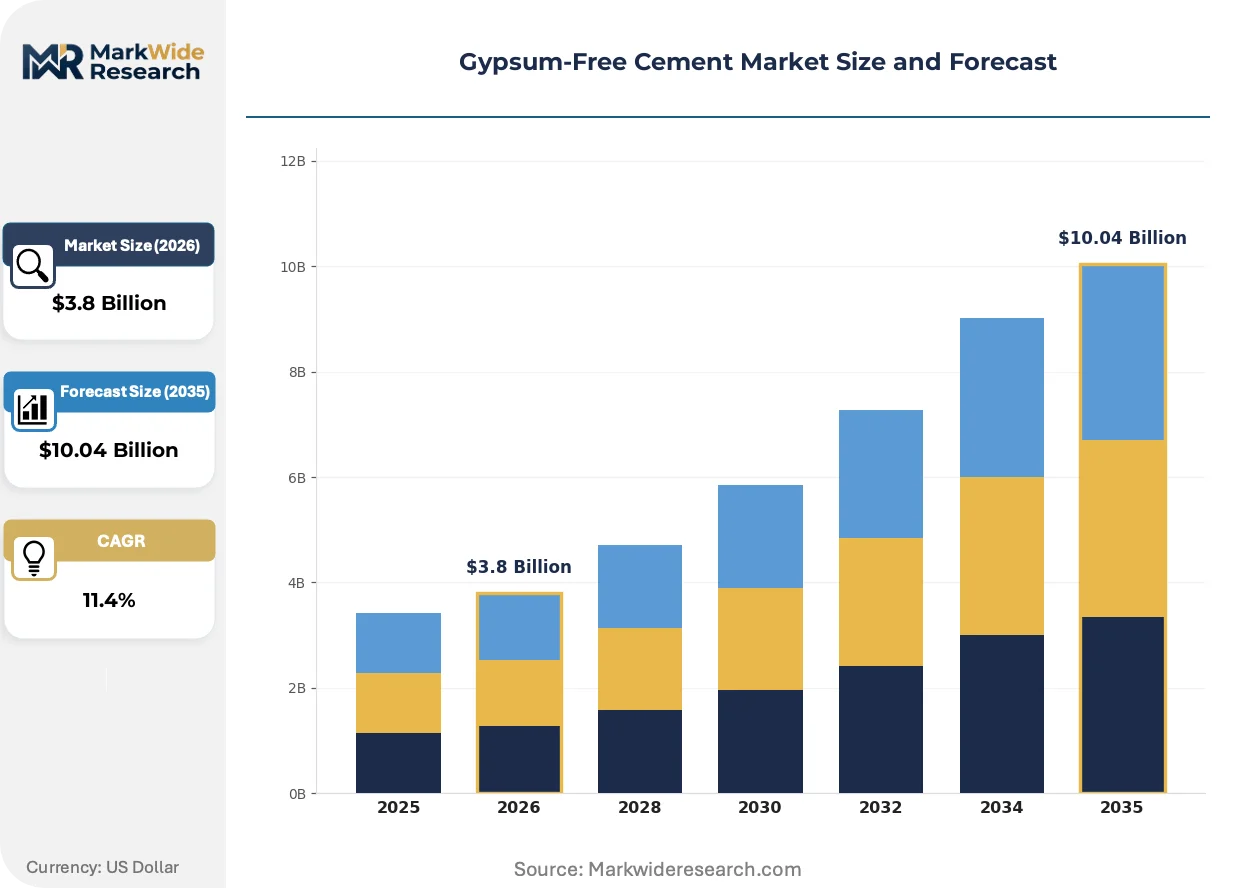
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance, Rapid-Setting, Self-Compacting, Lightweight Application: Residential Construction, Commercial Projects, Infrastructure Development, Repair Works End User: Construction Firms, Builders, Contractors, DIY Enthusiasts Distribution Channel: Online Retail, Wholesale Distributors, Specialty Stores, Direct Sales |
| Companies Covered | Knauf AG, Saint-Gobain, Tarmac, Yoshino Gypsum Co. Ltd., Georgia Pacific, American Gypsum, Jonoub Gypsum, Global Mining Company, Gypsona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gypsum-Free Cement Market Evolving Landscape
Digital quality control and alternative feedstock sourcing are compressing production timelines while regulatory disclosure requirements reshape competitive positioning across procurement channels.
Calcined clay activation technology is decentralizing binder production economics. Mobile calcination units enable on-site clay processing at quarry locations, eliminating intermediate freight legs. Regional cement producers in Indonesia and Thailand are deploying containerized systems to serve dispersed infrastructure projects. This distributed model is decentralizing supply chain control away from integrated multinationals toward mid-scale regional operators.
China's GB standards on low-carbon building materials now mandate embodied carbon disclosure for cement used in state-funded construction. The MEE enforcement mechanism ties procurement eligibility to verified carbon intensity thresholds. Domestic producers are reformulating product lines to qualify for Beijing-Shanghai high-speed rail expansion segments and Xiong'an New Area development contracts.
Direct contracting between project developers and specialty cement producers is bypassing traditional distributor networks in Southeast Asia. Large residential developers in Ho Chi Minh City and Bangkok now specify binder chemistry directly, unbundling technical service from material supply. This channel shift concentrates volume with formulators capable of custom blend engineering rather than commodity traders.
Gypsum-Free Cement Market Segmentation
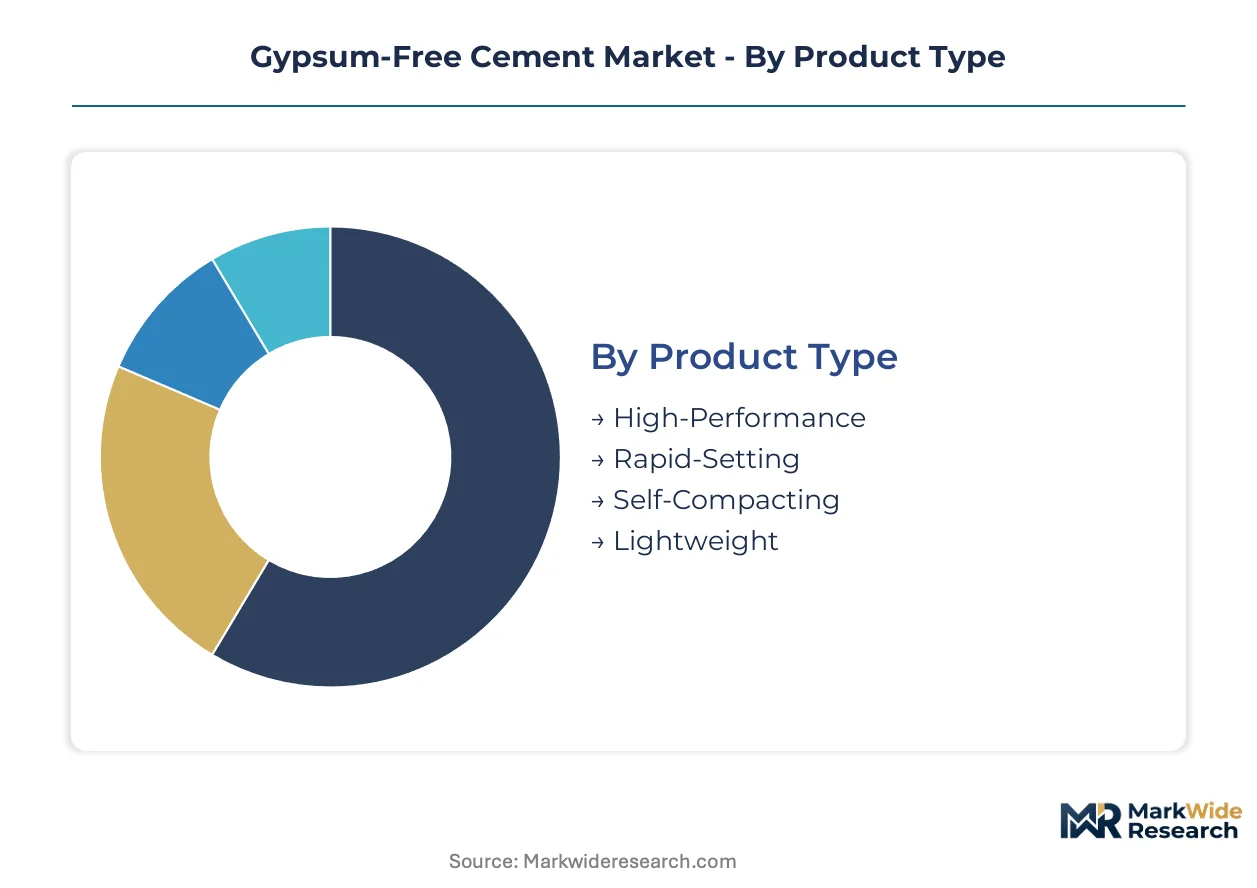
Segmentation in gypsum-free cement reveals how formulation chemistry, project scale, and procurement channel structure create distinct commercial battlegrounds. Each axis carries different margin profiles, certification requirements, and competitive intensity that reshape producer strategy.
Product Type:
Formulation technology determines energy input, setting kinetics, and the regulatory certifications required for market access.
- High-Performance:These formulations employ refined calcined clay ratios and optimized particle size distributions to achieve compressive strengths exceeding standard Portland cement benchmarks. Demand concentrates in Germany's high-rise residential towers where EN 197-5 certification and extended service life specifications justify premium positioning. Regulatory pressure on embodied carbon from the EU Green Deal accelerates specification in public procurement channels.
- Rapid-Setting:Accelerated hardening chemistry enables traffic-ready repairs within four to six hours, compressing project downtime for critical infrastructure. Vietnam's industrial zone expansion in Binh Duong and Dong Nai provinces drives volume as foreign manufacturers demand minimal production line interruption during facility maintenance.
- Self-Compacting:Flowable rheology eliminates mechanical vibration requirements in dense reinforcement configurations.
- Lightweight:Expanded shale or pumice aggregates reduce dead loads in high-seismic zones.
High-Performance leads on scale; Rapid-Setting leads on momentum.
Application:
Project category dictates volume scale, specification complexity, and the stakeholder network controlling procurement decisions.
- Residential Construction:Single-family and mid-rise housing dominates absolute volume flows, particularly across Southeast Asia where urban migration accelerates build rates. India's affordable housing mandates in Maharashtra and Karnataka specify low-carbon binders, creating anchor demand for regional producers. Cost sensitivity here compresses margins and rewards manufacturing scale.
- Infrastructure Development:Heavy civil works represent the steepest expansion trajectory as public agencies embed carbon intensity thresholds into tender requirements. Indonesia's trans-Java toll road program specifies sulfate-resistant formulations for coastal segments with saline groundwater exposure, opening premium positioning for technical specialists.
- Commercial Projects:Office towers and retail complexes balance aesthetic finish requirements with accelerated construction schedules.
- Repair Works:Structural rehabilitation and surface restoration demand specialized adhesion and compatibility characteristics.
Residential Construction dominates volume capture; Infrastructure Development commands the steepest expansion trajectory.
End User:
Customer scale and technical capability determine whether procurement flows through distributor networks or shifts toward direct manufacturer contracting.
- Construction Firms:Large integrated developers in Ho Chi Minh City and Bangkok now specify binder chemistry directly, unbundling technical service from material supply and concentrating volume with formulators capable of custom blend engineering.
- Contractors:Specialized repair and infrastructure contractors drive rapid-setting product demand where downtime minimization justifies unit economics.
- Builders:Regional residential specialists balance cost optimization with code compliance in fragmented procurement channels.
- DIY Enthusiasts:Small-scale renovation demand flows through retail hardware channels with minimal technical specification.
Construction Firms lead on procurement control; Contractors lead on technical specification intensity.
Distribution Channel:
Channel structure reflects customer scale, geographic dispersion, and the service intensity required for technical product adoption.
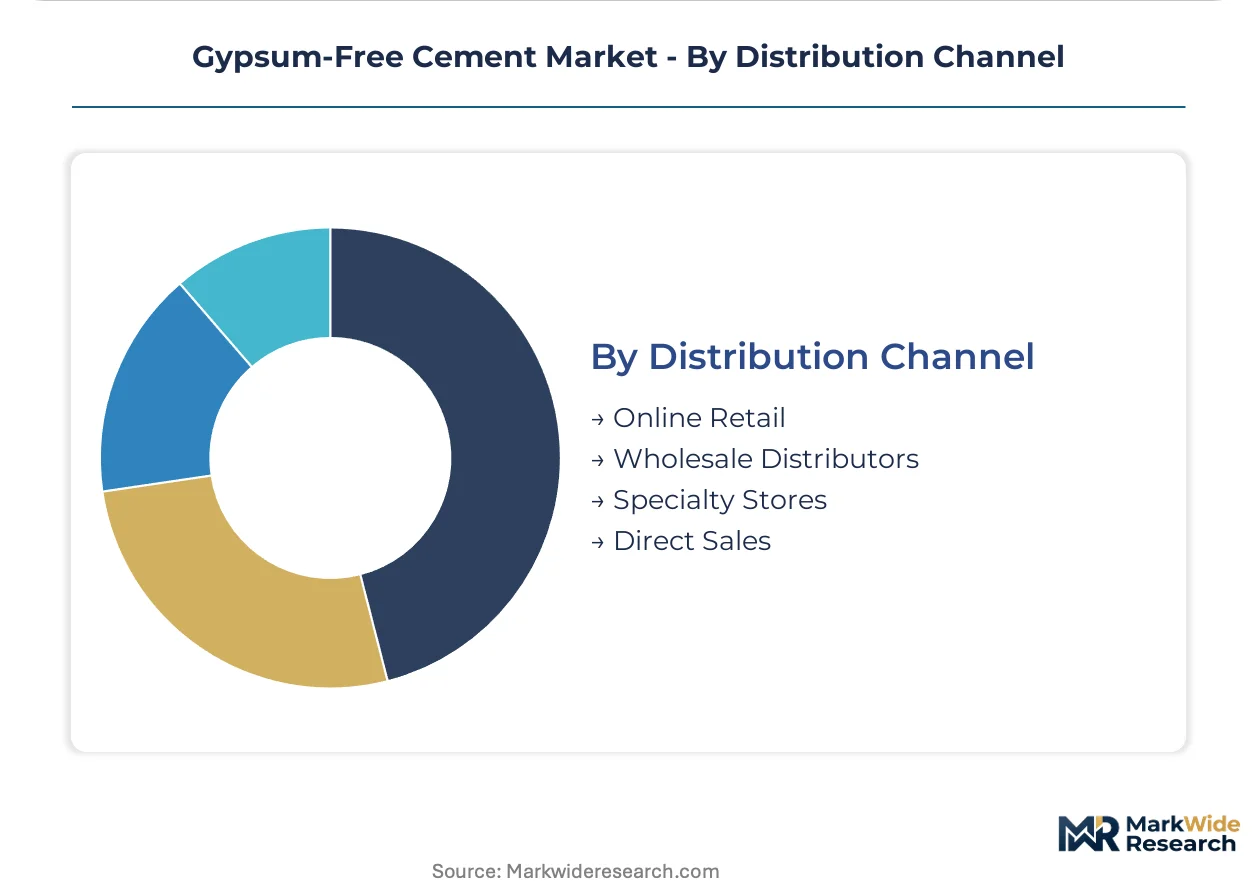
- Wholesale Distributors:Traditional bulk material networks retain dominance in residential and commercial construction where project scale justifies truckload logistics and established credit relationships.
- Direct Sales:Large infrastructure developers and industrial facility operators bypass intermediaries to secure volume commitments and technical support integration.
- Online Retail:Digital platforms capture small contractor and DIY demand with transparent pricing and specification documentation.
- Specialty Stores:Technical product showrooms serve repair specialists requiring application guidance and compatibility verification.
Wholesale Distributors retain volume leadership; Direct Sales gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors calcined clay cement production capacity, with integrated kiln clusters serving the Beijing-Shanghai high-speed rail corridor and Xiong'an New Area megaprojects.
China
State-funded construction mandates under MEE dual carbon enforcement drive specification shifts toward low-carbon binders. GB standards on embodied carbon disclosure now govern cement eligibility for public procurement. The Xiong'an New Area development contracts concentrate demand for reformulated product lines meeting verified carbon intensity thresholds.
India
Urban corridor projects in Maharashtra and Karnataka generate anchor demand for affordable housing and metro rail construction. State government mandates specify low-carbon binders for publicly funded infrastructure. Mumbai-Pune industrial belt producers scale manufacturing to capture volume from decentralized infrastructure spending.
Germany
High-rise residential towers in Frankfurt and Munich drive EN 197-5 certified high-performance formulations. EU Green Deal regulatory pressure accelerates specification in federal and municipal procurement channels. The Rhine-Ruhr industrial cluster hosts R&D-intensive producers optimizing calcined clay ratios for extended service life specifications.
Vietnam
Foreign manufacturing investment in Binh Duong and Dong Nai provinces fuels warehouse and factory construction demand. Industrial facility operators specify rapid-setting repair cements to minimize production line interruption. Ho Chi Minh City developers increasingly contract directly with specialty cement producers for custom blend engineering.
Indonesia
The trans-Java toll road program generates demand for sulfate-resistant formulations in coastal segments with saline groundwater exposure. Public-private partnership structures embed technical specifications favoring low-carbon alternatives. Surabaya-Gresik industrial corridor producers deploy containerized calcination systems to serve dispersed infrastructure projects.
Gypsum-Free Cement Market Competitive Landscape
Global majors compete with regional champions across formulation technology and procurement channel control. The market exhibits tiered concentration, with integrated multinationals commanding high-performance and rapid-setting segments while mid-scale regional operators capture volume through distributed manufacturing models. Three archetypes dominate: vertically integrated raw material specialists, R&D-intensive formulation leaders, and scale-driven rapid-setting producers. Competitive moves center on backward integration into kaolin sourcing and mobile calcination unit deployment to compress supply chain economics.
Within the raw material integration tier, Knauf AG exemplifies upstream control strategies through captive clay deposit access. Saint-Gobain occupies a position representing R&D-intensive formulation leadership in alternative binder chemistry. Tarmac anchors the scale-driven archetype in rapid-setting manufacturing capacity. These three entities collectively illustrate how competitive positioning stratifies across technical specialization, vertical integration depth, and production scale rather than geographic coverage alone.
| Leading Market Players |
|---|
| Knauf AG |
| Saint-Gobain |
| Tarmac |
| Yoshino Gypsum Co. Ltd. |
| Georgia Pacific |
| American Gypsum |
| Jonoub Gypsum |
| Global Mining Company |
| Gypsona |
| Others |
Value Network & Pricing Analysis
Kaolin freight costs from Brazil and Ukraine cascade through formulation economics, compressing margins at regional producers while integrated multinationals absorb volatility through captive clay deposits. This input-cost geography splits the market into price-takers dependent on spot procurement and price-setters commanding backward-integrated supply security.
Pricing Analysis
Input-cost pass-through from calcined clay procurement dominates pricing formation, with EN 197-5 certification grade and volume scale serving as primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels separates rapid-setting repair formulations from commodity residential binders. Pricing pressure stems from flash calcination technology narrowing the cost gap with conventional Portland cement. Residential construction buyers exhibit highest price sensitivity, while infrastructure developers prioritize performance specifications over unit economics.
Supply Chain Analysis
High-purity kaolin supply rests on Brazilian Minas Gerais deposits and Ukrainian Donbas basin extraction, with secondary sourcing from China's Jiangxi province. Calcined clay, limestone fines, and pozzolanic supplements constitute critical formulation inputs. Single-source vulnerability concentrates around Ukrainian clay corridors exposed to geopolitical disruption. Distribution runs through wholesale bulk networks for residential volume, with direct manufacturer contracting gaining share in infrastructure and industrial repair segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flash calcination technology deployment compresses production costs while premium-tier rapid-setting formulations capture widening spreads in industrial repair applications. Margin expansion potential concentrates with producers achieving captive kaolin supply or certification differentiation.
For Market Incumbents: Deepen backward integration into Brazilian kaolin deposits to neutralize freight volatility exposure from Ukrainian supply corridors. Secure EN 197-5 pre-certification for calcined clay blends to compress 90-day validation timelines that delay product launches. Geopolymer substitution threats in low-carbon infrastructure contracts demand accelerated R&D in alkali-activated binder compatibility.
For New Entrants and Emerging Players: Launch via mobile calcination unit deployment in Indonesia's Surabaya-Gresik corridor, where dispersed infrastructure projects lack integrated supply coverage. Target Vietnam's Binh Duong industrial zone rapid-setting demand with direct technical service models bypassing distributor networks. White-space opportunity concentrates in containerized on-site clay processing for mid-scale regional operators.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional producers with captive kaolin access because MEE dual carbon enforcement fragments procurement eligibility around verified carbon intensity thresholds. Five-to-ten year viability favors formulators with R&D capability in alternative binder chemistry and distributed manufacturing deployment. Watch China's GB standard threshold adjustments as inflection signals for specification-driven volume shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kaolin Sourcing | Captive Brazilian clay deposits neutralize Ukrainian supply corridor disruption risks for integrated producers. |
| Mobile Calcination Unit Deployment | Containerized on-site processing eliminates intermediate freight legs for Indonesia's dispersed infrastructure projects. |
| EN 197-5 Certification Investment | Pre-validation protocols compress 8-12 month product launch delays in European high-performance segments. |
| Direct Technical Service Contracting | Ho Chi Minh City and Bangkok developers now specify binder chemistry, unbundling supply from engineering support. |
| Carbon Capture Kiln Integration | Direct air capture systems enable negative-emission claims for premium Beijing-Shanghai high-speed rail bids. |
Research Methodology
Multiple input streams — executive interviews with cement plant managers and formulation chemists, procurement lead discussions at infrastructure developers, and technical R&D director consultations — were reconciled against customs trade data, MEE enforcement disclosures, and EN 197-5 certification timelines. Secondary validation drew from SEC filings of integrated building material producers, Chinese GB standard publication records, and Indian state government tender documentation. Bottom-up project pipeline aggregation and top-down sectoral demand modeling were cross-checked for consistency.
Data-stream reconciliation across product type, application category, end-user scale, and regional regulatory cluster dimensions anchored the analytical framework. CAGRs were derived from growth rate convergence modeling across the projection horizon. Industry-specific forecast inputs included calcined clay activation technology adoption curves and MEE dual carbon threshold enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption to Ukrainian kaolin corridors or accelerated geopolymer substitution in Nordic infrastructure. Assumptions reflect current regulatory trajectories and technology cost curves. A small set of named triggers — China's GB standard threshold revisions, flash calcination equipment cost declines, and EN 197-5 validation timeline compression — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Europe Bitumen Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Beneficiation Reagents Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
North America Paper Machine Oil Market