
 United Kingdom Adhesives Market | 2026-2036
United Kingdom Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Adhesives Market Analytics
Domestic specialty chemical producers is restructuring capacity around high-performance formulations for electric vehicle battery enclosures and lightweight body-in-white assemblies. Henkel AG & Co. KGaA leverages its European R&D network to sustain technical service density across British automotive OEMs. Dow Inc. anchors water-based acrylic supply for the corrugated packaging sector through its regional compounding operations. BASF plc competes on polyurethane systems tailored to the construction sector's moisture-cure requirements.
United Kingdom adhesives comprise formulated bonding agents ranging from emulsion polymers and reactive hot melts to cyanoacrylate and epoxy chemistries, typically specified by shear strength, open time, and substrate compatibility parameters. These materials permanently join dissimilar surfaces across manufacturing and assembly operations where mechanical fasteners add weight or stress concentration. Water-based adhesives dominate volume in food-contact packaging applications where migration limits favor low-VOC formulations. Structural adhesives capture disproportionate value in automotive and medical device bonding where load-bearing certification commands technical premiums. Bio-based adhesives represent the fastest-expanding technology category as brand owners mandate renewable content thresholds in consumer goods and furniture assembly supply chains.
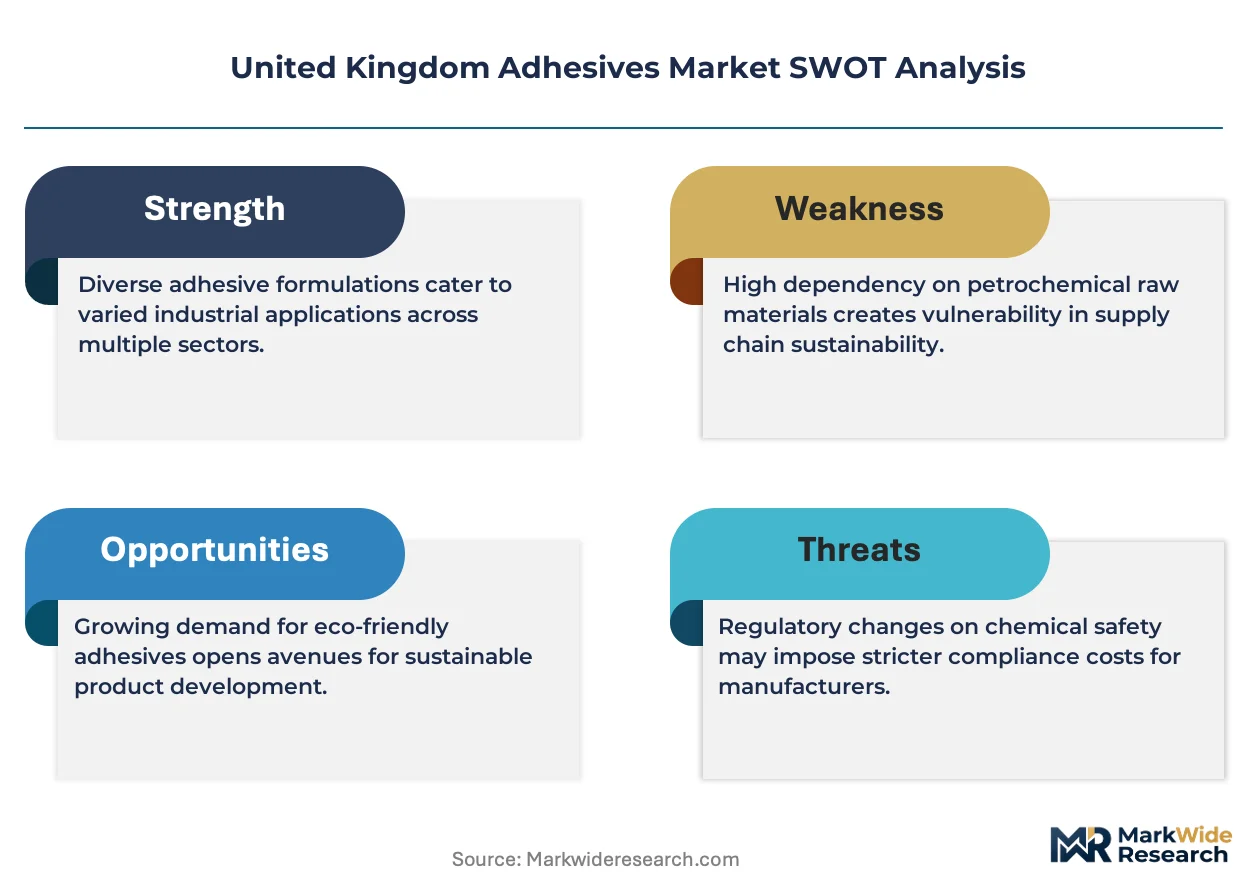
REACH retained in UK law through the Health and Safety Executive's UK REACH framework governs substance registration and restriction, while the Construction Products Regulation and BSI Kitemark standards dictate performance certification for structural bonding applications. The Environment Agency enforces solvent emission limits that push manufacturers toward hot melt and reactive systems with reduced volatile organic compound profiles. Stakeholders must monitor regulatory divergence between UK REACH and EU REACH substance restriction timelines to avoid dual-compliance costs or market exclusion risks.
Market Dynamics
Automotive electrification is restructuring adhesive demand toward thermally conductive bonding systems for battery thermal management and lightweight structural assembly across British manufacturing corridors.
Growth Catalysts
- EV Battery Assembly Standards:UK automotive OEMs are specifying high-thermal-conductivity adhesives for battery module bonding to meet crash safety and thermal runaway containment protocols mandated by vehicle type approval frameworks.
- West Midlands Manufacturing Density:Concentrated automotive production around Birmingham and Coventry creates localized demand clusters for just-in-time adhesive supply and technical service support.
- UK REACH Substance Registration:Continued enforcement of post-Brexit chemical registration requirements is consolidating compliant supplier bases and locking in market position for registered formulators.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and polyurethane monomer prices track naphtha and propylene indices, compressing formulation margins during upstream commodity spikes.
- Specialty Additive Import Concentration:Curing agents, tackifiers, and rheology modifiers concentrate supply from German and Dutch chemical producers, exposing British formulators to cross-channel logistics friction.
- Mechanical Fastener Substitution Resistance:Heavy-duty construction and marine applications retain bolting and welding for load-critical joints where adhesive certification cycles lag project timelines.
Strategic Opportunities
- Scottish Offshore Wind Fabrication:Tower and blade manufacturing at Scottish ports requires structural bonding systems certified for cyclical load fatigue in marine environments.
- Bio-Based Content Mandates:Furniture and consumer goods retailers are imposing renewable content thresholds that favor suppliers with certified bio-polyol and plant-oil-derived resin capabilities.
- Digital Adhesive Specification Platforms:Technical data sheet aggregation and substrate-matching algorithms are compressing buyer search costs and shifting specification authority from distributor field reps to procurement analytics teams.
Industry Challenges
- Formulation Chemist Talent Pipeline:Polymer science and adhesion engineering programs at British universities produce insufficient graduates to replace retiring technical specialists at specialty chemical firms.
- Dual-Certification Testing Burden:Diverging UK REACH and EU REACH restriction timelines force parallel toxicology and environmental fate studies for products serving both markets.
- Legacy Equipment Retrofit Complexity:Water-based and reactive hot melt systems require humidity-controlled storage and heated dispensing infrastructure incompatible with solvent adhesive handling equipment at smaller packaging converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Adhesives Market |
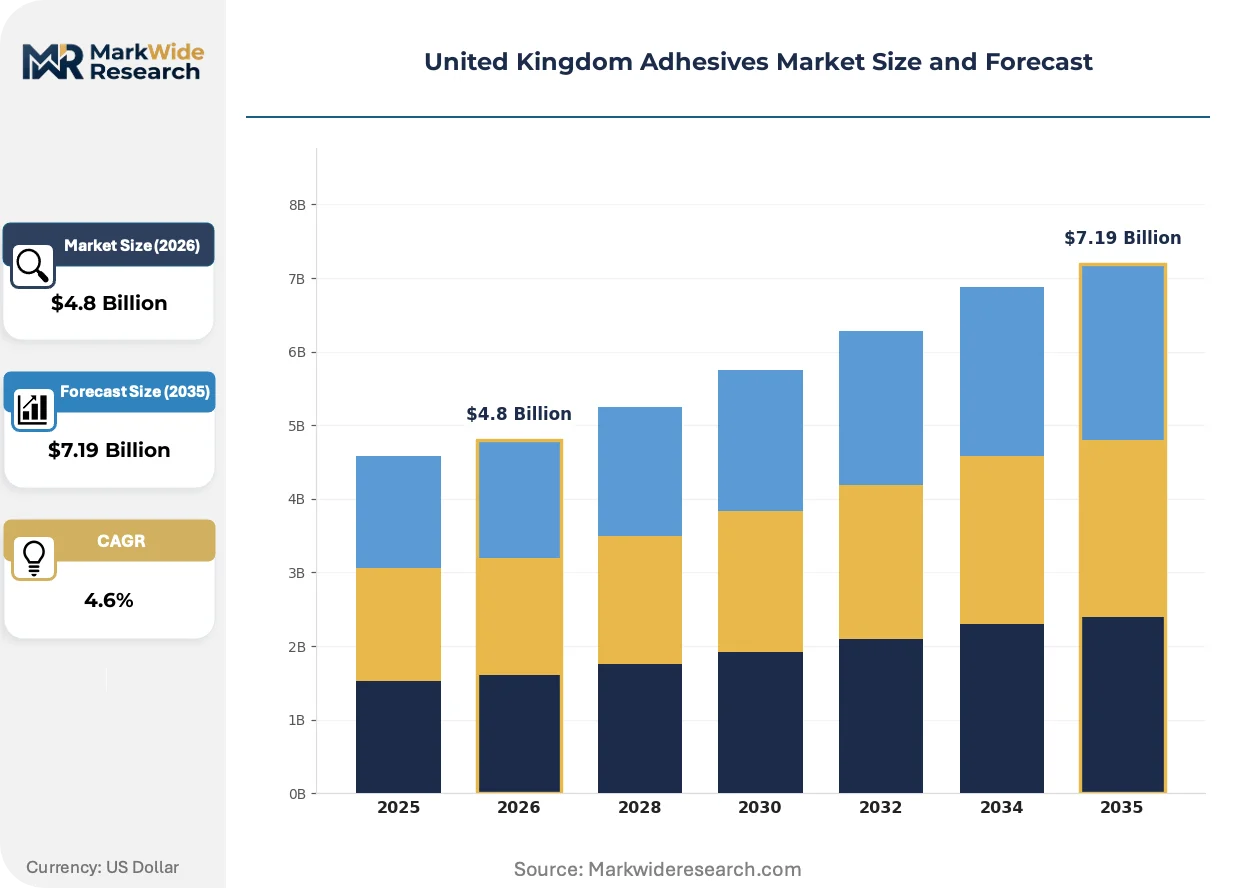
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Adhesives, Structural Adhesives, Hot Melt Adhesives, Water-Based Adhesives End User: Automotive Industry, Construction Sector, Packaging Industry, Electronics Sector Application: Transportation, Furniture Assembly, Medical Devices, Consumer Goods Technology: Chemical Adhesives, Bio-Based Adhesives, Thermosetting Adhesives, Reactive Adhesives |
| Companies Covered | H.B. Fuller Company, Beardow Adams, Henkel AG & Co. KGaA, Huntsman International LLC, Dow Inc., 3M Company, Arkema Group, BASF plc, Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Adhesives Market Evolving Landscape
Adhesive performance specifications are tightening around thermal management, crash durability, and circular end-of-life requirements as automotive and electronics OEMs push bonding systems deeper into structural applications.
Thermally conductive gap fillers is overtaking traditional mechanical clamping and potting compounds in electric vehicle battery pack assembly. Automotive tier-one suppliers in the West Midlands are qualifying silicone and acrylic-based thermal interface materials for cell-to-cell and module-to-cold-plate bonding. This shift is compressing the addressable market for legacy mechanical fastening hardware while expanding technical adhesive value per vehicle.
UK REACH restriction proposals on substances of very high concern are accelerating reformulation timelines for epoxy and polyurethane systems used in construction and marine applications. The Health and Safety Executive's substance evaluation program is forcing formulators to substitute bisphenol-A epoxies and certain isocyanate curing agents ahead of potential authorization requirements. Construction adhesive producers are responding with accelerated bio-based polyol and non-isocyanate polyurethane development programs to preempt regulatory exclusion.
Specification authority is migrating from distributor technical representatives to centralized procurement analytics platforms that aggregate performance data and substrate compatibility matrices. Large packaging converters in Greater Manchester are deploying software tools that algorithmically match adhesive chemistries to line speed, substrate, and migration limit requirements. This behavioral shift is most visible among mid-sized food-contact packaging firms where procurement teams now bypass traditional field sales relationships for direct digital specification.
United Kingdom Adhesives Market Segmentation
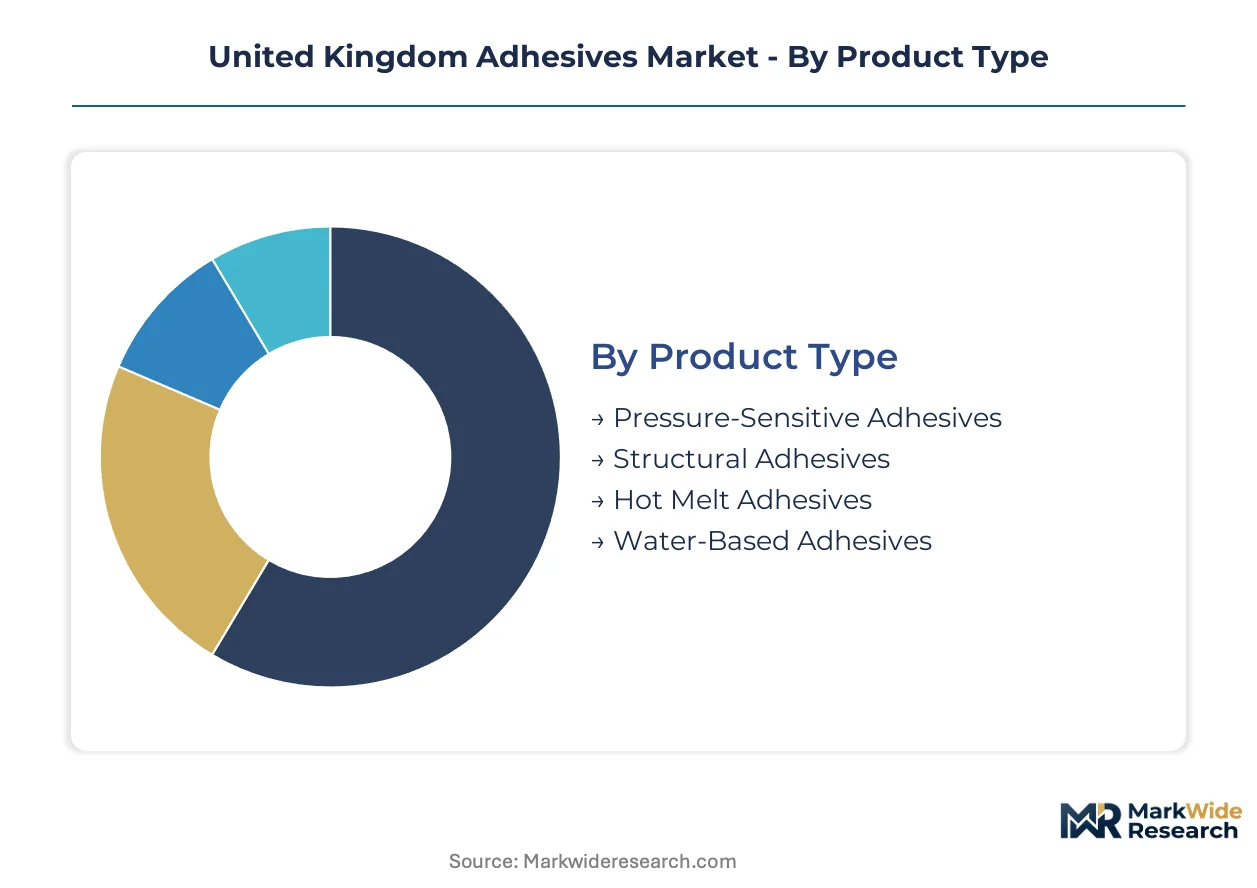
Segmentation in the United Kingdom adhesives market reveals how formulation chemistry and end-use certification requirements fragment supply chains. Manufacturers must align production assets with distinct technical specifications that govern thermal conductivity, bond durability, and regulatory compliance across British industrial corridors.
Product Type:
Supply concentration among British formulators clusters around chemistries that balance performance certification with REACH compliance cost structures.
- Structural Adhesives:Load-bearing epoxy, polyurethane, and acrylic systems specified for shear strength and crash durability. Demand concentrates in West Midlands automotive assembly where bonded body-in-white construction displaces spot welding for weight reduction.
- Water-Based Adhesives:Emulsion polymer formulations with low-VOC profiles dominate food-contact packaging. Greater Manchester corrugated converters specify these for migration-limit compliance under retained EU food contact frameworks.
- Pressure-Sensitive Adhesives:Permanent and removable tackified acrylic or rubber-resin systems for label and tape applications.
- Hot Melt Adhesives:Thermoplastic EVA and polyolefin formulations applied molten for rapid set speeds in high-speed packaging lines.
Today's leader: Structural Adhesives. Tomorrow's challenger: Water-Based Adhesives.
End User:
Application-specific certification requirements create divergent margin structures across British manufacturing sectors.
- Automotive Industry:OEMs and tier-one suppliers specify thermally conductive bonding for EV battery enclosures and structural assembly. West Midlands manufacturing density creates localized technical service demand for just-in-time adhesive supply.
- Construction Sector:Moisture-cure polyurethane and hybrid polymer systems for facade bonding and flooring installation. UK timber frame construction growth drives specification of certified structural wood adhesives under British Standards Institution Kitemark protocols.
- Packaging Industry:Corrugated box and flexible food packaging converters prioritize low-migration water-based and hot melt systems.
- Electronics Sector:Miniaturization trends demand precision dispensing of conductive and underfill adhesives for circuit board assembly.
Automotive commands premium pricing. Packaging drives volume scale.
Application:
Functional performance requirements segment British adhesive demand by load conditions and environmental exposure.
- Transportation:Structural bonding for rail, marine, and aerospace assembly where fatigue resistance and fire-retardant certification apply. Scottish offshore wind tower fabrication at Port of Nigg and Port of Dundee creates emerging demand for cyclical load-certified marine adhesives.
- Medical Devices:Biocompatible cyanoacrylate and UV-cure systems for disposable and implantable device assembly. Sterilization compatibility and ISO 10993 compliance govern supplier qualification.
- Furniture Assembly:Polyvinyl acetate and polyurethane hot melts for panel bonding and edge banding. Retailer mandates on renewable content favor bio-based formulation suppliers.
- Consumer Goods:General-purpose bonding for personal care and household product assembly with emphasis on aesthetic finish and skin-contact safety.
Medical applications extract highest value per kilogram. Transportation offers steepest expansion trajectory.
Technology:
Feedstock origin and cure chemistry determine compliance positioning against evolving UK REACH substance restrictions.
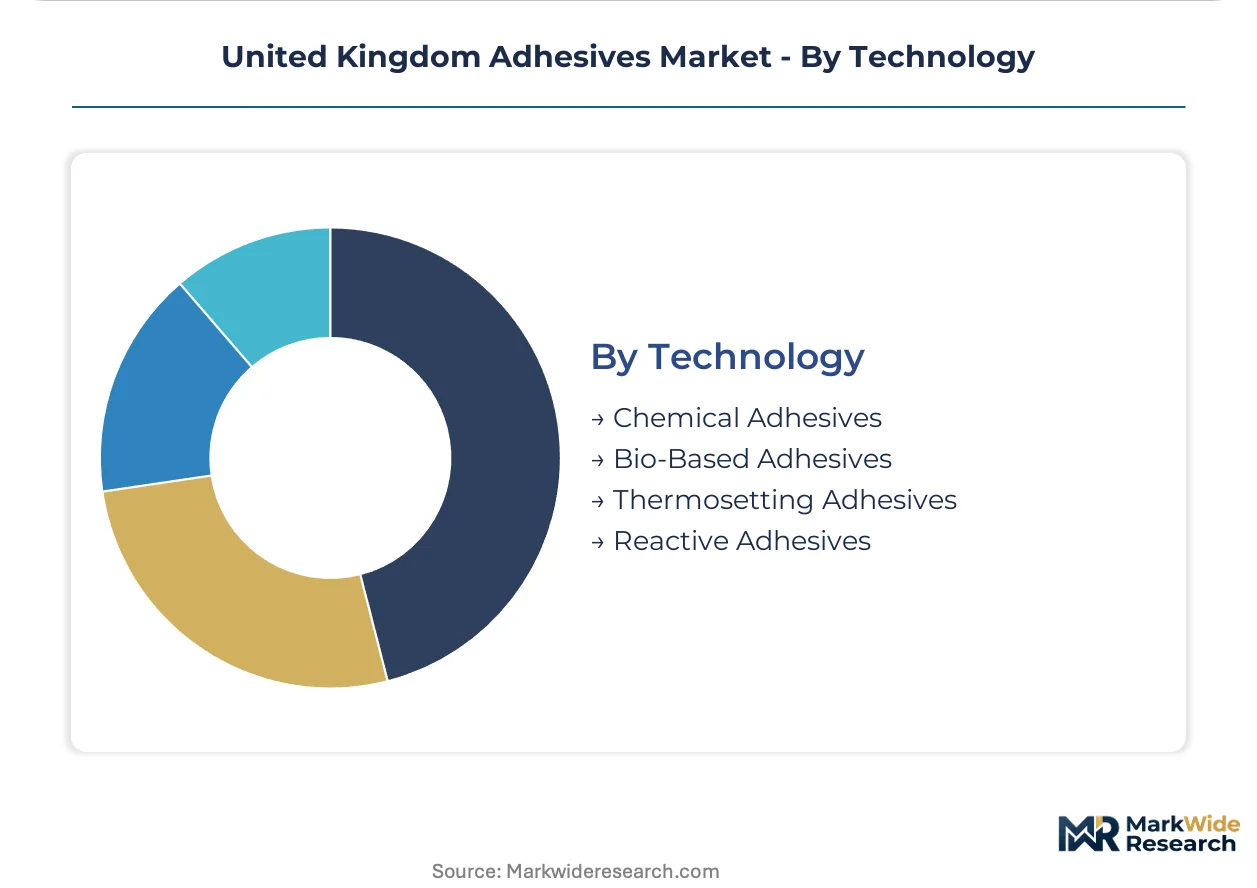
- Bio-Based Adhesives:Plant-oil-derived polyols and starch-modified emulsions with certified renewable content. Furniture and consumer goods retailers in British supply chains impose threshold mandates that accelerate formulation development at domestic specialty chemical firms.
- Reactive Adhesives:Two-component epoxy and polyurethane systems curing through chemical reaction for structural load bearing. Automotive battery assembly specifications favor these for thermal management and crash integrity.
- Chemical Adhesives:Solvent-borne and water-borne synthetic polymer systems from petrochemical feedstocks.
- Thermosetting Adhesives:Cross-linked polymers irreversibly cured through heat or catalyst for high-temperature resistance.
Bio-Based Adhesives gain share fastest. Reactive Adhesives defend structural applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK REACH compliance costs are pushing specialty adhesive formulators toward regional production hubs where regulatory arbitrage minimizes dual-certification burdens. Manufacturing investment clusters in sub-regions offering feedstock access, technical talent pools, and proximity to end-use demand corridors.
West Midlands
Automotive OEMs and tier-one suppliers in Birmingham and Coventry drive concentrated demand for thermally conductive bonding systems. The Health and Safety Executive's UK REACH enforcement creates localized compliance service ecosystems around Wolverhampton and Solihull. Battery assembly lines at Jaguar Land Rover's Solihull plant and Aston Martin's Gaydon facility specify just-in-time adhesive supply from regional compounders.
Greater Manchester
Corrugated packaging converters and flexible film manufacturers prioritize low-migration water-based adhesives for food-contact applications. Retained EU food contact frameworks govern specification standards across Trafford Park industrial estates. Specialized technical service teams from major formulators maintain permanent presence to support high-speed line trials at Smith Anderson and Saica Pack facilities.
Scotland
Offshore wind tower and blade fabrication at Port of Nigg and Port of Dundee creates emerging demand for cyclical load-certified marine adhesives. The Scottish Government's offshore wind manufacturing investment fund supports bonded composite manufacturing capabilities. Structural bonding qualification programs at the University of Strathclyde's Advanced Forming Research Centre anchor technical development partnerships.
Southeast England
Medical device manufacturers in Cambridge and Oxfordshire specify biocompatible cyanoacrylate and UV-cure systems for disposable and implantable assembly. MHRA oversight of ISO 10993 compliance governs supplier qualification protocols. Precision dispensing equipment clusters around Stevenage and Harlow support electronics miniaturization trends in aerospace and satellite manufacturing.
Wales
Furniture assembly and panel manufacturing in Deeside and Ebbw Vale respond to retailer mandates on renewable content thresholds. The Welsh Government's circular economy strategy accelerates bio-based polyol development programs at specialty chemical operations. Timber frame construction growth drives specification of certified structural wood adhesives under British Standards Institution Kitemark protocols.
United Kingdom Adhesives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and digital specification platforms as differentiation vectors. Market structure reflects moderate consolidation among multinational chemical conglomerates with regional compounding assets, alongside specialized domestic formulators serving niche certification requirements. Three archetypes dominate: petrochemical-integrated multinationals with European R&D networks, mid-cap British formulators with UK REACH registration advantages, and technology licensors supplying curing agent and additive packages. Competitive dynamics center on dual-certification testing partnerships and backward integration into bio-polyol feedstocks.
Among petrochemical-integrated multinationals, Henkel AG & Co. KGaA and Dow Inc. exemplify the technical service density archetype through sustained investment in British automotive and packaging sector relationships. BASF plc occupies a position representing the construction-focused polyurethane systems tier. Domestic specialists including Beardow Adams sit within the regional formulator archetype leveraging UK REACH registration timelines and just-in-time supply proximity to West Midlands automotive corridors. Huntsman International LLC anchors the reactive systems segment through isocyanate and epoxy technology platforms.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Beardow Adams |
| Henkel AG & Co. KGaA |
| Huntsman International LLC |
| Dow Inc. |
| 3M Company |
| Arkema Group |
| BASF plc |
| Sika AG |
| Others |
Value Network & Pricing Analysis
Captive backward integration into acrylic monomer and polyol production anchors pricing power for petrochemical-integrated multinationals serving British automotive OEMs, while specialty additive import dependence erodes margin control for domestic formulators lacking upstream synthesis assets.
Pricing Analysis
Distributor margin layers absorb 15-25 points between compounder gate pricing and Tier 1 automotive buyer invoices, compressing returns for mid-cap British formulators without direct OEM relationships. Three-tier pricing structure across certified structural, standard industrial, and commodity packaging grades reflects REACH registration cost amortization and thermal conductivity performance premiums. Cost compression in water-based packaging tiers is intensifying because Greater Manchester converters leverage digital specification platforms to force competitive bidding. Food-contact packaging buyers exhibit highest price sensitivity, whereas West Midlands battery assembly procurement teams prioritize thermal management certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Jaguar Land Rover and Aston Martin assembly lines, while independent distributors serve fragmented furniture and construction accounts across Wales and northern England. Acrylic acid and polyurethane precursor supply concentrates in Germany, the Netherlands, and Belgium, exposing British formulators to cross-channel logistics friction and potential customs documentation burdens. Curing agents, tackifiers, and rheology modifiers draw from German and Dutch chemical producers, creating single-source vulnerability for specialty additive packages. Distribution runs through regional compounding facilities in Wolverhampton and Manchester that blend imported base polymers with locally sourced bio-polyol feedstocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based formulation premiums and EV battery thermal management certification are expanding addressable margins for suppliers that capture renewable content mandates and automotive safety specification authority.
For Market Incumbents: Extend UK REACH registration advantages by accelerating dual-certification testing partnerships that preempt EU substance restriction timelines, locking in supplier status for cross-channel OEMs. Deepen captive supply of bio-polyol feedstocks through Welsh circular economy grant programs to defend margin position against petrochemical price volatility. Prioritize technical service density investments around Solihull and Gaydon battery assembly corridors where just-in-time supply relationships resist digital procurement disintermediation. For New Entrants and Emerging Players: Begin with Scottish offshore wind fabrication at Port of Nigg and Port of Dundee, where cyclical load-certified marine adhesive demand outruns established supplier technical service capacity. Target furniture assembly supply chains in Deeside and Ebbw Vale responding to retailer renewable content thresholds that favor certified bio-based formulation capabilities. Deploy digital adhesive specification platforms that aggregate substrate compatibility matrices to bypass entrenched distributor field rep relationships in Greater Manchester packaging. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap British formulators with UK REACH registration timelines and regional compounding assets because regulatory compliance creates customer switching costs that sustain acquisition premiums. Focus on targets with bio-polyol development programs and automotive thermal interface material qualifications that align with electrification content-per-vehicle expansion. Watch for divergence between UK REACH and EU REACH substance authorization timelines as the inflection signal that triggers dual-certification cost stress and distressed seller dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polyol Feedstocks | Welsh circular economy grants accelerate renewable content certification for furniture supply chains. |
| Dual-Certification Testing Partnerships | Parallel UK REACH and EU REACH studies preempt regulatory exclusion risk for cross-channel automotive OEMs. |
| Regional Compounding Capacity Expansion | West Midlands proximity to Solihull and Gaydon battery lines secures just-in-time supply relationships. |
| Digital Specification Platform Deployment | Algorithmic substrate-matching compresses buyer search costs and shifts procurement authority from field reps. |
| Scottish Offshore Wind Qualification Programs | University of Strathclyde partnerships anchor cyclical load certification for marine structural bonding. |
Research Methodology
Coverage spans the United Kingdom with primary inputs from West Midlands automotive corridors, Greater Manchester packaging hubs, and Scottish offshore wind fabrication ports. Primary interviews with adhesive formulator R&D directors, Tier 1 automotive procurement managers, corrugated packaging line engineers, and Health and Safety Executive regulatory affairs officers combined with secondary validation from UK REACH substance registration databases, British Standards Institution Kitemark certification records, and customs trade flow data. Bottom-up segmentation modeling triangulated against top-down industry association estimates ensures cross-verification of volume and value outputs.
Rate-of-change decomposition across the analysis window isolates volume growth from pricing and mix-shift effects through segmented elasticity modeling. Segmentation dimensions include formulation chemistry tier, end-use industry certification requirements, application load-bearing specifications, and feedstock origin technology. CAGRs derive from historical trajectory analysis adjusted for regulatory intervention timelines and automotive platform electrification roadmaps. Forecast inputs incorporate EV battery thermal interface material content-per-vehicle assumptions and bio-based renewable content mandate adoption curves across furniture retail supply chains.
Several conditions sit outside the modeled scope, including abrupt UK-EU trade agreement renegotiation, unilateral REACH substance restriction acceleration, and automotive OEM platform cancellation decisions. Forecasts reflect documented assumptions around petrochemical feedstock price stability and Scottish offshore wind manufacturing investment fund disbursement schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Global Emulsion Adhesives Market