
 Global Aerosol Propellant Market | 2026-2036
Global Aerosol Propellant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerosol Propellant Market Foresight
Pharmaceutical-grade propellant specifications is collapsing the gap between industrial and medical aerosol quality tiers. Honeywell International Inc. leverages its fluorocarbon technology heritage to sustain leadership in regulated medical applications. The Chemours Company anchors North American supply through integrated fluorochemical production. Arkema competes on dimethyl ether purity grades for European cosmetic manufacturers.
Aerosol propellants are liquefied or compressed gases that generate controlled pressure to dispense products from sealed containers, typically stored at vapor pressures between 20 and 80 psig at room temperature depending on the specific gas blend and application requirements. Their primary commercial purpose is to provide uniform, metered delivery of coatings, pharmaceuticals, personal care formulations, and industrial chemicals without mechanical pumping systems. Hydrocarbon propellants lead volume globally due to cost efficiency and compatibility with water-based formulations, while dimethyl ether segments capture expanding share in personal care applications where solvency and low residue properties command premium positioning. Compressed gases including nitrogen and carbon dioxide occupy niche roles in food-grade and pharmaceutical aerosols where inertness and non-flammability justify higher unit costs.
The EPA regulates propellant formulations under the Significant New Alternatives Policy program, while the EU F-Gas Regulation imposes phased reduction quotas on hydrofluorocarbon content. China's MEE enforces national standards for volatile organic compound emissions from aerosol manufacturing facilities. REACH compliance in Europe and evolving GB standards in China are raising formulation disclosure requirements and testing burdens for cross-border suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
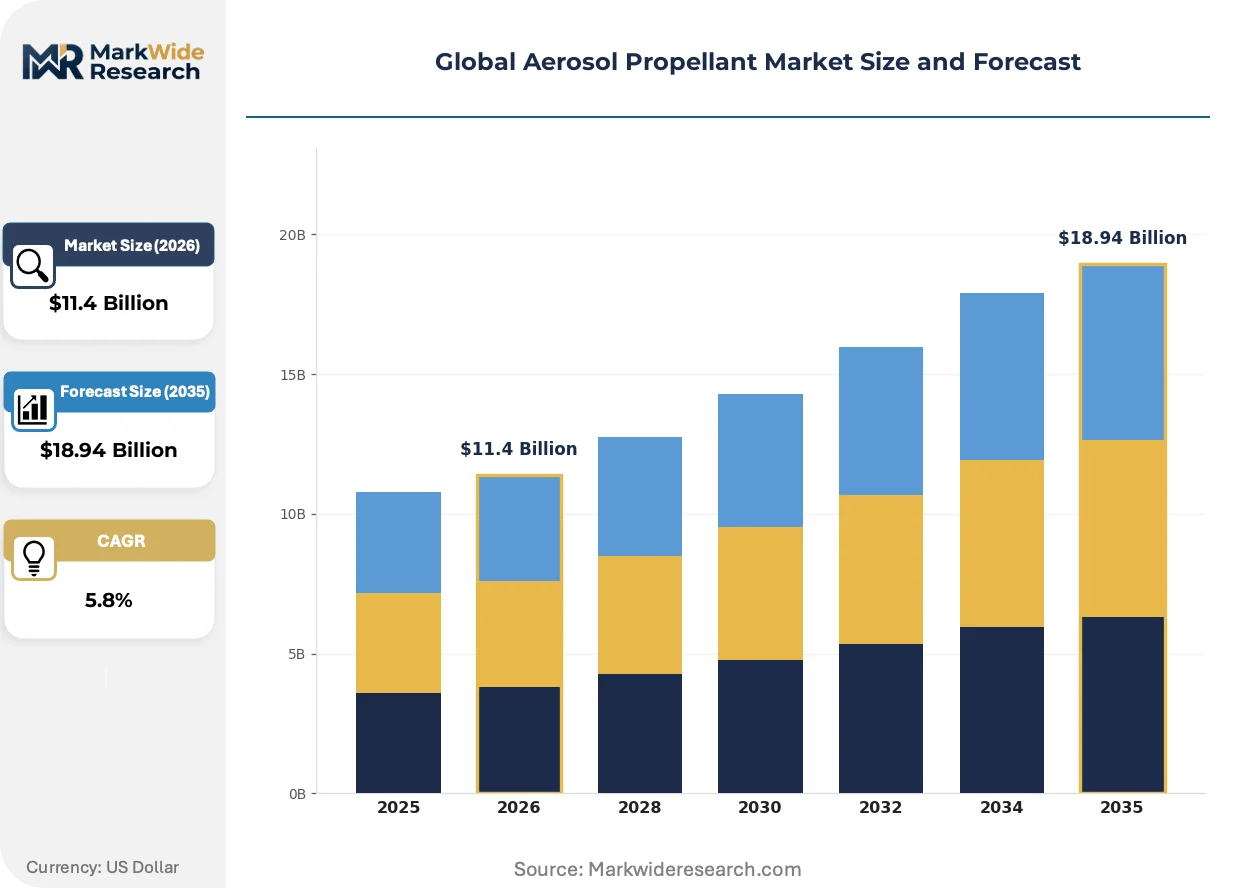
Market Dynamics
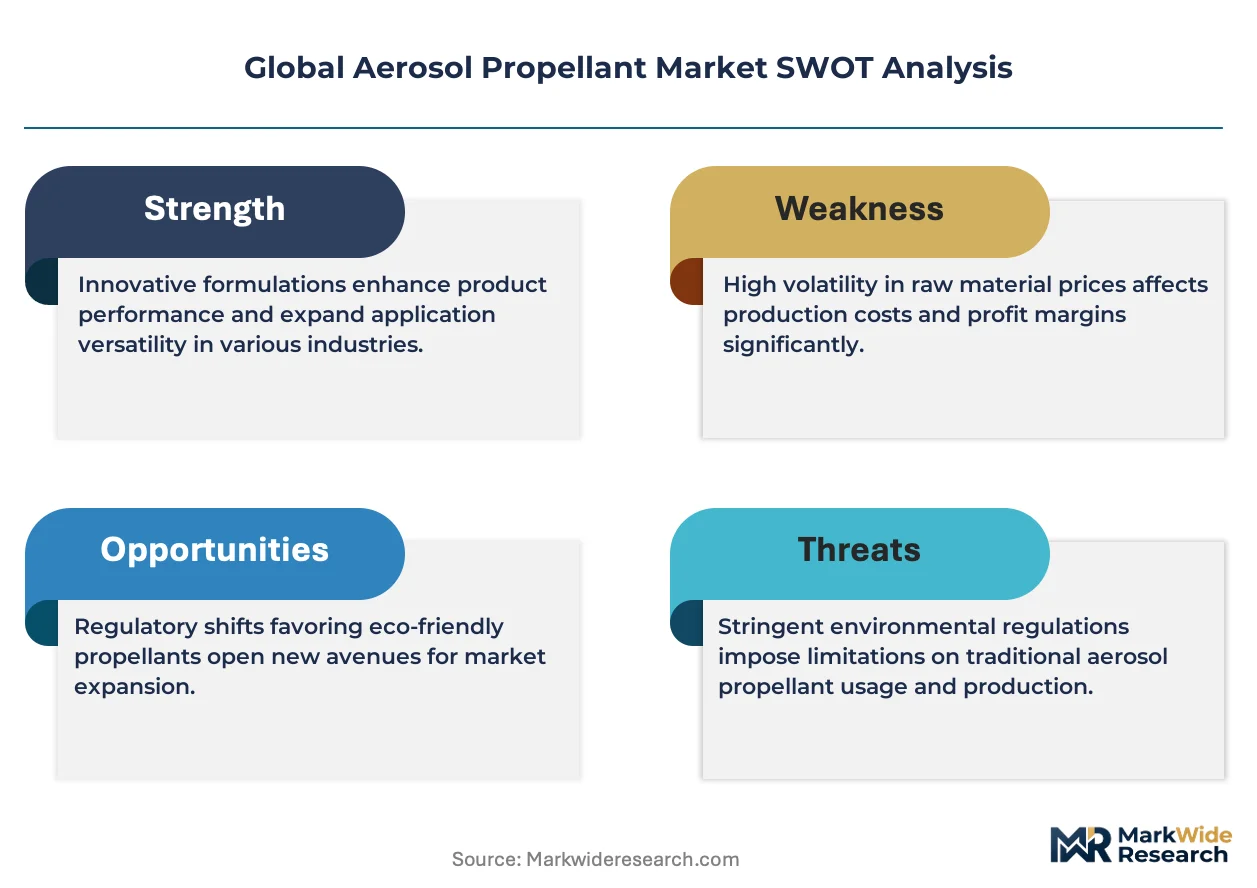
Regulatory phase-down of hydrofluorocarbon propellants under the EU F-Gas Regulation and EPA Significant New Alternatives Policy is forcing wholesale reformulation across personal care, pharmaceutical, and industrial aerosol segments. This structural shift is compressing incumbent supply chains while elevating hydrocarbon and dimethyl ether alternatives.
Growth Catalysts
- EU F-Gas Regulation phase-down quotas:Mandated reduction schedules for hydrofluorocarbon content accelerate supplier migration to hydrocarbon and dimethyl ether alternatives, expanding addressable market for compliant propellant technologies.
- Personal care spray formats:Consumer preference for convenient application methods in deodorants, hair care, and sun protection products drives volume expansion in fine-mist hydrocarbon systems.
- India and Brazil manufacturing clusters:Contract manufacturing capacity expansion in these markets concentrates demand for cost-efficient hydrocarbon propellants serving export-oriented cosmetic and household product brands.
Market Restraints
- Propylene and butane feedstock volatility:Hydrocarbon propellant cost structures remain exposed to petrochemical cracking margins and regional natural gas liquid availability swings.
- Dimethyl ether purity supply concentration:Pharmaceutical-grade and cosmetic-grade dimethyl ether production concentrates among limited European and Asian specialty chemical producers, creating bottleneck risk.
- Flammability classification barriers:Hydrocarbon propellants carry UN hazard classifications that restrict warehousing, transport routing, and retail channel access in densely populated jurisdictions.
Strategic Opportunities
- India domestic pharmaceutical aerosol expansion:CDSCO regulatory harmonization with ICH standards creates opening for pharmaceutical-grade propellant localization serving respiratory inhaler and topical spray manufacturers.
- Compressed gas food-grade applications:Nitrogen and carbon dioxide propellant systems capture share in cooking spray and whipped cream segments where flammability exclusion commands premium positioning.
- Water-based formulation compatibility:Hydrocarbon propellant solvency profiles enable novel emulsion stability in sunscreen and hair treatment products previously dependent on solvent-heavy delivery systems.
Industry Challenges
- REACH and GB standards compliance timelines:Cross-border suppliers face divergent substance registration deadlines and disclosure requirements between European and Chinese regulatory frameworks.
- Reformulation capex intensity:Transition from hydrofluorocarbon to hydrocarbon or dimethyl ether systems requires dedicated filling line modifications, pressure-rated storage infrastructure, and flammancy-rated facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerosol Propellant Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrofluorocarbons, Hydrocarbons, Compressed Gases, Dimethyl Ether, Nitrous Oxide Application: Personal Care, Household, Pharmaceutical, Automotive, Industrial Coatings End User: Cosmetic Manufacturers, Cleaning Service Providers, Medical Facilities, Vehicle Maintenance Centers, Paint Shops Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, Specialty Stores |
| Companies Covered | Honeywell International Inc., The Chemours Company, Royal Dutch Shell, Arkema, Akzo Nobel N.V., Linde Plc., BASF, Nouryon, Evonik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerosol Propellant Market Shifts & Advancements
Propellant technology trajectories center on environmental compliance acceleration, solvency performance optimization, and manufacturing footprint regionalization. These forces are compressing legacy product lifecycles while elevating specialty grade premiums.
Dimethyl ether is decomposing the traditional hydrocarbon-fluorocarbon dichotomy in personal care applications. European cosmetic manufacturers adopt high-purity grades for low-residue hair spray and dry shampoo formulations. This technology is decomposing established supply relationships as brands reformulate around solvency performance rather than historical propellant specifications.
The EPA Significant New Alternatives Policy maintains hydrofluorocarbon restrictions for specific end-uses despite broader phase-down flexibility. Industrial coating and adhesive aerosol segments face constrained propellant selection as acceptable alternatives narrow. Medical device and pharmaceutical manufacturers respond through dedicated hydrocarbon supply agreements and inventory hedging against regulatory tightening.
Brand procurement teams now mandate supplier certification to ISO 9001 and responsible care frameworks prior to contract award. This behavioral shift elevates compliance documentation burdens for mid-tier propellant blenders while concentrating volume among integrated producers with captive quality systems. The pattern is most pronounced in German and French cosmetic supply chains where ECHA transparency requirements intersect with retailer sustainability scorecards.
Global Aerosol Propellant Market Segmentation
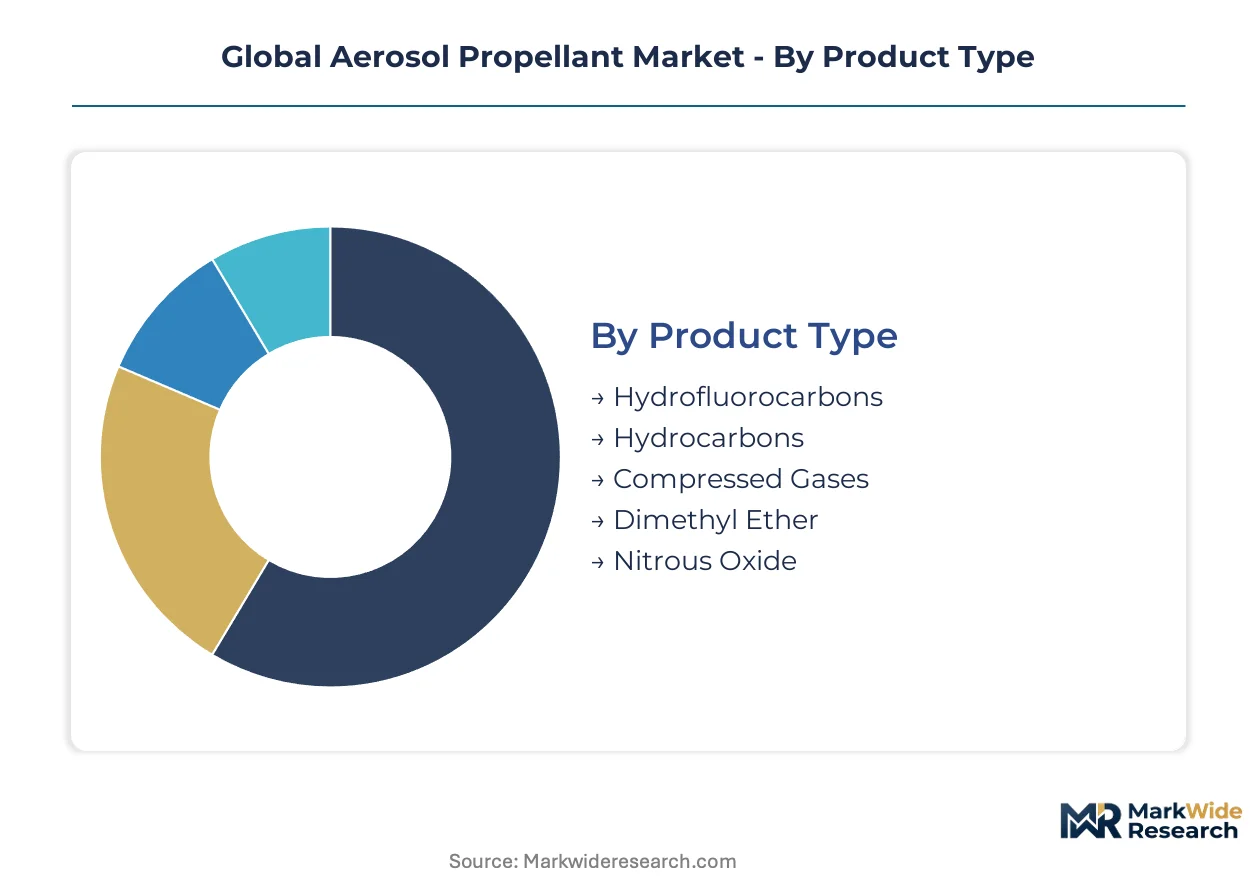
Propellant segmentation determines formulation compatibility, regulatory pathway, and supply chain configuration across aerosol manufacturing. Channel strategies diverge sharply between bulk industrial procurement and specialty-grade pharmaceutical sourcing.
Product Type:
Different propellant chemistries flow through distinct supply channels based on hazard classification and volume economics.
- Hydrocarbons:Blends of propane, isobutane, and n-butane deliver cost-efficient pressure generation for water-based personal care formulations. Demand concentrates in India and Brazil manufacturing clusters serving export-oriented cosmetic brands, though flammability restrictions complicate warehousing in densely populated jurisdictions.
- Dimethyl Ether:High-purity grades offer superior solvency and low residue properties that command premium positioning in European cosmetic applications. German and French hair spray manufacturers drive specification tightening as brands reformulate around performance rather than historical propellant standards.
- Hydrofluorocarbons:Facing phased reduction under EU F-Gas Regulation and EPA Significant New Alternatives Policy mandates.
- Compressed Gases:Nitrogen and carbon dioxide systems serve food-grade and pharmaceutical segments where inertness justifies higher unit costs.
- Nitrous Oxide:Specialized propellant for whipped cream and culinary applications with strict purity requirements.
By volume, hydrocarbons lead. By growth pace, dimethyl ether is climbing the fastest.
Application:
Application segments map to distinct margin tiers and regulatory intensity, with personal care and pharmaceutical commanding premium positioning over industrial uses.
- Personal Care:Deodorants, hair care, and sun protection products drive fine-mist hydrocarbon system expansion. Consumer preference for convenient spray formats accelerates volume growth in this segment.
- Pharmaceutical:Respiratory inhalers and topical sprays require pharmaceutical-grade propellant specifications that collapse quality tiers between industrial and medical applications. CDSCO regulatory harmonization with ICH standards in India creates localization opportunities.
- Household:Cleaning and air freshener applications prioritize cost efficiency over formulation sophistication.
- Automotive:Spray lubricants and detailing products face constrained propellant selection as EPA SNAP acceptable alternatives narrow.
- Industrial Coatings:Adhesive and protective coating aerosols encounter supply chain compression from hydrofluorocarbon phase-down timelines.
Personal care generates the highest absolute volume, while pharmaceutical applications sustain the steepest price premiums.
End User:
End user categories reflect procurement sophistication, with medical and cosmetic buyers imposing certification requirements that exclude mid-tier suppliers.
- Cosmetic Manufacturers:European brands mandate ISO 9001 and responsible care framework certification prior to contract award, elevating documentation burdens and concentrating volume among integrated producers.
- Medical Facilities:Respiratory inhaler manufacturers require dedicated hydrocarbon supply agreements and inventory hedging against regulatory tightening.
- Cleaning Service Providers:Bulk procurement of household aerosols through distributor networks with limited formulation specification.
- Vehicle Maintenance Centers:Aftermarket spray lubricant demand tied to automotive service bay throughput.
- Paint Shops:Industrial coating applications with exposure to VOC emission standards from China's MEE and evolving GB standards.
Cosmetic manufacturers dominate procurement value, while medical facilities impose the most stringent compliance thresholds.
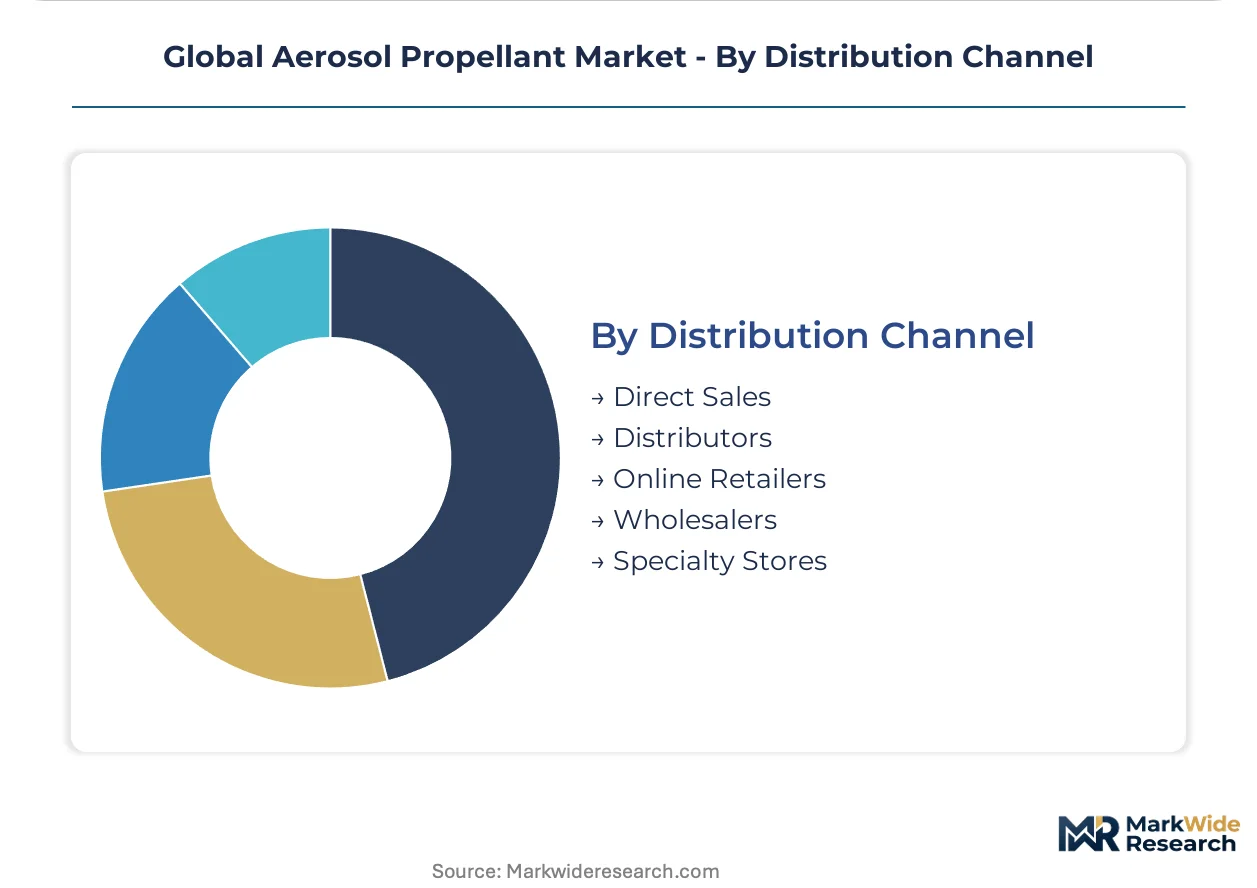
Distribution Channel:
Channel selection correlates with shipment scale and hazard classification, with flammability ratings restricting certain routes.
- Direct Sales:Integrated propellant producers serve high-volume cosmetic and pharmaceutical manufacturers through dedicated supply agreements. REACH compliance documentation and ECHA transparency requirements flow through these relationships.
- Distributors:Regional chemical distributors handle mid-tier hydrocarbon volumes for household and automotive segments, absorbing inventory risk and flammancy-rated warehousing costs.
- Online Retailers:Niche compressed gas systems for food-grade applications with limited scale.
- Wholesalers:Bulk procurement channels for industrial coating segments with price-sensitive formulation requirements.
- Specialty Stores:Professional-grade aerosol products for paint shop and vehicle maintenance applications.
Direct sales capture the highest revenue per shipment, while distributors manage the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports aerosol propellant intermediates to India and Brazil, where contract manufacturers assemble finished personal care products for European and North American retail buyers. This triangular trade pattern concentrates formulation expertise in Western Europe while shifting bulk production toward lower-cost manufacturing clusters.
United States
Pharmaceutical aerosol demand from respiratory inhaler manufacturers drives hydrocarbon propellant procurement volumes. The EPA Significant New Alternatives Policy constrains hydrofluorocarbon availability for industrial coating applications. Houston and Gulf Coast petrochemical corridors supply propane and butane feedstocks to domestic blenders serving cosmetic and household product brands.
Germany
Cosmetic manufacturers in North Rhine-Westphalia and Hesse mandate ISO 9001 certification and responsible care frameworks from propellant suppliers. The EU F-Gas Regulation imposes phased reduction quotas on hydrofluorocarbon content across all aerosol segments. Frankfurt-Rhine-Main logistics hubs coordinate dimethyl ether distribution to French and Benelux formulation facilities.
China
Domestic personal care brands expand manufacturing capacity for sunscreen and hair treatment sprays targeting Southeast Asian export markets. The Ministry of Ecology and Environment enforces volatile organic compound emission standards at aerosol filling facilities. Yangtze River Delta chemical clusters in Jiangsu and Zhejiang provinces concentrate dimethyl ether production for pharmaceutical-grade applications.
India
Contract manufacturers in Maharashtra and Gujarat produce deodorant and air freshener aerosols for European private-label retailers. CDSCO regulatory harmonization with ICH standards creates pathways for pharmaceutical-grade propellant localization. Mumbai-Pune industrial corridors attract hydrocarbon blending investments serving respiratory inhaler and topical spray manufacturers.
Brazil
São Paulo state hosts Latin America's largest aerosol filling capacity for hair care and sun protection products. ANVISA pharmaceutical regulations govern propellant specifications for medical device applications. The ABC industrial region near São Paulo concentrates demand for cost-efficient hydrocarbon systems serving Mercosur export markets.
Global Aerosol Propellant Market Competitive Landscape
Listed leaders compete with private specialists across integrated fluorochemical production versus outsourced hydrocarbon blending. The vendor base organizes into three tiers: multinational chemical conglomerates with captive propellant divisions, regional petrochemical processors serving bulk industrial demand, and specialty gas purifiers focused on pharmaceutical-grade specifications. Consolidation pressures favor scale-driven players with backward integration into feedstock cracking, while niche specialists defend position through certification depth and customer co-development relationships.
Within the integrated chemical tier, Honeywell International Inc. and The Chemours Company exemplify divergent strategic postures. Honeywell sustains fluorocarbon technology heritage in regulated medical applications where substitution timelines lag personal care segments. Chemours anchors North American supply through integrated fluorochemical production infrastructure. Arkema occupies a distinct position among European specialists competing on dimethyl ether purity grades for cosmetic manufacturers reformulating around solvency performance.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| The Chemours Company |
| Royal Dutch Shell |
| Arkema |
| Akzo Nobel N.V. |
| Linde Plc. |
| BASF |
| Nouryon |
| Evonik |
| Others |
Supply & Pricing Matrix
REACH compliance gates both supplier qualification and price differentiation simultaneously, as European cosmetic manufacturers mandate ISO 9001 certification and responsible care framework adherence before contract award, collapsing mid-tier blenders into commodity tiers while elevating integrated producers to premium positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade dimethyl ether commands the highest tier through purity specifications and CDSCO harmonization requirements, while bulk hydrocarbon blends for household applications trade at compressed margins. Price differentiation rests on certification grade and volume scale, with flammability-rated warehousing costs feeding into delivered pricing. Cost compression in standard-tier hydrocarbon segments is intensifying because propylene and butane feedstock volatility exposes blenders to petrochemical cracking margin swings. Household cleaning product manufacturers exhibit the greatest price sensitivity, whereas respiratory inhaler producers accept premium positioning for supply security.
Supply Chain Analysis
Strait of Malacca transit underwrites dimethyl ether feedstock flows from Yangtze River Delta chemical clusters to Indian and Brazilian formulation facilities. Supply concentrates in China, Germany, and the United States, with Jiangsu and Zhejiang provinces hosting pharmaceutical-grade production and North Rhine-Westphalia coordinating European distribution. Raw material dependencies draw from propane and isobutane cracking operations, high-purity methanol for dimethyl ether synthesis, and fluorochemical precursors for residual hydrofluorocarbon output. Single-source vulnerability concentrates in European dimethyl ether purification capacity, where limited specialty producers create bottleneck exposure. Distribution runs through direct sales agreements for high-volume cosmetic and pharmaceutical manufacturers, with regional distributors absorbing flammability-rated inventory risk for mid-tier household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against hydrocarbon propellants as compressed gas and pump spray formats capture share in premium personal care positioning.
For Market Incumbents: Secure dedicated hydrocarbon supply agreements with respiratory inhaler manufacturers before CDSCO localization matures, locking in pharmaceutical-grade offtake. Deepen backward integration into propane and butane cracking to insulate margin structures from feedstock volatility. Prioritize ISO 9001 and responsible care framework certification depth to maintain exclusionary positioning against mid-tier blenders in German and French cosmetic supply chains.
For New Entrants and Emerging Players: CDSCO regulatory harmonization with ICH standards creates a certification fast-track for pharmaceutical-grade propellant localization in Maharashtra and Gujarat manufacturing corridors. Target contract manufacturing clusters serving European private-label deodorant and air freshener brands with cost-efficient hydrocarbon blending capacity. Pursue co-development relationships with topical spray manufacturers seeking supply security against import dependency.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down completion reshapes the acquisition landscape toward hydrocarbon and dimethyl ether specialists with compliant capacity. Long-term viability favors integrated producers with captive feedstock cracking and certification infrastructure over outsourced blenders facing stranded asset risk. Watch for ANVISA regulatory tightening in Brazil as the signal indicating accelerated consolidation opportunity across Latin American supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Cracking | Captive propane and butane supply insulates margin structures from Gulf Coast petrochemical volatility. |
| Pharmaceutical-Grade Certification Investment | CDSCO harmonization with ICH standards opens respiratory inhaler supply agreements in India. |
| Dimethyl Ether Purity Scale-Up | High-purity grades command premium positioning in European hair spray and dry shampoo reformulation. |
| Flammability-Rated Warehousing Expansion | Dedicated infrastructure unlocks densely populated jurisdictions restricting standard hydrocarbon distribution. |
| Long-Term Supply Agreement with Cosmetic Manufacturers | ISO 9001-certified direct sales relationships exclude mid-tier competitors from German and French procurement. |
Research Methodology
Desk research of customs and trade flow databases, ECHA substance registration filings, and EPA SNAP program determinations preceded structured interviews with propellant plant managers, procurement leads at personal care OEMs, pharmaceutical aerosol formulators, and regional chemical distribution partners. Primary fieldwork captured formulation specification trends, regulatory compliance timelines, and inventory hedging behaviors across European, North American, and Asia-Pacific supply chains. Secondary validation drew from SEC 10-K disclosures of integrated chemical producers, national VOC emission enforcement records from China's MEE, and ANVISA pharmaceutical registration databases. Bottom-up volume estimates from filling line capacity and offtake agreements were triangulated against top-down market sizing from feedstock consumption patterns.
Variance decomposition across product type, application segment, grade tier, and regional production hub drove analytical framework construction throughout the projection horizon. Segmentation modeling incorporated hydrocarbon versus dimethyl ether versus compressed gas chemistry splits, personal care versus pharmaceutical versus industrial end-use distinctions, and certification-grade versus standard-grade quality tiers. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs included EU F-Gas Regulation phase-down quota schedules and CDSCO regulatory harmonization implementation pacing.
Underlying assumptions cover sustained hydrocarbon feedstock availability, REACH and GB standards compliance timeline adherence, and flammability classification stability across transport modes, with deviation risk concentrated in propylene and butane price volatility, dimethyl ether purity supply concentration, and regulatory divergence between jurisdictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Pressure Filter Market
Industrial Chemicals
Global Substrate Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Industrial Phosphate Market
Industrial Chemicals
Heat Shrink Tubes Market