
 Industrial Oxygen Market | 2026-2036
Industrial Oxygen Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Oxygen Market Outlook
The capital-intensity divergence between on-site generation specialists and bulk liquid distributors is rotating competitive advantage toward integrated infrastructure owners. Linde plc leverages its global cryogenic network to sustain long-term supply contracts with steel producers across multiple continents. Air Liquide anchors its position through proprietary membrane and adsorption technologies that reduce customer energy costs. Messer Group competes by specializing in regional hub-and-spoke distribution models that serve mid-sized metal fabrication clusters.
Industrial oxygen is a high-purity gas typically exceeding 99.5% O₂ concentration, produced through cryogenic air separation, pressure swing adsorption, or vacuum pressure swing adsorption processes, and serves primarily as an oxidizing agent in combustion, chemical synthesis, and metal refining operations. The steel production application dominates volume consumption due to basic oxygen furnace requirements and electric arc furnace enrichment protocols. The pharmaceutical production segment commands premium pricing because batch consistency demands exceed standard industrial grades. Medical oxygen maintains structural separation from industrial supply chains despite overlapping production infrastructure, driven by pharmacopeia compliance and patient safety protocols.
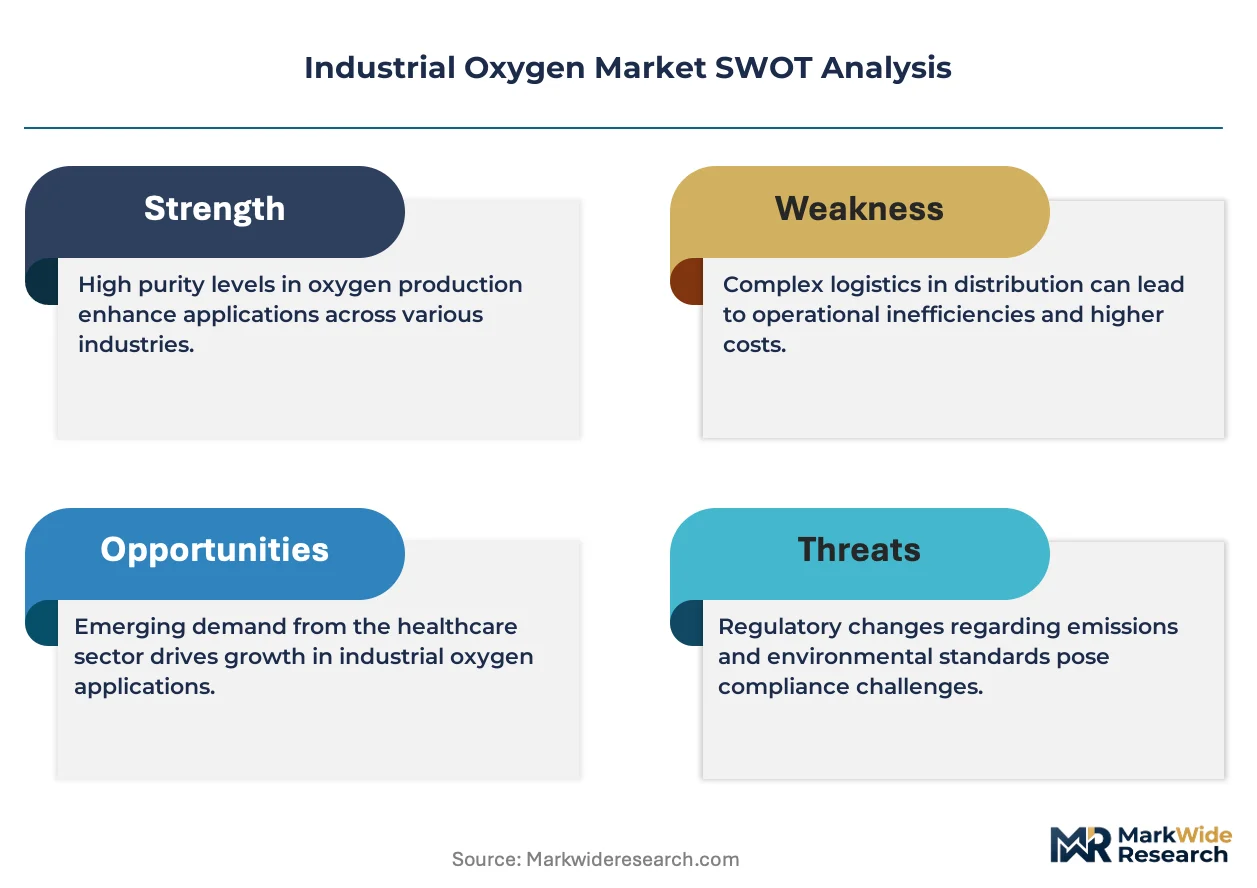
The US EPA and OSHA enforce emissions caps and workplace exposure limits that mandate leak detection and ventilation upgrades at oxygen production and consumption sites. The EU F-Gas Regulation and REACH framework indirectly shape equipment specifications by restricting certain compressor lubricants and sealing materials used in cryogenic systems. Stakeholders must monitor evolving carbon border adjustment mechanisms that could restructure cost competitiveness between regional production bases and import-dependent markets.
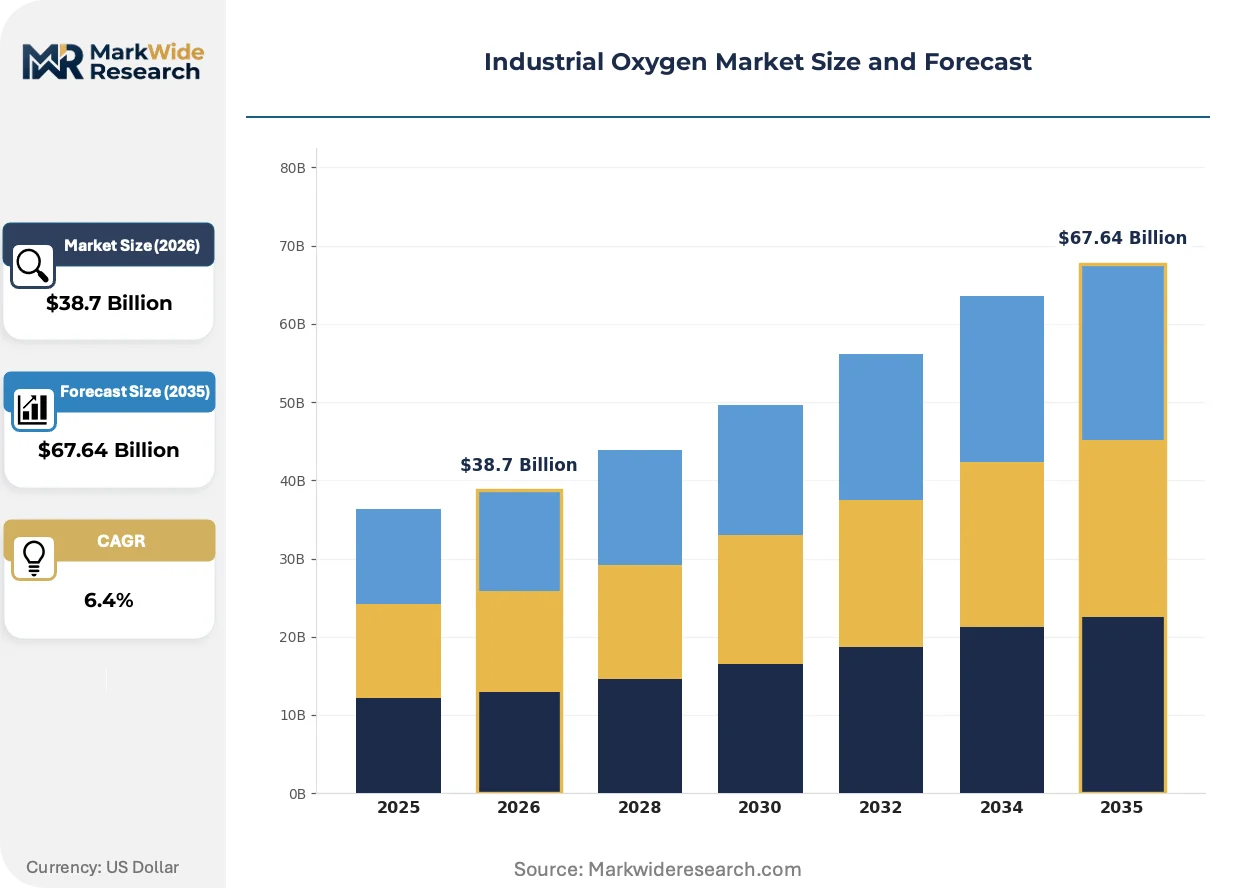
Market Dynamics
Steel producers in China and India are accelerating captive oxygen generation investments to sever dependency on merchant liquid supply, compressing the addressable market for bulk distributors while elevating long-term contract values for integrated infrastructure owners.
Growth Catalysts
- EPA and OSHA tightening:Emissions caps and workplace exposure mandates at US production facilities are forcing ventilation upgrades and leak detection systems that favor on-site generation over delivered bulk supply.
- Basic oxygen furnace intensity:Integrated steel complexes in East Asian manufacturing corridors require reliable high-volume oxygen delivery for converter operations, locking in decade-long supply agreements.
- Membrane technology maturation:Proprietary adsorption systems are reducing customer energy costs below cryogenic baselines, expanding addressable markets to mid-scale chemical synthesis operations.
Market Restraints
- Electricity cost volatility:Cryogenic air separation and pressure swing adsorption are power-intensive processes; grid price spikes in Germany and South Korea directly erode production economics.
- Merchant supply concentration:Hub-and-spoke distribution networks concentrate in regional clusters, leaving remote fabrication sites exposed to single-source dependency and transport cost premiums.
- Carbon border adjustment exposure:Emerging EU CBAM frameworks threaten to restructure cost competitiveness between import-dependent markets and regional production bases.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Rapid industrialization in Southeast Asian manufacturing corridors lacks corresponding oxygen infrastructure, creating first-mover positioning for on-site generation deployments.
- Pharmaceutical grade premium capture:Batch consistency demands exceeding standard industrial grades command pricing multiples, with pharmacopeia compliance creating structural separation from commodity supply chains.
- Green hydrogen feedstock convergence:Electrolysis-based hydrogen production requires oxygen as a co-product, enabling integrated energy-chemical complexes to monetize stranded output streams.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in vacuum insulation, turboexpander maintenance, and cold-box assembly is concentrating at legacy equipment manufacturers, constraining deployment velocity.
- Legacy system integration friction:Brownfield steel and chemical facilities face compressed downtime windows for connecting new on-site generation to existing distribution manifolds and safety interlocks.
- Pharmacopeia certification timelines:Medical oxygen qualification requires 18-24 month validation protocols that delay revenue recognition from dual-use production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Oxygen Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Medical Oxygen, Industrial Oxygen, Laser Cutting Oxygen, Oxygen for Aquaculture End User: Manufacturing, Healthcare, Metal Fabrication, Chemical Processing Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Third-Party Logistics Application: Welding, Water Treatment, Pharmaceutical Production, Steel Production |
| Companies Covered | Air Liquide, Linde plc, Air Products and Chemicals, Inc., Messer Group, Taiyo Nippon Sanso Corporation, Matheson Tri-Gas, Universal Industrial Gases, Iwatani Corporation, SOL SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Oxygen Market Strategic Shifts
Modular generation architectures and regulatory carbon accounting are compressing project development cycles, while procurement rationalization is consolidating buyer power among integrated steel and chemical complexes.
Containerized pressure swing adsorption units are miniaturizing. These skid-mounted systems serve mid-scale metal fabrication clusters requiring 10-50 tons per day without cryogenic infrastructure. Fabricators in Poland and Mexico are adopting lease-based deployment models that eliminate capital commitment. The technology is miniaturizing the minimum viable plant size, fragmenting demand across distributed production sites previously served by liquid bulk delivery.
EU F-Gas Regulation restrictions on certain compressor lubricants and sealing materials are reshaping equipment specifications for cryogenic systems. Manufacturers must reformulate rotating machinery to maintain efficiency under revised chemical compliance frameworks. Steel producers in Germany and the Netherlands face accelerated replacement cycles for cold-box compressors, elevating maintenance capital intensity.
Long-term take-or-pay contracts are displacing spot merchant purchases among integrated steel producers. Basic oxygen furnace operators in Japan and South Korea are consolidating procurement under decade-spanning agreements that bundle maintenance, energy optimization, and reliability guarantees. This concentration of buyer power is compressing margins for distributors lacking captive generation assets or proprietary technology differentiation.
Industrial Oxygen Market Segmentation
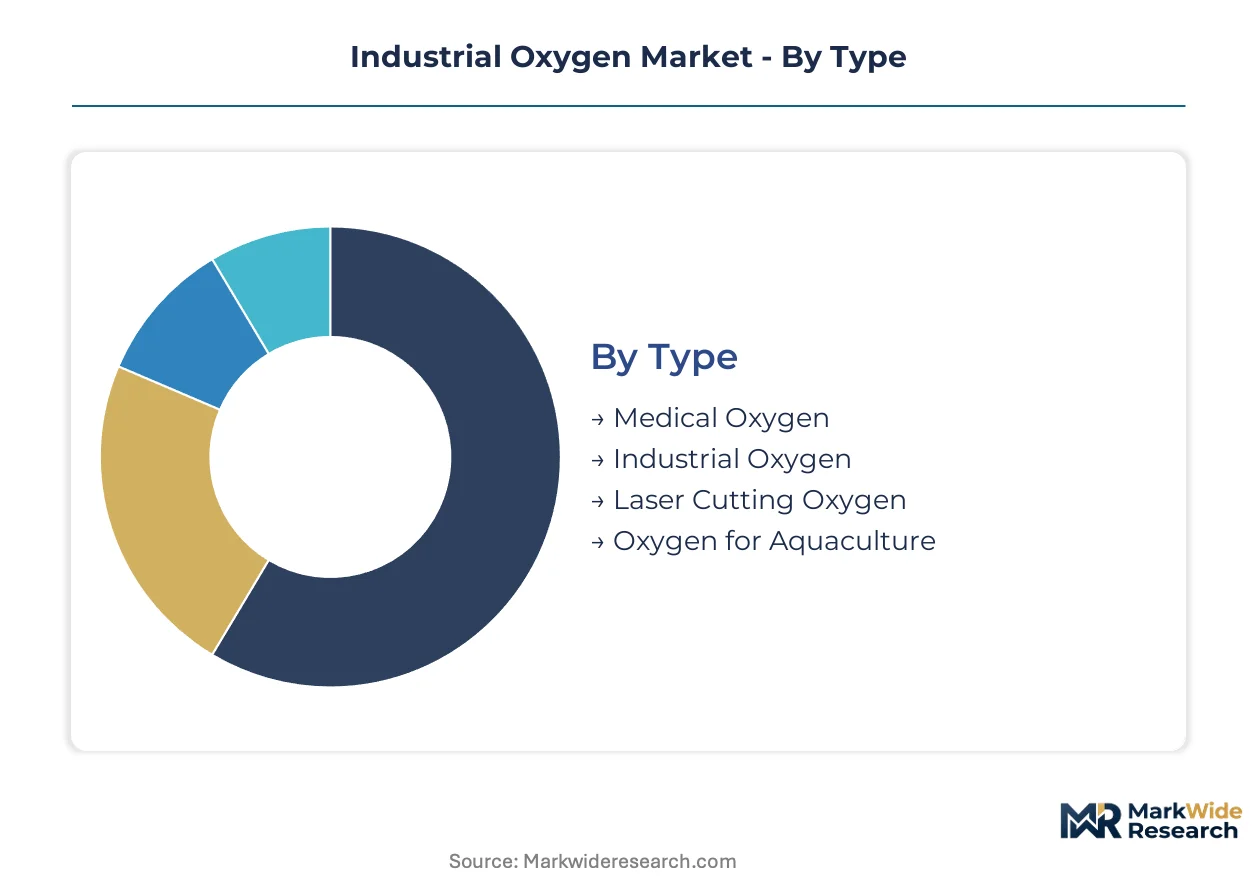
Industrial oxygen flows through distinct channel architectures shaped by purity thresholds, volume scale, and proximity to consumption points. Each segmentation dimension reveals how supply chain configuration determines margin capture and competitive positioning across steel, healthcare, and chemical end-uses.
Type:
Channel-mix varies sharply by purity grade, with medical and laser grades commanding specialized distribution while industrial bulk moves through integrated supply contracts.
- Industrial Oxygen:Standard-grade product exceeding 99.5% purity serves basic oxygen furnaces and combustion enrichment. Demand concentrates in East Asian steel corridors where integrated mills negotiate decade-long take-or-pay agreements with on-site generation providers.
- Medical Oxygen:Pharmacopeia-compliant grade requires 18-24 month validation protocols and maintains structural separation from industrial supply chains. German and Japanese hospital networks source through certified regional distributors with cold-chain integrity guarantees.
- Laser Cutting Oxygen:High-purity stream optimized for thermal cutting precision in metal fabrication clusters. Polish and Mexican job shops increasingly adopt lease-based PSA deployments to avoid cryogenic infrastructure investment.
- Oxygen for Aquaculture:Moderate-purity supply for dissolved oxygen management in intensive fish farming operations. Norwegian and Chilean salmon producers integrate generation with existing hatchery infrastructure.
Industrial oxygen dominates installed base. Medical oxygen is where expansion concentrates.
End User:
Cost-tier differentiation separates capital-intensive integrated producers from price-sensitive distributed consumers.
- Manufacturing:Broad category spanning automotive assembly, glass production, and electronics fabrication. German automotive OEMs bundle oxygen procurement with nitrogen and argon under multi-gas supply agreements.
- Healthcare:Hospitals, clinics, and home care providers require uninterrupted supply with redundant backup systems. Japanese medical gas distributors maintain 48-hour inventory buffers at regional hub facilities.
- Metal Fabrication:Mid-scale job shops and specialty processors generate 10-50 tons per day demand. Vietnamese and Indonesian fabrication corridors lack corresponding infrastructure, creating first-mover positioning for modular PSA deployments.
- Chemical Processing:Ethylene oxide and partial oxidation reactors consume high-volume continuous supply. US Gulf Coast petrochemical complexes favor pipeline-connected on-site generation over merchant liquid delivery.
Manufacturing commands volume leadership. Metal fabrication is climbing the fastest.
Distribution Channel:
Supply concentration shapes channel viability, with direct sales anchoring large accounts and distributors fragmenting across regional clusters.
- Direct Sales:Long-term contracts between producers and integrated steel or chemical complexes bundle equipment, maintenance, and energy optimization. Japanese and South Korean basic oxygen furnace operators consolidate procurement under single-source agreements spanning ten-plus years.
- Wholesale Distributors:Regional hub-and-spoke networks serve mid-sized fabrication sites with liquid bulk delivery and cylinder exchange programs. German metalworking clusters depend on concentrated distributor presence with single-source exposure.
- Third-Party Logistics:Specialized cryogenic transport providers handle last-mile delivery from production plants to consumption sites. EU F-Gas Regulation restrictions on compressor lubricants reshape equipment specifications across cold-chain logistics fleets.
- Online Retail:Digital platforms facilitate cylinder and concentrator procurement for small-scale welding and aquaculture operators. Limited to portable and packaged gas formats unsuitable for bulk industrial supply.
Direct sales anchors contract value. Third-party logistics is gaining share fastest.
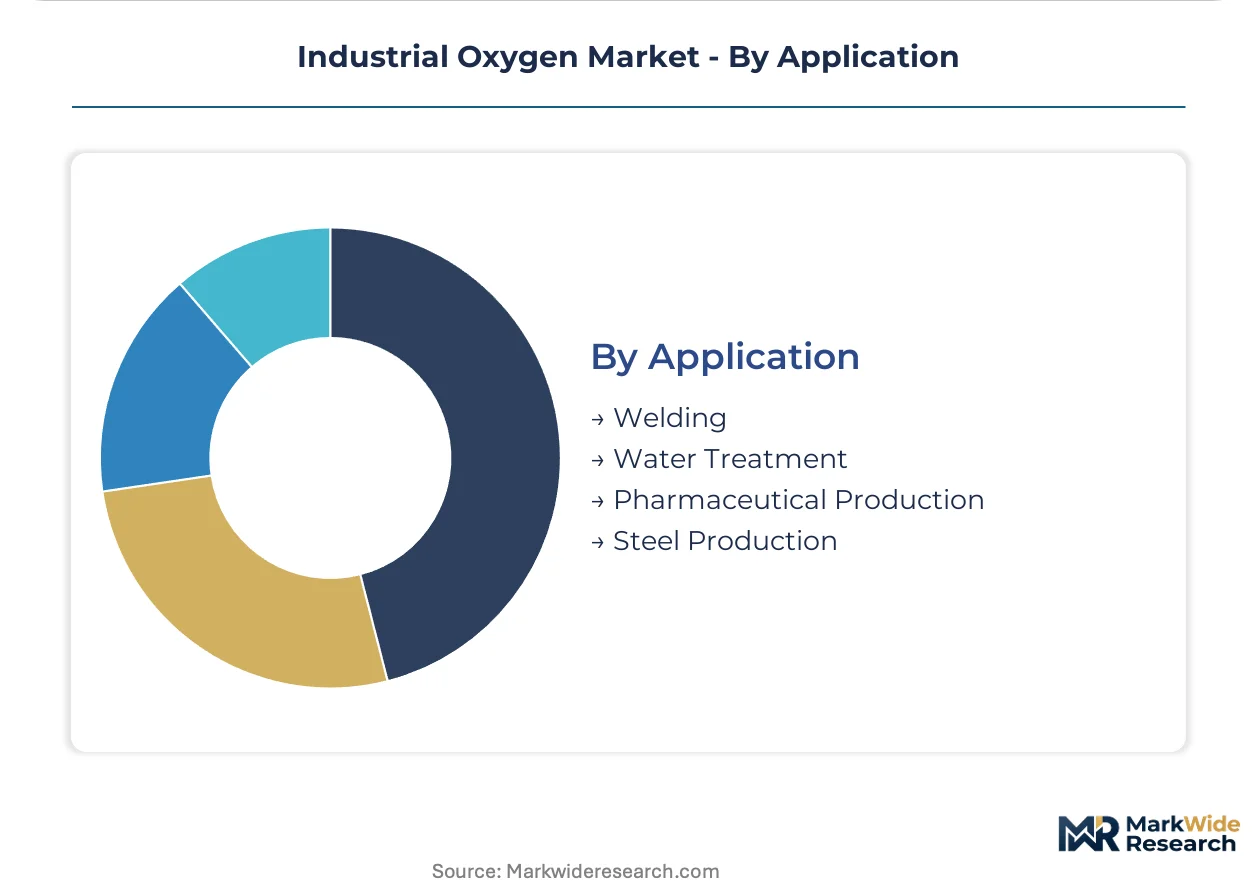
Application:
Volume-maturity divergence separates established steel and welding demand from emerging pharmaceutical and environmental applications.
- Steel Production:Basic oxygen furnace operations and electric arc furnace enrichment constitute the dominant volume consumption segment. Chinese and Indian producers are accelerating captive generation investments to sever merchant supply dependency.
- Welding:Oxy-fuel cutting and shielding gas mixtures serve construction and shipbuilding fabrication. Korean shipyards maintain dedicated oxygen pipelines from on-site air separation units.
- Pharmaceutical Production:Batch consistency demands exceeding standard industrial grades command pricing multiples. FDA and EMA pharmacopeia compliance creates structural separation from commodity supply chains.
- Water Treatment:Ozone generation and aerobic digestion applications in municipal and industrial wastewater facilities. Growing adoption of advanced oxidation processes in US and European treatment plants.
Steel production dominates installed base. Pharmaceutical production is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and the Netherlands exceeds that in Vietnam and Indonesia by substantial margins, reflecting infrastructure maturity gaps that shape competitive entry strategies across manufacturing corridors.
China
Steel producers in Hebei and Jiangsu provinces are accelerating captive oxygen generation investments to sever dependency on merchant liquid supply. MEE emissions enforcement and dual carbon goals mandate energy efficiency upgrades at air separation facilities. The Yangtze River Delta chemical complexes lock in decade-long supply agreements with integrated infrastructure owners.
United States
EPA emissions caps and OSHA workplace exposure mandates force ventilation upgrades and leak detection systems at Gulf Coast petrochemical complexes. The US Gulf Coast favors pipeline-connected on-site generation over merchant liquid delivery for ethylene oxide and partial oxidation reactors. Texas and Louisiana facilities bundle procurement under multi-gas supply agreements spanning ten-plus years.
Germany
EU F-Gas Regulation restrictions on compressor lubricants and sealing materials reshape equipment specifications for cryogenic systems across the Ruhr industrial belt. REACH framework compliance elevates maintenance capital intensity for cold-box compressors at steel producers. The automotive OEMs in Bavaria and Baden-Württemberg bundle oxygen procurement with nitrogen and argon under integrated supply contracts.
India
Steel producers in Odisha and Jharkhand are expanding captive oxygen generation capacity to reduce dependency on merchant supply from bulk distributors. BIS standards and state-level industrial safety regulations tighten equipment certification requirements. The Delhi-Mumbai Industrial Corridor chemical complexes require reliable high-volume oxygen delivery for continuous process operations.
Japan
Basic oxygen furnace operators in Chiba and Kanagawa prefectures consolidate procurement under decade-spanning take-or-pay agreements that bundle maintenance and reliability guarantees. METI industrial efficiency programs incentivize energy optimization at air separation units. The Kansai manufacturing belt maintains 48-hour inventory buffers at regional hub facilities for uninterrupted supply.
Industrial Oxygen Market Competitive Environment
Concentration sits with integrated cryogenic network operators and proprietary technology licensors. The vendor base spans three tiers: global infrastructure owners with captive generation assets, regional hub-and-spoke distributors serving mid-scale fabrication clusters, and modular PSA specialists penetrating underpenetrated Southeast Asian corridors. Dominant competitive moves include long-term contract bundling of equipment-maintenance-energy optimization and geographic expansion through first-mover on-site generation deployments in Vietnam and Indonesia.
Among global infrastructure owners, Linde plc and Air Liquide anchor the premium tier through cryogenic network scale and proprietary membrane-adsorption technologies. Messer Group occupies a position within the regional specialist archetype, concentrating hub-and-spoke distribution across European metal fabrication clusters. Taiyo Nippon Sanso Corporation represents the Asia-Pacific integrated operator archetype, with positioning tied to Japanese steel and chemical complex relationships. These three exemplify how competitive advantage rotates toward integrated infrastructure ownership and proprietary technology differentiation.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products and Chemicals, Inc. |
| Messer Group |
| Taiyo Nippon Sanso Corporation |
| Matheson Tri-Gas |
| Universal Industrial Gases |
| Iwatani Corporation |
| SOL SpA |
| Others |
Value Chain & Pricing Dynamics
Long-term take-or-pay contracts between steel producers and on-site generation providers lock in supply access and price visibility across multi-year horizons, insulating integrated mills from electricity cost volatility while compressing margin flexibility for merchant liquid distributors.
Pricing Analysis
Configured-to-order pricing for on-site generation systems commands a 15-30% premium over standard merchant liquid supply, reflecting engineering customization and bundled maintenance services. Price differentiation separates pharmacopeia-certified medical oxygen from industrial bulk grades, with FDA and EMA compliance tiers adding certification overhead. Cost compression in standard industrial grades is intensifying as Chinese and Indian steel producers accelerate captive generation investments. Mid-scale metal fabrication clusters in Poland and Mexico exhibit the highest price sensitivity, driving adoption of lease-based PSA deployments that eliminate capital commitment.
Supply Chain Analysis
China, the United States, and Germany anchor cryogenic air separation capacity, with Hebei province and the US Gulf Coast housing the largest integrated production clusters. Production economics draw from electricity pricing, compressor lubricant formulations restricted under EU F-Gas Regulation, and specialized cold-box engineering talent concentrated at legacy equipment manufacturers. Single-source vulnerability runs through regional hub-and-spoke distribution networks serving German metalworking clusters. Distribution runs through pipeline-connected on-site generation for integrated steel complexes, liquid bulk delivery for mid-scale fabrication, and cylinder exchange for portable applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial oxygen market sits at a platform-economics inflection where electrolysis-based hydrogen production creates oxygen co-product monetization opportunities, rewiring competitive advantage toward integrated energy-chemical complexes with stranded output stream capture capabilities.
For Market Incumbents: Shield long-term contract portfolios from substitution pressure by deepening captive generation penetration in East Asian steel corridors and embedding energy optimization services that reduce customer power intensity. Accelerate proprietary membrane-adsorption R&D to maintain technology differentiation against modular PSA specialists targeting underpenetrated Southeast Asian fabrication clusters. For New Entrants and Emerging Players: Differentiate on deployment speed and capital-light lease structures to capture Vietnamese and Indonesian metal fabrication corridors lacking corresponding oxygen infrastructure. Target pharmaceutical-grade oxygen qualification as the most penetrable premium segment, exploiting 18-24 month pharmacopeia validation timelines that delay incumbent revenue recognition from dual-use assets. For Investors and Strategic Acquirers: Capital is best deployed toward integrated infrastructure owners with captive generation assets and decade-long supply contracts, rather than regional liquid distributors facing margin compression from electricity cost volatility. Watch carbon border adjustment mechanism implementation as the critical inflection signal that could restructure cost competitiveness between import-dependent markets and regional production bases.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Japanese and South Korean basic oxygen furnace operators consolidate procurement under decade-spanning contracts bundling maintenance and reliability guarantees. |
| Backward Integration | Chinese and Indian steel producers expand captive oxygen generation capacity to sever dependency on merchant liquid supply from bulk distributors. |
| Green Manufacturing Transition | EU F-Gas Regulation restrictions on compressor lubricants reshape equipment specifications and accelerate replacement cycles for cold-box compressors. |
| Capacity Expansion | Vietnamese and Indonesian fabrication corridors lack corresponding oxygen infrastructure, creating first-mover positioning for modular PSA deployments. |
| Joint Venture | Electrolysis-based hydrogen production requires oxygen as a co-product, enabling integrated energy-chemical complexes to monetize stranded output streams. |
Study Parameters
A spread of perspectives from plant engineers at integrated steel complexes, procurement leads at petrochemical facilities, technical R&D directors at air separation unit manufacturers, and distribution channel partners converged on the working assumptions. Primary interviews combined with secondary validation from EPA emissions filings, OSHA workplace exposure standards, EU F-Gas Regulation compliance documentation, and customs trade data for cryogenic equipment imports. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the analysis window.
Segmentation dimensions modeled include purity grade tier, end-use industry application, distribution channel architecture, and regional production hub clustering. CAGRs were derived from production capacity buildout trajectories, steel output forecasts, and electrification intensity assumptions. Industry-specific forecast inputs incorporated MEE emissions enforcement timelines in China and METI industrial efficiency program incentives in Japan.
The analysis sits within stated boundaries; outcomes outside sustained steel production intensity, stable electricity pricing in Germany and South Korea, or unchanged pharmacopeia certification timelines would require recalibration. Forecasts reflect documented assumptions about captive generation investment velocity and modular PSA technology maturation. Recalibration cycles align with material shifts in carbon border adjustment mechanism scope and electrolysis-based hydrogen production deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
High Purity Methane Gas Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
Argon Gas Market
Industrial Gases
Syngas Market
Industrial Gases
Europe Syngas Market
Industrial Gases
Food-Grade Gases Market
Industrial Gases
Asia-Pacific Syngas Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Gas Processing Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market