
 Metal Cutting Gas Market | 2026-2036
Metal Cutting Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Cutting Gas Market Foresight
Buyer concentration among Asian shipbuilders and Korean heavy-industry contractors is shifting procurement power toward volume-contract frameworks. Linde plc leverages its on-site generation infrastructure to anchor long-term supply agreements at major yards. Air Liquide competes through localized liquid oxygen networks that sustain delivery reliability across fragmented port geographies. Messer Group GmbH specializes in customized acetylene-oxygen blends that differentiate its offering for thick-plate cutting applications.
Metal cutting gas denotes industrial-grade reactive or inert gases, typically oxygen with purity exceeding 99.5 percent or acetylene with defined flame temperature parameters, deployed to generate controlled exothermic reactions that sever ferrous and non-ferrous alloys. The primary commercial purpose centers on achieving precise kerf geometry with minimal slag adhesion across fabrication, demolition, and repair operations. Oxygen dominates product type revenue due to its irreplaceable role in oxy-fuel cutting of carbon steel, while propane gains structural share in lower-temperature applications where cost efficiency outweighs thermal intensity. Industrial cutting anchors application demand through continuous consumption at automotive stamping plants and structural steel mills, whereas on-site generation represents the fastest-expanding delivery mode as large fabricators seek to decouple from cylinder logistics.
The US OSHA and EPA jointly govern workplace exposure limits and emissions profiles for acetylene and propane storage facilities, compelling distributors to upgrade containment systems and vapor recovery hardware. China's MEE enforces dual carbon goals that tighten emissions benchmarks for gas production plants, redirecting capital toward electrolytic oxygen and lower-carbon feedstock pathways. The EU F-Gas Regulation and REACH framework restrict certain fluorinated additives and mandate chemical safety documentation across imported gas mixtures. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate compliance cost allocation and supply chain restructuring.
Market Dynamics
On-site gas generation infrastructure is compressing traditional cylinder distribution economics, forcing merchant suppliers to restructure contract frameworks around captive production assets at major fabrication clusters.
Growth Catalysts
- Shipbuilding intensity:Korean and Chinese yards consume high-purity oxygen-acetylene blends for precision hull cutting, anchoring volume demand at coastal industrial nodes.
- EU F-Gas Regulation:Mandates for lower-carbon gas formulations accelerate R&D investment in reformulated blends and alternative feedstock pathways.
- Plasma-oxygen hybrid systems:Thick-plate fabricators adopt combined thermal cutting technologies that sustain oxy-fuel gas consumption while improving kerf quality.
Market Restraints
- Acetylene feedstock volatility:Calcium carbide price swings and energy input costs destabilize margin structures for packaged gas distributors.
- Merchant supply concentration:Three industrial gas majors control bulk liquid oxygen terminals at major East Asian port complexes, limiting buyer negotiation leverage.
- Substitution by fiber laser:Thin-sheet metal processors in automotive stamping increasingly bypass thermal cutting entirely, eliminating gas offtake.
Strategic Opportunities
- India's PLI scheme:Domestic manufacturing incentives for specialty steel and shipbuilding create captive generation opportunities at greenfield industrial corridors.
- Electrolytic oxygen pathways:Renewable-powered electrolysis enables zero-carbon oxygen production aligned with EU Green Deal procurement criteria.
- Direct-to-fabricator digital channels:Telemetry-enabled cylinder tracking and automated reordering systems bypass traditional distributor networks.
Industry Challenges
- Welding technician certification gaps:Shortages of oxy-fuel cutting specialists delay deployment of precision gas mixtures at expanding Southeast Asian yards.
- Legacy cylinder fleet retrofit costs:Compliance with updated pressure vessel standards requires capital-intensive requalification of existing logistics assets.
- Multi-jurisdiction documentation:REACH chemical safety filings, EPA emissions reporting, and MEE carbon audits create overlapping compliance burdens for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Cutting Gas Market |
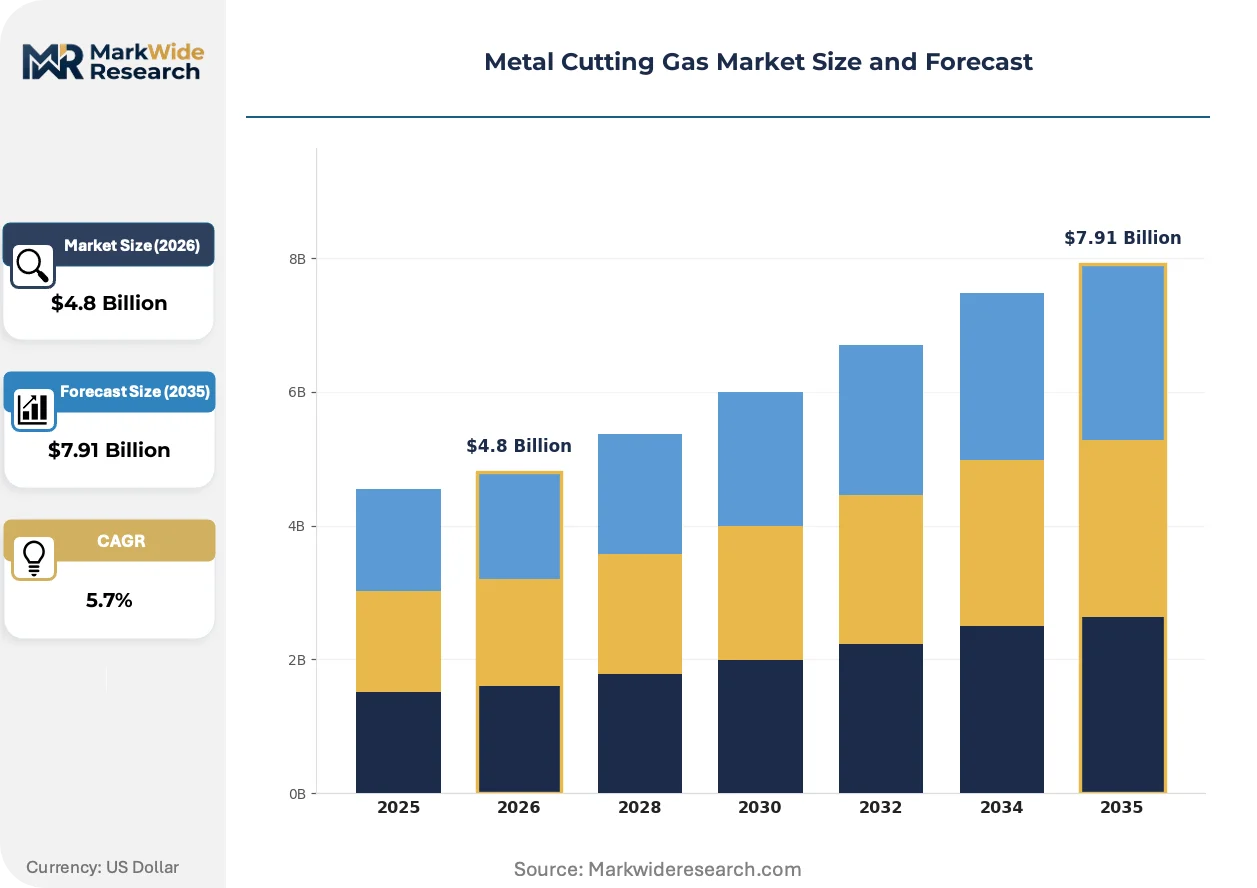
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen, Acetylene, Propane, Nitrogen Application: Welding, Industrial Cutting, Jewelry Manufacturing, Automotive Repairs End User: Manufacturing Plants, Repair Workshops, Construction Companies, Metal Fabricators Delivery Mode: Cylinders, Bulk Tanks, On-Site Generation, Liquid Form |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Messer Group GmbH, Matheson Tri-Gas, Inc., Taiyo Nippon Sanso Corporation, Nippon Sanso Holdings Corporation, Air Water Inc., Iwatani Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Cutting Gas Market Shifts & Advancements
Plasma-oxygen hybrid cutting architectures and renewable-powered on-site generation are restructuring how industrial gases reach fabrication floors. These shifts compress traditional merchant supply chains while elevating purity and carbon-intensity specifications.
Plasma-oxygen hybrid torches integrate high-velocity plasma arcs with concentric oxygen jets for thick stainless and mild steel severing. Major structural steel contractors in Germany and Japan are retrofitting existing oxy-fuel stations with these systems. The technology is electrifying thermal cutting operations by reducing pure oxygen consumption per meter of cut while maintaining exothermic reaction efficiency.
The EU F-Gas Regulation imposes phasedown schedules for fluorinated greenhouse gases used in certain specialty cutting blends and mandates carbon footprint disclosure for imported gas mixtures. Gas formulators must requalify product portfolios under ECHA REACH documentation protocols. Korean industrial gas subsidiaries serving EU-exporting shipyards face the steepest reformulation timelines and are accelerating low-GWP additive substitution programs.
Volume-contract procurement with embedded price-indexation clauses is displacing spot cylinder purchases at major automotive and heavy-equipment stamping plants. Tier-one fabricators in China's Yangtze River Delta now specify take-or-pay structures tied to steel throughput volumes. This behavioral shift concentrates purchasing power among consolidated manufacturing groups while marginalizing independent job shops dependent on traditional distributor relationships.
Metal Cutting Gas Market Segmentation
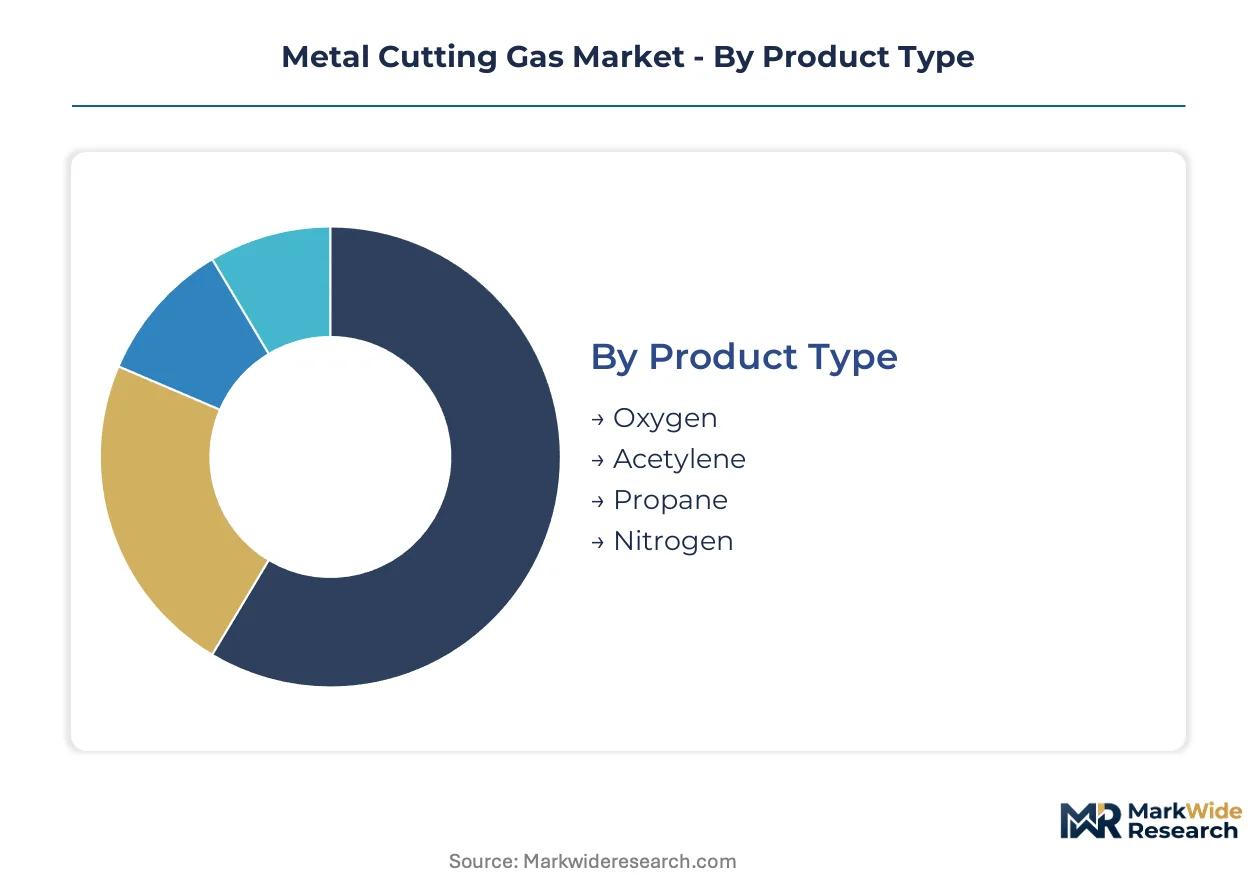
Metal cutting gas procurement patterns diverge sharply across product specifications, end-use intensity, and logistics infrastructure. Understanding these segment boundaries clarifies where volume concentrates versus where margin structures favor specialized supply arrangements.
Product Type:
Purity thresholds and flame temperature specifications differentiate commercial positioning across reactive and inert gas categories.
- Oxygen:Industrial-grade oxygen exceeding 99.5% purity drives oxy-fuel cutting of carbon steel through controlled exothermic reactions. Korean shipbuilders at Ulsan and Geoje anchor volume demand for high-purity grades in precision hull severing operations.
- Acetylene:Defined flame temperature parameters around 3,100°C enable precise kerf geometry in thick-plate applications. Calcium carbide feedstock volatility from Chinese producers destabilizes margin structures for packaged distributors serving fragmented repair networks.
- Propane:Lower thermal intensity suits cost-sensitive operations where cutting speed trades off against fuel economy.
- Nitrogen:Inert shielding properties protect stainless steel kerf zones from oxidation during plasma-assisted severing.
Oxygen leads on scale; acetylene leads on momentum in premium fabrication segments.
Application:
Process intensity and precision requirements segment demand across thermal joining, severing, and finishing operations.
- Industrial Cutting:Continuous consumption at automotive stamping plants and structural steel mills sustains bulk oxygen offtake. China's Yangtze River Delta industrial cluster concentrates demand for high-volume oxy-fuel severing of carbon steel plate.
- Welding:Oxy-acetylene flame temperatures enable fusion joining of ferrous alloys in field repair contexts. German automotive suppliers specify certified gas mixtures for chassis fabrication quality assurance.
- Automotive Repairs:Cylinder-based propane and oxygen supply serves collision repair shops with intermittent consumption patterns.
- Jewelry Manufacturing:Precision flame control requirements drive demand for ultra-high-purity acetylene in precious metal joining.
Industrial cutting commands volume concentration; welding maintains technology leadership in specification development.
End User:
Scale economics and technical capability requirements stratify procurement behavior across integrated and fragmented buyer types.
- Manufacturing Plants:Continuous process demand justifies captive on-site generation infrastructure. Japanese heavy-equipment producers at Komatsu and Hitachi Zosen yards specify take-or-pay contracts tied to steel throughput.
- Metal Fabricators:Batch production patterns favor bulk liquid oxygen terminals with telemetry-enabled replenishment systems.
- Construction Companies:Mobile cutting requirements sustain cylinder distribution networks for structural steel erection sites.
- Repair Workshops:Fragmented demand and credit constraints limit contract penetration among independent service providers.
Manufacturing plants lead on scale; metal fabricators climb the fastest in contract sophistication.
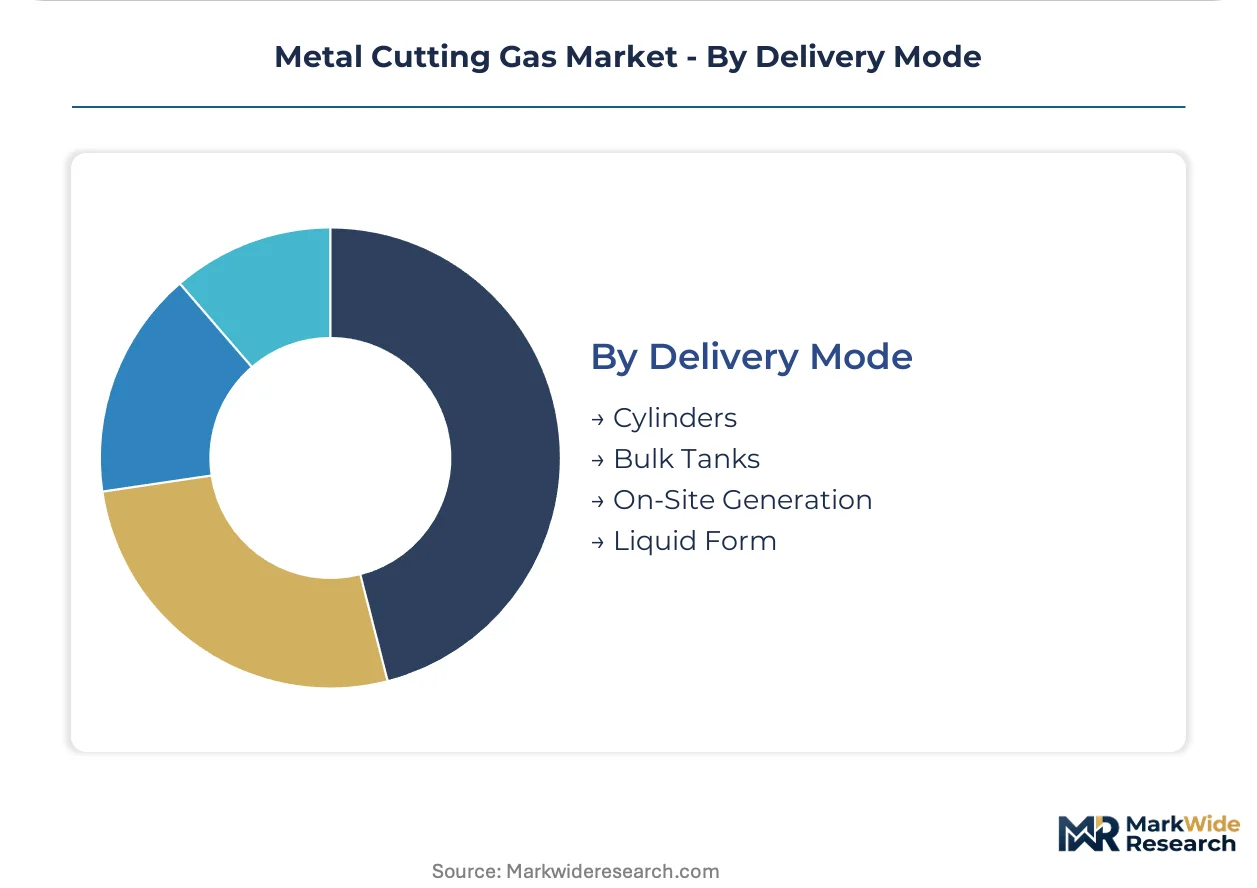
Delivery Mode:
Logistics configuration and capital intensity determine competitive positioning across merchant and captive supply structures.
- On-Site Generation:Air separation units at major fabrication clusters decouple volume consumers from cylinder logistics. Renewable-powered electrolytic pathways align with EU Green Deal procurement criteria for carbon-intensive steel severing.
- Liquid Form:Cryogenic tanker networks sustain delivery reliability across fragmented port geographies in Southeast Asian shipbuilding corridors.
- Bulk Tanks:Intermediate-scale storage serves regional metal service centers with predictable consumption patterns.
- Cylinders:Traditional packaged gas distribution faces compression from on-site alternatives at volume accounts while retaining niche positioning in mobile and intermittent applications.
On-site generation leads on scale; liquid form gains share fastest in coastal industrial node development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta industrial cluster generates higher oxygen throughput than Germany's Ruhr Valley steel corridor, yet Korean shipbuilders at Ulsan and Geoje command premium pricing for high-purity acetylene blends.
China
Structural steel mills and automotive stamping plants in Jiangsu and Zhejiang provinces consume bulk liquid oxygen through take-or-pay contracts tied to steel throughput. MEE enforces dual carbon goals that tighten emissions benchmarks for gas production plants, redirecting capital toward electrolytic oxygen pathways. The Yangtze River Delta industrial cluster concentrates demand for high-volume oxy-fuel severing of carbon steel plate at Baosteel and Shagang facilities.
South Korea
Shipbuilders at DSME and Hyundai Heavy Industries anchor volume demand for precision hull-cutting gas mixtures with purity exceeding 99.5 percent. MFDS maintains workplace exposure limits for acetylene storage facilities that compel distributors to upgrade containment systems. The Ulsan-Geoje coastal corridor hosts captive on-site generation infrastructure decoupling major yards from cylinder logistics.
Germany
Structural steel contractors retrofit existing oxy-fuel stations with plasma-oxygen hybrid torches for thick stainless and mild steel severing. ECHA REACH documentation protocols mandate chemical safety filings for imported gas mixtures. The Ruhr Valley industrial belt sustains demand for certified gas mixtures among automotive chassis fabricators and heavy-equipment producers.
United States
Automotive stamping plants in Michigan and Ohio specify telemetry-enabled cylinder tracking and automated reordering systems bypassing traditional distributor networks. OSHA and EPA jointly govern workplace exposure limits and emissions profiles for acetylene and propane storage facilities. The Great Lakes manufacturing corridor concentrates bulk oxygen offtake at Ford and General Motors stamping operations.
Japan
Heavy-equipment producers at Komatsu and Hitachi Zosen yards specify take-or-pay contracts tied to steel throughput volumes. METI promotes renewable-powered electrolysis pathways enabling zero-carbon oxygen production aligned with procurement criteria. The Chubu-Nagoya industrial zone sustains delivery reliability through cryogenic tanker networks serving fragmented port geographies.
Metal Cutting Gas Market Competitive Landscape
European producers anchor one tier; East Asian specialists hold differentiated positions in high-purity formulation. Three industrial gas majors control bulk liquid oxygen terminals at major East Asian port complexes, creating a consolidated supply structure around captive generation assets. Strategic archetypes include integrated industrial gas conglomerates with on-site infrastructure, regional formulators specializing in customized acetylene-oxygen blends, and merchant distributors with telemetry-enabled logistics networks. Capacity expansion and strategic partnerships dominate competitive moves as suppliers restructure contract frameworks around captive production assets.
Within the integrated conglomerate tier, Linde plc and Air Liquide exemplify global-scale positioning through on-site generation infrastructure and localized liquid oxygen networks respectively. Among German-based formulators, Messer Group GmbH occupies a position representing specialized acetylene-oxygen blend customization for thick-plate cutting applications. These three anchors reflect the market's bifurcation between volume-driven infrastructure plays and precision formulation specialists.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Messer Group GmbH |
| Matheson Tri-Gas, Inc. |
| Taiyo Nippon Sanso Corporation |
| Nippon Sanso Holdings Corporation |
| Air Water Inc. |
| Iwatani Corporation |
| Others |
Supply & Pricing Matrix
Plasma-oxygen hybrid torches are compressing per-meter oxygen consumption while elevating purity specifications, simultaneously fragmenting traditional merchant supply economics and concentrating pricing power among on-site generation specialists at Korean and Chinese fabrication clusters.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for bulk liquid oxygen through take-or-pay contracts tied to steel throughput volumes. Three-tier pricing structure across premium, standard, and economy levels differentiates high-purity acetylene blends for precision hull cutting against commodity propane for cost-sensitive repair shops. Pricing pressure stems from calcium carbide feedstock volatility destabilizing packaged gas distributor margins. Repair workshops exhibit highest price sensitivity due to fragmented demand and credit constraints, while Korean shipbuilders at DSME and Hyundai Heavy Industries accept premium positioning for certified gas mixtures.
Supply Chain Analysis
Cryogenic tanker freight costs from coastal air separation units to inland fabrication centers compress margin structures for merchant distributors serving China's Jiangsu and Zhejiang provinces. Supply concentrates in China, South Korea, and Germany, with calcium carbide feedstock, renewable electricity for electrolytic pathways, and high-purity oxygen extraction equipment anchoring input dependencies. Single-source vulnerability around Chinese calcium carbide producers exposes formulators to energy input cost swings. Distribution runs through captive on-site generation at major automotive stamping plants and structural steel mills, with liquid form networks sustaining coastal shipbuilding corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal cutting gas market reads as a late-cycle quality story, with Korean shipbuilders and German automotive chassis fabricators shifting procurement toward certified high-purity blends that command structural premiums over commodity alternatives.
For Market Incumbents: Deepen backward integration into calcium carbide production or renewable-powered electrolytic oxygen pathways to insulate margin structures from feedstock volatility. Anchor long-term supply agreements at major East Asian shipyards through captive on-site generation infrastructure, while accelerating low-GWP additive substitution programs to preempt EU F-Gas Regulation compliance deadlines.
For New Entrants and Emerging Players: Begin with India's PLI scheme corridors, where domestic manufacturing incentives for specialty steel and shipbuilding create greenfield captive generation opportunities underserved by established liquid oxygen networks. Target metal fabricators in Southeast Asian port geographies with telemetry-enabled cylinder tracking systems that bypass traditional distributor relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional acetylene-oxygen blend formulators with specialized thick-plate capabilities but limited on-site infrastructure scale. Long-term viability hinges on electrolytic oxygen pathway investments aligned with EU Green Deal procurement criteria. Watch for MFDS and MEE emissions benchmark tightening as inflection signals for capital reallocation toward lower-carbon production assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calcium Carbide | Secures feedstock supply for acetylene production against Chinese producer price volatility. |
| Electrolytic Oxygen Pathway Investment | Enables zero-carbon production aligned with EU Green Deal procurement criteria at German steel mills. |
| Telemetry-Enabled Cylinder Tracking | Bypasses traditional distributor networks for fragmented repair workshops in US Great Lakes corridor. |
| Plasma-Oxygen Hybrid Torch Retrofit | Reduces pure oxygen consumption per meter while maintaining kerf quality at Japanese heavy-equipment yards. |
| Long-Term Supply Agreement Restructuring | Locks in take-or-pay contracts tied to steel throughput at China's Baosteel and Shagang facilities. |
Research Methodology
Multiple input streams — primary interviews with industrial gas procurement managers, shipyard operations directors, and regulatory compliance officers; secondary validation through customs/trade data, SEC filings from listed industrial gas conglomerates, and ECHA REACH documentation protocols — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from plant engineers and aftermarket service heads to model projections across the analysis window. Segmentation dimensions included purity grade tier, end-use application intensity, delivery mode configuration, and regional production hub clustering. CAGRs were derived from reconciling supply-side capacity expansion announcements with demand elasticity estimates from automotive stamping and shipbuilding sectors.
Several conditions sit outside the modeled scope, including abrupt calcium carbide export restrictions, unilateral regulatory phaseout schedules for fluorinated additives, and breakthrough fiber laser substitution rates in thin-sheet automotive applications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
High Purity Methane Gas Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Asia-Pacific Industrial Gases Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Middle-East and Africa Syngas Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Global Argon Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
Noble Gas Market
Industrial Gases
Helium Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
Xenon Gas Market