
 Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market | 2026-2036
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market Insights
Long-term hydrogen supply contracting is consolidating as the dominant commercial model for industrial cluster decarbonization. Air Liquide leverages its pipeline network density across the Port of Rotterdam to anchor offtake agreements with steel and chemical producers. Linde plc sustains technology leadership through high-pressure electrolyzer integration and cryogenic logistics specialization. Nel ASA competes on modular PEM electrolyzer manufacturing scale, positioning its standardized units for rapid cluster deployment timelines.
Low-carbon hydrogen solutions for industrial cluster decarbonization encompass engineered systems that produce, purify, store, and distribute hydrogen with greenhouse gas emissions below conventional steam methane reforming thresholds, typically targeting carbon intensities under two kilograms of CO2 equivalent per kilogram of hydrogen through electrolysis, pyrolysis, or biomass gasification pathways. These installations serve concentrated industrial zones where multiple heavy emitters share pipeline backbone, storage caverns, and offtake infrastructure to achieve collective decarbonization at lower unit cost than isolated facility upgrades. Electrolysis technology dominates current deployment pipelines due to its compatibility with renewable electricity sourcing and modular scaling, while biomass gasification represents a nascent but growing pathway where agricultural residue feedstocks cluster near industrial demand centers. Steel manufacturing and ammonia production applications command the largest share of committed offtake volumes, reflecting their limited electrification alternatives and exposure to carbon border adjustment mechanisms.
The EU ETS, F-Gas Regulation, and national hydrogen bank frameworks collectively shape project economics by setting carbon price floors, restricting high-global-warming-potential refrigerants in liquefaction systems, and providing production subsidies that bridge cost gaps with grey hydrogen benchmarks. The EPA in the United States and MEE in China operate parallel certification schemes that influence equipment standards and cross-border technology trade flows. Stakeholders must monitor how evolving carbon accounting methodologies for imported hydrogen reshape competitive positioning between domestic production and international supply corridors.
Market Dynamics
The EU ETS carbon price mechanism is compressing project payback periods for industrial cluster hydrogen retrofits, forcing steel and ammonia producers to accelerate offtake commitments before 2030 compliance deadlines tighten.
Growth Catalysts
- EU Hydrogen Bank auction mechanism:Germany, the Netherlands, and Belgium channel production subsidies that bridge cost gaps with grey hydrogen benchmarks, accelerating electrolyzer deployment timelines across the Rhine-Ruhr corridor.
- Steel sector blast furnace replacement:Hydrogen-direct reduction technology commands committed offtake volumes as carbon border adjustment mechanisms expose European steel exports to competitive disadvantage.
- Rotterdam-Antwerp pipeline clustering:Shared backbone infrastructure enables collective storage cavern utilization and distribution cost amortization across multiple chemical producers.
Market Restraints
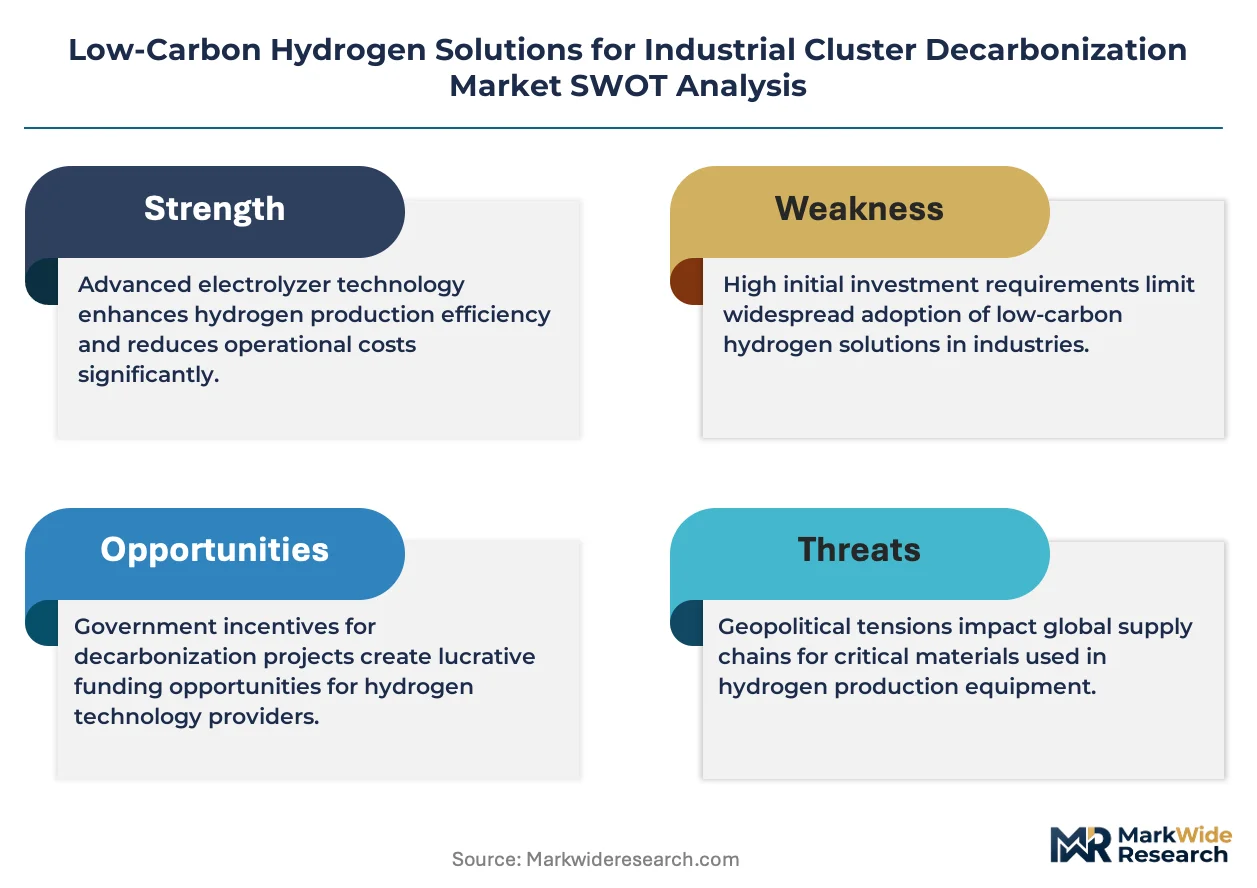
- Renewable electricity price volatility:Electrolyzer operators face margin compression when wind and solar capture prices spike above contracted baseload thresholds.
- European electrolyzer manufacturing concentration:Supply bottlenecks for PEM stack membranes and bipolar plates concentrate in German and Norwegian component suppliers.
- F-Gas Regulation refrigerant restrictions:Liquefaction system retrofits face extended certification timelines as hydrofluorocarbon alternatives require redesigned heat exchanger architectures.
Strategic Opportunities
- Biomass gasification pathway expansion:Agricultural residue feedstock clusters near industrial demand centers in northern France and Poland enable carbon-negative hydrogen production claims.
- Offshore wind-to-hydrogen integration:North Sea lease auctions in Dutch and German waters pair electrolyzer platforms with dedicated pipeline injection points.
- CSRD disclosure mandates:Corporate sustainability reporting requirements force Scope 3 emissions transparency, driving chemical purchasers toward certified low-carbon hydrogen contracting.
Industry Challenges
- High-pressure electrolyzer technician scarcity:Specialized commissioning and maintenance expertise for 700-bar systems concentrates with Linde plc and Air Liquide service networks.
- Cross-border hydrogen certification harmonization:Divergent carbon accounting methodologies between CertifHy, TÜV SÜD, and proposed ISO 19870 standards create trade friction.
- Legacy ammonia plant retrofit complexity:Haber-Bosch reactor integration with hydrogen supply requires extended shutdown windows that compress annual production volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market |
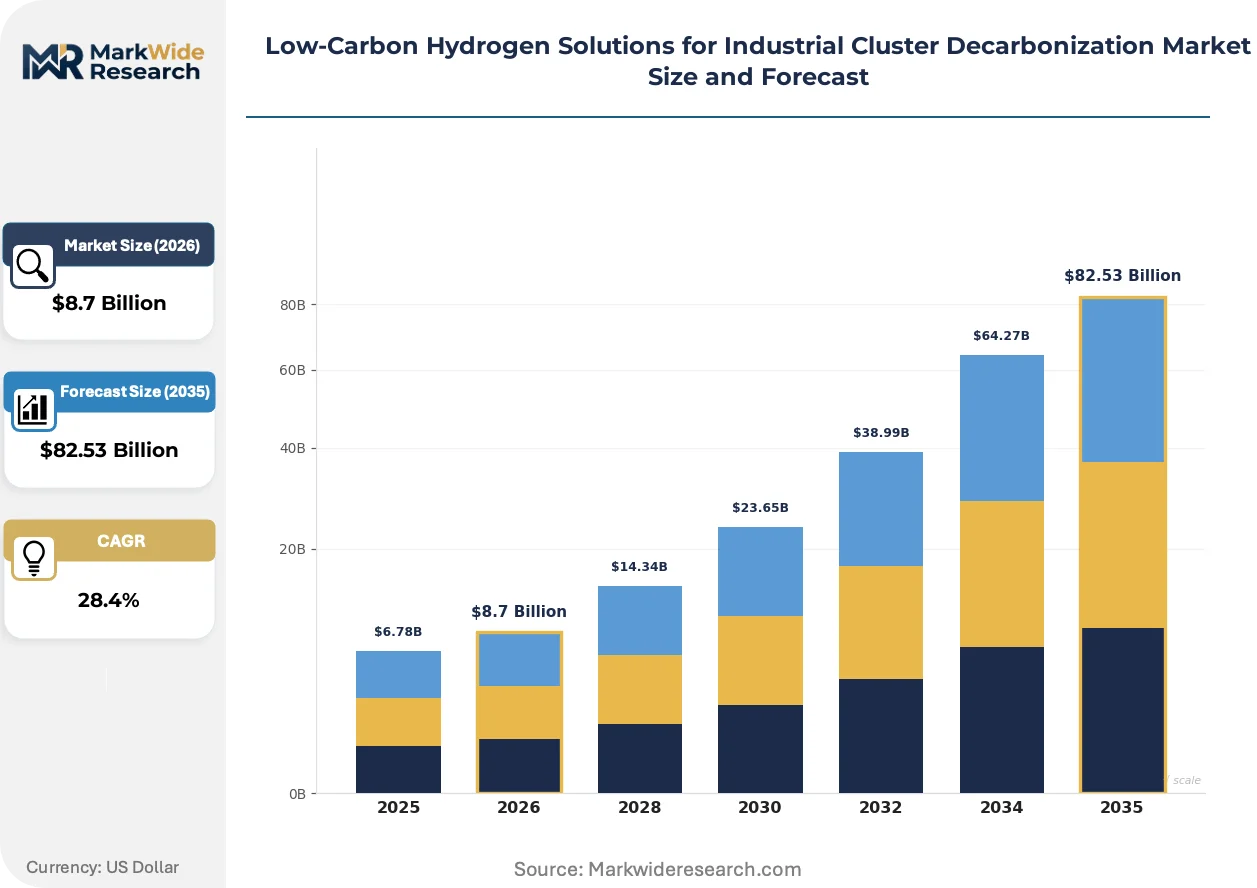
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Steam Methane Reforming, Pyrolysis, Biomass Gasification, Coal Gasification, Sorption Enhanced Reforming Application: Power Generation, Steel Manufacturing, Chemical Production, Refineries, Fertilizer Synthesis, Ammonia Production End User: Electric Utilities, Metal Producers, Petrochemical Plants, Fertilizer Manufacturers, Energy Service Companies, Specialty Chemical Firms Deployment: Onsite Production, Centralized Production, Distributed Production, Pipeline Integration, Storage Facilities, Export Terminals |
| Companies Covered | Air Liquide, Linde plc, Air Products and Chemicals, Siemens Energy, Shell, Engie, Nel ASA, ITM Power, Plug Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market Trends and Innovations
Electrolyzer technology trajectories and procurement model evolution are compressing deployment timelines while regulatory frameworks harden certification requirements for imported hydrogen supply chains.
Solid oxide electrolysis is overtaking alkaline systems for high-temperature industrial integration. Steel producers in the Port of Rotterdam cluster adopt SOE units for waste heat co-utilization. This thermal efficiency advantage is overtaking pure electricity cost metrics in total cost of ownership calculations for integrated steel-ammonia complexes.
The F-Gas Regulation is tightening refrigerant phase-down schedules for hydrogen liquefaction infrastructure. Equipment suppliers must redesign cold box architectures using natural refrigerant cascades. Chemical offtakers in Belgium and the Netherlands face accelerated capital replacement cycles for existing storage terminals.
Steel and ammonia buyers are consolidating procurement through 10-15 year hydrogen purchase agreements with take-or-pay structures. Long-term contracting replaces spot market exposure as the dominant commercial model. This shift concentrates most visibly in German industrial clusters where bankability requirements for project finance mandate revenue certainty.
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market Segmentation
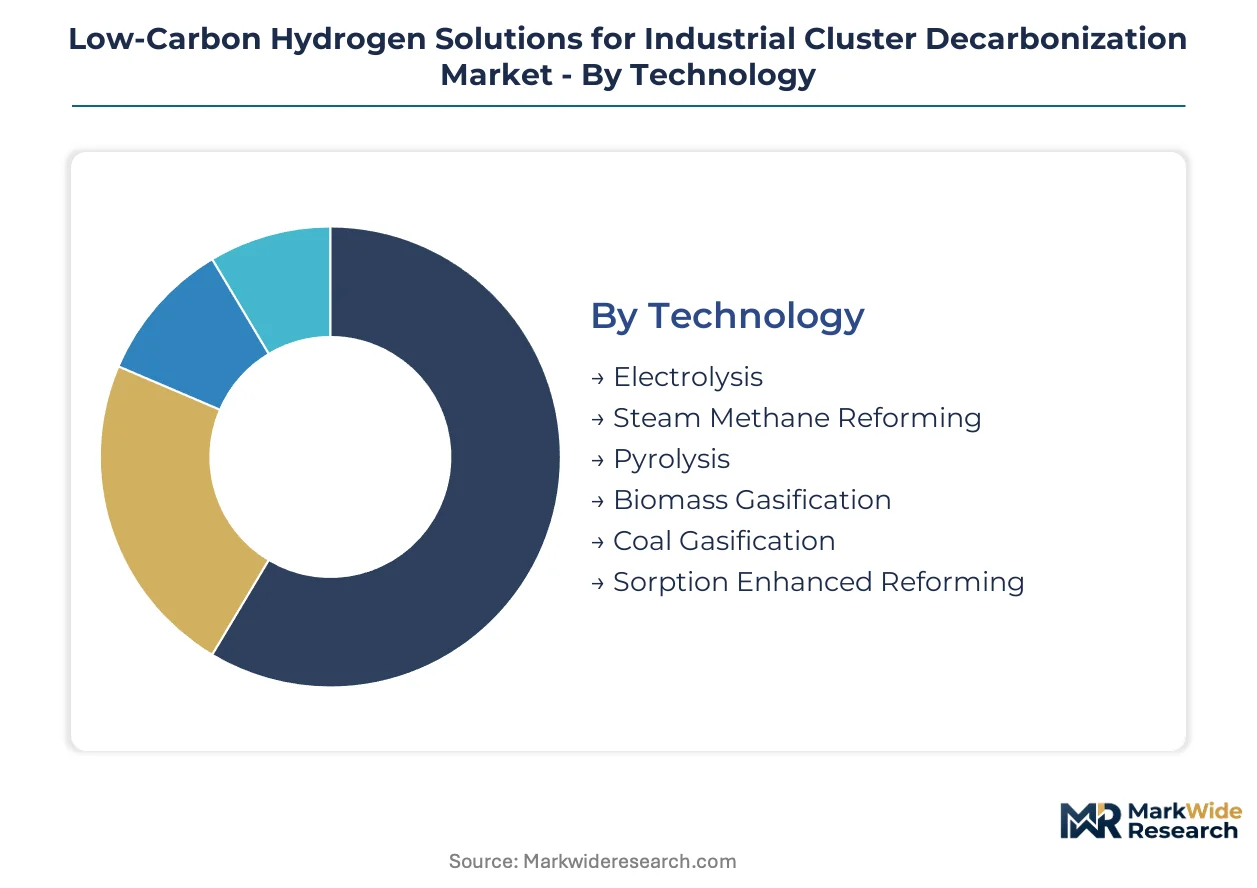
Segmentation in low-carbon hydrogen solutions reveals how technology pathways, application requirements, and infrastructure configurations determine project bankability and offtake contracting structures. Each dimension shapes capital allocation decisions differently across European industrial clusters.
Technology:
Electrolysis systems dominate current deployment pipelines due to their compatibility with renewable electricity sourcing and modular scaling capabilities.
- Electrolysis:Alkaline and proton exchange membrane systems split water using renewable electricity, achieving carbon intensities below two kilograms CO2 equivalent per kilogram hydrogen. Steel producers in the Rhine-Ruhr corridor favor PEM units for rapid response to grid price signals.
- Steam Methane Reforming:Conventional methane reforming paired with carbon capture achieves near-term cost parity with grey hydrogen while awaiting electrolyzer scale-up. Dutch chemical clusters deploy SMR-CCS as bridge infrastructure during renewable electricity capacity buildout.
- Pyrolysis:Thermal decomposition of methane yields hydrogen and solid carbon without CO2 emissions, attracting interest from carbon black manufacturers seeking feedstock integration.
- Biomass Gasification:Agricultural residue conversion enables carbon-negative production claims where feedstock clusters exist near industrial demand centers in northern France and Poland.
- Coal Gasification:High-carbon intensity pathway faces declining competitiveness under EU ETS price trajectories and carbon border adjustment exposure.
- Sorption Enhanced Reforming:Integrated carbon capture within the reaction vessel reduces equipment footprint and capture energy penalties for distributed production scenarios.
Electrolysis leads on scale; Biomass Gasification leads on momentum.
Application:
Application segmentation tracks where hydrogen substitutes for carbon-intensive feedstocks or fuels under regulatory compliance pressure.
- Steel Manufacturing:Hydrogen-direct reduction replaces coke in blast furnace operations, commanding committed offtake volumes as carbon border adjustment mechanisms expose European steel exports to competitive disadvantage.
- Ammonia Production:Haber-Bosch reactor retrofits require high-purity hydrogen supply with minimal nitrogen contamination, driving specifications for electrolyzer outlet gas treatment systems.
- Chemical Production:Hydrogen serves as reduction agent and hydrogenation feedstock across methanol, refining, and specialty chemical processes in Rotterdam-Antwerp pipeline clusters.
- Refineries:Hydrocracking and desulfurization units consume hydrogen for fuel quality upgrading, with demand concentrated in Belgian and Dutch coastal facilities.
- Fertilizer Synthesis:Ammonia-derived nitrogen fertilizer production integrates with agricultural supply chains, linking hydrogen cost to food security policy frameworks.
- Power Generation:Turbine blending and fuel cell applications represent emerging demand with lower volume certainty than industrial feedstock contracts.
Steel Manufacturing anchors committed volumes; Ammonia Production shows the steepest expansion trajectory.
End User:
End user categories reflect organizational capacity for long-term contracting and infrastructure co-investment.
- Metal Producers:Integrated steel and aluminum companies with blast furnace assets drive demand for high-pressure hydrogen delivery systems and direct reduction pilot programs.
- Petrochemical Plants:Refinery and olefin producers leverage existing hydrogen networks while retrofitting for low-carbon supply integration.
- Fertilizer Manufacturers:Yara and similar operators seek supply security through equity participation in electrolyzer projects rather than pure merchant offtake.
- Electric Utilities:Power sector buyers prioritize flexible hydrogen supply for peaking generation and grid balancing services.
- Energy Service Companies:Third-party operators aggregate smaller industrial demand into bankable offtake pools for project finance.
- Specialty Chemical Firms:Pharmaceutical and fine chemical producers require ultra-high purity grades with stringent contamination specifications.
Metal Producers dominate capital deployment; Energy Service Companies are gaining share fastest through demand aggregation models.
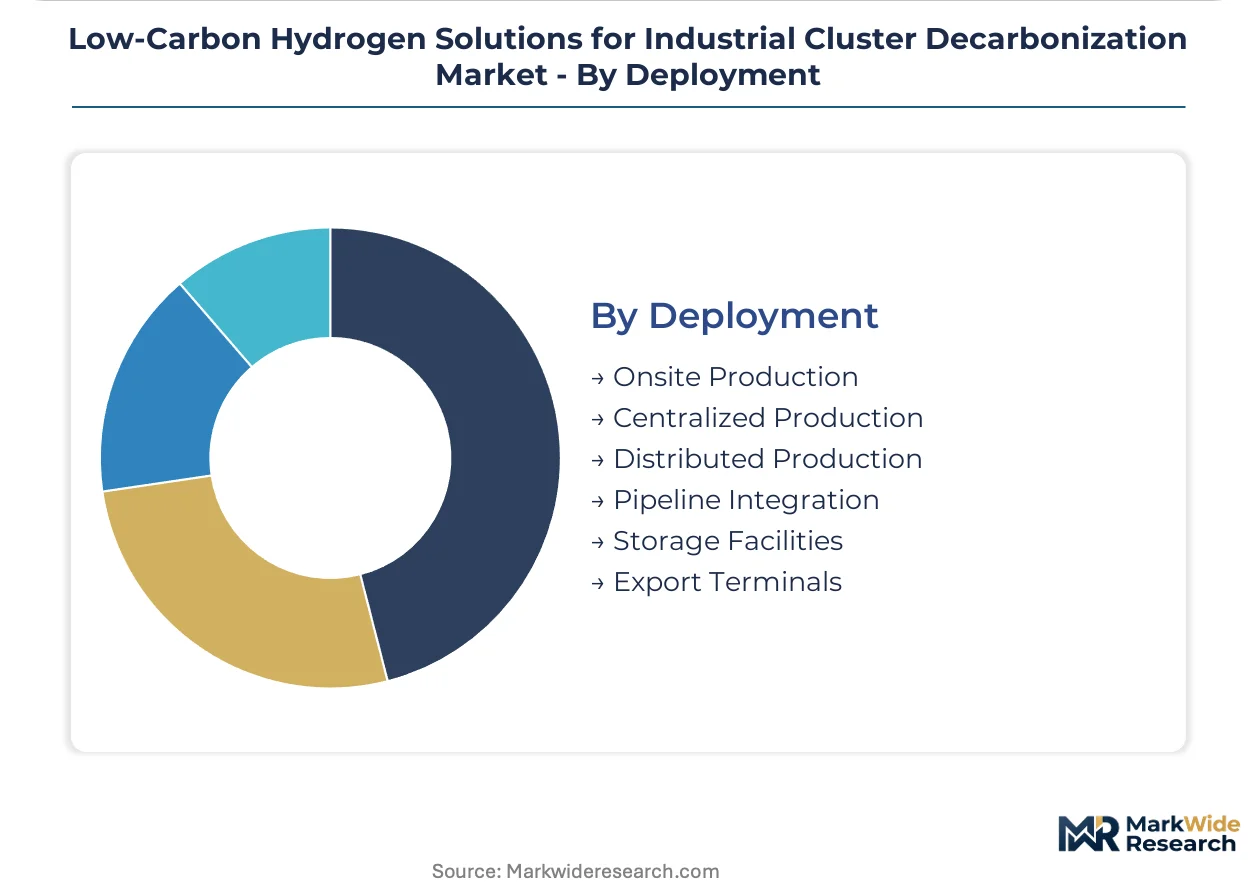
Deployment:
Deployment configuration determines infrastructure sharing economics and regulatory jurisdiction for certification.
- Pipeline Integration:Backbone connections to Rotterdam-Antwerp and Rhine-Ruhr networks enable collective storage cavern utilization and distribution cost amortization across multiple offtakers.
- Centralized Production:Large-scale electrolyzer parks achieve equipment and labor efficiencies while requiring dedicated transmission infrastructure investment.
- Onsite Production:Captive electrolyzers eliminate transport costs for isolated facilities with sufficient renewable electricity access or grid connection capacity.
- Distributed Production:Modular PEM units serve smaller industrial clusters without pipeline access, trading scale economies for location flexibility.
- Storage Facilities:Salt cavern and depleted field storage provides seasonal buffering against renewable generation intermittency.
- Export Terminals:Liquefaction and ammonia conversion infrastructure positions supply for intercontinental trade under evolving carbon accounting methodologies.
Pipeline Integration captures the largest committed volumes; Onsite Production is climbing fastest as electrolyzer capital costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces the Netherlands in committed electrolyzer capacity while Belgium concentrates more storage cavern development per square kilometer than any neighbor.
Germany
Steel producers in the Rhine-Ruhr corridor drive hydrogen demand for blast furnace replacement, with ThyssenKrupp and Salzgitter anchoring offtake volumes. The national hydrogen strategy channels EU Hydrogen Bank subsidies toward electrolyzer deployment timelines. The Port of Rotterdam pipeline extension into German industrial zones enables shared infrastructure economics across chemical clusters in Duisburg and Dortmund.
Netherlands
Offshore wind-to-hydrogen platforms in Dutch North Sea waters pair electrolyzer capacity with dedicated pipeline injection points. The F-Gas Regulation tightens refrigerant phase-down schedules for liquefaction infrastructure at Rotterdam terminals. Chemical producers in the Rotterdam-Antwerp corridor leverage collective storage cavern utilization across multiple offtakers.
Belgium
Ammonia producers in the Port of Antwerp cluster seek high-purity hydrogen supply for Haber-Bosch reactor retrofits with minimal nitrogen contamination. The EU ETS carbon price mechanism compresses project payback periods for industrial hydrogen retrofits. Steel and chemical offtakers share backbone pipeline infrastructure enabling distribution cost amortization.
France
Agricultural residue feedstock clusters in northern France enable biomass gasification pathways for carbon-negative hydrogen production claims. The CSRD disclosure mandates force Scope 3 emissions transparency among chemical purchasers. Industrial demand centers in Lille and Dunkirk position for pipeline integration with Belgian and Dutch networks.
Poland
Coal-dependent steel and chemical sectors face accelerating EU ETS compliance pressure with limited renewable electricity capacity for electrolysis. The country's national hydrogen strategy prioritizes SMR-CCS bridge infrastructure during renewable buildout. Agricultural residue availability in northern provinces supports emerging biomass gasification pilot projects near industrial clusters.
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated gas majors controlling pipeline backbone assets while pure-play electrolyzer vendors compete on modular deployment speed. The vendor base concentrates around three strategic archetypes: infrastructure incumbents with captive distribution networks, technology specialists with proprietary stack designs, and project developers aggregating offtake demand. Dominant competitive moves include strategic partnerships for co-investment in shared storage caverns and technology licensing agreements that accelerate manufacturing scale-up without capital-heavy capacity builds.
Within the infrastructure incumbent tier, Air Liquide and Linde plc exemplify archetypes built on pipeline network density and cryogenic logistics specialization respectively. Nel ASA occupies a position among modular technology specialists, representing the standardized PEM manufacturing scale that compresses cluster deployment timelines. These three anchors illustrate how competitive positioning diverges between asset-heavy distribution control and manufacturing-led deployment acceleration.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products and Chemicals |
| Siemens Energy |
| Shell |
| Engie |
| Nel ASA |
| ITM Power |
| Plug Power |
| Others |
Pricing and Supply Chain Analysis
European electricity spot price indices cascade through electrolyzer operating costs into three-tier pricing structures across premium, standard, and economy levels. Renewable capture price volatility in German and Dutch markets compresses margin buffers for merchant hydrogen producers while reinforcing long-term offtake contracting premiums.
Pricing Analysis
Capacity additions in the Netherlands and Germany are reshaping price floors for pipeline-delivered hydrogen. Pricing stratifies across premium, standard, and economy tiers based on CertifHy certification grade and volume scale commitments. Cost compression in standard-tier supply is intensifying because PEM stack manufacturing scale is outpacing alkaline system deployment. Fertilizer manufacturers show highest price sensitivity due to thin ammonia margins, while steel producers absorb premiums for high-pressure delivery reliability.
Supply Chain Analysis
Dual-sourcing requirements from offtakers like ThyssenKrupp and Yara mandate qualified suppliers across German, Norwegian, and Belgian component manufacturers. PEM stack membranes and bipolar plates draw from concentrated European specialty materials suppliers. Single-source vulnerability persists for iridium catalyst coatings sourced from South African refiners. Distribution runs through Rotterdam-Antwerp pipeline backbone with last-mile compression skids at cluster boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where steel and ammonia buyers are consolidating procurement around certified low-carbon specifications rather than grey hydrogen substitutes.
For Market Incumbents: Extend pipeline network density through shared storage cavern co-investment with chemical clusters in the Rotterdam-Antwerp corridor. Anchor offtake agreements using take-or-pay structures before modular PEM vendors achieve manufacturing scale that erodes incumbent technology premiums. Prioritize backward integration into offshore wind development to secure captive renewable electricity supply. For New Entrants and Emerging Players: Enter via agricultural residue aggregation networks in northern France and Poland where biomass gasification pathways face limited incumbent competition. Target distributed production configurations for smaller industrial clusters without pipeline access, using standardized PEM units that compress deployment timelines versus centralized project development cycles. Lead with carbon-negative production claims that command certification premiums under evolving EU carbon accounting methodologies. For Investors and Strategic Acquirers: Asymmetric upside sits with project developers holding permitted North Sea lease positions paired with electrolyzer platform engineering capabilities. Five-to-ten year viability hinges on EU Hydrogen Bank subsidy continuity and carbon border adjustment mechanism enforcement stringency. Monitor F-Gas Regulation refrigerant phase-down timelines as inflection indicator for liquefaction infrastructure replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Steel producers anchor project finance through 10-15 year offtake commitments with take-or-pay structures. |
| Backward Integration | Electrolyzer operators secure captive renewable electricity through offshore wind equity participation in Dutch waters. |
| Joint Venture | Shared storage cavern development amortizes capital across multiple chemical offtakers in Belgian clusters. |
| Technology Licensing | PEM stack manufacturers accelerate scale without capital-heavy capacity builds through regional licensing agreements. |
| Green Certification Program | CertifHy and TÜV SÜD certification investments differentiate supply for CSRD-mandated Scope 3 disclosure compliance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged electrolyzer project developers, steel procurement directors, ammonia plant engineering leads, and EU hydrogen bank program officers. Secondary validation drew from EIA hydrogen production databases, IEA technology roadmaps, FERC interconnection filings, and project development tracking services. Bottom-up electrolyzer capacity buildout estimates triangulated against top-down industrial hydrogen demand projections.
Segment-weighting approaches distributed value across technology pathways, application requirements, and deployment configurations. The analytical framework modeled electrolysis versus biomass gasification momentum, steel versus ammonia offtake growth trajectories, and pipeline versus onsite production economics across the projection horizon. CAGRs derived from equipment cost learning curves, renewable electricity price trajectories, and carbon price mechanism sensitivity analysis. Forecast inputs incorporated EU ETS price band assumptions and national hydrogen strategy subsidy continuity scenarios.
Inputs from electrolyzer OEM order backlogs and industrial offtake announcement trackers were available through the study window; gaps in final investment decision timing for announced projects introduce uncertainty bands around capacity deployment schedules. Forecasts reflect documented assumptions regarding EU regulatory framework stability and renewable electricity buildout rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Neon Gas Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Asia-Pacific Industrial Gases Market
Industrial Gases
Noble Gas Market
Industrial Gases
Argon Gas Market
Industrial Gases
Welding Gas Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Syngas Market
Industrial Gases
Krypton Gas Market
Industrial Gases
Middle-East and Africa Syngas Market