
 Gas Processing Market | 2026-2036
Gas Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Processing Market Analysis
Middle Eastern sour gas capacity is shifting toward integrated treatment complexes. Exxon Mobil Corporation leverages its Permian Basin infrastructure to anchor downstream processing economics. Linde PLC sustains cryogenic technology leadership through proprietary liquefaction cycles. Shell plc competes on floating LNG platforms that reduce onshore footprint constraints.
Gas processing encompasses the treatment, separation, and conditioning of raw natural gas to pipeline specifications, typically requiring acid gas removal below four percent CO2 and dehydration to seven pounds per million cubic feet. The primary purpose is to extract methane for pipeline delivery while recovering natural gas liquids for petrochemical feedstock. Amine gas treatment dominates existing plant retrofits due to proven reliability in high-volume sulfur removal. Membrane separation occupies the fastest-expanding technology tier for offshore and remote field applications. Natural gas liquids represents the most margin-intensive product category, with ethane and propane fractions commanding premium offtake from Gulf Coast crackers.
The EPA enforces methane performance standards under New Source Performance Standards 40 CFR Part 60 Subpart OOOOa, compelling operators to replace pneumatic controllers and implement leak detection protocols. OSHA's Process Safety Management standard governs handling thresholds for amine solutions and cryogenic fluids in onshore facilities. ISO 13628-7 provides subsea production system specifications that shape equipment procurement for deepwater gas developments. Stakeholders must weigh carbon capture retrofit economics against greenfield hydrogen-ready plant designs when committing capital to next-generation processing infrastructure.
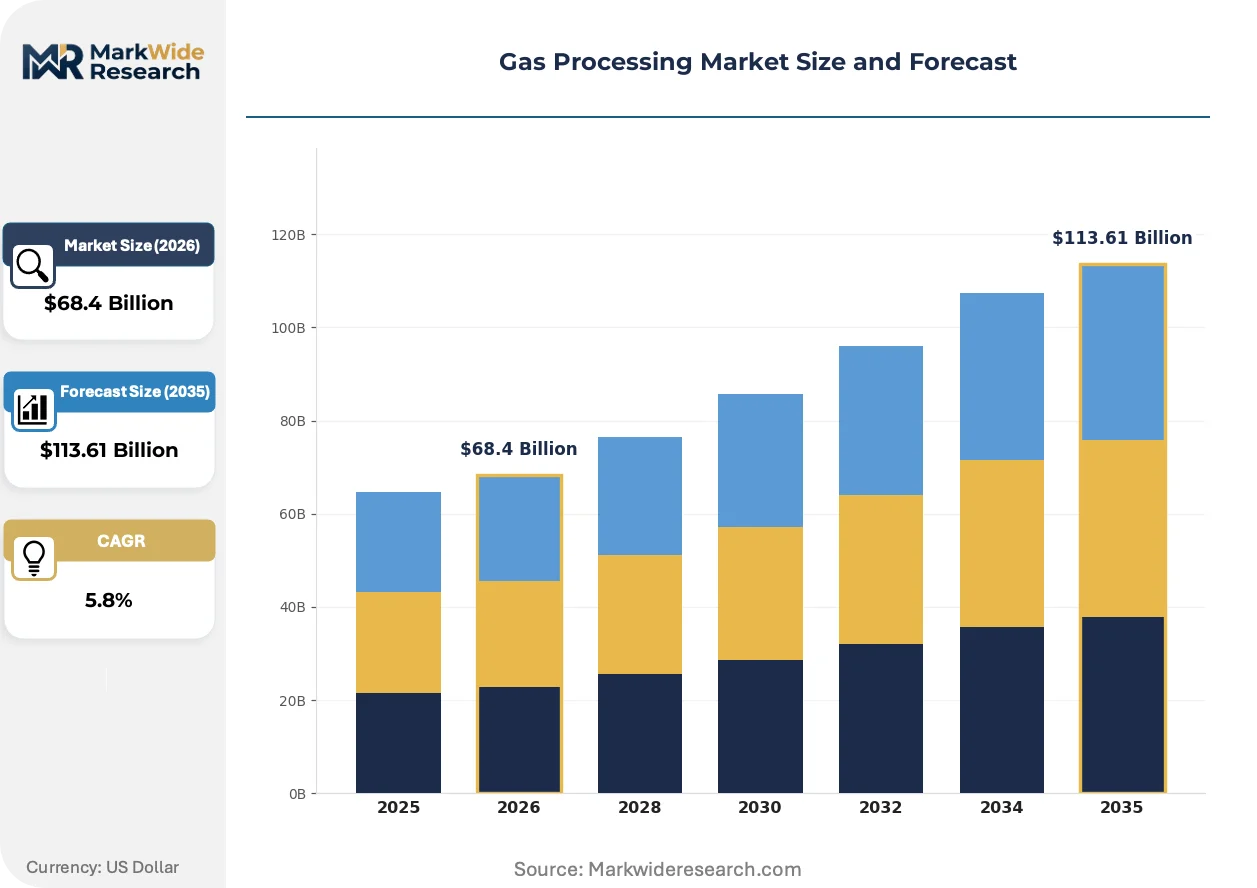
Market Dynamics
Capital migration toward LNG export infrastructure is compressing processing capacity availability for domestic petrochemical buyers, while EPA methane rules force simultaneous equipment replacement cycles across North American facilities.
Growth Catalysts
- 40 CFR Part 60 Subpart OOOOa:The EPA's methane performance standards mandate pneumatic controller replacement and leak detection protocols, compelling facility upgrades that expand equipment procurement pipelines.
- Qatar-Saudi concentration:Middle Eastern sour gas processing demand clusters around integrated treatment complexes, drawing engineering and construction capacity toward high-specification projects.
- Natural gas liquids recovery:Ethane and propane fractionation for Gulf Coast crackers generates margin premiums that justify capital-intensive cryogenic separation investments.
Market Restraints
- Amine solution volatility:Monoethanolamine and diethanolamine supply chains concentrate among specialty chemical producers, exposing processors to input cost swings without backward integration options.
- Deepwater equipment procurement:ISO 13628-7 subsea production specifications limit qualified supplier pools for high-pressure gas treatment systems, creating single-source dependencies.
- Electrification substitution:Grid-scale battery storage and renewable hydrogen projects compete for the same institutional capital pools that historically funded gas processing infrastructure.
Strategic Opportunities
- Carbon capture retrofits:Post-combustion amine scrubbing and cryogenic carbon capture units create upgrade revenue streams at existing dehydration and acid gas removal facilities.
- Hydrogen-ready plant designs:Greenfield processing infrastructure configured for hydrogen blending and methanol synthesis feedstock prepares operators for fuel-transition scenarios.
- Membrane separation convergence:Polymeric membrane systems paired with pressure swing adsorption enable modular, skid-mounted treatment packages for remote and offshore field development.
Industry Challenges
- Cryogenic fluid handling expertise:OSHA Process Safety Management thresholds for liquefied natural gas and nitrogen refrigeration systems exceed available certified technician supply in several producing regions.
- Legacy SCADA integration:Digital methane monitoring and automated leak detection systems must interface with decades-old distributed control architectures without triggering unplanned shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Processing Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Gas Liquids, Gas Conditioning Equipment, Gas Compressors, Cryogenic Equipment Technology: Membrane Separation, Amine Gas Treatment, Adsorption, Fractionation End User: Oil & Gas Industry, Power Generation, Petrochemical Industry, Industrial Users Application: Processing Plants, Natural Gas Treating, LNG Production, Gas Storage |
| Companies Covered | Air Liquide, Linde PLC, Air Products and Chemicals, Messer SE & Co. KGaA, Nippon Sanso Holdings Corporation, Exxon Mobil Corporation, Shell plc, Chevron Corporation, BP PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Processing Market Emerging Trajectories
Processing technology is pivoting toward modular, electrification-compatible architectures that reduce onsite emissions while accommodating variable feedstock compositions from unconventional reservoirs.
Small-scale liquefaction trains with nitrogen rejection and helium recovery circuits are integrating into Permian Basin gathering systems, enabling stranded gas monetization without pipeline access. Midstream operators deploy these units as mobile assets, relocating them between declining well pads. The technology is integrating field-level processing economics with downstream LNG offtake contracts, compressing the traditional boundary between production and midstream functions.
The EU F-Gas Regulation phase-down schedule restricts hydrofluorocarbon refrigerants in cryogenic cooling circuits, forcing adoption of ammonia and mixed-refrigerant alternatives. European engineering contractors redesign liquefaction cycles to accommodate lower-global-warming-potential working fluids. This regulatory pressure most affects floating LNG platform specifications, where space constraints complicate alternative refrigeration system packaging.
Petrochemical buyers now specify certified low-methane-intensity natural gas in procurement tenders, displacing undifferentiated commodity supply. This certification-driven preference shift requires processors to implement continuous emissions monitoring and third-party verification protocols. The phenomenon is most visible in Gulf Coast ethylene cracker supply agreements, where feedstock provenance now influences contract pricing structures.
Gas Processing Market Segmentation
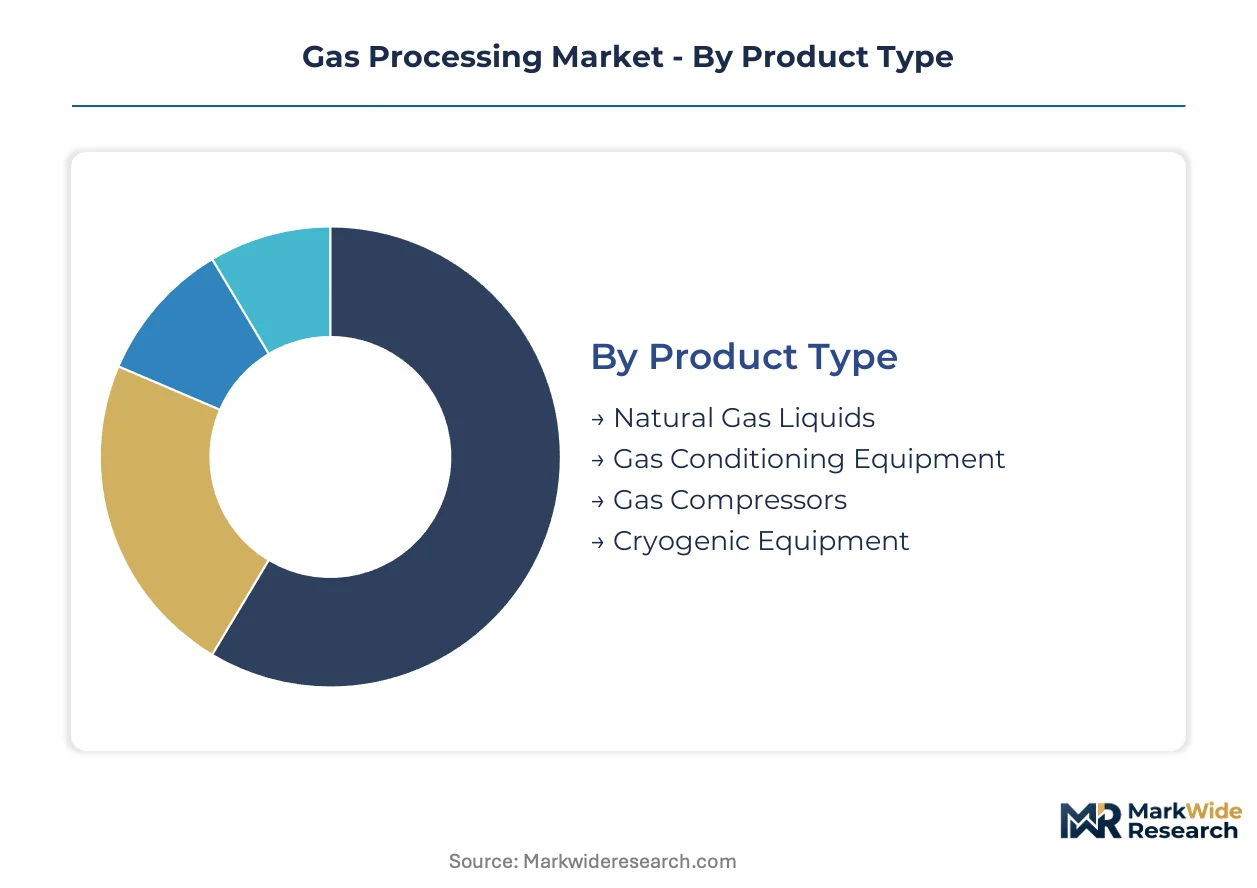
Gas processing infrastructure exhibits divergent engineering specifications across product types, with cryogenic systems demanding precision manufacturing while conditioning equipment tolerates broader fabrication standards. Technology selection follows feedstock composition and scale economics, creating tiered procurement patterns. End-user concentration in integrated oil majors versus fragmented industrial buyers shapes contract structures and service intensity.
Product Type:
Customization intensity spans from standardized compressor skids to engineered-to-order cryogenic trains, with specification variance driving order-to-delivery cycles from weeks to years.
- Natural Gas Liquids:Ethane, propane, butane, and heavier hydrocarbon fractions recovered through cryogenic separation or absorption processes. Demand clusters around Gulf Coast petrochemical corridors where ethane feedstock contracts anchor cracker economics. Margin premiums justify capital-intensive fractionation investments despite volatile commodity spreads.
- Gas Conditioning Equipment:Dehydration units, filter separators, and heating systems that prepare raw gas for pipeline transport. Standardized package designs dominate this tier, enabling rapid deployment across Permian Basin gathering networks. Procurement concentrates with midstream operators seeking modular, relocatable assets.
- Gas Compressors:Centrifugal and reciprocating units for pressure maintenance and gas lift operations. Pipeline operators favor API 618 specification machines for station reliability.
- Cryogenic Equipment:Heat exchangers, cold boxes, and refrigeration circuits operating below minus 150 degrees Celsius. LNG liquefaction projects specify aluminum brazed exchangers from qualified fabricators.
Leading the category by volume: Gas Conditioning Equipment. Growing fastest: Cryogenic Equipment.
Technology:
Technology adoption correlates with facility scale and sulfur loading, with amine systems dominating high-volume sweetening while membranes capture niche remote applications.
- Membrane Separation:Polymeric or ceramic barriers that selectively permeate acid gases and water vapor from methane streams. Offshore platforms and stranded field developments favor skid-mounted membrane packages for minimal footprint and unmanned operation. CO2 permeability limitations restrict application to moderate acid gas concentrations.
- Amine Gas Treatment:Alkanolamine absorption processes for bulk CO2 and H2S removal from sour gas streams. Qatar's North Field expansion and Saudi Aramco's Master Gas System anchor global demand for high-capacity amine units. Proven reliability at million-cubic-meter-per-day scale sustains technology dominance despite energy-intensive regeneration requirements.
- Adsorption:Solid desiccant and molecular sieve systems for deep dehydration and trace contaminant removal. Molecular sieves achieve seven pounds per million cubic feet water content specifications.
- Fractionation:Distillation-based separation of natural gas liquids into purity product streams. Demethanizer and deethanizer column configurations vary by NGL composition.
Amine Gas Treatment commands the largest installed base. Membrane Separation expands most quickly in offshore applications.
End User:
Customer concentration ranges from vertically integrated supermajors with captive engineering capability to price-sensitive industrial buyers procuring through distributors.
- Oil & Gas Industry:Upstream producers and midstream operators requiring field gathering, processing, and transportation infrastructure. Integrated majors leverage in-house technical specifications that exceed industry standards, creating qualification barriers for equipment vendors. Permian Basin independents prioritize rapid deployment over customization.
- Petrochemical Industry:Ethylene crackers and derivative plants purchasing specification-grade ethane and propane feedstock. Gulf Coast crackers now require certified low-methane-intensity supply, forcing processors to implement emissions monitoring and third-party verification protocols. Feedstock provenance clauses increasingly influence contract pricing.
- Power Generation:Gas turbine operators requiring conditioned fuel gas meeting NOx emission and combustion stability specifications. Combined cycle plants specify Wobbe index consistency.
- Industrial Users:Fertilizer, steel, and manufacturing facilities consuming natural gas as process fuel or feedstock. Price sensitivity drives spot market procurement.
Petrochemical Industry leads procurement value. Power Generation shows steepest specification tightening.
Application:
Application scale determines automation architecture, with processing plants requiring distributed control systems while storage facilities operate through simpler programmable logic controllers.
- Processing Plants:Centralized facilities integrating acid gas removal, dehydration, NGL recovery, and fractionation in sequential unit operations. Qatar's Ras Laffan Industrial City and Saudi Arabia's Shedgum Gas Plant represent benchmark installations. Engineering-procurement-construction contractors bundle technology packages for lump-sum turnkey delivery.
- LNG Production:Liquefaction trains with nitrogen rejection, helium recovery, and storage loading systems. Floating LNG platforms reduce onshore footprint constraints for remote gas discoveries. Shell's Prelude and Petronas' PFLNG Dua demonstrate commercial viability of offshore liquefaction.
- Natural Gas Treating:Field-level conditioning to pipeline tariff specifications. Treating intensity varies by reservoir geology.
- Gas Storage:Underground salt cavern and depleted reservoir facilities for seasonal demand balancing. Injection-withdrawal cycling stresses dehydration equipment.
Processing Plants dominate capital deployment. LNG Production gains share fastest in frontier basins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors North American gas processing investment, while Qatar's North Field and Saudi Arabia's Master Gas System concentrate Middle Eastern capacity expansion.
United States
Permian Basin shale output drives small-scale liquefaction deployment for stranded gas monetization. EPA methane rules under 40 CFR Part 60 Subpart OOOOa mandate pneumatic controller replacement across Texas and New Mexico facilities. Gulf Coast petrochemical corridors in Texas and Louisiana anchor ethane fractionation demand.
Qatar
North Field expansion phases sustain global demand for high-capacity amine treatment systems. QatarEnergy's integrated LNG megaprojects enforce specification standards that shape vendor qualification. Ras Laffan Industrial City clusters engineering-procurement-construction contractors for lump-sum turnkey delivery.
Saudi Arabia
Master Gas System upgrades and new sour gas developments concentrate processing demand. SFDA and SASO technical regulations govern equipment import and safety certification. Shedgum and Uthmaniyah gas plants anchor domestic treatment capacity.
Germany
EU F-Gas Regulation phase-down forces ammonia and mixed-refrigerant adoption in cryogenic cooling circuits. ECHA REACH compliance shapes chemical supply chains for amine solutions. Engineering contractors in North Rhine-Westphalia redesign liquefaction cycles for lower-global-warming-potential working fluids.
China
Shale gas development in Sichuan Basin expands domestic processing infrastructure. MIIT and MEE emissions standards tighten methane monitoring requirements. Yangtze River Delta engineering hubs manufacture modular cryogenic equipment for domestic and export markets.
Gas Processing Market Vendor Landscape
Global majors compete with regional champions across technology licensing and equipment fabrication. The vendor base spans consolidated industrial gas specialists, integrated oil majors with captive engineering capability, and fragmented regional fabricators. Three archetypes dominate: cryogenic technology licensors, amine system packagers, and modular skid-mounted equipment suppliers. Capacity expansion and strategic technology partnerships constitute the primary competitive moves.
Within the industrial gas tier, Linde PLC and Air Liquide occupy positions as cryogenic technology anchors. Exxon Mobil Corporation and Shell plc exemplify integrated oil major participation through captive processing infrastructure and floating LNG platform development. Air Products and Chemicals represents the specialist fabricator archetype with modular system capabilities.
| Leading Market Players |
|---|
| Air Liquide |
| Linde PLC |
| Air Products and Chemicals |
| Messer SE & Co. KGaA |
| Nippon Sanso Holdings Corporation |
| Exxon Mobil Corporation |
| Shell plc |
| Chevron Corporation |
| BP PLC |
| Others |
Supply Flow & Price Mechanics
Integrated oil majors and Gulf Coast petrochemical buyers concentrate procurement around long-term offtake agreements, anchoring contract-based pricing with embedded service bundles for maintenance and spare parts inventory. This buyer archetype's volume scale and captive engineering capability compress spot market liquidity and elevate importance of technical specification compliance over transactional price competition.
Pricing Analysis
Extended warranty coverage and predictive maintenance subscriptions are unbundled from base equipment sales, creating separate revenue streams for cryogenic train vendors. Three-tier pricing structure across premium, standard, and economy levels separates API-certified amine systems from modular membrane packages and refurbished compressor skids. Cost compression in standard-tier conditioning equipment is intensifying because midstream operators prioritize rapid deployment over customization. Industrial gas users exhibit highest price sensitivity due to spot market procurement patterns, while LNG project developers accept premium tiers for qualified vendor status.
Supply Chain Analysis
Freight costs for oversized cryogenic cold boxes and aluminum brazed heat exchangers absorb disproportionate project economics, favoring regional fabrication hubs over centralized manufacturing. Supply concentrates in Germany, China, and the United States for precision cryogenic equipment, while amine solution production clusters with specialty chemical producers in Belgium and South Korea. Raw material dependencies span nickel alloys for low-temperature service, specialty steels for high-pressure vessels, and alkanolamine formulations for acid gas removal. Single-source vulnerability persists for ISO 13628-7 qualified subsea treatment systems. Distribution runs through engineering-procurement-construction contractors bundling lump-sum turnkey packages for Middle Eastern megaprojects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating into a vertical-integration race as players pursue captive control over cryogenic liquefaction cycles and proprietary amine formulations to defend margin erosion from commoditized conditioning equipment.
For Market Incumbents: Acquire membrane technology specialists to anchor modular product portfolios for offshore and stranded field applications. Lock in long-term alkanolamine supply agreements with BASF or Dow to mitigate input cost volatility from specialty chemical producers. Electrification substitution threatens capital allocation to gas processing infrastructure; backward integration into carbon capture retrofit capabilities creates defensive revenue streams at existing dehydration facilities. For New Entrants and Emerging Players: Engineering-procurement-construction contractors in Southeast Asia represent underexploited channel partners for skid-mounted treatment packages targeting Indonesia and Vietnam gas developments. White-space concentration sits with small-scale liquefaction trains for Permian Basin stranded gas monetization, where mobility and rapid redeployment outweigh absolute efficiency metrics. Partner with nitrogen rejection unit specialists to bundle helium recovery circuits as differentiated value proposition. For Investors and Strategic Acquirers: The window for entry favors hydrogen-ready plant design specialists ahead of fuel-transition inflection. Long-term viability hinges on operators configuring greenfield infrastructure for methanol synthesis feedstock and hydrogen blending compatibility. Watch EPA methane enforcement intensity as signal for equipment replacement cycle acceleration across North American facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Deployment | Post-combustion amine scrubbing at existing dehydration facilities creates upgrade revenue streams under EPA methane rules. |
| Hydrogen-Ready Plant Configuration | Greenfield infrastructure designed for methanol synthesis feedstock prepares operators for fuel-transition scenarios. |
| Membrane Technology Acquisition | Polymeric membrane systems enable modular, unmanned operation for offshore platforms and remote field developments. |
| Long-Term Amine Supply Agreement | Backward integration into alkanolamine supply chains mitigates input cost volatility from specialty chemical producers. |
| Small-Scale Liquefaction Deployment | Mobile nitrogen rejection units monetize stranded Permian Basin gas without pipeline access, compressing production-midstream boundaries. |
Methodological Framework
Document review covered EIA production data, FERC facility filings, and EPA regulatory dockets, complemented by interviews with gas processing plant managers, EPC contractor procurement leads, cryogenic equipment technical directors, and petrochemical feedstock buyers. Secondary validation drew from SEC 10-K disclosures of integrated oil majors, ISO certification registries, and customs trade records for liquefaction train imports. Bottom-up capacity aggregation across named facilities was cross-referenced against top-down demand estimates from Gulf Coast cracker expansions and LNG export terminal commitments.
Historical capacity deployment patterns were cross-referenced against expert panel assessments of project sanctioning timelines across the analysis window. Segmentation modeling captured product type tiers, technology adoption curves, end-user concentration patterns, and application scale distributions. CAGRs were derived from facility-level investment tracking and announced project pipelines. Industry-specific forecast inputs incorporated EPA methane rule compliance schedules and QatarEnergy megaproject phasing.
Caveats apply where regulatory enforcement intensity, feedstock composition shifts from unconventional reservoirs, or electrification substitution rates could materially shift the outlook. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Argon Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Argon Gas Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Syngas Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Welding Gas Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Food-Grade Gases Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Global Helium Gas Market