
 Gas Sampling Line Market | 2026-2036
Gas Sampling Line Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Sampling Line Market Insights
Environmental monitoring is broadening its share of gas sampling line procurement as industrial operators face stricter emission accountability. Medline Industries leverages its hospital supply chain density to compete in clinical gas sampling applications. Smiths Medical anchors its position through R&D intensity in respiratory care interfaces. Salter Labs specializes in disposable configurations that reduce cross-contamination risk in high-turnover settings.
Gas sampling lines are tubular assemblies—typically constructed from PTFE, stainless steel, or borosilicate glass—engineered to transport representative gas specimens from collection points to analytical instruments without adsorption, permeation, or chemical alteration. Standard operating pressures range from vacuum to 150 psi, with temperature tolerances dictating material selection for stack monitoring or process control. Plastic and composite configurations command the fastest growth due to their flexibility in portable deployment and reduced weight for field technicians. Fixed installations retain the largest value pool, particularly in chemical processing plants where permanent infrastructure justifies higher-grade metal construction. Real-time analysis technology is displacing passive sampling in environmental compliance applications, creating margin concentration among suppliers integrating sensor-ready connectivity.
EPA emission standards and EU Green Deal monitoring protocols shape product specifications, with REACH compliance governing material composition for European deployments. The FDA regulates clinical gas sampling lines as Class II medical devices, requiring biocompatibility validation for patient-connected applications. OSHA process safety mandates in the US and MEE dual carbon enforcement in China are expanding the addressable base for industrial-grade sampling infrastructure. Stakeholders must weigh material certification costs against the premium commanded in regulated end-use verticals.
Market Dynamics
Real-time emission tracking technology is compressing replacement cycles across industrial and environmental monitoring installations, forcing suppliers to integrate sensor-ready connectivity into legacy sampling infrastructure.
Growth Catalysts
- EU Green Deal compliance timelines:German industrial clusters face accelerated stack monitoring upgrades as 2030 carbon neutrality milestones approach. Fixed installations in chemical processing plants drive premium-grade metal construction demand.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment mandates expanded industrial-grade sampling infrastructure at steel and cement facilities. This creates new procurement volume for high-temperature tolerant assemblies.
- PTFE composite flexibility:Portable deployment configurations gain preference among field technicians conducting fugitive emission surveys. Reduced weight specifications enable single-operator sampling protocols.
Market Restraints
- Fluoropolymer feedstock volatility:PTFE resin prices fluctuate with fluorspar mining output concentrated in China and Mexico. Material certification costs for REACH compliance add 15-25% to European-bound product landed costs.
- Stainless steel supply concentration:Specialty 316L tubing for corrosive process control applications sources predominantly from German and Japanese mills. Geopolitical friction threatens just-in-time delivery schedules for North American fabricators.
- Passive sampling displacement:Real-time analyzer integration renders grab-sampling manifold architectures obsolete. Existing installed base amortization slows upgrade decisions at budget-constrained municipal air quality stations.
Strategic Opportunities
- India's PLI scheme for environmental equipment:Domestic manufacturing incentives attract sampling line assembly operations serving South Asian petrochemical corridors. Local content requirements favor joint ventures with established tubing extruders.
- Hydrogen economy infrastructure:Purity verification protocols for fuel cell supply chains require ultra-clean sampling pathways free from metallic contamination. Borosilicate glass and specialized polymer configurations address embrittlement risks.
- Digital twin convergence:Sensor-embedded sampling lines feeding predictive maintenance algorithms differentiate premium offerings. System integrators bundle hardware with cloud-based leak detection subscriptions.
Industry Challenges
- Welding certification bottlenecks:ASME Section IX qualified technicians for orbital welding of high-purity process lines command premium wages. Training pipeline deficits constrain capacity expansion at fabrication shops.
- Legacy analyzer protocol fragmentation:Fieldbus compatibility layers for 4-20mA, HART, and emerging IO-Link standards multiply engineering validation cycles. Retrofit projects stall on integration uncertainty.
- Biocompatibility validation timelines:FDA 510(k) clearance for patient-connected respiratory sampling interfaces extends 18-24 months. Clinical market entrants face working capital strain during regulatory dormancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Sampling Line Market |
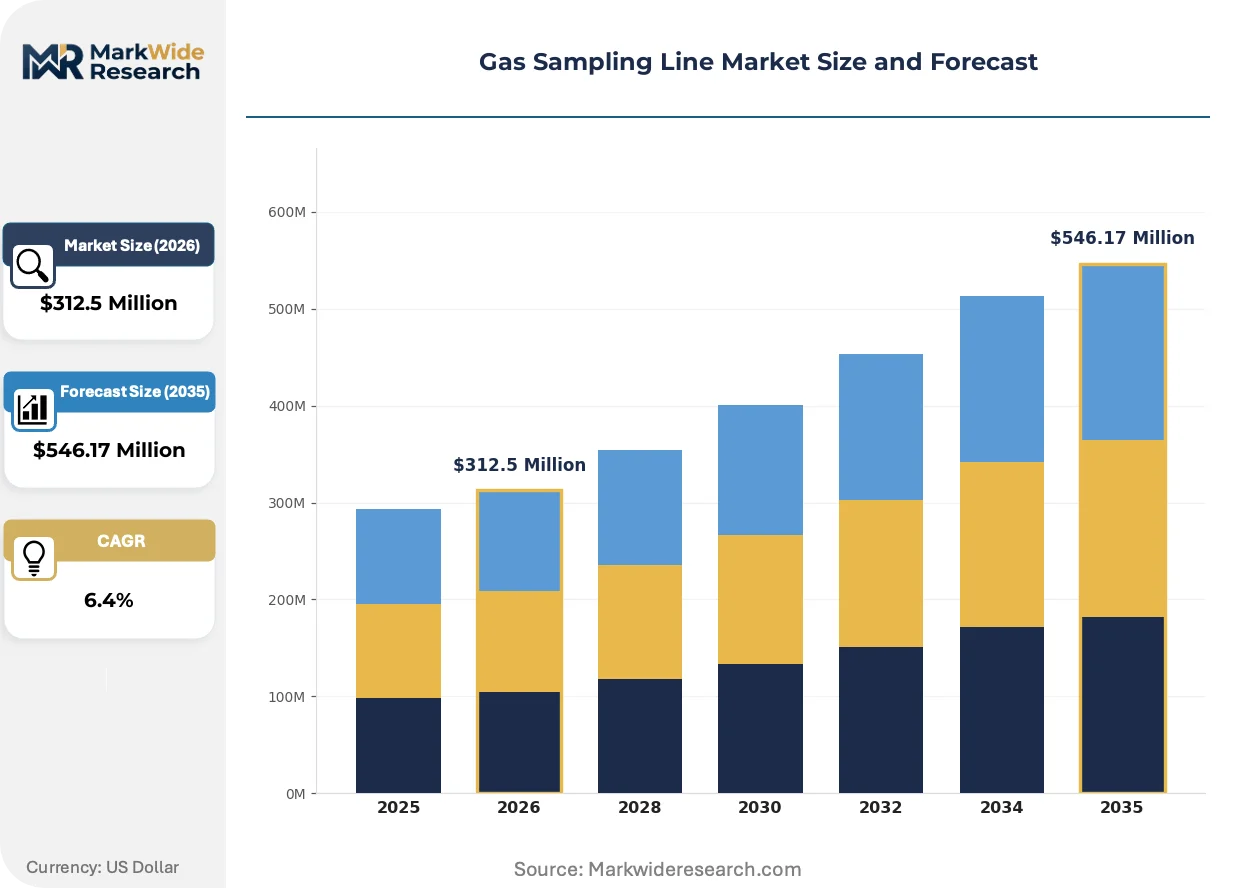
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Plastic, Composite, Glass End User: Oil & Gas, Environmental Monitoring, Chemical Processing, Water Treatment Installation: Fixed, Portable, Semi-Permanent, Temporary Technology: Vacuum Extraction, Pressure Sampling, Passive Sampling, Real-Time Analysis |
| Companies Covered | R-Vent Medikal, Sharn Anesthesia Inc., Medline Industries, Smiths Medical, Truer Medical, Salter Labs, Runmai Medical, Teleflex, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Sampling Line Market Trends and Innovations
Connected diagnostics and material science advances are redefining performance benchmarks across environmental compliance, process control, and clinical gas handling applications.
MEMS-based microfluidic sampling modules are automating continuous emission monitoring at distributed industrial sites. Power plant operators and refinery maintenance teams deploy these compact assemblies for perimeter fence-line monitoring. The technology is automating technician dispatch decisions by flagging threshold excursions before manual inspection rounds.
REACH Article 33 disclosure requirements for SVHC content above 0.1% w/w are forcing material composition transparency across European supply chains. Tubing vendors must document fluoropolymer additive packages and metal alloy trace elements. Environmental monitoring agencies in Germany, the Netherlands, and Belgium now specify full material declarations in tender documentation.
Hospital supply chains are consolidating anesthesia gas sampling procurement under group purchasing organization frameworks. Medline Industries and similar distributors bundle disposable lines with broader respiratory consumables contracts. This concentration is squeezing standalone specialty manufacturers in the US acute care segment.
Gas Sampling Line Market Segmentation
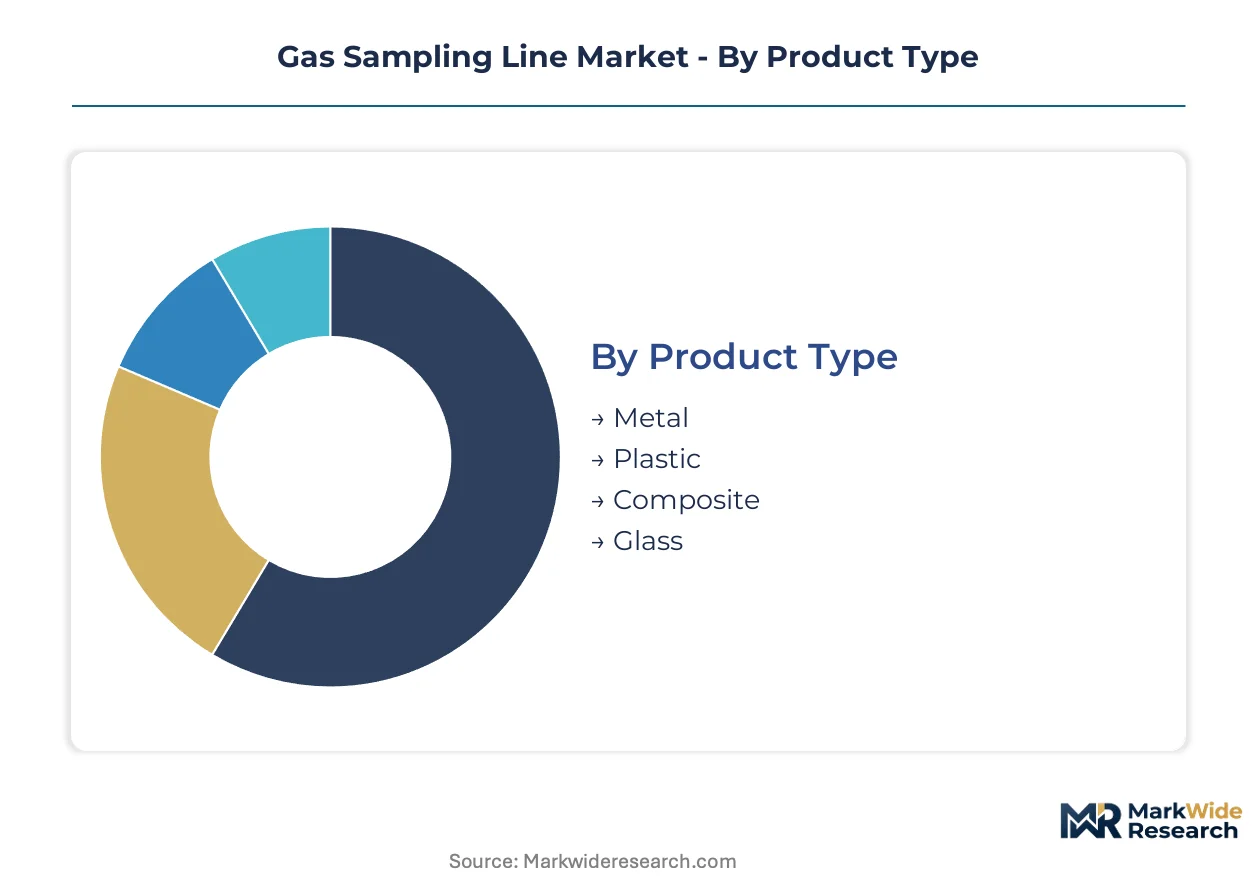
Gas sampling line procurement patterns diverge sharply across material specifications, installation permanence, and analytical technology. Segment boundaries reflect competing pressures between regulatory compliance mandates and operational cost optimization in field deployment.
Product Type:
Material selection hinges on chemical inertness requirements, thermal tolerance, and weight constraints for technician mobility.
- Metal:Stainless steel and specialty alloys dominate corrosive process control environments. Fixed installations in German chemical clusters specify 316L tubing for REACH-compliant longevity under acidic stack conditions.
- Plastic:PTFE and fluoropolymer configurations enable single-operator portable protocols. Reduced weight specifications accelerate uptake in China's MEE-mandated fugitive emission surveys at steel facilities.
- Composite:Hybrid polymer-metal assemblies balance flexibility with pressure rating for semi-permanent industrial monitoring.
- Glass:Borosilicate pathways serve ultra-purity verification for hydrogen fuel cell supply chains, eliminating metallic embrittlement risks.
Mature deployment sits with Metal. Newer deployment is concentrated in Plastic.
End User:
Regulatory enforcement intensity varies dramatically across verticals, shaping specification stringency and replacement cadence.
- Oil & Gas:Upstream flare monitoring and downstream refinery perimeter surveillance require explosion-rated assemblies. EPA consent decree timelines compress upgrade cycles at US Gulf Coast facilities.
- Environmental Monitoring:Air quality agencies deploy distributed sensor networks. EU Green Deal 2030 milestones accelerate stack monitoring procurement in Belgium and the Netherlands.
- Chemical Processing:Process analytical technology integration demands sensor-ready connectivity for predictive maintenance algorithms.
- Water Treatment:Biogas capture and digester gas analysis specifications lag industrial counterparts in connectivity adoption.
Volume concentration rests with Oil & Gas. Margin expansion is strongest in Environmental Monitoring.
Installation:
Capital commitment horizons and mobility requirements partition procurement between infrastructure-grade and field-configurable solutions.
- Fixed:Permanent manifold architectures justify premium-grade construction in chemical processing plants. German industrial clusters anchor demand for orbital-welded high-purity lines.
- Portable:Battery-powered analyzer compatibility drives lightweight specification. Field technicians conducting MEE enforcement rounds in China favor single-operator deployment kits.
- Semi-Permanent:Seasonal construction site monitoring and turnaround inspection cycles favor rapid deployment without permanent infrastructure commitment.
- Temporary:Emergency response and accident investigation protocols specify disposable configurations to eliminate cross-contamination protocols between sites.
Value capture concentrates in Fixed. Volume growth is climbing fastest in Portable.
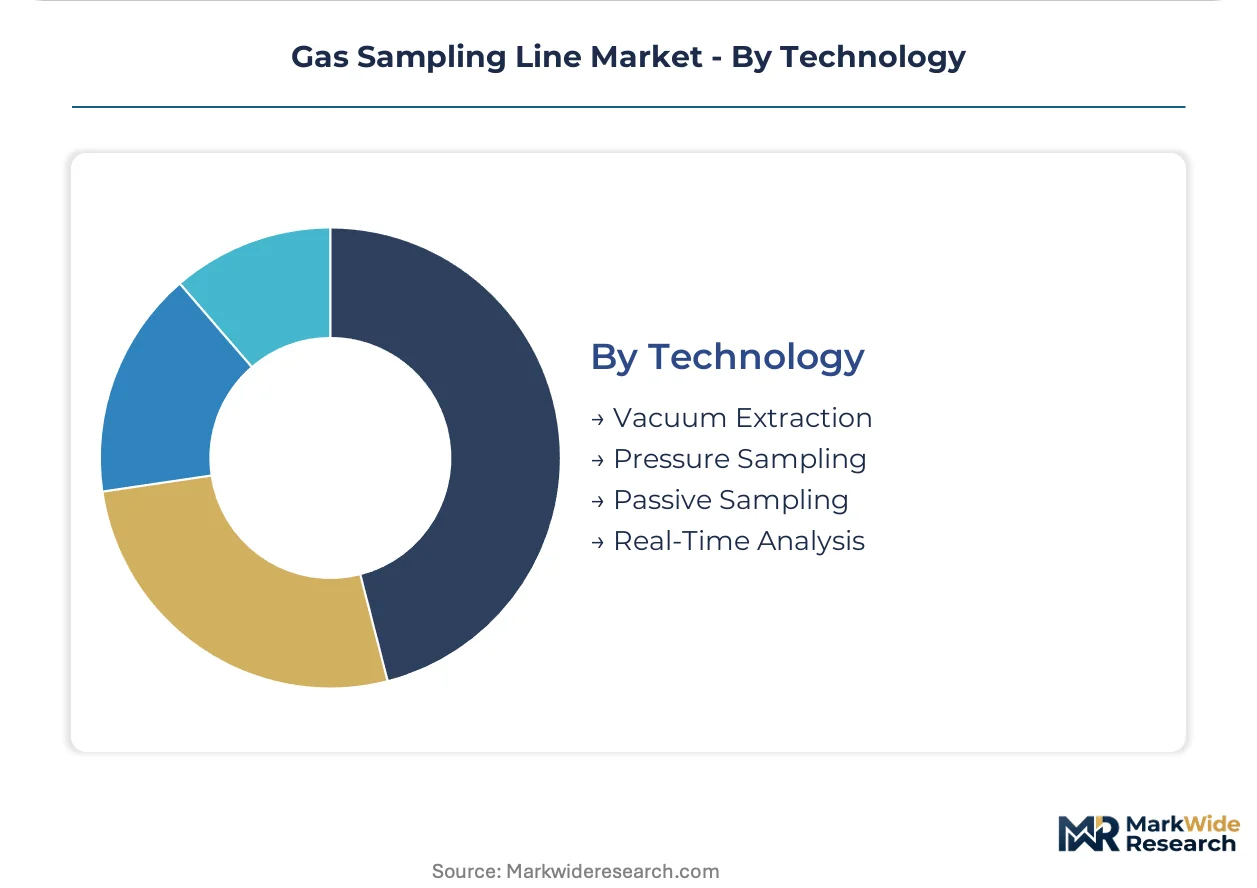
Technology:
Analytical methodology selection determines sampling line architecture, from passive grab-sample manifolds to continuous sensor integration.
- Vacuum Extraction:Negative pressure systems transport reactive specimens without compressor contamination. Soil vapor intrusion assessments in US EPA brownfield remediation specify evacuated canister compatibility.
- Pressure Sampling:Positive pressure configurations dominate stack monitoring where particulate loading requires inline filtration. German TÜV certification mandates specify burst pressure ratings for pressurized process connections.
- Passive Sampling:Diffusion-based grab sampling retains cost advantage at budget-constrained municipal stations. Displacement by real-time alternatives constrains replacement revenue.
- Real-Time Analysis:MEMS microfluidic modules automate continuous emission monitoring. Power plant operators in India deploy perimeter fence-line arrays under tightening CPCB enforcement.
Installed base amortization slows Passive Sampling upgrades. Steepest expansion trajectory belongs to Real-Time Analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and Germany's Ruhr industrial corridor concentrate gas sampling line procurement as environmental enforcement tightens. Tax incentives for clean technology manufacturing accelerate supplier localization in these corridors. Regional demand patterns diverge sharply between mature regulatory environments and emerging enforcement regimes.
United States
EPA consent decree timelines compress upgrade cycles at Gulf Coast petrochemical complexes. OSHA process safety mandates expand the addressable base for industrial-grade sampling infrastructure. Houston's Energy Corridor anchors demand for explosion-rated assemblies serving upstream flare monitoring applications.
Germany
EU Green Deal 2030 carbon neutrality milestones accelerate stack monitoring procurement in the Ruhr industrial cluster. REACH Article 33 disclosure requirements force material composition transparency across tubing supply chains. BASF's Ludwigshafen complex drives specification for orbital-welded high-purity process lines.
China
MEE dual carbon enforcement mandates expanded sampling infrastructure at steel and cement facilities in Hebei Province. GB standards for continuous emission monitoring tighten specification requirements. The Yangtze River Delta special economic zone attracts domestic assembly operations serving South Asian petrochemical corridors.
India
PLI scheme incentives for environmental equipment attract sampling line assembly operations to Gujarat's petrochemical belt. CPCB enforcement tightening drives perimeter fence-line monitoring deployment at power plants. Reliance Industries' Jamnagar complex anchors demand for high-temperature tolerant assemblies.
Netherlands
EU Green Deal compliance timelines accelerate replacement cycles at Rotterdam's port industrial cluster. TÜV certification mandates specify burst pressure ratings for pressurized process connections. The Amsterdam-Rijnmond chemical corridor concentrates procurement for sensor-ready connectivity integration.
Gas Sampling Line Market Competitive Landscape
Top-tier vendors anchor premium-grade fixed installations, while mid-tier fabricators compete on portable deployment configurations. The vendor base stratifies across medical device specialists, industrial process suppliers, and diversified hospital supply distributors. Three archetypes dominate: clinical consumables bundlers, respiratory care R&D-intensive specialists, and disposable configuration pure-plays. Consolidation pressure intensifies through group purchasing organization contract concentration and vertical integration into fluoropolymer extrusion capacity.
Among clinical gas sampling specialists, Medline Industries, Smiths Medical, and Salter Labs represent distinct competitive positions. Medline Industries leverages hospital supply chain density to compete in clinical applications. Smiths Medical anchors its market presence through R&D intensity in respiratory care interfaces. Salter Labs exemplifies the disposable configuration archetype that reduces cross-contamination risk in high-turnover settings.
| Leading Market Players |
|---|
| R-Vent Medikal |
| Sharn Anesthesia Inc. |
| Medline Industries |
| Smiths Medical |
| Truer Medical |
| Salter Labs |
| Runmai Medical |
| Teleflex |
| ICU Medical |
| Others |
Pricing and Supply Chain Analysis
ASME Section IX qualified orbital welders in the US Gulf Coast and German Ruhr corridor command premium wages that widen spreads between certified premium-grade lines and uncertified economy alternatives. Labor-cost differentials between these specialized fabrication hubs and emerging assembly operations in India and China feed directly into three-tier pricing structures across the industry.
Pricing Analysis
Short lead-time premiums of 20-35% apply to sensor-ready configurations for EU Green Deal compliance deadlines, while spot inventory of standard PTFE tubing trades at discounts. The dominant pricing structure is contract-based long-term offtake with volume tiers. Price differentiation rests on REACH certification grade and orbital welding qualification. Cost compression in economy-grade plastic configurations is intensifying because of fluoropolymer feedstock volatility. Municipal environmental agencies exhibit highest price sensitivity; hydrogen fuel cell suppliers show least sensitivity due to purity-critical specifications.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns serving field technician deployment networks. Manufacturing concentrates in Germany, China, and the United States. Raw material dependencies include fluorspar-derived PTFE resin, 316L stainless steel from Japanese and German mills, and borosilicate glass tubing. Single-source vulnerability threatens specialty alloy supply from concentrated mill bases. Distribution runs through industrial gas equipment distributors and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas sampling line market sits in a technology-transition phase as MEMS-based microfluidic modules displace passive grab-sampling architectures across environmental compliance applications.
For Market Incumbents: Anchor market position through backward integration into fluoropolymer extrusion capacity and captive supply of 316L tubing. Sensor-ready connectivity integration represents the priority R&D lever against modular microfluidic substitutes. Certification investment in REACH Article 33 documentation capabilities defends premium positioning as EU tender requirements tighten. For New Entrants and Emerging Players: Portable deployment kits for China's MEE enforcement rounds offer the most penetrable entry point given specification standardization and volume procurement. Hydrogen fuel cell purity verification protocols present a second white-space target with limited incumbent specialization. A direct-to-plant technical sales model bypasses established distributor relationships in industrial clusters. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier fabricators possessing ASME welding certification and sensor integration capabilities given real-time analyzer convergence. The 5-10 year viability window favors suppliers with dual clinical-industrial certification breadth. Watch for CPCB enforcement intensity in India as the inflection signal for South Asian capacity deployment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Ready Connectivity Integration | MEMS microfluidic compatibility differentiates premium offerings for EU Green Deal stack monitoring upgrades. |
| Backward Integration into Fluoropolymer Extrusion | Captive PTFE supply hedges against Chinese fluorspar price volatility and REACH certification delays. |
| ASME Section IX Welding Certification Investment | Qualified orbital welder pipelines constrain capacity expansion at German and US fabrication shops. |
| Hydrogen Purity Verification Product Line | Borosilicate and specialized polymer configurations address metallic embrittlement risks in fuel cell supply chains. |
| Digital Twin Platform Partnership | Cloud-based leak detection subscriptions bundled with hardware create recurring revenue in predictive maintenance. |
Research Methodology
SEC 10-K filings, EPA emission inventory databases, and EU ETS transaction records formed the secondary backbone for market sizing and competitive positioning. Primary interviews with plant engineers at German chemical clusters, procurement managers at US Gulf Coast refineries, and field technicians conducting MEE enforcement rounds in China validated demand assumptions. This study combined bottom-up shipment data from tubing fabricators with top-down spending analysis from environmental monitoring agencies. Triangulation across these sources anchored volume and value estimates.
Bottom-up modeling tracked material-grade shipments across metal, plastic, composite, and glass configurations, while top-down analysis calibrated spending patterns against regulatory enforcement budgets. Segmentation dimensions included installation permanence, analytical technology type, and end-use vertical. CAGRs were derived from regression analysis of replacement cycle compression and real-time analyzer adoption curves. Industry-specific inputs incorporated EU Green Deal milestone timelines and MEE dual carbon enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluoropolymer feedstock disruption and welding certification pipeline constraints. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Asia-Pacific Syngas Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Krypton-85 Market
Industrial Gases
US Specialty Gas Market
Industrial Gases
Argon Gas Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Asia-Pacific Industrial Gases Market
Industrial Gases
North America Syngas Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Helium Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market