
 Germany Commercial Vehicles Lubricants Market | 2026-2036
Germany Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Commercial Vehicles Lubricants Market Foresight
ACEA E6 and E8 heavy-duty specifications are reorganizing procurement priorities across German fleet operators. ExxonMobil Corporation leverages its synthetic base stock technology to anchor premium engine oil positioning for long-haul heavy duty trucks. LIQUI MOLY specializes in additive packages that meet extended drain intervals demanded by logistics operators running tight turnaround schedules. Fuchs controls distribution through direct technical service relationships with municipal bus fleets in North Rhine-Westphalia.
Commercial vehicles lubricants comprise formulated oils and greases engineered with Group II/III base oils and performance additives to reduce friction, dissipate heat, and prevent wear in diesel and natural gas engines operating under severe duty cycles. Viscosity grades such as 5W-30 and 10W-40 dominate current fill practices for German heavy duty trucks, while low-SAPS formulations address exhaust aftertreatment compatibility in Euro VI-compliant engines. Engine oils capture the largest value pool given high consumption rates and specification intensity, whereas hydraulic fluids for construction vehicles represent a faster-growing margin segment as infrastructure contractors modernize equipment fleets. The end user industry dimension reveals logistics operators as the most consolidated buyer group, with public transport companies presenting steadier but lower-volume contract structures.
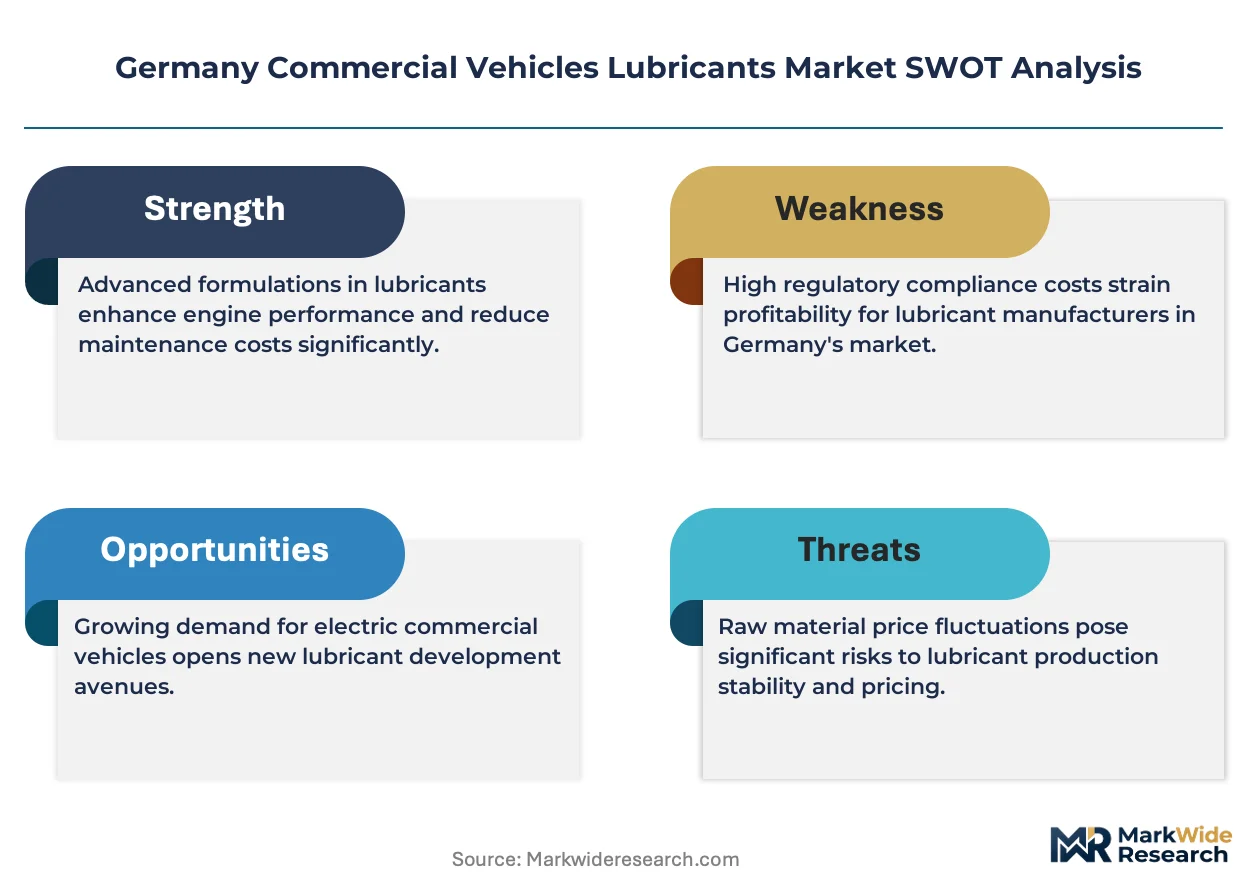
Germany's lubricant market operates under REACH chemical registration requirements, the EU F-Gas Regulation for climate-relevant substances, and KBA vehicle type-approval standards that cascade into lubricant performance claims. REACH compliance costs are filtering smaller blenders from formulations containing novel friction modifiers, while KBA enforcement of OEM fill specifications limits aftermarket substitution for warranty-covered commercial vehicles. Fleet procurement managers and lubricant blenders must monitor the EU Green Deal's evolving carbon border adjustments and bio-based content mandates to anticipate specification shifts before they harden into tender requirements.
Market Dynamics
The EU Green Deal is compressing formulation timelines for German lubricant blenders, forcing simultaneous compliance with tightening emissions targets and extended drain interval demands from logistics fleets operating Hamburg-Munich-Rhine-Ruhr corridors.
Growth Catalysts
- Euro VI engine architecture:Exhaust aftertreatment systems require low-SAPS lubricant chemistries, pulling premium formulation demand from heavy-duty truck operators.
- REACH chemical registration:Compliance barriers filter smaller blenders from novel friction modifier segments, consolidating volume among technically capable suppliers.
- Just-in-time logistics networks:Bavarian and Baden-Württemberg fleet operators prioritize extended drain intervals to minimize vehicle downtime across dense delivery schedules.
Market Restraints
- Group III base oil supply concentration:Dependence on refinery-linked feedstock exposes blenders to crude-linked volatility and limited domestic sourcing alternatives.
- KBA type-approval enforcement:OEM fill specifications lock aftermarket substitution for warranty-covered commercial vehicles, constraining independent service channel expansion.
- Bio-based feedstock cost premiums:Rapeseed and synthetic ester base stocks carry 15-40% cost deltas versus mineral alternatives, compressing margin at price-sensitive municipal fleet tiers.
Strategic Opportunities
- North Rhine-Westphalia municipal bus electrification:Hybrid and battery-electric powertrains create dedicated thermal management fluid categories absent legacy competition.
- EU carbon border adjustment mechanisms:Anticipatory carbon accounting in tender requirements rewards early bio-content certification and lifecycle transparency.
- Direct technical service models:Bypassing traditional distribution layers through on-site oil analysis and drain interval optimization contracts captures fleet relationship depth.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise for ACEA E8 heavy-duty specifications concentrates among retiring specialists, constraining R&D velocity at mid-tier blenders.
- Legacy ERP integration with predictive maintenance platforms:Fleet telematics systems demand real-time lubricant condition data feeds that older inventory management architectures cannot accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Commercial Vehicles Lubricants Market |
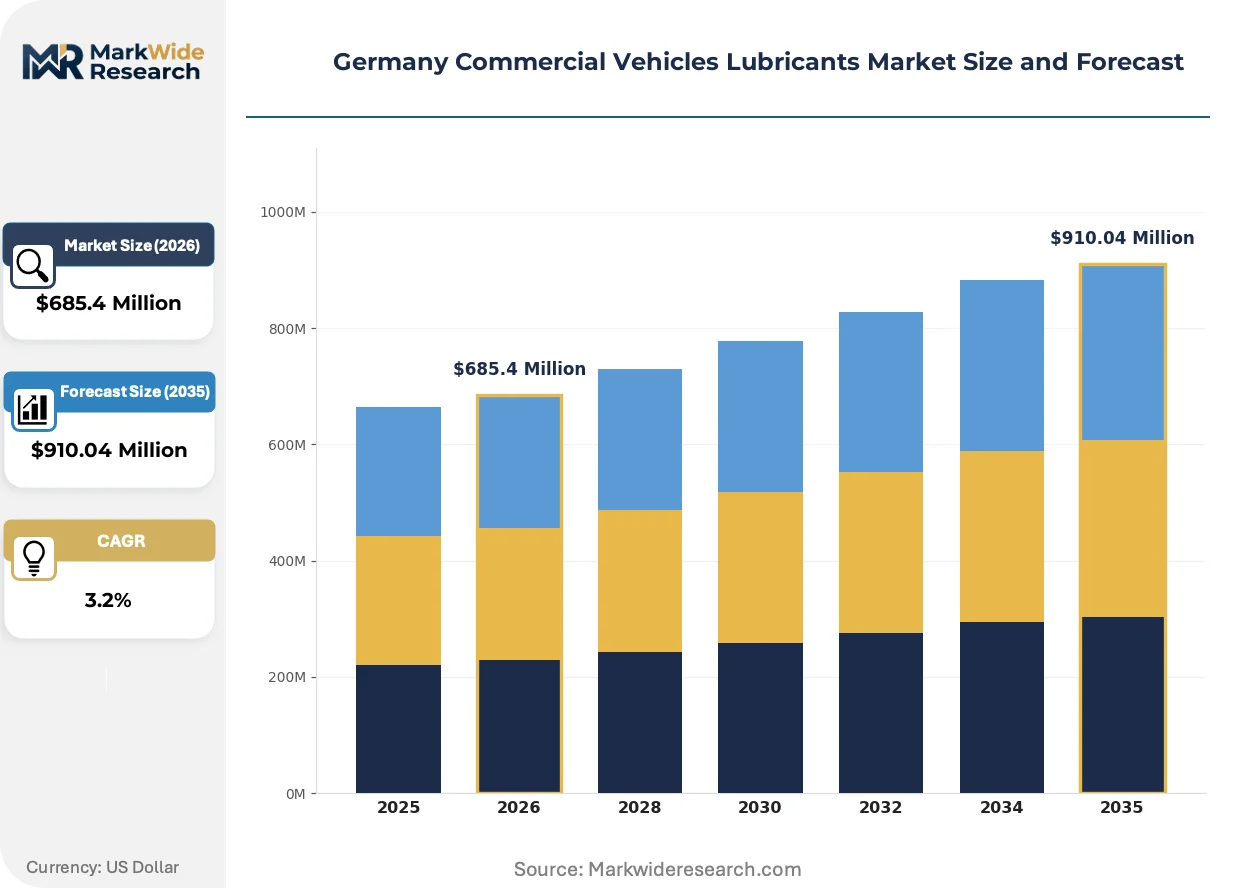
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $910.04 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Gear Oils, Hydraulic Fluids, Greases, Transmission Fluids Vehicle Type: Heavy Duty Trucks, Light Duty Trucks, Buses, Delivery Vans, Construction Vehicles Application: Fuel Efficiency Improvement, Engine Protection, Wear Resistance, Emission Control, Thermal Stability End User Industry: Logistics Operators, Public Transport Companies, Infrastructure Contractors, Agricultural Enterprises |
| Companies Covered | ExxonMobil Corporation, LIQUI MOLY, ADDINOL, ROWE Mineralölwerk GmbH, Ravensberger Schmierstoffvertrieb GmbH, BP PLC (Castrol), Fuchs, Shell, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Commercial Vehicles Lubricants Market Shifts & Advancements
Synthetic base stock technology and additive package architecture are fragmenting competitive positions across German commercial vehicle lubricants, with specification intensity rising faster than volume growth.
Polyalphaolefin (PAO) and gas-to-liquid (GTL) base stocks are fragmenting traditional Group II/III supply hierarchies in heavy-duty engine oils. Logistics operators running Euro VI fleets across Bavaria are adopting 5W-30 full synthetics at accelerated replacement cycles. This technology shift is fragmenting procurement decisions away from single-supplier volume contracts toward specification-tiered sourcing strategies.
REACH authorization requirements for novel friction modifiers are compressing formulation innovation cycles for German blenders. The ECHA evaluation timeline creates 18-36 month lag between laboratory validation and commercial deployment. Heavy-duty truck lubricants face the tightest constraints, as OEM warranty positions harden around pre-approved additive packages.
Fleet procurement departments are unbundling lubricant supply from bundled maintenance contracts. Large logistics operators in the Rhine-Ruhr industrial belt now tender lubricants separately from workshop services, forcing direct price transparency on historical package deals. This pattern concentrates most visibly among operators managing 200+ vehicle fleets with centralized procurement functions.
Germany Commercial Vehicles Lubricants Market Segmentation
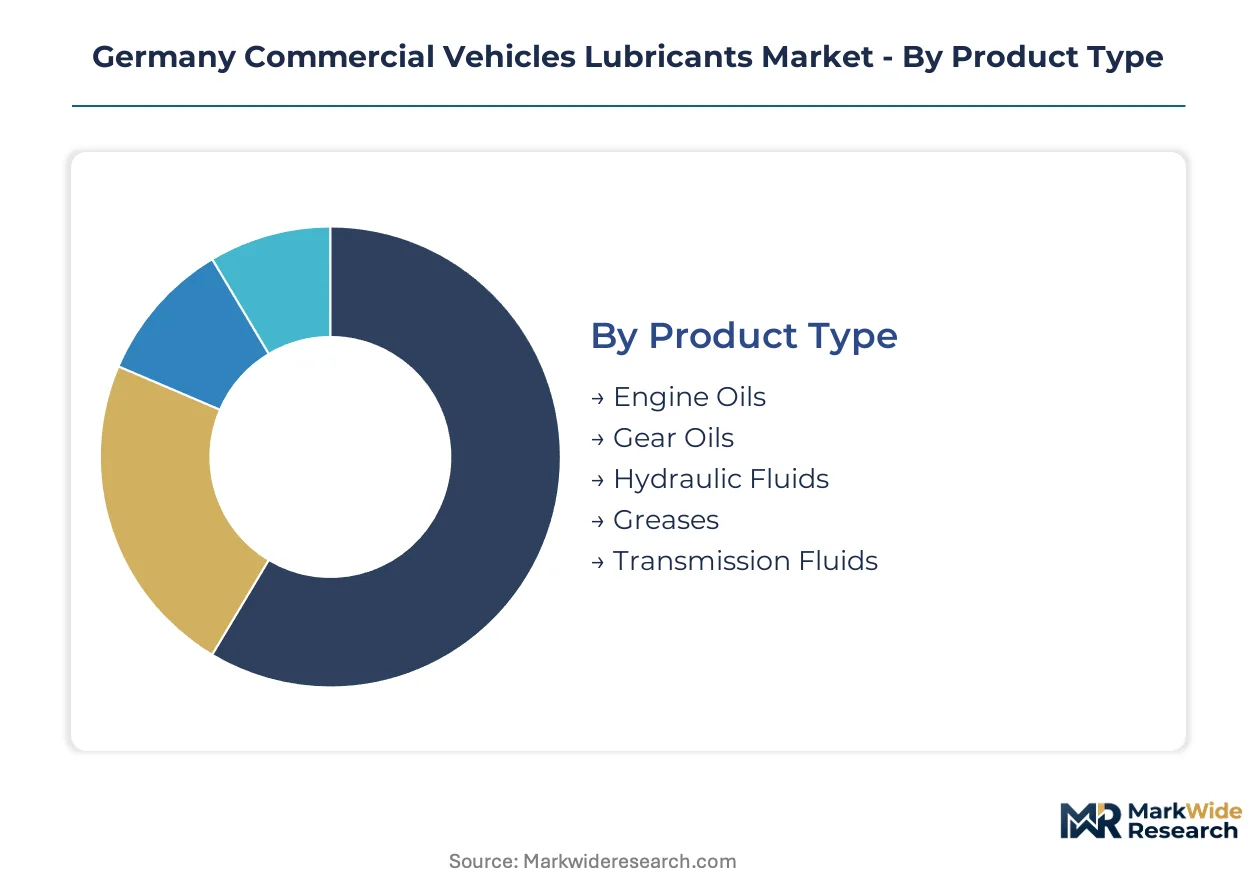
German fleet procurement departments unbundle lubricant specifications across multiple dimensions to match total cost of ownership targets. Segmentation clarity determines whether blenders capture extended drain interval premiums or surrender volume to price competitors.
Product Type:
Engine oils face the strongest substitution pressure from hydraulic fluids as construction equipment electrification redirects thermal management spending.
- Engine Oils:Formulated with Group III base stocks and ACEA E6/E8 additive packages for Euro VI exhaust aftertreatment compatibility. Demand concentrates among Hamburg-Munich-Rhine-Ruhr logistics corridors where low-SAPS formulations protect diesel particulate filters across extended drain intervals.
- Hydraulic Fluids:Anti-wear formulations with zinc dithiophosphate chemistry for high-pressure construction equipment circuits. Infrastructure contractors in North Rhine-Westphalia specify ISO VG 46 grades as excavator fleets modernize, pulling volume from traditional engine oil maintenance budgets.
- Gear Oils:Extreme-pressure lubricants with sulfur-phosphorus additive systems for differential and transmission protection.
- Greases:Lithium complex and calcium sulfonate thickeners for chassis lubrication points and bearing applications.
- Transmission Fluids:Synthetic ATF and manual transmission oils with friction modifier packages for synchronized gearboxes.
Engine oils anchor the volume base while hydraulic fluids gain share at the steepest rate.
Vehicle Type:
Cost tier stratification separates premium synthetic specifications for long-haul assets from mineral-based fills for short-cycle municipal equipment.
- Heavy Duty Trucks:Euro VI-compliant tractors and rigids operating above 16 tonnes gross vehicle weight. Bavarian and Baden-Württemberg logistics operators specify 5W-30 full synthetics to maximize drain intervals across just-in-time delivery networks.
- Construction Vehicles:Excavators, wheel loaders, and articulated dump trucks subject to severe duty cycles. Infrastructure contractors prioritize hydraulic fluid performance over engine oil specifications as equipment utilization rates climb.
- Buses:Urban transit and intercity coaches with compressed natural gas and diesel powertrains.
- Light Duty Trucks:Delivery vehicles between 3.5 and 7.5 tonnes serving regional distribution routes.
- Delivery Vans:Last-mile vehicles below 3.5 tonnes with stop-start operating profiles.
Heavy duty trucks dominate procurement volume while construction vehicles expand most quickly as infrastructure investment accelerates.
Application:
Margin concentration follows performance tier differentiation, with emission control commanding premium formulation pricing.
- Emission Control:Low-SAPS and mid-SAPS chemistries protecting diesel particulate filters and selective catalytic reduction systems. REACH-registered friction modifiers enable compliance without sacrificing wear protection.
- Fuel Efficiency Improvement:Viscosity grade reductions and friction modifier packages reducing parasitic losses. Rhein-Ruhr fleet operators specify 5W-30 over 10W-40 to extract marginal fuel savings across high-mileage corridors.
- Engine Protection:Detergent-dispersant packages maintaining piston cleanliness and bearing corrosion resistance.
- Wear Resistance:Anti-wear additives for camshaft, piston ring, and cylinder liner protection under boundary lubrication conditions.
- Thermal Stability:Oxidation inhibitors extending oil life in high-turbocharger applications.
Emission control specifications capture the steepest margin expansion while engine protection maintains the broadest installed base.
End User Industry:
Customer type determines contract structure, with logistics operators consolidating procurement and public transport favoring municipal tender formats.
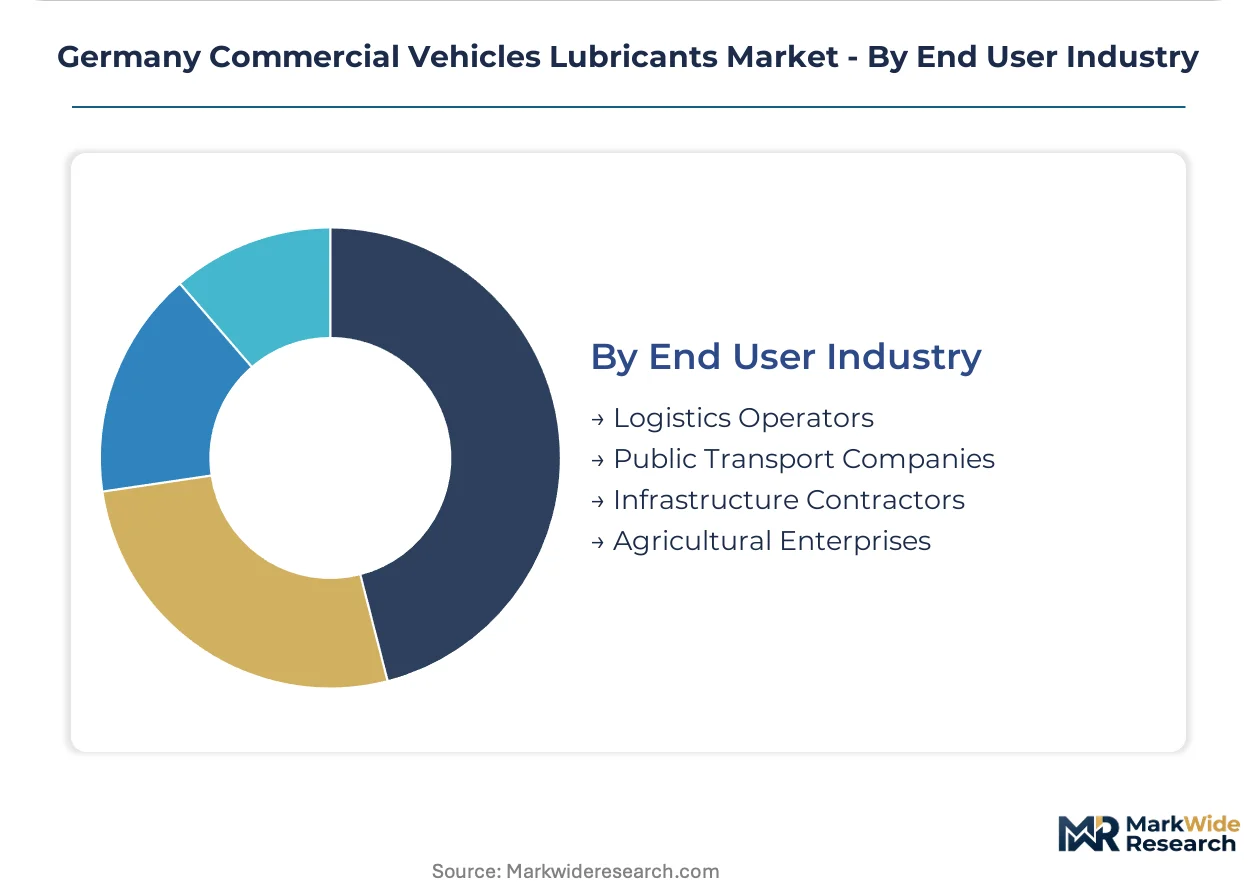
- Logistics Operators:Fleet managers running 200-plus vehicle networks across German long-haul corridors. Centralized procurement functions unbundle lubricant supply from workshop services, demanding direct price transparency and drain interval guarantees.
- Public Transport Companies:Municipal and regional bus operators with stable route profiles and predictable maintenance windows. North Rhine-Westphalia transit authorities favor technical service relationships over transactional supply.
- Infrastructure Contractors:Construction and civil engineering firms with seasonal equipment utilization patterns.
- Agricultural Enterprises:Farm operators with mixed diesel and natural gas equipment fleets.
Logistics operators concentrate the largest contract value while infrastructure contractors present the most volatile demand pattern.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery-linked base oil capacity clusters along the Rhine-Ruhr industrial corridor and Hamburg port complex, concentrating lubricant blending infrastructure within 200 kilometers of Germany's densest logistics networks. This geographic lock-in shapes regional procurement patterns and specification adoption timelines across federal states.
Bavaria
Just-in-time logistics operators across the Munich-Nuremberg corridor specify 5W-30 full synthetics to maximize drain intervals. KBA type-approval standards cascade into fleet procurement tenders, hardening OEM fill specifications for warranty-covered assets. The Augsburg-Ingolstadt manufacturing belt concentrates heavy-duty truck distribution centers where centralized lubricant procurement functions unbundle supply from workshop services.
North Rhine-Westphalia
Municipal bus fleets in Cologne, Düsseldorf, and Dortmund favor technical service relationships over transactional supply contracts. REACH chemical registration requirements filter smaller blenders from novel friction modifier formulations, consolidating volume among technically capable suppliers. The Rhine-Ruhr industrial belt anchors Germany's largest concentration of logistics operators managing 200-plus vehicle networks with dedicated procurement departments.
Baden-Württemberg
Automotive supplier logistics networks around Stuttgart demand extended drain interval guarantees to maintain just-in-time delivery schedules. EU Green Deal emissions targets tighten lubricant formulation standards for heavy-duty trucks serving long-haul corridors into Switzerland and France. The Karlsruhe-Mannheim highway junction serves as a critical refueling and maintenance node where premium synthetic specifications achieve highest penetration rates.
Hamburg
Port logistics operators and intermodal freight terminals drive demand for low-SAPS formulations compatible with Euro VI exhaust aftertreatment systems. The EU F-Gas Regulation for climate-relevant substances shapes thermal management fluid categories for emerging hybrid powertrains. The Hamburg-Berlin freight corridor concentrates Germany's highest-density long-haul trucking activity, pulling premium lubricant specifications northward from traditional industrial centers.
Lower Saxony
Agricultural equipment fleets and food logistics operators in the Hanover-Brunswick region present seasonal demand patterns distinct from long-haul trucking. Bio-based feedstock cost premiums compress margins at price-sensitive municipal fleet tiers, slowing rapeseed and synthetic ester adoption. The Volkswagen commercial vehicle manufacturing presence in Wolfsburg influences regional service network specifications and warranty-linked procurement requirements.
Germany Commercial Vehicles Lubricants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the German market. Integrated energy majors leverage captive base oil supply and global R&D scale, while domestic specialists compete through technical service depth and additive package customization. Three archetypes dominate: multinational integrated suppliers with synthetic base stock technology, regional blenders with direct fleet relationships, and additive-focused formulators serving niche specification tiers. Competitive intensity centers on M&A consolidation of mid-tier blending capacity and strategic partnerships between lubricant suppliers and fleet telematics platforms.
Among integrated energy majors with German market presence, ExxonMobil Corporation and Shell occupy positions defined by synthetic base stock technology and global specification leadership. Domestic specialists LIQUI MOLY and Fuchs exemplify the technical service archetype, anchoring competitive positioning through direct relationships with municipal and logistics fleet operators. ADDINOL and ROWE Mineralölwerk GmbH represent mid-scale German blenders navigating REACH compliance barriers and KBA type-approval requirements.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| LIQUI MOLY |
| ADDINOL |
| ROWE Mineralölwerk GmbH |
| Ravensberger Schmierstoffvertrieb GmbH |
| BP PLC (Castrol) |
| Fuchs |
| Shell |
| Chevron Corporation |
| Others |
Supply & Pricing Matrix
Refinery-scale economies in Group III base oil production concentrate formulation cost advantages among integrated suppliers serving Hamburg-Rhine-Ruhr logistics corridors, compressing price floors for mid-tier blenders while anchoring premium tiers around REACH-compliant additive packages. This scale concentration shapes procurement leverage across German fleet operators, with extended drain interval guarantees commanding measurable premiums over transactional supply contracts.
Pricing Analysis
KBA type-approval standards dictate the pricing tier structure across German commercial vehicle lubricants, separating OEM-warranted fills from aftermarket alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ACEA E6/E8 certification grades and volume scale commitments from 200-plus vehicle fleets. Cost compression in economy tiers intensifies because municipal bus operators prioritize technical service relationships over specification premiums. Logistics operators running just-in-time networks exhibit least price sensitivity, while agricultural equipment fleets in Lower Saxony present highest sensitivity to bio-based feedstock premiums.
Supply Chain Analysis
Strategic stockpile preferences dominate German lubricant procurement, with fleet operators maintaining 30-45 day inventory buffers against refinery-linked supply volatility. Base oil supply concentrates in Germany, Netherlands, and Belgium, drawing from integrated refining complexes along ARA corridor. Formulation rests on Group II/III base stocks, PAO synthetics, and zinc dithiophosphate additive packages. Single-source vulnerability persists in friction modifier feedstocks subject to REACH authorization delays. Distribution runs through direct technical service relationships with municipal fleets and centralized procurement contracts with logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German commercial vehicle lubricants face substitution pressure from electrification-driven thermal management fluids, requiring incumbents to defend engine oil volume while capturing emerging powertrain categories.
For Market Incumbents: Shield synthetic base stock positioning through backward integration into Group III supply and preemptive ACEA E8 formulation certification before regulatory hardening. Consolidate technical service relationships with North Rhine-Westphalia municipal fleets to lock out price competitors. Prioritize drain interval guarantee contracts over transactional supply to embed switching costs. For New Entrants and Emerging Players: Anchor in hybrid powertrain thermal management fluids for municipal bus electrification in Cologne-Düsseldorf-Dortmund triangle, where legacy competition remains absent. Target infrastructure contractor segments with ISO VG 46 hydraulic fluid specifications as construction equipment utilization climbs. Pursue direct fleet telematics integration as go-to-market angle, bypassing traditional distribution layers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors additive-package specialists with REACH-registered friction modifier portfolios and direct OEM relationships. Long-term viability hinges on bio-content certification capabilities ahead of EU carbon border adjustment enforcement. Acquisition target archetype: mid-scale German blenders with KBA type-approval track records and stranded R&D talent. Signal to watch: fleet telematics platforms unbundling lubricant procurement from bundled maintenance contracts.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Registration Investment | Secures 18-36 month formulation lead time for ECHA-authorized friction modifiers ahead of competitor lag. |
| Direct Fleet Telematics Integration | Captures real-time oil condition data feeds that legacy ERP architectures cannot accommodate for logistics operators. |
| Bio-Based Feedstock Certification | Anticipates EU carbon border adjustment tender requirements with rapeseed and synthetic ester lifecycle transparency. |
| Technical Service Contract Expansion | Locks municipal bus procurement in North Rhine-Westphalia through on-site oil analysis and drain optimization guarantees. |
| Synthetic Base Stock Backward Integration | Reduces crude-linked volatility exposure while securing Group III supply for premium 5W-30 full synthetic positioning. |
Research Methodology
Operator-level perspectives from fleet procurement managers, lubricant blending plant directors, additive chemists, municipal transit authority technical officers, and aftermarket distribution channel heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against KBA type-approval databases, REACH registration filings, EU Green Deal policy documentation, and customs trade records for base oil imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for German commercial vehicle activity.
Sensitivity analysis around crude price volatility, REACH authorization timelines, and fleet electrification penetration shaped scenario boundaries across the projection horizon. The analytical framework modeled volume and value outputs across product type, vehicle class, application performance tier, and end-user industry segmentation dimensions. CAGRs derived from regression against historical consumption patterns, OEM fill specification adoption curves, and infrastructure investment trajectories. Industry-specific inputs incorporated Euro VI engine architecture deployment rates and extended drain interval guarantee penetration among logistics operators.
Material uncertainties — regulatory acceleration in bio-based mandates, additive chemist talent scarcity, and hybrid powertrain thermal management fluid category definition — sit outside the modeled envelope. Forecasts reflect assumptions around REACH compliance cost pass-through and KBA enforcement continuity. Revision becomes warranted when fleet electrification penetration crosses thresholds that structurally displace engine oil demand volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Poland Industrial Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
North America and Europe Forestry Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Marine Grease Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Global Grease Market
Lubricants
Plastic Lubricants Market
Lubricants
Global Engineered Fluids Market