
 CNG, RNG, and Hydrogen Tanks Market | 2026-2036
CNG, RNG, and Hydrogen Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
CNG, RNG, and Hydrogen Tanks Market Insights
Aftermarket certification and recertification services is tilting toward composite tank specialists who capture recurring revenue from fleet operators. Hexagon Composites ASA leverages its type-4 cylinder platform to dominate European bus and truck retrofits. Worthington Industries sustains manufacturing scale across metal-lined CNG cylinders for North American distribution networks. Luxfer Group anchors its position through aluminum alloy expertise in high-pressure hydrogen storage systems.
CNG, RNG, and hydrogen tanks are pressure vessels engineered to store compressed gases at service pressures ranging from 250 bar to 700 bar, constructed from aluminum, steel, or polymer-lined carbon-fiber composites through filament winding or autofrettage processes, designed to fuel vehicles, power fuel cells, or buffer industrial gas supply. Composite tank types lead value generation due to their weight advantage in mobility applications, while hydrogen storage segments record the fastest capacity expansion as fuel cell bus and truck deployments multiply. Metal tank categories retain cost competitiveness in stationary CNG storage and emerging market transportation fleets where capital constraints persist.
The EPA regulates greenhouse gas emissions from heavy-duty vehicles under the Clean Air Act, directly expanding the compliant fuel system addressable base, while CARB enforces the Advanced Clean Trucks rule mandating zero-emission vehicle sales percentages that pull hydrogen and RNG tank demand forward. ISO 19881 and UN ECE R134 govern hydrogen cylinder design and vehicle integration safety, creating certification barriers that favor incumbent producers with testing infrastructure. Stakeholders must monitor how the Inflation Reduction Act production tax credits restructure total cost of ownership calculations across fleet procurement cycles.
Market Dynamics
Fleet procurement cycles are compressing as California's hydrogen hub zones and EPA tailpipe mandates force capital deployment toward compliant fuel systems before compliance windows close.
Growth Catalysts
- Advanced Clean Trucks rule:CARB's zero-emission vehicle sales percentages pull hydrogen and RNG tank demand forward in California freight corridors. Fleet operators accelerate orders to meet mandated phase-in thresholds.
- Type-4 composite cylinders:Polymer-lined carbon-fiber construction through filament winding cuts weight versus metal alternatives. Bus and truck retrofits across European networks favor this technology for range extension.
- Freight corridor clustering:Demand concentrates along California's I-10 and I-5 corridors where hydrogen refueling infrastructure is co-located with warehouse distribution centers.
Market Restraints
- Carbon fiber supply concentration:Filament winding feedstock depends on limited precursor suppliers in Japan and the United States. Input cost volatility constrains composite tank production scaling.
- ISO 19881 certification timelines:Hydrogen cylinder design validation requires extensive cyclic pressure testing. Testing infrastructure bottlenecks extend product qualification cycles.
- Stationary CNG metal tanks:Steel and aluminum alternatives retain cost competitiveness in emerging market transportation fleets where capital constraints persist.
Strategic Opportunities
- India's LNG-to-RNG conversion:The country's national petroleum regulator is streamlining cylinder recertification protocols. Fleet operators seek compliant retrofit pathways for existing vehicle platforms.
- Inflation Reduction Act production tax credits:IRA incentives restructure total cost of ownership calculations across fleet procurement cycles. Hydrogen storage systems capture credit eligibility through domestic content requirements.
- Fuel cell bus integration:Type-4 cylinders converging with fuel cell stack thermal management enable packaged powertrain solutions. Municipal transit authorities issue bundled tenders.
Industry Challenges
- Autofrettage process engineering:Metal-lined cylinder production requires specialized pressure vessel fabrication skills. Workforce gaps in precision welding and liner-to-composite bonding constrain output.
- UN ECE R134 vehicle integration:Hydrogen cylinder mounting and crashworthiness certification demands concurrent engineering with OEM chassis teams. Timeline misalignment delays fleet deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNG, RNG, and Hydrogen Tanks Market |
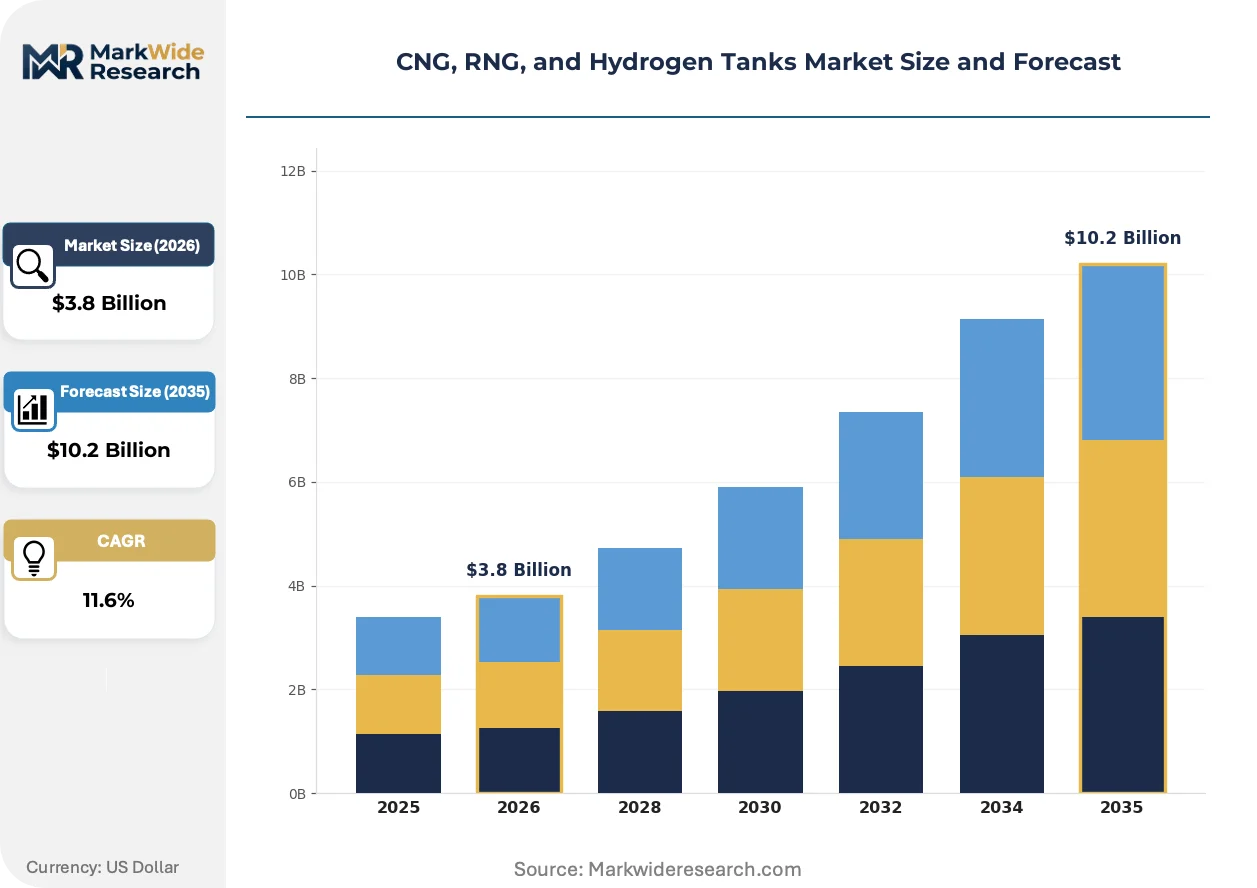
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tank Type: Composite, Metal, Hydrogen Storage, CNG Storage Capacity: 100 liters, 200 liters, 300 liters, 500 liters End User: Transportation, Industrial, Residential, Commercial Application: Fuel Cell, Natural Gas Vehicles, Energy Storage, Equipment |
| Companies Covered | Hexagon Composites ASA, Worthington Industries, Luxfer Group, Faber Industrie SpA, Everest Kanto Cylinders Ltd., Chart Industries, Quantum Fuel Systems, Xinyi Beijing Tianhai Industry Co. Ltd., Lianyungang Zhongfu Lianzhong Composites Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNG, RNG, and Hydrogen Tanks Market Trends and Innovations
Digital engineering tools are compressing product development cycles while regulatory frameworks force material transitions across pressure vessel categories.
Filament-wound composite liners are virtualizing the traditional metal-dominated cylinder supply base. Type-4 construction replaces steel and aluminum in mobility applications where weight reduction directly extends vehicle range. Fleet operators in European bus networks now specify composite platforms as standard.
EPA greenhouse gas regulations under the Clean Air Act are expanding the compliant fuel system addressable base. Heavy-duty vehicle emission limits tighten progressively, pulling capital toward alternative fuel infrastructure. CARB enforcement in California freight corridors is accelerating hydrogen and RNG tank procurement ahead of federal mandates.
Aftermarket certification services are unbundling from original equipment supply. Fleet operators now contract directly with composite tank specialists for recertification cycles. This pattern concentrates in California's freight corridors where high-utilization vehicles face compressed inspection intervals.
CNG, RNG, and Hydrogen Tanks Market Segmentation
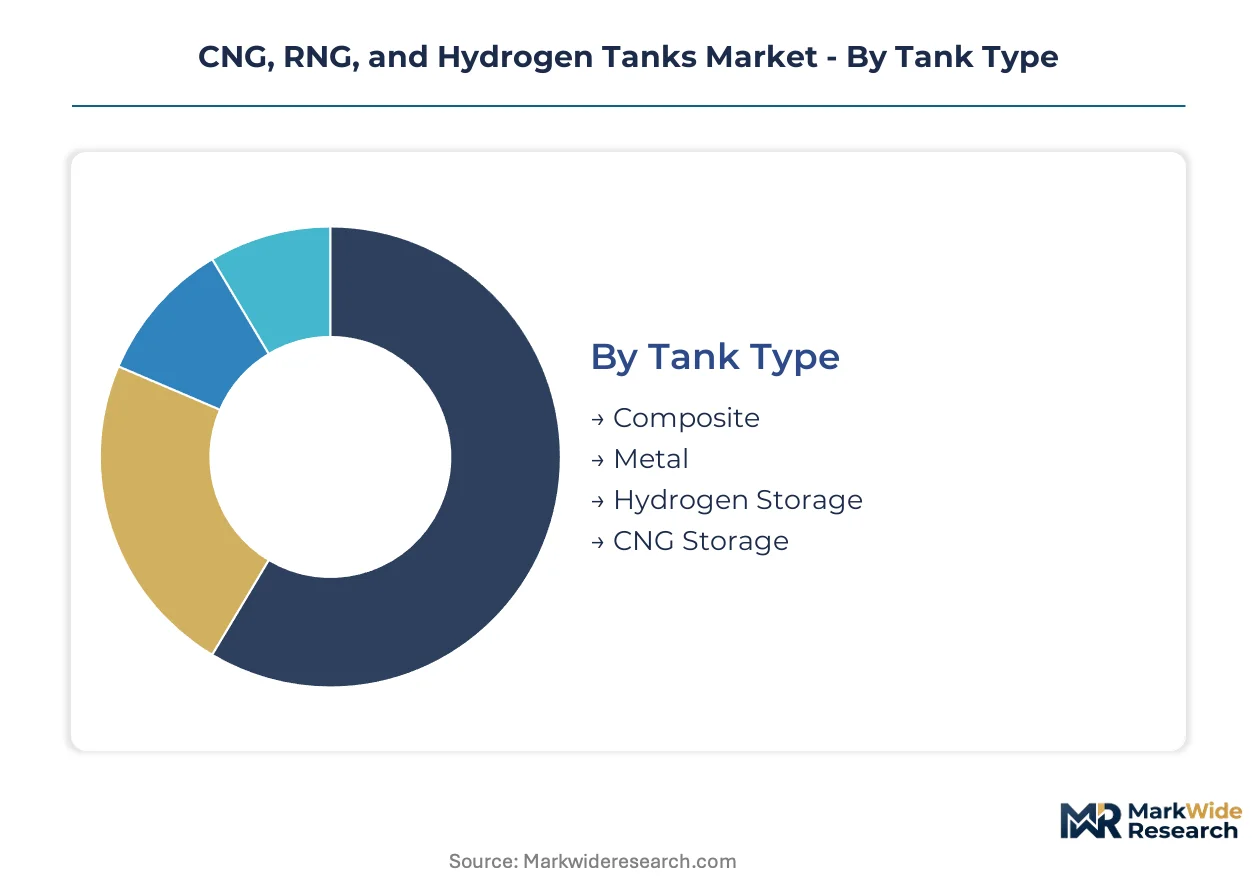
Tank type and capacity configurations determine procurement cycles across fleet and stationary applications. End-user concentration in freight corridors and application-specific pressure requirements create distinct margin profiles within each segment.
Tank Type:
Composite cylinders turn over fastest in mobility retrofits, while metal tanks cycle slower in stationary infrastructure.
- Composite:Polymer-lined carbon-fiber construction through filament winding cuts weight by half versus metal alternatives. Demand clusters in California hydrogen hub zones where CARB mandates accelerate bus and truck fleet conversions.
- Hydrogen Storage:Type-4 cylinders rated to 700 bar service pressure enable fuel cell range extension. European transit authorities specify these systems for municipal bus tenders, driving capacity expansion ahead of other tank categories.
- Metal:Steel and aluminum construction retains cost competitiveness in emerging market transportation fleets with capital constraints.
- CNG Storage:Metal-lined cylinders serve stationary buffering applications and lower-pressure vehicle fueling systems.
Metal tanks dominate installed base. Hydrogen storage is where expansion concentrates.
Capacity:
Cost tier stratification separates premium large-capacity systems from economy small-tank configurations.
- 500 liters:Heavy-duty truck and bus platforms specify these units for range-critical freight corridor operations. Fleet operators in California's I-5 corridor absorb premium pricing to maximize uptime between refueling stops.
- 300 liters:Mid-size commercial vehicles and regional delivery trucks balance payload capacity with fuel autonomy. European retrofit specialists standardize this configuration for urban bus networks.
- 200 liters:Light commercial vehicles and passenger car conversions favor compact packaging.
- 100 liters:Small fleet vehicles and auxiliary power units utilize minimal footprint designs.
300-liter systems anchor current fleet procurement. 500-liter configurations are climbing the fastest as long-haul trucking electrifies.
End User:
Application maturity varies sharply, with transportation fleets cycling equipment faster than stationary industrial installations.
- Transportation:Heavy-duty trucking and municipal bus fleets generate recurring demand through compressed procurement cycles. EPA tailpipe mandates force capital deployment toward compliant fuel systems before compliance windows close.
- Industrial:Manufacturing facilities and warehouse distribution centers install stationary buffering tanks with decade-long service intervals. RNG injection into pipeline networks drives incremental capacity additions.
- Commercial:Retail fueling stations and fleet maintenance depots specify mid-size storage systems.
- Residential:Limited deployment concentrates in off-grid heating and backup power applications.
Transportation commands revenue concentration. Industrial installations provide stable aftermarket service attach rates.
Application:
Customer type fragmentation separates mobility integrators from stationary energy infrastructure developers.
- Fuel Cell:Hydrogen storage systems integrated with fuel cell stacks enable zero-emission powertrains. OEM chassis teams coordinate cylinder mounting and thermal management for municipal transit bundled tenders.
- Natural Gas Vehicles:CNG and RNG tanks serve dual-fuel and dedicated gaseous fuel platforms. Fleet operators in California freight corridors scale orders ahead of CARB Advanced Clean Trucks phase-in thresholds.
- Energy Storage:Stationary buffering tanks balance renewable gas supply intermittency.
- Equipment:Portable and auxiliary power units utilize compact cylinder configurations.
Natural gas vehicles hold current volume leadership. Fuel cell applications are gaining share fastest as hydrogen hub infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet buyers in Germany and Japan absorb premium pricing for composite cylinders with minimal volume elasticity, while operators in India and Brazil negotiate aggressively on metal-tank procurement where capital constraints dominate purchasing decisions.
United States
California's freight corridors generate concentrated demand for 500-liter hydrogen and RNG systems as CARB's Advanced Clean Trucks rule forces compliance investments. EPA tailpipe mandates under the Clean Air Act expand the addressable base for compliant fuel systems nationwide. Houston and Los Angeles anchor hydrogen hub deployments where warehouse distribution centers co-locate refueling infrastructure.
Germany
European transit authorities specify Type-4 composite cylinders for municipal bus tenders, driving premium procurement cycles. KBA enforces UN ECE R134 vehicle integration standards that compress product qualification timelines. Bavaria's automotive engineering clusters coordinate OEM chassis teams with cylinder mounting specialists for fuel cell powertrain integration.
China
Domestic fuel cell bus deployments in Beijing-Tianjin-Hebei and the Yangtze River Delta absorb high-pressure hydrogen storage capacity. MIIT's dual carbon goals accelerate fleet electrification mandates across heavy-duty segments. Shanghai's port logistics operators pilot 700-bar systems for container truck electrification along coastal freight routes.
India
National petroleum regulator streamlining of cylinder recertification protocols unlocks retrofit demand for existing CNG fleets. PLI scheme incentives for clean mobility infrastructure pull capital toward compliant storage systems. Maharashtra and Gujarat host the densest concentrations of LNG-to-RNG conversion activity among commercial vehicle operators.
Japan
METI hydrogen roadmap targets drive municipal bus and commercial truck fuel cell deployments. JIS standards for high-pressure gas cylinders create certification barriers that favor incumbent testing infrastructure. Tokyo and Osaka metropolitan areas concentrate early infrastructure buildout where station operators bundle storage tenders with dispensing equipment.
CNG, RNG, and Hydrogen Tanks Market Competitive Landscape
Capability concentration sits with composite specialists who command certification infrastructure and filament-winding expertise; scale advantage sits with metal fabricators who sustain throughput across standardized cylinder geometries. The market structures around three archetypes: European composite platform leaders, North American metal-lined volume producers, and Asian integrated manufacturers. Dominant competitive moves include capacity expansion in hydrogen-rated Type-4 production and strategic partnerships between tank fabricators and fuel cell stack integrators.
Among European composite specialists, Hexagon Composites ASA and Faber Industrie SpA occupy positions anchored to Type-4 cylinder platforms for bus and truck retrofits. Worthington Industries exemplifies the North American metal-lined volume tier with sustained manufacturing scale across CNG cylinder categories. Everest Kanto Cylinders Ltd. represents Asian integrated manufacturing capability serving emerging market transportation fleets where cost competitiveness determines procurement outcomes.
| Leading Market Players |
|---|
| Hexagon Composites ASA |
| Worthington Industries |
| Luxfer Group |
| Faber Industrie SpA |
| Everest Kanto Cylinders Ltd. |
| Chart Industries |
| Quantum Fuel Systems |
| Xinyi Beijing Tianhai Industry Co. Ltd. |
| Lianyungang Zhongfu Lianzhong Composites Group Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Japanese carbon fiber precursor suppliers anchor filament-winding feedstock for Type-4 composite cylinders, concentrating margin capture in the hands of incumbent tank fabricators who have secured long-term offtake agreements and ISO 19881 certification infrastructure.
Pricing Analysis
Aftermarket recertification services generate lifetime value multiples exceeding initial equipment sales for composite tank specialists. Three-tier pricing structure across premium certified, standard compliant, and economy metal-lined tiers separates fleet operators by CARB compliance urgency. Cost compression in metal-lined CNG categories intensifies as Indian and Brazilian fleet buyers negotiate aggressively on capital-constrained procurement. Transportation fleets in California freight corridors show minimal price elasticity for 700-bar hydrogen systems.
Supply Chain Analysis
Tariff exposure between the United States and China dominates composite precursor sourcing decisions for North American tank fabricators. Filament-winding feedstock draws from Japan, the United States, and limited European suppliers. Toray and Teijin carbon fiber, polymer liner resins, and precision winding equipment constitute critical input dependencies. Single-source vulnerability in aerospace-grade precursor allocation constrains Type-4 scaling. Distribution runs through OEM chassis integrators, aftermarket service networks, and direct fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel cell bus powertrain standardization is creating platform-economics inflection as municipal transit authorities issue bundled tenders integrating cylinder storage with thermal management systems.
For Market Incumbents: Pre-empt emerging Asian integrated manufacturers by securing captive carbon fiber supply through backward integration into precursor production or long-term offtake with Japanese suppliers. Expand 700-bar Type-4 capacity in hydrogen hub zones ahead of CARB Advanced Clean Trucks phase-in thresholds. Certification infrastructure moats erode if testing backlog delays product qualification cycles. For New Entrants and Emerging Players: India's LNG-to-RNG conversion corridor offers the most penetrable white-space target as the national petroleum regulator streamlines recertification protocols. Maharashtra and Gujarat fleet operators seek compliant retrofit pathways for existing vehicle platforms. Target municipal bus aftermarket services through direct contracting models that bypass OEM channel control. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European composite specialists holding Type-4 platforms but lacking fuel cell stack integration partnerships. Five-to-ten-year viability hinges on hydrogen hub infrastructure maturation beyond demonstration projects. Watch for bundled tender awards from California transit authorities as inflection indicator for powertrain packaging consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor | Secures filament-winding feedstock against Toray and Teijin allocation constraints. |
| 700-bar Type-4 Capacity Expansion | Captures CARB-driven demand in California I-5 and I-10 freight corridors. |
| Fuel Cell Stack Partnership | Enables bundled municipal transit tenders integrating thermal management systems. |
| Recertification Service Unbundling | Concentrates recurring revenue from high-utilization fleet operators in hydrogen zones. |
| India Regulatory Compliance Positioning | Aligns with PLI scheme incentives and streamlined cylinder recertification protocols. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement directors, cylinder fabrication engineers, fuel cell system integrators, and aftermarket service managers and refined through secondary validation against EPA regulatory filings, CARB compliance databases, UN ECE R134 certification records, and hydrogen hub infrastructure deployment trackers. Bottom-up fleet order aggregation and top-down fuel system addressable market sizing were triangulated to constrain volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include tank type, pressure rating tier, vehicle platform class, end-use application, and regional regulatory cluster. CAGRs were derived from fleet procurement cycle compression analysis and infrastructure deployment pacing. Fuel cell bus tender awards and hydrogen station commissioning rates served as industry-specific forecast inputs.
Practitioners should monitor carbon fiber precursor allocation shifts, ISO 19881 certification timeline extensions, and IRA domestic content requirement rulings for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Middle-East and Africa Syngas Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Syngas Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Welding Gas Market
Industrial Gases
North America Syngas Market
Industrial Gases
Helium Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Gas Purifiers Market
Industrial Gases
Argon Gas Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
3D Printing Gases Market