
 Syngas Market | 2026-2036
Syngas Market Size, Share, and Industry Trends Forecast 2026-2036
Syngas Market Intelligence
China's substantial investment in coal-to-chemical infrastructure is tilting the feedstock balance toward coal gasification on a large scale. Major technology licensors and engineering firms are central to these developments. Shell plc leverages its advanced gasification technology for large-scale projects, while Air Products and Chemicals Inc. operates extensive syngas production and supply networks for industrial clients. Topsoe A/S specializes in high-performance catalysts essential for converting syngas into valuable end products like methanol and ammonia.
Syngas is a fuel gas mixture composed primarily of hydrogen and carbon monoxide, with varying amounts of carbon dioxide. It is produced via the gasification or reforming of a carbon-containing feedstock and serves as a critical intermediate for manufacturing hydrogen, methanol, and synthetic hydrocarbon fuels. While coal remains a dominant feedstock type globally, the use of biomass and municipal solid waste is expanding in modular units designed for decentralized power or chemical production. Chemical manufacturing commands the largest share of end-use applications, but the synthetic fuels segment represents the fastest-growing outlet.
Regulatory frameworks directly shape technology selection and operational viability in the syngas industry. Mandates from bodies such as the US EPA and China's Ministry of Ecology and Environment (MEE) on emissions from industrial facilities drive investment in cleaner gasification and gas cleanup technologies. The EU's REACH regulation governs the chemical products derived from syngas, setting standards for market entry. Future investment decisions will hinge on balancing feedstock security against evolving carbon pricing schemes and circular economy policies.
Market Dynamics
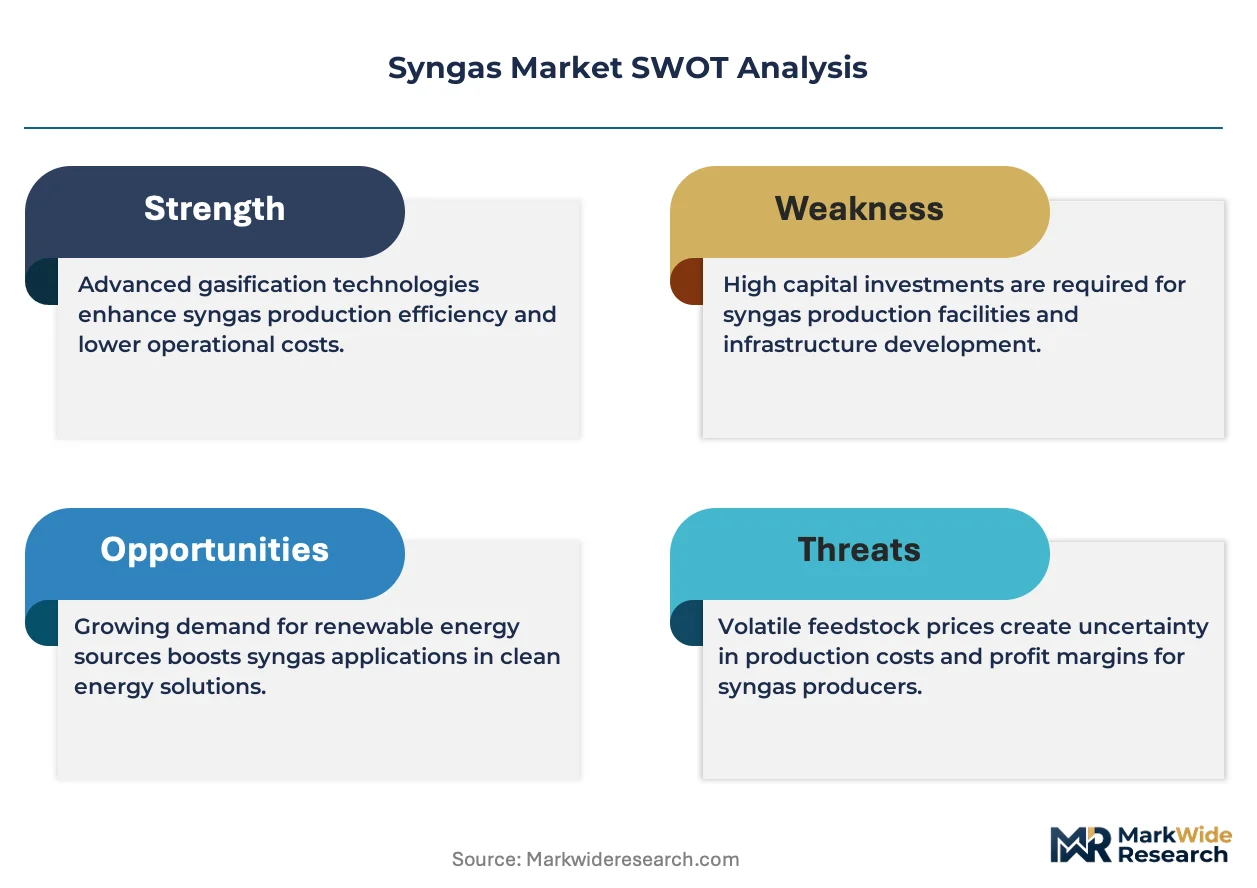
The syngas market is defined by a core tension between established, large-scale fossil fuel gasification and the push toward decarbonization. National industrial strategies, particularly China's dual carbon goals, reinforce coal's role, while circular economy policies simultaneously promote alternative feedstocks.
Growth Catalysts
- National Industrial Strategies:China's focus on coal-to-chemical pathways, driven by its dual carbon policy framework, underpins massive investment in new gasification capacity to ensure feedstock security for its domestic chemical and fertilizer industries.
- Chemical Sector Expansion:Concentrated demand from new fertilizer and methanol plant constructions in the industrial zones of India provides a significant pull for syngas production, serving as a foundational building block for these high-value products.
- Feedstock Diversification:The development of modular gasification units is enabling the use of biomass and municipal solid waste, supporting decentralized power generation and chemical production aligned with circular economy objectives.
Market Restraints
- High Capital Intensity:The construction of world-scale syngas production facilities, particularly coal gasification plants, requires substantial upfront capital investment, creating a high barrier to entry for new participants.
- Stringent Emission Controls:Regulations from bodies like the US EPA and China's MEE impose strict limits on pollutants such as sulfur oxides and nitrogen oxides, necessitating costly gas cleanup and purification systems.
- Feedstock Price Volatility:Syngas production economics are highly sensitive to price fluctuations in primary feedstocks like natural gas and coal, creating margin pressure and operational uncertainty for producers.
Strategic Opportunities
- Sustainable Aviation Fuels:The synthetic fuels segment, particularly the production of sustainable aviation fuel (SAF) via Fischer-Tropsch synthesis from syngas, represents the fastest-growing outlet, driven by aviation industry decarbonization targets.
- Waste-to-Value Conversion:EU circular economy policies and incentives create a strong business case for deploying advanced gasification technologies that convert non-recyclable municipal and industrial waste into valuable syngas.
- Low-Carbon Chemical Pathways:Integrating carbon capture, utilization, and storage (CCUS) technologies with syngas production units offers a pathway to produce low-carbon hydrogen, ammonia, and methanol, meeting future climate policy demands.
Industry Challenges
- Complex Project Execution:The engineering, procurement, and construction of large-scale gasification plants involve long timelines and significant logistical complexity, creating risks of budget overruns and commissioning delays.
- Technology Licensing Hurdles:Accessing state-of-the-art gasification and synthesis catalyst technologies often involves navigating intricate and expensive licensing agreements with a concentrated group of specialized technology providers.
- Legacy System Integration:Retrofitting existing industrial facilities with modern, flexible feedstock gasifiers or advanced gas cleanup systems presents significant technical challenges and potential operational disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syngas Market |
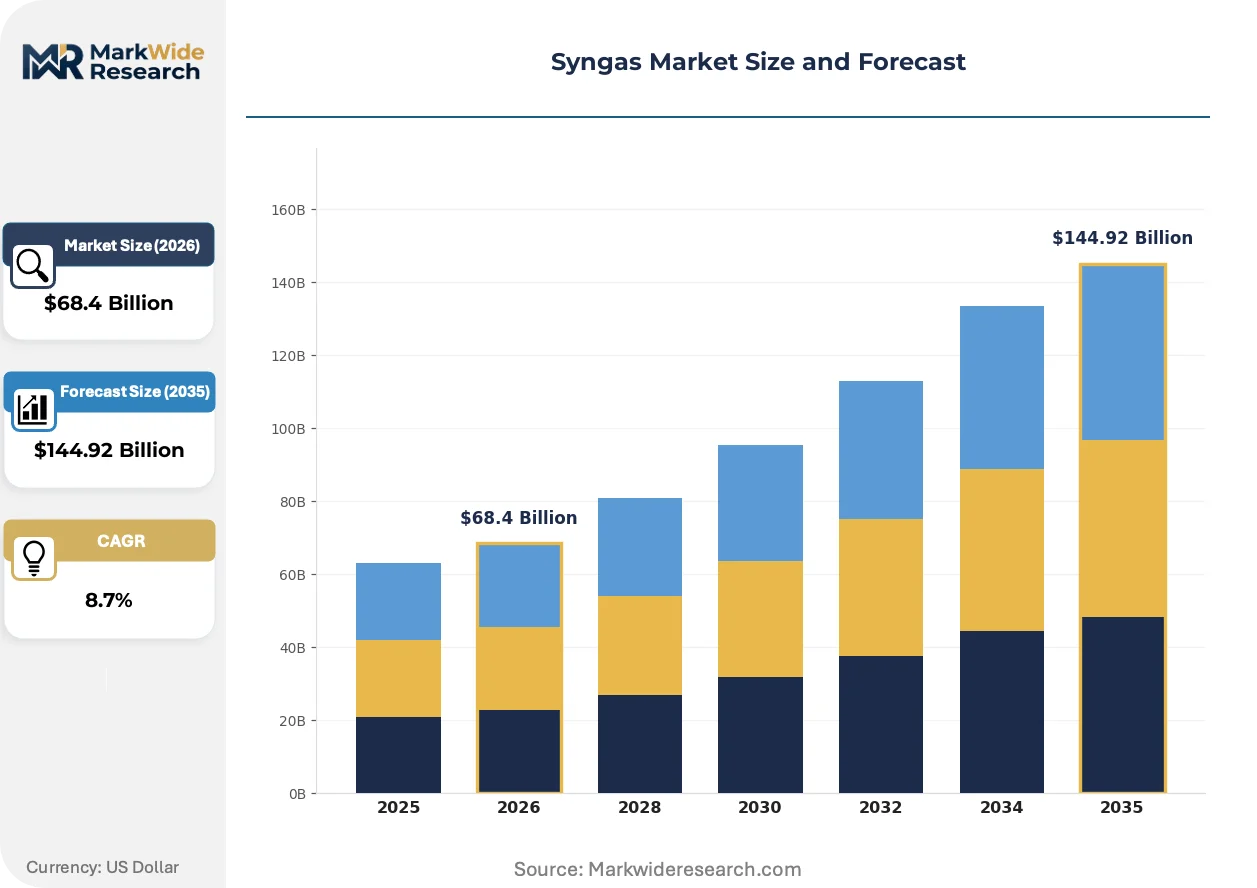
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Coal, Natural Gas, Biomass, Industrial Waste Gases, Municipal Solid Waste Production Technology: Gasification, Reforming, Partial Oxidation, Autothermal Reforming, Methanation End Use Industry: Chemical Manufacturing, Power Generation, Synthetic Fuels, Fertilizer Production, Metal Processing Deployment Model: Onsite Plants, Centralized Facilities, Modular Units, Portable Systems |
| Companies Covered | Shell plc, Topsoe A/S, Air Liquide, Methanex Corporation, BASF SE, Air Products and Chemicals Inc., Sasol, KBR Inc., Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syngas Market Strategic Shifts & Innovations
Technological advancements are fundamentally expanding the viable feedstock base beyond traditional fossil fuels. This shift is enabling the integration of waste streams and biomass into the chemical value chain, driven by both regulatory pressures and corporate sustainability mandates.
Advanced gasification methods, such as plasma and fluidized bed systems, are designed to process heterogeneous feedstocks including municipal solid waste and agricultural residues. Chemical producers and waste-to-energy project developers are increasingly adopting these systems in new-build projects. This development is collapsing the economic and logistical barriers that have historically separated waste management from chemical feedstock procurement, creating novel circular economy models.
The EU's REACH regulation is a significant force shaping market access and product specifications for syngas derivatives. This framework requires comprehensive data on chemical safety, compelling producers to invest in sophisticated gas purification to meet the high-purity standards for products like methanol sold in Europe. Chemical manufacturers targeting the EU are therefore upgrading their gas cleanup trains to ensure compliance and maintain market entry.
A notable shift in operational models is the adoption of long-term, over-the-fence supply agreements for industrial gases. Large chemical and refining customers are outsourcing the production of syngas to dedicated industrial gas specialists who build and operate the plants on-site. This trend is most visible in major industrial hubs in the US Gulf Coast and China, allowing end-users to de-risk capital spending and focus on core downstream chemical conversion.
Syngas Market Segmentation
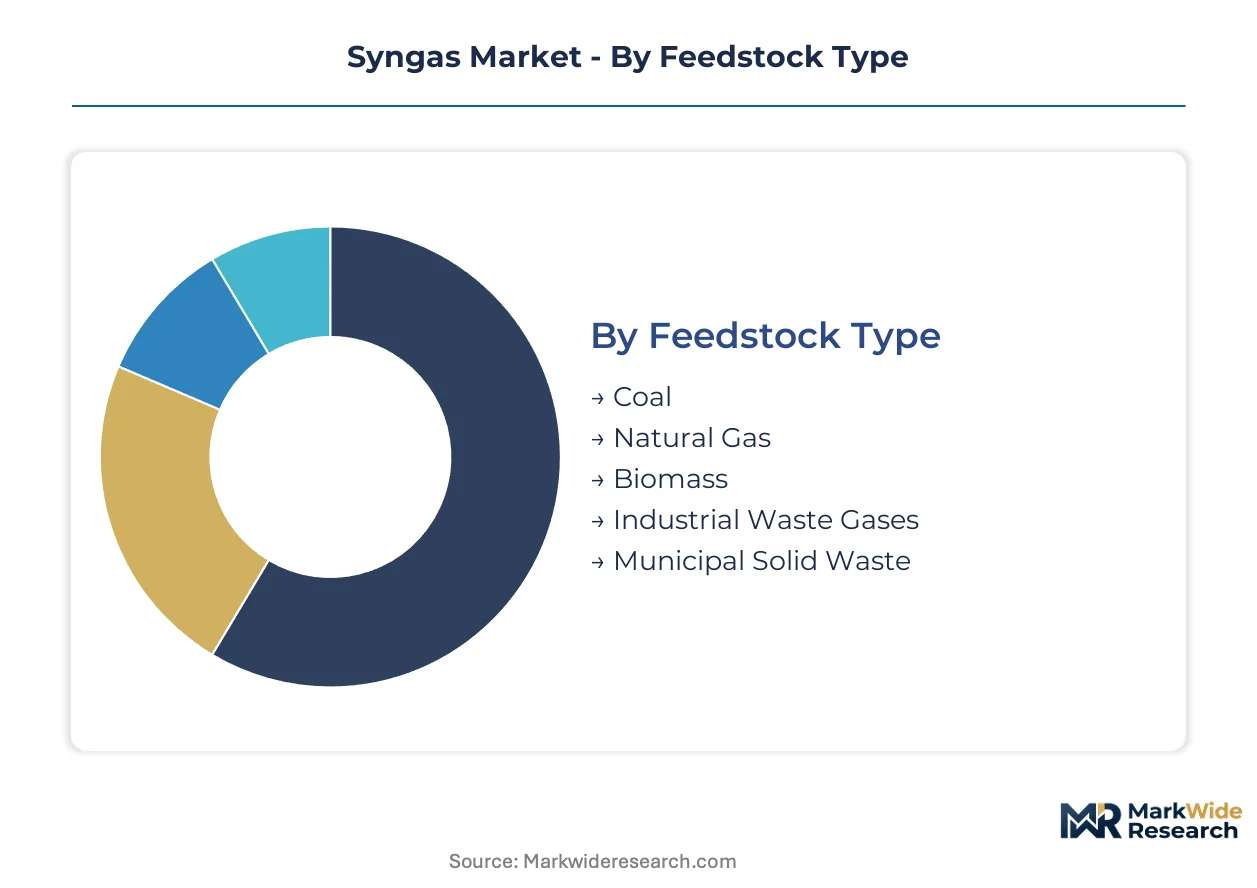
Understanding the syngas market through segmentation reveals the diverse pathways and applications driving its expansion. This granular analysis highlights specific feedstock preferences, technological advancements, end-user requirements, and operational models shaping industry investments. Each segment reflects distinct value propositions and growth trajectories within the broader syngas ecosystem.
Feedstock Type:
The feedstock dimension categorizes syngas production based on the primary carbon-containing material used for gasification or reforming processes.
- Coal:This fossil fuel remains a dominant feedstock globally, particularly in countries like China, where it underpins large-scale chemical and fertilizer production to ensure national resource security. Demand concentration is high for coal-to-chemical infrastructure projects.
- Biomass:Derived from organic matter such as agricultural residues or forestry waste, biomass gasification offers a renewable pathway for syngas, supporting decentralized power and chemical production. This segment aligns with circular economy objectives and sustainability mandates.
- Natural Gas:A widely available and relatively clean-burning fossil fuel, natural gas is reformed to produce syngas for hydrogen, ammonia, and methanol synthesis. Its use depends heavily on regional gas prices and infrastructure availability.
- Industrial Waste Gases:These are by-products from industrial processes, such as steel manufacturing or refining, which can be captured and converted into syngas. This approach enhances resource efficiency and reduces industrial emissions.
- Municipal Solid Waste:Non-recyclable urban waste streams are gasified to produce syngas, offering a waste-to-energy or waste-to-chemical solution. This segment addresses waste management challenges while creating valuable products.
Coal commands the established base. The steepest expansion runs through Biomass.
Production Technology:
Syngas generation methods define this segment, encompassing various thermochemical processes designed to convert diverse feedstocks into the gas mixture.
- Gasification:This process converts carbonaceous feedstocks into syngas at high temperatures with a controlled amount of oxygen and/or steam, forming the fundamental method for solid and liquid feedstocks. Advanced gasification systems process heterogeneous materials like waste.
- Reforming:Primarily applied to natural gas or light hydrocarbons, reforming uses steam or dry carbon dioxide to produce syngas, serving as a critical step for hydrogen and methanol production. Demand is strong in petrochemical hubs like the US Gulf Coast.
- Partial Oxidation:This technology involves the sub-stoichiometric combustion of a feedstock with oxygen, producing syngas with minimal nitrogen dilution. It is often used for heavier hydrocarbons and residual oils.
- Autothermal Reforming:Combining elements of steam reforming and partial oxidation, this method leverages the exothermic heat from partial oxidation to drive endothermic steam reforming reactions. It offers efficiency advantages for natural gas conversion.
- Methanation:While not a primary syngas production method, methanation converts syngas (specifically CO and H2) into methane. This process is crucial for producing synthetic natural gas (SNG) from syngas.
While Gasification remains fundamental, Autothermal Reforming is rapidly gaining traction for specific applications.
End Use Industry:
The ultimate application of syngas determines demand patterns, spanning a range of industrial sectors that rely on it as a chemical intermediate or fuel.
- Chemical Manufacturing:Syngas is a foundational building block for producing a vast array of chemicals, including methanol, ammonia, and acetic acid. This sector represents the largest share of syngas consumption globally.
- Synthetic Fuels:This segment involves converting syngas into liquid fuels like diesel, gasoline, or sustainable aviation fuel (SAF) via processes such as Fischer-Tropsch synthesis. Aviation industry decarbonization targets drive this segment.
- Fertilizer Production:Syngas is a critical raw material for ammonia synthesis, which is then converted into various nitrogen-based fertilizers. India's new fertilizer plant constructions significantly boost this demand.
- Power Generation:Syngas can be combusted in gas turbines or engines to generate electricity, often as part of integrated gasification combined cycle (IGCC) plants. This application provides a cleaner alternative to direct coal combustion.
- Metal Processing:Syngas finds use in the metallurgical industry as a reducing agent in direct reduced iron (DRI) production. This reduces reliance on traditional coke.
Chemical Manufacturing drives the largest volume, with Synthetic Fuels showing the most dynamic growth.
Deployment Model:
Operational scale and location differentiate deployment models, reflecting varied strategies for syngas production and supply to end-users.
- Centralized Facilities:These are large-scale syngas production plants, often located in industrial zones, serving multiple customers or integrated downstream processes. They benefit from economies of scale and extensive infrastructure.
- Modular Units:Smaller, pre-fabricated syngas units designed for decentralized deployment, often processing biomass or waste near the feedstock source. These units offer flexibility and reduced capital intensity for specific projects.
- Onsite Plants:Dedicated syngas production facilities built directly within or adjacent to a single industrial customer's premises. This model ensures a continuous, reliable supply, de-risking capital for end-users.
- Portable Systems:Highly compact and mobile syngas generators, typically for niche applications or remote power generation. These systems offer rapid deployment and flexibility for temporary needs.
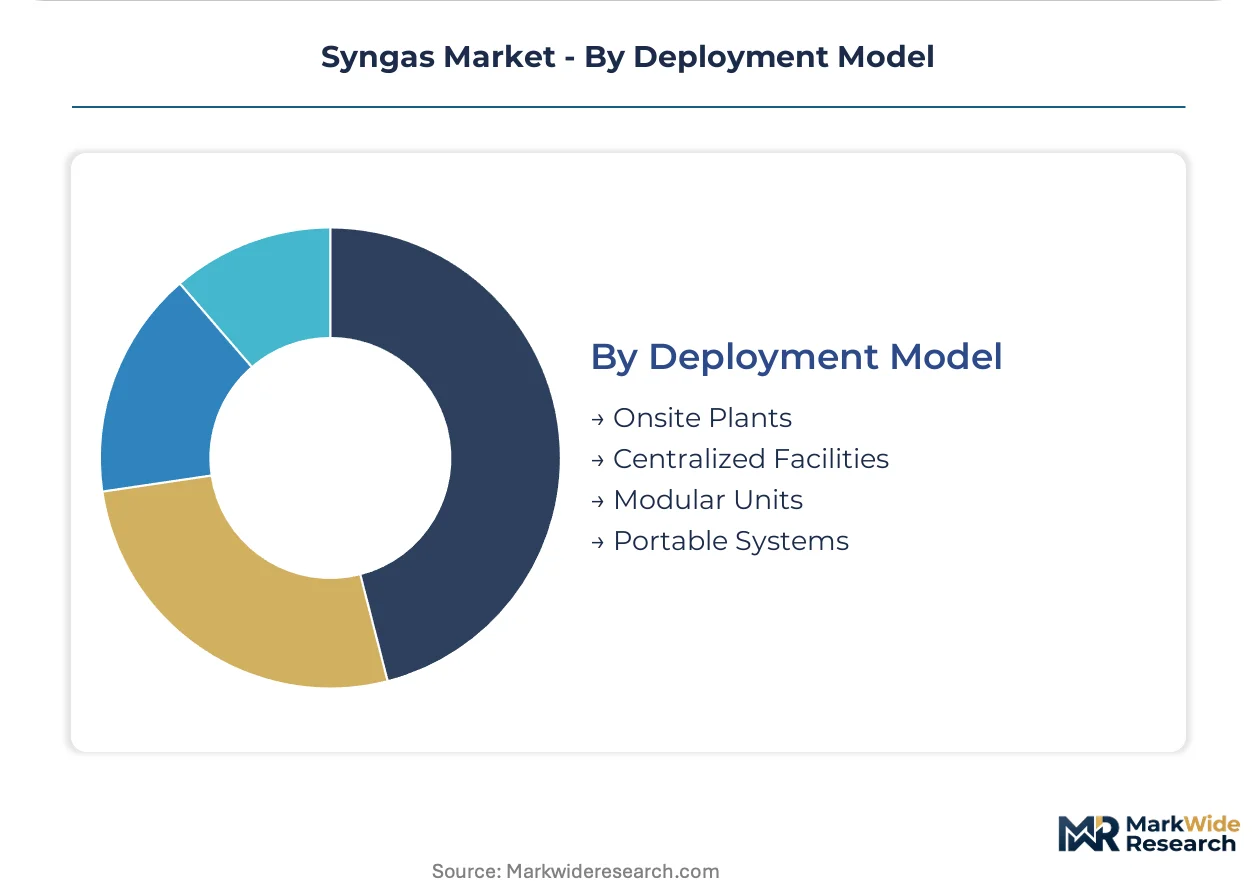
The majority of current capacity resides in Centralized Facilities, but Modular Units offer significant future potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Well-developed industrial gas pipeline networks facilitate the efficient distribution of syngas across key production and consumption hubs globally. These critical infrastructure assets enable large-scale chemical manufacturing and fuel production. Strategic investments in these networks support the market's expansion into new applications.
China
China's vast coal transportation networks underpin its significant investment in coal-to-chemical infrastructure for syngas production. Demand primarily stems from its domestic chemical and fertilizer industries. The Ministry of Ecology and Environment (MEE) enforces strict emission standards, driving investment in cleaner gasification technologies. Industrial zones across the Yangtze River Delta concentrate these large-scale syngas facilities.
India
New port developments along India's coastline support the import of feedstocks and export of syngas derivatives, driving local market expansion. New fertilizer and methanol plant constructions create substantial demand for syngas as a foundational building block. India's Production Linked Incentive (PLI) scheme encourages domestic chemical manufacturing. Industrial clusters in Gujarat and Maharashtra are rapidly expanding syngas production capacities.
United States
Extensive natural gas pipeline systems in the United States provide reliable feedstock supply for syngas production. Strong demand originates from hydrogen and methanol synthesis within the petrochemical sector. The US Environmental Protection Agency (EPA) mandates stringent emission controls, necessitating advanced gas cleanup systems. The US Gulf Coast petrochemical hubs remain major centers for syngas production and consumption.
Germany
Germany's robust rail and waterway infrastructure supports the movement of diverse feedstocks, including biomass and waste, for syngas generation. Chemical manufacturing drives significant syngas consumption, alongside emerging waste-to-value conversion projects. The EU's REACH regulation dictates product specifications for syngas derivatives. Chemical parks in regions like North Rhine-Westphalia adopt advanced gasification technologies.
Netherlands
The Port of Rotterdam serves as a critical hub for importing and exporting feedstocks and syngas-derived products. Demand is strong for methanol and ammonia production, with a growing focus on circular economy initiatives using biomass. European circular economy policies foster the deployment of advanced gasification for waste conversion. The industrial complex around Rotterdam integrates various syngas-consuming chemical processes.
Syngas Market Key Industry Players
Platform integrators command the system tier, while component specialists sit upstream, providing critical technologies and catalysts for syngas production. The syngas market exhibits a tiered structure, with large industrial gas companies offering integrated solutions alongside specialized technology licensors. Strategic archetypes include large-scale industrial gas providers, technology-focused licensors, and chemical manufacturing giants. Dominant competitive moves involve strategic partnerships for complex project execution and continuous portfolio diversification into new feedstock types.
Within the large-scale industrial gas and technology provider tier, Shell plc exemplifies integrated solutions for complex syngas projects. Air Products and Chemicals Inc. occupies a position as a dedicated industrial gas specialist, operating extensive production and supply networks for diverse industrial clients. Topsoe A/S represents a key component specialist, offering high-performance catalysts essential for converting syngas into valuable end products like methanol and ammonia. These entities collectively shape the market's technological trajectory and operational models. Their strategic focus on efficiency and feedstock flexibility drives industry innovation, particularly in challenging regulatory environments.
| Leading Market Players |
|---|
| Shell plc |
| Topsoe A/S |
| Air Liquide |
| Methanex Corporation |
| BASF SE |
| Air Products and Chemicals Inc. |
| Sasol |
| KBR Inc. |
| Linde plc |
Cost & Logistics Intelligence
Industrial gas pipeline networks, critical for efficient syngas distribution, influence cost dynamics by centralizing supply in key hubs and enabling price differentiation based on delivery method and scale. This infrastructure directly impacts the economic viability of large-scale syngas production and its downstream applications.
Pricing Analysis
Contract-based long-term offtake with volume-based tiering defines the dominant pricing structure for syngas. Price differentiation stems from geographic delivery costs and the purity standards mandated by regulations like the EU's REACH. Pricing pressure intensifies due to feedstock price volatility and the high capital expenditure required for advanced gas cleanup systems. Modular units for waste-to-value conversion often exhibit the highest price sensitivity, balancing initial investment with long-term operational savings.
Supply Chain Analysis
Upstream feedstock sourcing is concentrated, with China dominating coal-to-chemical supply and the US Gulf Coast providing extensive natural gas for reforming processes. Key raw material dependencies include coal, natural gas, biomass, and specialized catalysts from providers like Topsoe A/S. Commodity price volatility for primary feedstocks presents a significant supply chain risk for producers. Downstream distribution typically involves direct, on-site supply through dedicated pipelines or long-term over-the-fence agreements with major industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This syngas market is experiencing a cyclical recovery, primarily driven by expanding chemical sector demand and significant investments in new industrial facilities across developing economies.
For Market Incumbents:
Pre-empt competitive threats from alternative feedstocks by integrating advanced gasification technologies for biomass and waste streams. Deepen vertical integration into catalyst development to mitigate licensing hurdles and optimize process efficiency. Invest in carbon capture, utilization, and storage (CCUS) solutions to future-proof facilities against evolving carbon pricing schemes and stringent emission controls from bodies like the US EPA.
For New Entrants and Emerging Players:
Underpenetrated regions in Southeast Asia and parts of Africa offer white-space opportunities for modular syngas units processing local biomass. Target the rapidly expanding sustainable aviation fuel (SAF) segment, leveraging Fischer-Tropsch synthesis from syngas. A viable go-to-market angle involves offering integrated waste-to-chemical or waste-to-energy solutions, aligning with circular economy objectives and local waste management challenges.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized technology licensors and industrial gas providers with proven advanced gasification or catalyst expertise. The long-term viability of syngas is robust, driven by its foundational role in chemical manufacturing and its potential for decarbonization. An ideal acquisition target archetype possesses strong intellectual property in gasification or synthesis catalysts. The signal to watch is the acceleration of national mandates for low-carbon hydrogen or SAF production.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Low-Carbon Methanol | Meets growing demand for a versatile chemical building block while addressing climate policy demands. |
| Partnerships for SAF Production | Secures market share in the fastest-growing syngas application, driven by aviation decarbonization targets. |
| Integration of CCUS Technologies | Enhances environmental compliance and enables production of low-carbon hydrogen and ammonia. |
| Diversification into Biomass/Waste Feedstocks | Reduces reliance on fossil fuels and supports circular economy models, mitigating feedstock price volatility. |
| Advanced Catalyst Research and Development | Improves conversion efficiency and product selectivity, offering a competitive advantage in high-value derivatives. |
Research Approach
Desk research of industry reports, regulatory filings from the US EPA and China's MEE, and technology patent databases preceded structured interviews with plant managers, chemical engineers, procurement leads at chemical manufacturers, and technology licensors. This approach enabled comprehensive data collection and facilitated a robust bottom-up and top-down triangulation of market insights.
Assumptions regarding feedstock availability and pricing stability were held constant across the analysis window, while variations in regulatory stringency and technological adoption rates were modeled. The analytical framework segmented the market by feedstock type, production technology, end-use industry, deployment model, and regional regulatory frameworks. Compound annual growth rates were derived by correlating historical market expansion with projected industrial output and energy policy shifts.
Practitioners should monitor geopolitical events impacting feedstock supply and rapid technological breakthroughs in alternative energy for early signals of market shifts. Forecasts reflect these underlying assumptions. Cross-checking against international energy agency reports and chemical industry association projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
North America Specialty Gas Market
Industrial Gases
High Purity Methane Gas Market
Industrial Gases
Neon Gas Market
Industrial Gases
US Specialty Gas Market
Industrial Gases
Argon Gas Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
Europe Syngas Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
High Purity Gas Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Global Nitrogen Market