
 Industrial Hydrogen Peroxide Market | 2026-2036
Industrial Hydrogen Peroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hydrogen Peroxide Market Outlook
Middle Eastern capacity expansion is fragmenting the traditional supply hierarchy among established producers. Solvay leverages its integrated peroxide-to-derivatives chain across Belgian and Italian sites to sustain margin capture. Evonik Industries AG anchors its position through proprietary anthraquinone process technology that dominates high-concentration segments. Kemira Oyj competes aggressively in Nordic and Baltic water treatment markets where seasonal pulp mill cycles create volume spikes.
Industrial hydrogen peroxide is an aqueous solution of hydrogen peroxide (H₂O₂) typically manufactured through the anthraquinone auto-oxidation process, with commercial grades ranging from 35% to 70% concentration depending on end-use requirements. The compound functions primarily as a powerful oxidizing agent, bleaching medium, and environmental treatment chemical across industrial processes. Technical Grade commands the largest volume share due to its broad compatibility with pulp bleaching sequences and chemical synthesis loops, while Food Grade carries premium positioning driven by stringent FSSAI and FDA purity mandates that limit producer eligibility. Water Treatment application segments are expanding fastest as municipal utilities and industrial effluent plants adopt advanced oxidation processes for emerging contaminant removal.
EPA effluent guidelines and OSHA permissible exposure limits shape product formulation standards and worker safety protocols in North American facilities. EMA and ECHA frameworks under REACH regulate residual stabilizer chemistries and impurity profiles for pharmaceutical-grade material circulating within Europe. China's MEE enforces discharge standards that directly boost hydrogen peroxide demand in flue gas desulfurization and wastewater treatment installations. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment competitive positioning across regional supply bases.
Market Dynamics
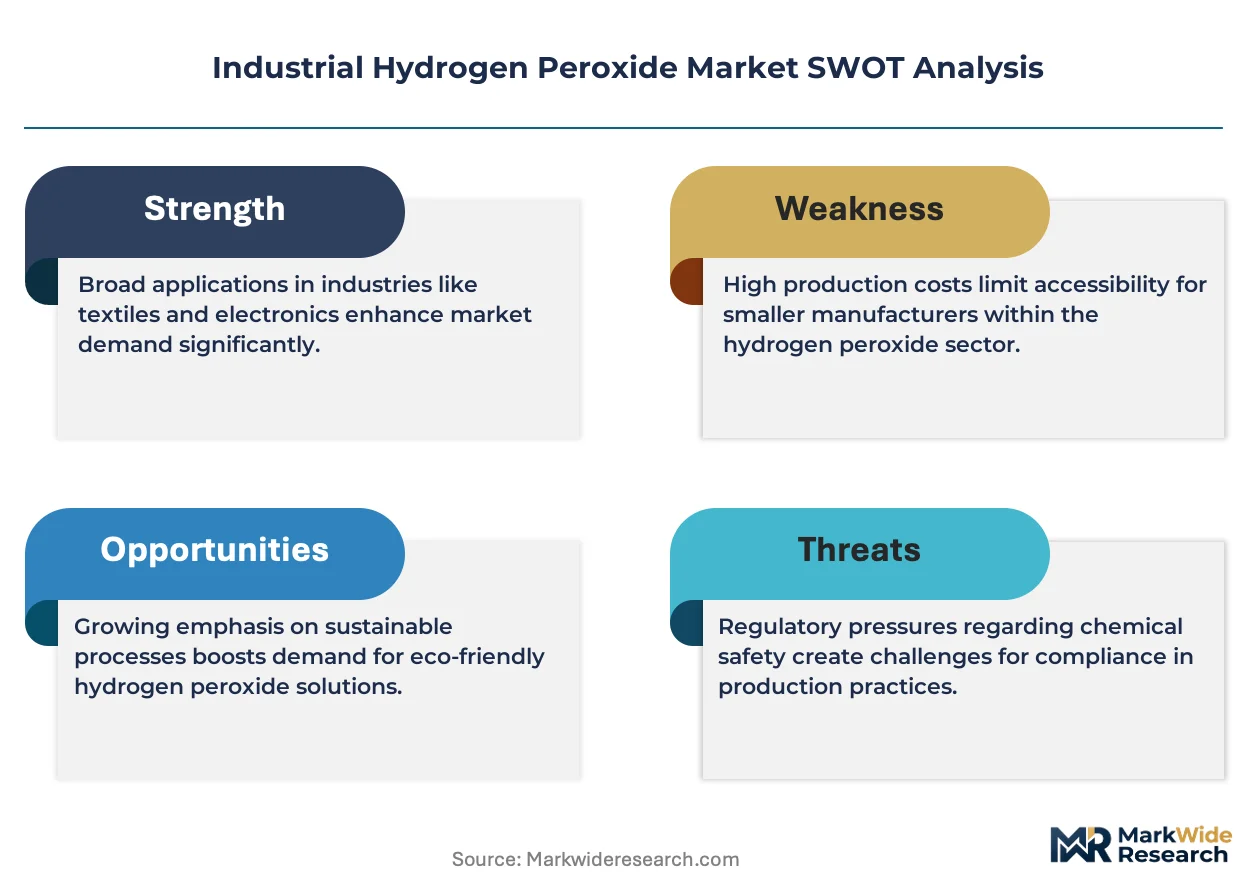
REACH compliance in Europe is compressing producer margins through purity threshold tightening while simultaneously accelerating substitution toward cleaner oxidation chemistries across textile and electronics manufacturing clusters.
Growth Catalysts
- Pulp mill bleaching modernization:North American and Nordic facilities are retrofitting chlorine-free sequences, pulling concentrated hydrogen peroxide into multi-stage delignification loops.
- EPA effluent guidelines:Municipal utilities across the United States are deploying advanced oxidation processes for PFAS and pharmaceutical residue destruction, expanding technical grade offtake.
- China's MEE discharge mandates:Flue gas desulfurization and industrial wastewater installations in Jiangsu and Zhejiang provinces are scaling hydrogen peroxide dosing systems.
Market Restraints
- Anthracene derivative input volatility:2-ethylanthraquinone feedstock costs fluctuate with naphtha-cracker economics, squeezing anthraquinone process margins unpredictably.
- High-concentration logistics concentration:Specialized tanker fleets and certified storage infrastructure cluster in Belgium, Germany, and the US Gulf Coast, creating regional supply bottlenecks.
- Peracetic acid substitution:Food and beverage sterilization applications in Europe are partially migrating to peracetic acid blends with lower regulatory classification burdens.
Strategic Opportunities
- Saudi Arabia and UAE industrial zones:Green hydrogen integration projects at Jubail and Ruwais are piloting electrolysis-derived hydrogen peroxide for petrochemical oxidation.
- Semiconductor wafer cleaning:Ultra-high purity grades are penetrating South Korean and Taiwanese foundries as node sizes shrink below 3 nanometers.
- EU Green Deal carbon border adjustments:Low-carbon process certifications are creating premium pricing tiers for anthraquinone producers with renewable energy integration.
Industry Challenges
- Anthraquinone process engineering expertise:The specialized knowledge required for hydrogenation catalyst management and explosion-proof reactor design faces generational attrition in Western Europe.
- Food Grade certification timelines:FSSAI and FDA dual-track approvals for Indian export-oriented producers extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hydrogen Peroxide Market |
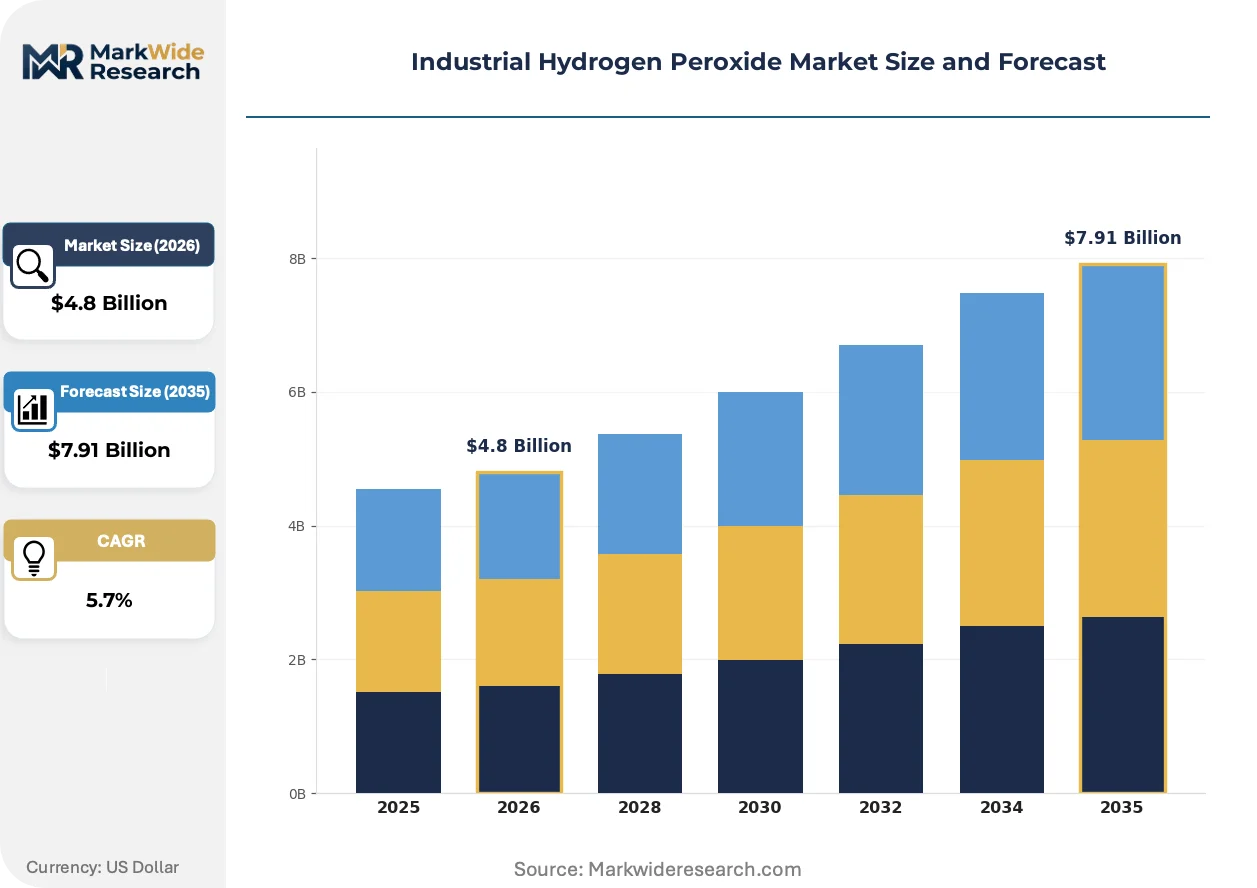
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stabilized Grade, Unstabilized Grade, Food Grade, Technical Grade Application: Pulp & Paper, Textile, Water Treatment, Chemical Manufacturing End User: Food Processing, Pharmaceuticals, Agriculture, Electronics Packaging Type: Drums, IBC Totes, Bulk Tanks, Canisters |
| Companies Covered | Solvay, Evonik Industries AG, BASF SE, Arkema, FMC Corporation, Mitsubishi Gas Chemical Company, Inc., Akzo Nobel N.V., Kemira Oyj, Taekwang Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hydrogen Peroxide Market Strategic Shifts
Process intensification and regulatory chemistry mandates are converging to reshape production economics and end-use specifications across the value chain.
Membrane electrolysis technology for direct hydrogen peroxide synthesis is migrating from pilot installations at German chemical parks toward commercial-scale deployment. Specialty chemical producers in the Rhine-Ruhr region are evaluating modular units for on-site generation to circumvent concentrated transport regulations. This distributed production model is compressing the traditional hub-and-spoke supply architecture dominated by large-scale anthraquinone facilities.
REACH Annex XVII restrictions on residual stabilizer chemistries are forcing reformulation of pharmaceutical-grade hydrogen peroxide circulating within the European Economic Area. ECHA evaluations of quaternary ammonium compounds and organophosphonates are driving producers toward phosphate-free stabilizer systems. German and Italian pharmaceutical contract manufacturers are front-loading compliance investments to secure uninterrupted supply for aseptic packaging applications.
Integrated service contracts bundling chemical supply with dosing equipment and performance monitoring are displacing traditional bulk commodity transactions in North American water treatment markets. Municipal utilities in California and Texas are consolidating vendor relationships around full-service oxidation system operators. This procurement compression favors producers with captive engineering services and regional technical support infrastructure over pure chemical merchants.
Industrial Hydrogen Peroxide Market Segmentation
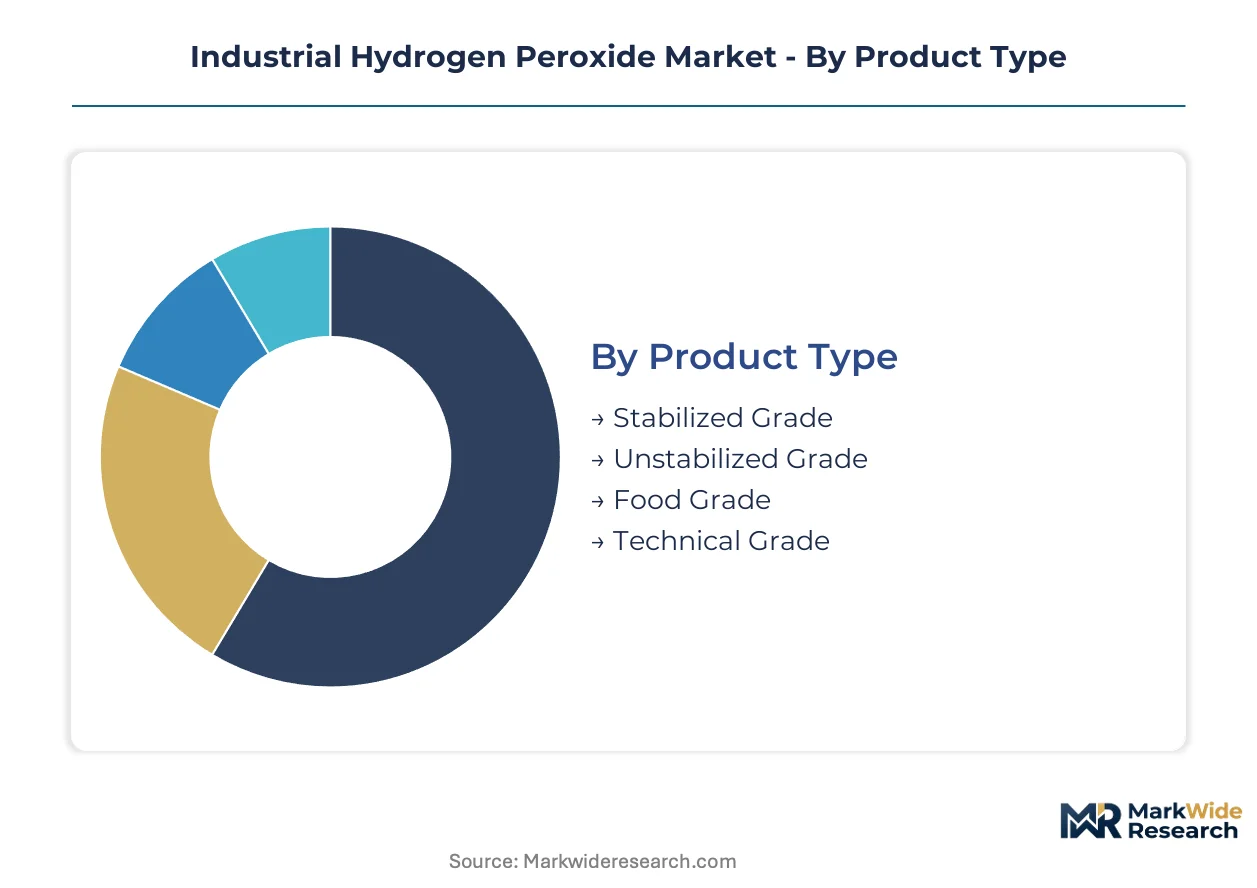
Industrial hydrogen peroxide demand fragments across purity grades, application chemistries, and logistics formats. Each segmentation axis carries distinct margin profiles and regulatory burdens that reshape competitive positioning across supply tiers.
Product Type:
Purity thresholds and stabilizer chemistry define cost tiers and end-use eligibility across manufacturing verticals.
- Technical Grade:Aqueous solutions of 35-70% concentration with organophosphonate or phosphate-based stabilizers for industrial oxidation. Pulp mills in Finland and Sweden deploy this grade in multi-stage chlorine-free bleaching sequences where ECF/TCF mandates drive volume.
- Food Grade:Ultra-low heavy metal specifications under FDA 21 CFR 184.1366 and FSSAI standards, requiring dedicated production trains and stainless-steel distribution infrastructure. Indian exporters face 18-24 month dual-track certification timelines that compress supplier pools.
- Stabilized Grade:Enhanced shelf-life formulations with chelating agents for extended storage in tropical climates and remote industrial sites.
- Unstabilized Grade:Rapid-decomposition variants for immediate-use chemical synthesis where stabilizer interference would compromise reaction kinetics.
Technical Grade commands the established base. The steepest expansion runs through Food Grade as aseptic packaging demand climbs.
Application:
End-use chemistry determines concentration requirements, dosing infrastructure, and service intensity across customer relationships.
- Water Treatment:Advanced oxidation processes for PFAS and pharmaceutical residue destruction in California and Texas municipal utilities. EPA effluent guidelines are accelerating technical grade offtake as ozone-peroxide combinations displace conventional chlorination.
- Pulp & Paper:Delignification and brightening sequences in Nordic and North American mills retrofitting away from elemental chlorine. Seasonal volume spikes align with annual maintenance shutdown cycles.
- Textile:Bleaching and desizing operations concentrated in Jiangsu and Zhejiang provinces where China's MEE discharge standards enforce hydrogen peroxide adoption over hypochlorite.
- Chemical Manufacturing:Propylene oxide and organic peroxide synthesis serving petrochemical oxidation chains.
Pulp & Paper retains the volume anchor. Water Treatment is gaining share fastest on regulatory enforcement tailwinds.
End User:
Customer type dictates certification burden, technical support requirements, and contract structure across procurement relationships.
- Food Processing:Sterilization of aseptic packaging and equipment sanitation with FSSAI/FDA dual compliance. European substitution toward peracetic acid blends is fragmenting growth trajectories.
- Pharmaceuticals:API synthesis and cleanroom sanitation with EMA purity mandates and REACH Annex XVII stabilizer restrictions forcing phosphate-free reformulation investments.
- Electronics:Semiconductor wafer cleaning and PCB etching in South Korean and Taiwanese foundries where sub-3 nanometer nodes demand ultra-high purity grades.
- Agriculture:Seed treatment and irrigation system disinfection with emerging biologicals compatibility requirements.
Food Processing anchors current demand. Electronics is climbing the fastest on node shrinkage and foundry expansion.
Packaging Type:
Logistics format shapes working capital intensity, regulatory compliance scope, and geographic reach of individual supply points.
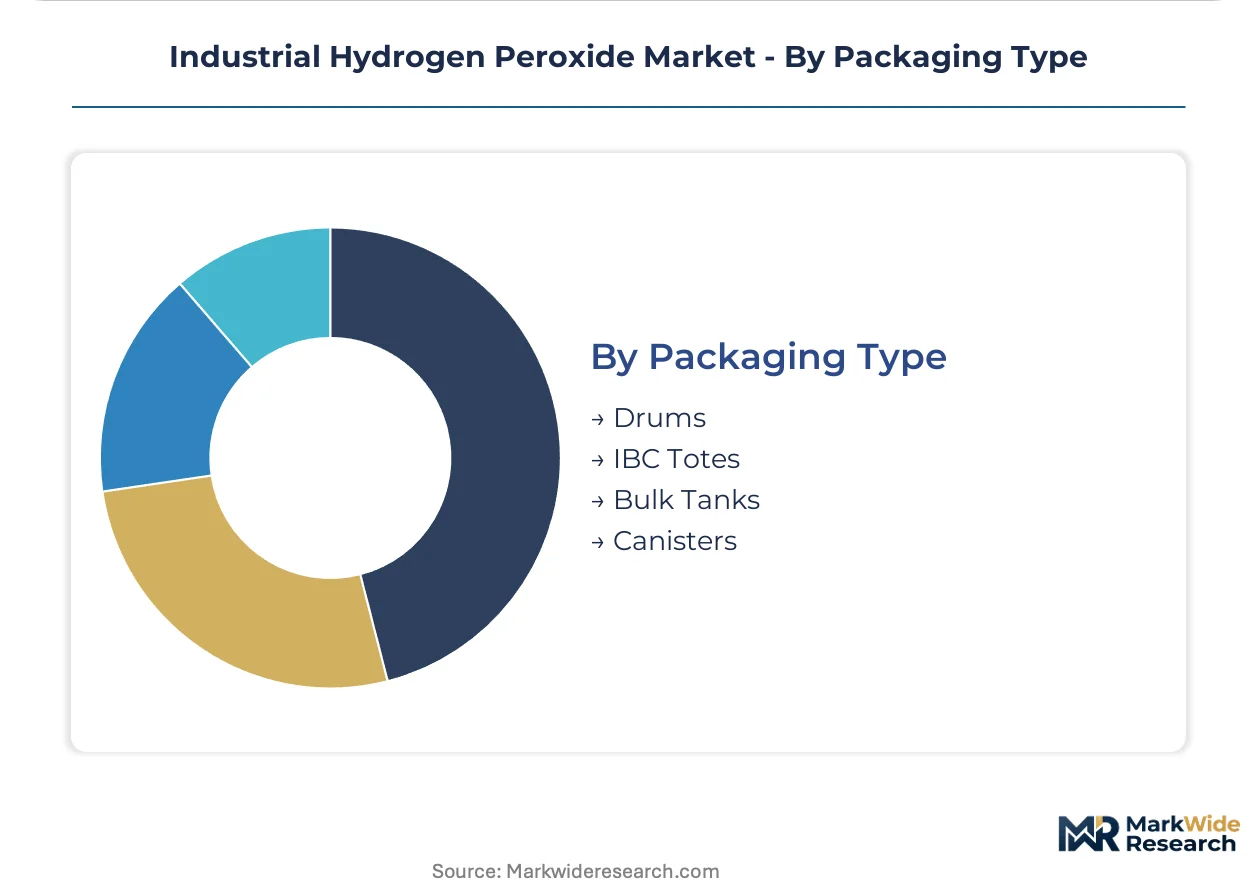
- Bulk Tanks:Dedicated stainless-steel trailers and certified storage terminals serving pulp mills and chemical complexes in Belgium, Germany, and the US Gulf Coast. Concentrated infrastructure creates regional supply bottlenecks for high-concentration material.
- IBC Totes:Intermediate bulk containers for mid-scale water treatment and textile operations requiring flexibility without full tanker economics.
- Drums:Standard 200-liter steel or polyethylene containers for chemical manufacturing and smaller agricultural applications.
- Canisters:Small-format packaging for laboratory, pharmaceutical, and specialty electronics use with highest per-unit logistics cost.
Bulk Tanks command the established base. IBC Totes show the steepest expansion as distributed water treatment scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE discharge mandates anchor the dominant geography, with Jiangsu and Zhejiang provinces driving concentrated demand for flue gas desulfurization and wastewater treatment applications.
United States
EPA effluent guidelines propel municipal utilities toward advanced oxidation processes for PFAS destruction. California and Texas utilities consolidate vendor relationships around full-service oxidation system operators. The US Gulf Coast hosts specialized tanker fleets and certified storage infrastructure for high-concentration material.
Germany
Rhine-Ruhr specialty chemical producers evaluate modular membrane electrolysis units for on-site generation. ECHA evaluations under REACH Annex XVII drive phosphate-free stabilizer reformulation for pharmaceutical-grade material. German pharmaceutical contract manufacturers front-load compliance investments for aseptic packaging supply security.
Finland
Nordic pulp mills retrofit chlorine-free bleaching sequences, pulling concentrated hydrogen peroxide into multi-stage delignification loops. Seasonal volume spikes align with annual maintenance shutdown cycles. Kemira Oyj competes aggressively in water treatment markets where seasonal pulp mill cycles create demand volatility.
Saudi Arabia
Green hydrogen integration projects at Jubail pilot electrolysis-derived hydrogen peroxide for petrochemical oxidation. The country's national industrial development program supports capacity expansion in strategic chemicals. Ruwais industrial zones attract downstream derivative investments linked to peroxide supply chains.
South Korea
Semiconductor wafer cleaning applications penetrate foundries as node sizes shrink below 3 nanometers. Ultra-high purity grades command premium positioning in electronics manufacturing clusters. The country's national technology regulator enforces purity standards that limit qualified supplier pools.
Industrial Hydrogen Peroxide Market Competitive Environment
Integrated chemical conglomerates and specialty oxidation specialists split the market between scale-driven commodity supply and application-engineered service models. Belgian and Italian sites sustain margin capture through captive derivatives chains, while Nordic operators compete on seasonal flexibility. Strategic moves concentrate on capacity expansion in Middle Eastern industrial zones and technology licensing for membrane electrolysis pilots.
Among European-based chemical conglomerates, Solvay and Evonik Industries AG exemplify divergent archetypes: the former leverages integrated peroxide-to-derivatives positioning, while the latter anchors high-concentration segments through proprietary process technology. Kemira Oyj represents the regional specialist model, concentrating on water treatment and pulp applications where seasonal demand patterns favor agile supply structures.
| Leading Market Players |
|---|
| Solvay |
| Evonik Industries AG |
| BASF SE |
| Arkema |
| FMC Corporation |
| Mitsubishi Gas Chemical Company, Inc. |
| Akzo Nobel N.V. |
| Kemira Oyj |
| Taekwang Industrial Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Middle Eastern hydrogen peroxide installations is compressing supplier pricing power while simultaneously forcing European anthraquinone producers toward premium positioning through carbon-certification differentiation. This utilization imbalance creates divergent margin trajectories across regional supply bases, with concentrated logistics infrastructure amplifying price spreads between high-concentration hubs and distributed consumption points.
Pricing Analysis
Geographic price spreads between Belgium-Germany high-concentration hubs and Asian manufacturing clusters exceed transport-equivalent differentials, reflecting certification-tier segmentation. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade concentration levels anchors the model, with FDA/FSSAI dual-track compliance commanding substantial premia. Cost compression in technical-grade material is intensifying because Middle Eastern capacity additions erode legacy producer volume leverage. Municipal utilities in water treatment applications demonstrate highest price sensitivity due to consolidated procurement and performance-based contracting, while semiconductor foundries show lowest sensitivity given node-shrinkage purity requirements.
Supply Chain Analysis
2-ethylanthraquinone feedstock draws from naphtha-cracker economics in Belgium, Germany, and the US Gulf Coast, tethering production costs to volatile petrochemical input cycles. Anthraquinone process catalysts, hydrogenation reactor vessels, and phosphate-free stabilizer chemistries constitute critical component dependencies. Single-source vulnerability concentrates in specialized tanker fleets certified for high-concentration transport, creating regional chokepoints. Distribution runs through hub-and-spoke bulk tank infrastructure for pulp mills and chemical complexes, with membrane electrolysis pilots threatening to disperse this architecture toward on-site generation models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated municipal utilities and multinational pulp conglomerates, fragmenting supplier leverage across fragmented merchant chemical producers. This procurement compression rewards integrated service bundling over pure commodity supply relationships.
For Market Incumbents: Pre-empt peracetic acid substitution in European food sterilization applications by accelerating phosphate-free stabilizer reformulation investments ahead of REACH Annex XVII enforcement. Anchor volume commitments through captive engineering services and regional technical support infrastructure, defending against integrated oxidation system operators consolidating vendor relationships in North American water treatment markets.
For New Entrants and Emerging Players: Establish a beachhead in Saudi Arabian and UAE green hydrogen integration zones where electrolysis-derived production pilots lack established supply relationships. Target modular membrane electrolysis deployment for Rhine-Ruhr specialty chemical parks seeking to circumvent concentrated transport regulations. Lead with distributed generation value propositions emphasizing regulatory bypass and working capital reduction over commodity price competition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among water treatment service integrators bundling chemical supply with dosing equipment and performance monitoring. Long-term viability across the analysis window favors producers with backward integration into anthraquinone process technology and captive derivatives chains. Watch for inflection signals in semiconductor node-shrinkage timelines below 3 nanometers, where ultra-high purity grade qualification pools remain restricted.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Electrolysis-derived production at Jubail and Ruwais bypasses anthraquinone feedstock volatility. |
| Backward Integration | Captive 2-ethylanthraquinone production insulates margins from naphtha-cracker cycle exposure. |
| Long-term Supply Agreement | Municipal utility consolidation in California and Texas rewards full-service oxidation system operators. |
| Joint Venture | Pharmaceutical contract manufacturers front-load REACH Annex XVII compliance investments through partnerships. |
| Capacity Expansion | Middle Eastern industrial zones fragment traditional European supply hierarchy through scale economics. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pulp mill technical directors, municipal utility procurement managers, pharmaceutical contract manufacturing executives, and semiconductor foundry chemical engineers. Secondary validation drew from EPA effluent guideline filings, ECHA REACH Annex XVII evaluations, China MEE discharge standard documentation, and customs trade data. Bottom-up capacity and consumption estimates were triangulated against top-down macroeconomic drivers.
Calibration against historical volume trajectories and announced capacity additions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use application chemistry, packaging logistics format, and regional regulatory cluster. CAGRs were derived through regression analysis of demand drivers and supply elasticity parameters, with specific inputs from pulp mill bleaching modernization cycles and semiconductor node-shrinkage roadmaps.
Sensitivities concentrate around REACH compliance timeline acceleration, Middle Eastern capacity utilization rates, and membrane electrolysis commercialization pace. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution technology penetration. Material shifts in EU carbon border adjustment implementation or anthraquinone process catalyst breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
North America Syngas Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Oxygen Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
Europe Syngas Market
Industrial Gases
Fluorocarbon Gases Market