
 Asia-Pacific Syngas Market | 2026-2036
Asia-Pacific Syngas Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Syngas Market Outlook
ISO 14001 environmental management certification is unwinding the competitive landscape for syngas technology providers across Asia-Pacific. Haldor Topsoe A/S leverages its proprietary catalytic reforming platforms to dominate high-efficiency ammonia and methanol loops. Linde plc anchors large-scale gasification deployments through engineering partnerships with state-backed energy conglomerates. Air Products and Chemicals Inc. extends its position via on-site syngas supply contracts with integrated steel and chemical complexes.
Syngas is a mixture of hydrogen, carbon monoxide, and minor fractions of carbon dioxide and methane, produced through partial oxidation or steam reforming of carbonaceous feedstocks at temperatures exceeding 1,000°C; its primary purpose is to serve as an intermediate for hydrogen, ammonia, methanol, and synthetic fuel synthesis. Coal gasification still occupies the largest feedstock share due to abundant domestic reserves in China and India, though biomass gasification is registering the fastest technology trajectory as carbon intensity rules tighten. Chemical production applications command the deepest margin pools, particularly for methanol and ammonia derivatives serving fertilizer and polymer value chains.
China's MEE enforces escalating carbon intensity benchmarks for coal-to-chemical complexes, while India's CEA mandates emission monitoring for captive syngas power units under revised environmental clearance protocols. Japan's METI promotes hydrogen-from-syngas pathways through feed-in tariff adjustments for clean fuel off-take. Stakeholders must track how bilateral clean hydrogen partnerships between Australia, Japan, and South Korea reshape syngas-to-hydrogen offtake economics and technology licensing terms.
Market Dynamics
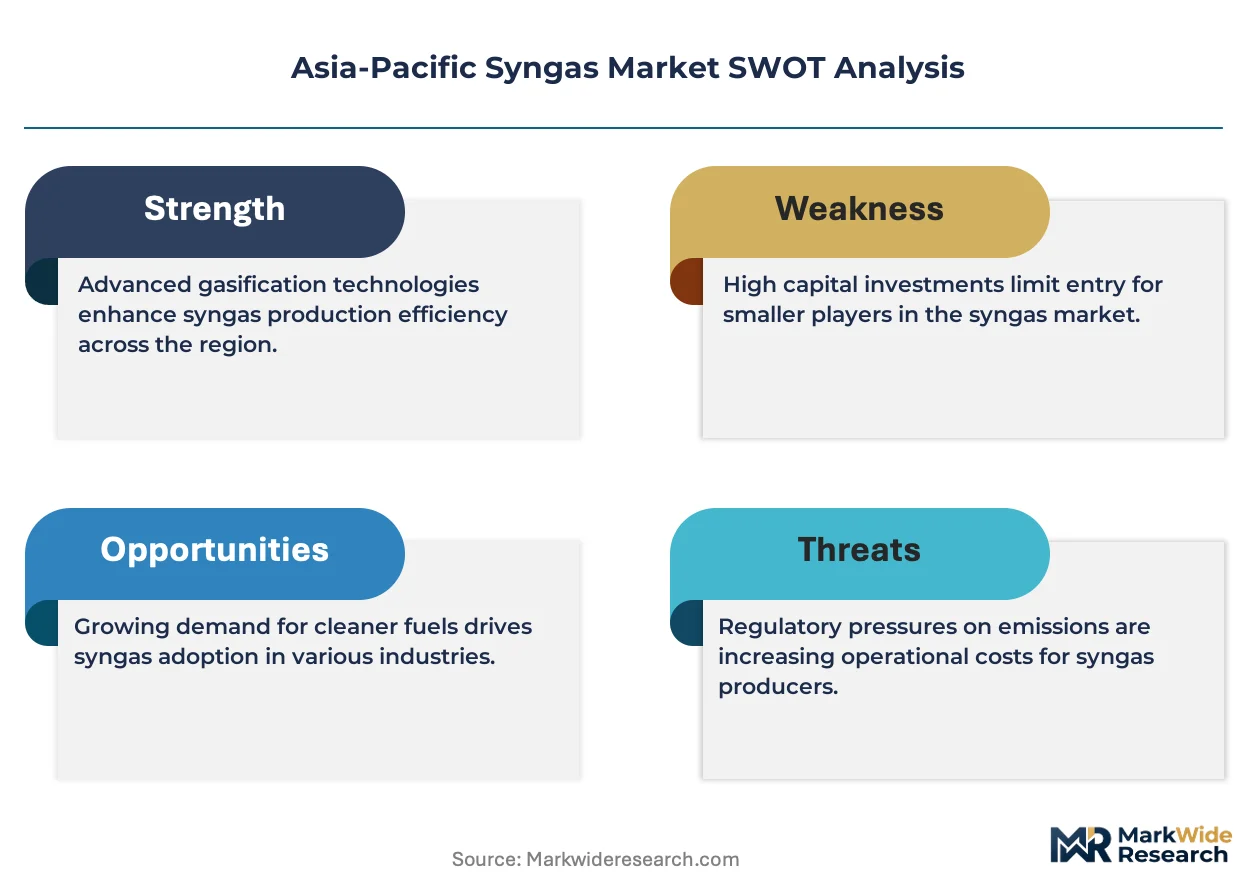
China's MEE carbon intensity benchmarks and India's PLI scheme for clean energy are compressing coal-to-chemical margins while redirecting capital toward biomass gasification and hydrogen-from-syngas pathways across eastern China's industrial clusters and India's Gujarat-Maharashtra corridor.
Growth Catalysts
- Dual carbon goals enforcement:China's MEE mandates are accelerating retrofit demand for high-efficiency gasification trains in coal-to-chemical complexes, tightening feedstock specifications and emissions thresholds simultaneously.
- Steel sector decarbonization:Direct reduction iron processes using syngas are scaling rapidly as Indian and Chinese steel producers face mounting pressure to displace blast furnace capacity.
- Biomass gasification trajectory:Carbon intensity accounting rules are elevating agricultural residue feedstocks to commercial parity in select clusters, attracting engineering procurement focused on integrated biorefinery configurations.
Market Restraints
- Coal price volatility:Thermal coal input cost swings in China and Australia are destabilizing unit economics for gasification assets without long-term fuel supply agreements or captive mine access.
- Oxygen supply concentration:Cryogenic air separation unit capacity concentrates among a limited set of industrial gas suppliers, creating bottleneck risk for large-scale syngas project commissioning schedules.
- Carbon capture integration lag:Post-combustion capture technology remains technically immature at the scale required for coal-to-chemical complexes, delaying compliance with tightening MEE benchmarks.
Strategic Opportunities
- Clean hydrogen export corridors:Bilateral partnerships between Australia, Japan, and South Korea are reshaping syngas-to-hydrogen offtake economics, creating technology licensing windows for reforming platform providers.
- Methanol-to-olefins pivot:Polymer value chain demand in China is elevating methanol derivative margins, rewarding syngas producers with integrated downstream chemical capabilities.
- Captive power reconfiguration:India's CEA emission monitoring mandates for syngas-based captive units are opening retrofit and efficiency upgrade contracts for engineering service providers.
Industry Challenges
- High-temperature materials engineering scarcity:Refractory and catalyst specialists capable of sustaining 1,000°C-plus operating environments remain concentrated among a limited pool of technology licensors, constraining project execution velocity.
- Environmental clearance timeline compression:India's revised protocols under CEA and state pollution control boards are extending pre-construction approval cycles, delaying financial close for greenfield gasification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Syngas Market |
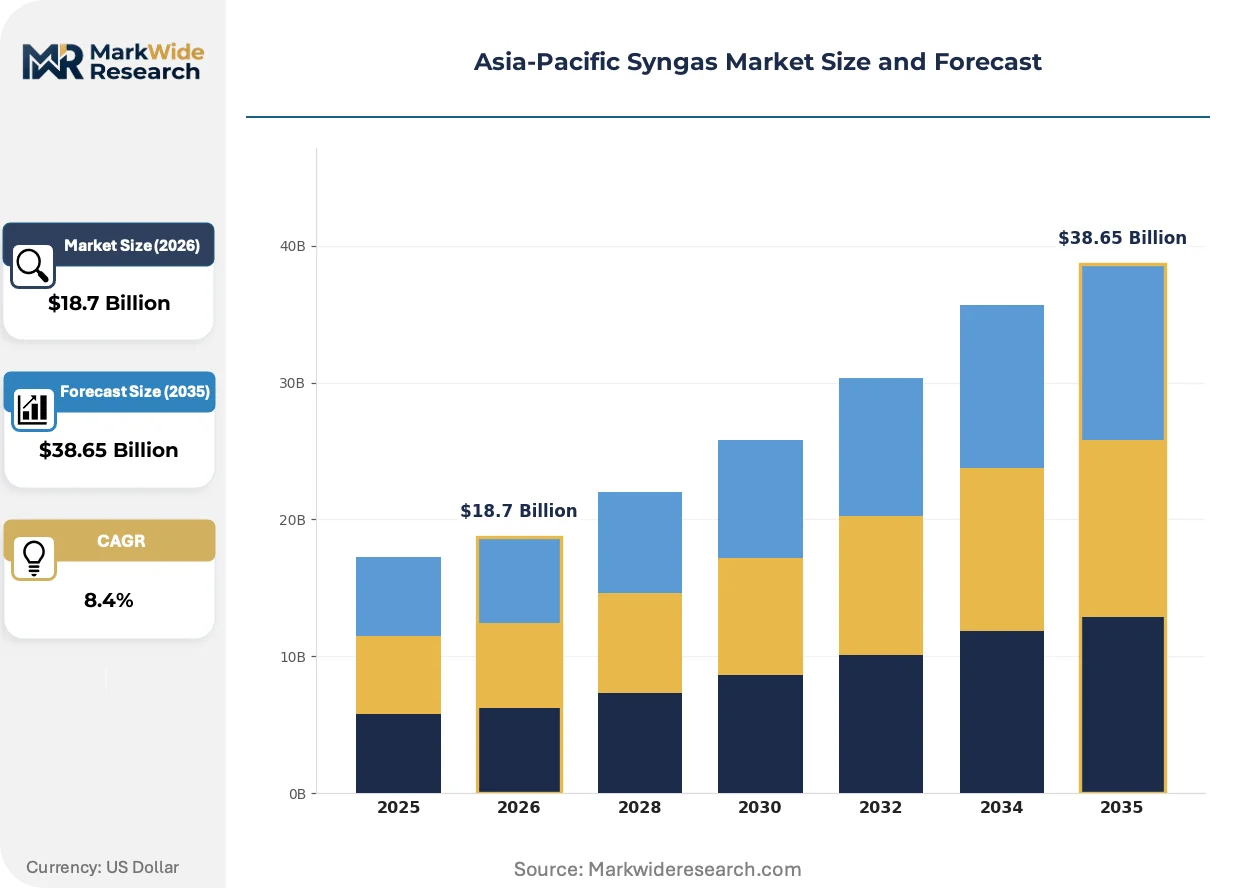
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Natural Gas, Coal, Biomass, Petroleum Coke Technology: Gasification, Reforming, Pyrolysis, Fermentation End User: Chemical Industry, Energy Sector, Metal Production, Power Generation Application: Fuel, Feedstock, Chemical Production, Electricity Generation |
| Companies Covered | Haldor Topsoe A/S, BASF SE, Air Products and Chemicals Inc., Royal Dutch Shell plc, General Electric, Linde plc, Sasol, KBR Inc., Air Liquide, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Syngas Market Strategic Shifts
Technology pathways and offtake structures across the Asia-Pacific syngas market are fragmenting along carbon intensity lines, with regulatory pressure and buyer procurement criteria diverging investment toward divergent feedstock and end-use configurations.
Biomass gasification technology is bifurcating the feedstock landscape as agricultural residue and energy crop pathways achieve technical maturity at demonstration scale. Chemical producers in Thailand and Indonesia are piloting integrated biorefinery configurations, though coal gasification retains cost advantage in baseload applications. The technology split is compressing capital allocation timelines for conventional gasification engineering.
Japan's METI feed-in tariff adjustments for clean hydrogen offtake are redirecting syngas project economics toward hydrogen export rather than domestic chemical synthesis. The policy mechanism is accelerating electrolysis and reforming technology convergence in Australian-Japanese supply partnerships. Steel and ammonia producers in Japan's Keihin and Keiyo industrial zones face the most acute feedstock sourcing recalibration.
Integrated steel complexes are consolidating syngas procurement under long-term on-site supply contracts, displacing merchant gas transactions. Engineering firms and industrial gas providers are restructuring commercial models around availability guarantees and carbon intensity specifications rather than volumetric pricing. This concentration is most visible in China's Shandong and Hebei provinces where state-backed steel groups dominate capacity expansion.
Asia-Pacific Syngas Market Segmentation
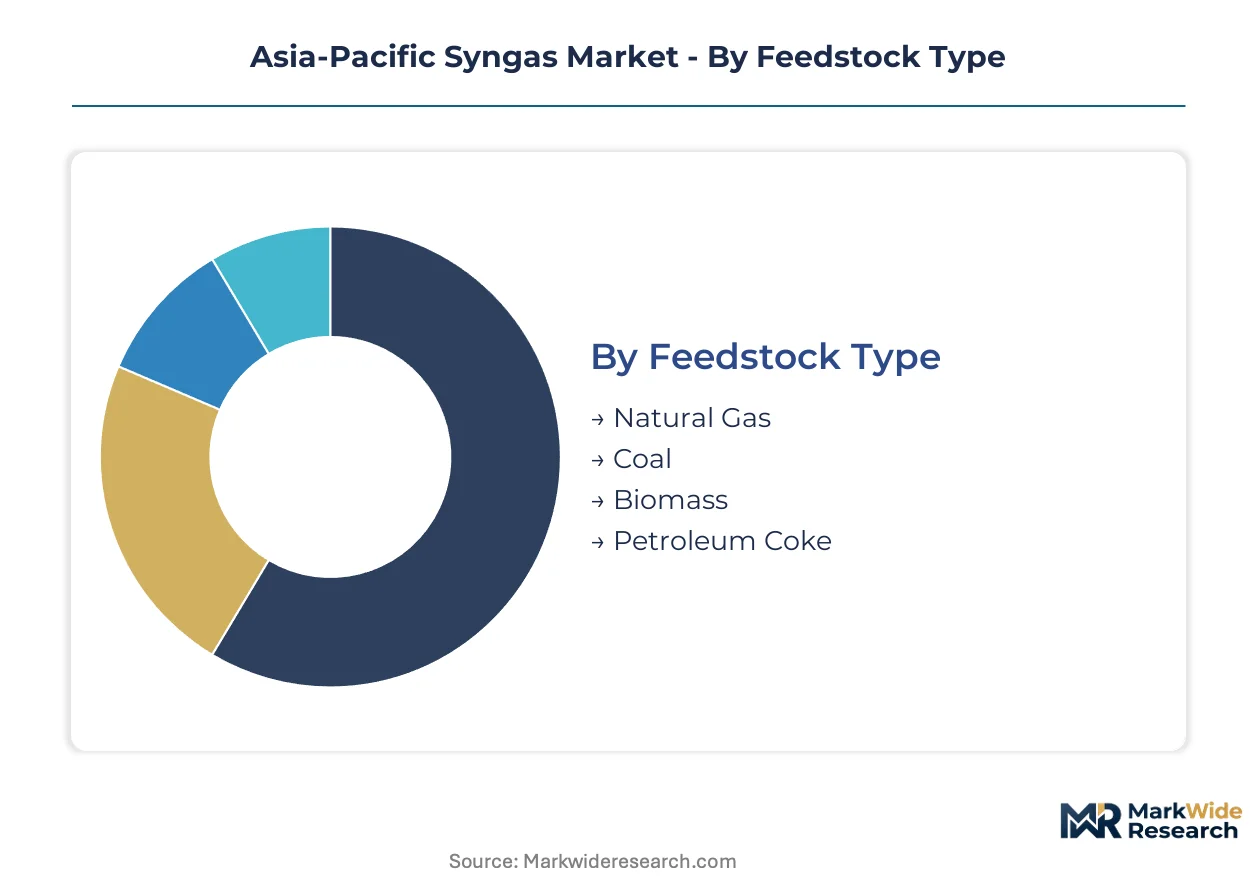
Feedstock composition and technology selection determine carbon intensity profiles and regulatory compliance trajectories for syngas producers across Asia-Pacific. Segmentation choices increasingly hinge on bilateral clean hydrogen partnerships and domestic energy security priorities rather than pure cost optimization.
Feedstock Type:
Domestic coal reserves anchor supply security for Chinese and Indian producers, while natural gas pathways serve export-oriented hydrogen corridors to Japan and South Korea. Biomass feedstocks concentrate in agricultural surplus zones of Thailand and Indonesia with emerging biorefinery integration.
- Coal:Abundant domestic reserves in Shanxi and Inner Mongolia sustain baseload gasification economics despite tightening MEE carbon intensity benchmarks. Steel and ammonia producers in eastern China's industrial clusters rely on captive coal supply for cost stability.
- Natural Gas:Steam methane reforming dominates hydrogen export projects targeting Japanese METI feed-in tariff structures. Australian gas fields supply reforming trains for bilateral clean fuel partnerships with South Korean off-takers.
- Biomass:Agricultural residue pathways in Thailand's central plains and Indonesia's palm oil regions gain commercial traction under carbon accounting rules favoring biogenic carbon cycles.
- Petroleum Coke:Refinery byproduct streams in India's Gujarat-Maharashtra corridor feed high-capacity gasification units with integrated petrochemical downstream.
Coal holds the largest share; momentum sits with biomass as carbon intensity rules tighten.
Technology:
Capital intensity and operating temperature regimes differentiate technology choices, with high-pressure gasification commanding premium engineering margins and fermentation emerging as the lowest-carbon pathway for specific feedstock combinations.
- Gasification:Entrained-flow and fluidized-bed configurations at 1,200-1,500°C process coal and petroleum coke for steel and chemical applications. China's Shandong and Hebei provinces concentrate the largest installed base of pressurized gasification trains.
- Reforming:Catalytic steam reforming of natural gas produces high-purity hydrogen for ammonia loops and export corridors. Australian-Japanese supply partnerships prioritize autothermal reforming with integrated carbon capture.
- Pyrolysis:Lower-temperature thermal decomposition of biomass yields syngas with elevated methane fractions, suiting distributed power generation in Indonesia's outer islands.
- Fermentation:Anaerobic digestion pathways convert agricultural residues to syngas with near-zero carbon intensity scores, attracting pilot investments from Thai chemical producers seeking biorefinery integration.
Gasification dominates installed capacity; fermentation gains share fastest in sustainability-weighted procurement.
End User:
Customer concentration varies by carbon exposure, with metal producers facing the steepest decarbonization mandates and chemical buyers prioritizing feedstock cost stability over emission profiles.
- Chemical Industry:Methanol and ammonia synthesis loops consume the largest syngas volumes, with Chinese coal-to-chemical complexes serving domestic fertilizer and polymer demand. MEE emission benchmarks force efficiency retrofits on aging gasification assets.
- Metal Production:Direct reduction iron processes in India and China displace blast furnace capacity using syngas-derived hydrogen. Tata Steel and Baowu Group anchor demand for high-purity reducing gas supply contracts.
- Energy Sector:Hydrogen export projects target Japanese and South Korean clean fuel procurement under bilateral supply agreements.
- Power Generation:Captive syngas-fired units in Gujarat and Maharashtra face CEA emission monitoring mandates under revised environmental clearance protocols.
Chemical Industry commands the deepest volume; Metal Production shows the steepest expansion trajectory.
Application:
Value capture potential diverges sharply, with chemical synthesis offering integrated margin pools and fuel applications constrained by commodity pricing exposure.
- Chemical Production:Methanol-to-olefins and ammonia derivative synthesis generate the highest value per unit syngas consumed. Chinese producers in Ningbo and Dalian integrate downstream polymer capacity to capture full chain margins.
- Feedstock:Intermediate syngas supply to merchant hydrogen and synthetic fuel producers serves export-oriented demand from Australian-Japanese corridors.
- Fuel:Synthetic natural gas and liquid fuel synthesis competes with conventional hydrocarbons on cost parity, limiting deployment to carbon-priced jurisdictions.
- Electricity Generation:Captive power applications in Indian industrial zones provide baseload reliability for chemical and metal complexes subject to grid instability.
Chemical Production captures the highest margins; Feedstock applications expand most quickly under clean hydrogen export economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE carbon intensity benchmarks and India's PLI scheme for clean energy are redirecting capital toward biomass gasification and hydrogen-from-syngas pathways across eastern China's industrial clusters and India's Gujarat-Maharashtra corridor.
China
Steel and ammonia producers in Shandong and Hebei provinces drive retrofit demand for high-efficiency gasification trains. MEE mandates tighten feedstock specifications and emissions thresholds simultaneously for coal-to-chemical complexes. Ningbo and Dalian industrial zones integrate downstream polymer capacity to capture full chain margins from methanol-to-olefins output.
India
Tata Steel and other metal producers scale direct reduction iron processes using syngas-derived hydrogen to displace blast furnace capacity. CEA emission monitoring mandates for captive syngas power units extend pre-construction approval cycles under revised environmental clearance protocols. Gujarat-Maharashtra corridor concentrates refinery byproduct gasification with integrated petrochemical downstream.
Japan
METI feed-in tariff adjustments for clean hydrogen offtake redirect syngas project economics toward export rather than domestic chemical synthesis. Keihin and Keiyo industrial zones face acute feedstock sourcing recalibration as steel and ammonia producers adjust procurement. Australian-Japanese supply partnerships prioritize autothermal reforming with integrated carbon capture.
Australia
Gas fields in Western Australia and Queensland supply reforming trains for bilateral clean fuel partnerships with South Korean and Japanese off-takers. Export-oriented hydrogen projects leverage natural gas steam methane reforming to meet METI procurement criteria. Technology convergence with electrolysis accelerates in supply partnerships targeting Asian clean fuel demand.
South Korea
Bilateral clean hydrogen agreements with Australia reshape offtake economics for syngas-to-hydrogen pathways. Industrial gas consumers in Ulsan and Yeosu chemical complexes negotiate long-term supply contracts with carbon intensity specifications. Domestic steel producers evaluate direct reduction iron technology licensing from European and Japanese engineering providers.
Asia-Pacific Syngas Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and on-site supply contracting. The vendor base concentrates around three strategic tiers: integrated engineering conglomerates with gasification platforms, industrial gas providers with cryogenic air separation integration, and catalytic technology licensors with proprietary reforming systems. Dominant competitive moves include engineering partnerships with state-backed energy conglomerates and restructuring commercial models around availability guarantees rather than volumetric pricing.
Within the technology licensor tier, Haldor Topsoe A/S exemplifies the catalytic reforming specialist archetype, while Linde plc and Air Products and Chemicals Inc. represent the integrated industrial gas and engineering conglomerate model. These three entities occupy positions spanning high-efficiency ammonia loops, large-scale gasification deployments, and on-site syngas supply contracts with integrated steel and chemical complexes. Their geographic footprints and organizational structures reflect divergent approaches to capital intensity and customer concentration risk across Asia-Pacific industrial clusters.
| Leading Market Players |
|---|
| Haldor Topsoe A/S |
| BASF SE |
| Air Products and Chemicals Inc. |
| Royal Dutch Shell plc |
| General Electric |
| Linde plc |
| Sasol |
| KBR Inc. |
| Air Liquide |
| Others |
Value Chain & Pricing Dynamics
ISO 14001 environmental management certification gates both supplier qualification and price differentiation for syngas technology providers across Asia-Pacific. Buyers in eastern China's industrial clusters and India's Gujarat-Maharashtra corridor weight certification status heavily in procurement decisions, compressing margins for uncertified engineering firms while rewarding premium positioning for compliant licensors.
Pricing Analysis
Certification level creates the primary spread between technology licensors, with ISO 14001-compliant providers commanding 15-25% premiums over uncertified competitors in ammonia and methanol loop contracts. Project-based licensing with royalty escalators dominates large-scale gasification deployments, while smaller biomass units favor fixed engineering fees. Pricing pressure intensifies in coal-to-chemical segments as China's MEE carbon intensity benchmarks force retrofit investments that erode buyer willingness to pay. Merchant gas buyers in steel and power applications exhibit highest price sensitivity; integrated chemical complexes with captive syngas show lowest sensitivity due to downstream margin capture.
Supply Chain Analysis
China and India anchor refractory and catalyst manufacturing for high-temperature gasification trains, while Germany and Japan supply precision engineering for cryogenic air separation units. Australian natural gas fields feed reforming trains for hydrogen export corridors to Japan and South Korea. Supply chain risk concentrates in oxygen supply bottlenecks, with cryogenic air separation capacity controlled by a limited set of industrial gas providers. Distribution runs through long-term on-site supply contracts with integrated steel and chemical complexes, displacing merchant gas transactions in China's Shandong and Hebei provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering capability for 1,000°C-plus operating environments constrains project execution velocity across Asia-Pacific syngas deployments. Refractory specialists and catalytic reforming platform providers face acute scarcity, compressing timelines for technology licensing and retrofit commissioning.
For Market Incumbents: Shield proprietary reforming platforms through accelerated patent filing in Australian-Japanese hydrogen corridors. Deepen backward integration into refractory manufacturing to reduce dependency on concentrated specialist suppliers. China's MEE retrofit mandates create defensive moats for incumbents with certified high-efficiency gasification trains.
For New Entrants and Emerging Players: Lead with biomass gasification configurations targeting Thailand's central plains and Indonesia's palm oil regions where agricultural residue feedstocks achieve carbon accounting parity. White-space opportunity concentrates in distributed power applications for Indonesia's outer islands, where lower-temperature pyrolysis pathways suit methane-rich syngas output. Partner with Thai chemical producers seeking biorefinery integration to bypass incumbent engineering procurement relationships.
For Investors and Strategic Acquirers: China's dual carbon goals enforcement reshapes the acquisition landscape toward hydrogen-from-syngas technology licensors with integrated carbon capture capabilities. Target reforming platform providers serving Australian-Japanese bilateral supply partnerships. Monitor Japan's METI feed-in tariff adjustments as the signal for clean hydrogen offtake economics inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Haldor Topsoe's catalytic reforming platforms capture premium positioning in ammonia loops serving India's PLI clean energy scheme. |
| Backward Integration into Catalyst Manufacturing | Refractory specialists reduce supply risk for 1,200°C gasification trains in China's Shandong province. |
| Long-term On-site Supply Contract | Air Products anchors steel complex relationships in Hebei through availability guarantees replacing volumetric pricing. |
| Biomass Gasification Scale-up | Thai chemical producers pilot integrated biorefinery configurations under tightening carbon intensity rules. |
| Carbon Capture Integration | Australian-Japanese supply partnerships prioritize autothermal reforming with capture to meet METI procurement criteria. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs data, SEC filings from listed engineering conglomerates, and MEE emission benchmark disclosures. Interviews with gasification plant managers, cryogenic air separation procurement leads at steel complexes, catalytic technology R&D directors, and EPC contractors in eastern China and Gujarat inform demand-side validation. Bottom-up capacity assessments triangulate against top-down chemical production forecasts across the analysis window.
Segmentation dimensions modeled include feedstock type, gasification technology temperature regime, end-use industry carbon exposure, and regional regulatory framework stringency. CAGRs derive from production capacity buildout timelines, retrofit investment cycles, and bilateral hydrogen offtake agreement trajectories. Forecast inputs incorporate China's MEE carbon intensity benchmark compliance schedules and India's CEA environmental clearance protocol revisions.
Forecasts assume regulatory continuity in China's MEE enforcement and India's PLI scheme implementation; material policy shifts would require re-modeling. Commodity price volatility in thermal coal and natural gas, plus carbon capture technology maturity delays, constitute primary revision risks. Recalibration cycles align with material shifts in bilateral clean hydrogen partnership structures and MEE benchmark tightening announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
Europe Syngas Market
Industrial Gases
Noble Gas Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Fluorocarbon Gases Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
North America Syngas Market
Industrial Gases
Food-Grade Gases Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
South-East Asia (SEA) Syngas Market