
 High Purity Methane Gas Market | 2026-2036
High Purity Methane Gas Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Methane Gas Market Outlook
Long-term gas supply contracts with embedded maintenance and purity certification services is consolidating vendor-customer relationships across the electronics supply chain. Air Liquide S.A. leverages its global cylinder fleet and on-site gas generation footprint to anchor premium contracts with leading foundries. Linde plc sustains competitive positioning through backward integration into methane purification and regional air separation assets. Taiyo Nippon Sanso Corporation specializes in ultra high purity packaging protocols that meet Japanese semiconductor fabs.
High purity methane gas denotes CH4 refined to concentrations typically exceeding 99.999% with controlled limits on oxygen, moisture, and hydrocarbon impurities, produced via cryogenic distillation or pressure swing adsorption followed by catalytic purification. Its primary commercial purpose centers on serving as a process gas and carbon precursor in chemical vapor deposition, annealing atmospheres, and fuel cell membrane testing where trace contaminants would degrade performance. Ultra high purity grades command the deepest margin pools as semiconductor node shrinks tighten impurity tolerances below parts-per-billion thresholds. Electronics manufacturing applications represent the fastest-expanding demand segment as advanced packaging and gate-all-around transistor architectures proliferate. Direct sales channels dominate high-volume contracts while distributors occupy fragmented laboratory and academic procurement.
The EPA enforces emissions tracking and feedstock provenance rules that shape methane sourcing for US-based purification facilities. REACH and the EU Green Deal impose carbon intensity disclosures on imported industrial gases entering European semiconductor fabs. China's SAMR administers GB standards that certify purity grades for domestic electronics manufacturing. Buyers must monitor how tightening Scope 3 emissions accounting will reshape supplier qualification criteria and contract structures.
Market Dynamics
Semiconductor node shrinks below 3nm are multiplying EUV lithography steps at foundries across East Asia, forcing gas suppliers to certify methane batches at parts-per-billion impurity thresholds that legacy purification infrastructure cannot reliably hit.
Growth Catalysts
- Gate-all-around transistor architectures:Samsung and TSMC process migrations are consuming 40% more carbon precursor gas per wafer than FinFET predecessors, tightening volume commitments with purification vendors.
- EU Green Deal carbon intensity disclosures:REACH amendments now mandate Scope 3 tracking for industrial gases entering European semiconductor fabs, advantaging suppliers with certified low-emission feedstock chains.
- South Korea's K-Semiconductor Belt:Government-backed cluster development in Yongin and Pyeongtaek is aggregating demand from six simultaneous fab construction projects, creating anchor contracts for on-site methane generation systems.
Market Restraints
- Biogenic feedstock cost volatility:Renewable natural gas premiums swing with agricultural commodity cycles, compressing margins for purification facilities dependent on landfill and dairy digester supply.
- Cryogenic distillation energy intensity:Achieving 6N purity requires liquefaction temperatures below -160°C, locking operators into natural-gas-linked electricity exposure in deregulated grids like Texas and Germany.
- Substitution by synthetic methane:Power-to-gas electrolysis projects in Denmark and the Netherlands are piloting fossil-free CH4 that could bypass conventional purification entirely for carbon-neutral fab claims.
Strategic Opportunities
- India's semiconductor subsidy schemes:PLI incentives and state-level fab commitments in Gujarat and Tamil Nadu are creating first-mover openings for gas suppliers before domestic purification capacity matures.
- Packaging-driven demand dispersion:Advanced packaging facilities in Malaysia and Vietnam are fragmenting procurement authority away from captive foundry gas systems, opening distributor channels previously locked by volume contracts.
- On-site generation technology convergence:Integration of small-scale steam methane reforming with pressure swing adsorption is enabling fab-adjacent production that eliminates cylinder logistics and contamination risk from transport.
Industry Challenges
- Ultra high purity certification timelines:SEMI standards and customer-specific particle-count protocols require 18-24 month qualification cycles that delay revenue recognition on new purification assets.
- Specialized technician scarcity:Cryogenic systems maintenance and gas chromatography calibration demand skills concentrated at Air Liquide and Linde training centers, constraining independent operator expansion.
- Legacy cylinder fleet integration:Transitioning foundries from batch delivery to pipeline supply requires coordinated decommissioning of established handling protocols without disrupting production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Methane Gas Market |
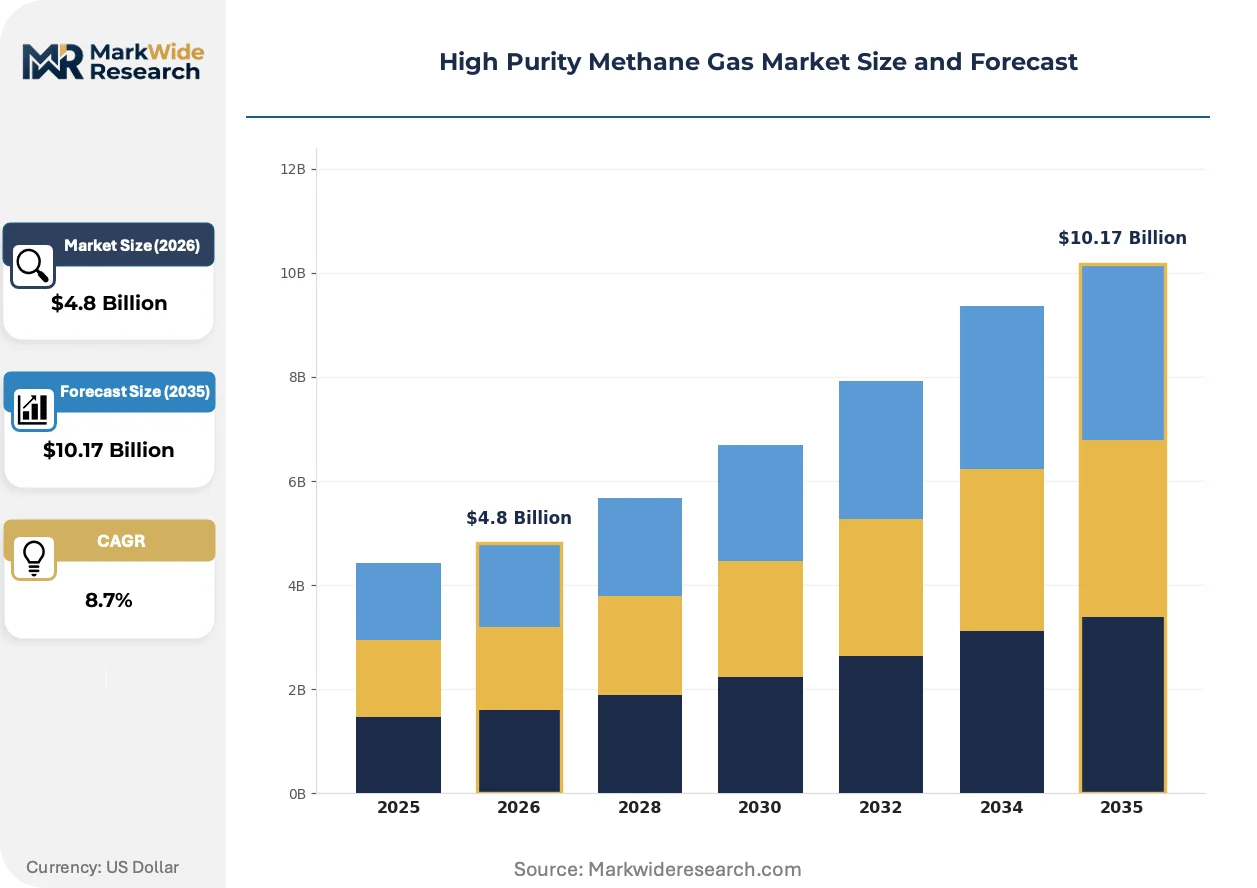
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Ultra High Purity, Industrial Grade, Laboratory Grade Application: Research, Electronics Manufacturing, Chemical Processing, Fuel Cell End User: Academic Institutions, Semiconductor Industry, Energy Sector, Labs Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Air Liquide S.A., Linde plc, Air Products and Chemicals Inc., Taiyo Nippon Sanso Corporation, Messer Group GmbH, Osaka Gas Liquid Co., Ltd., Matheson Tri-Gas, Inc., Sumitomo Seika Chemicals Company, Ltd., Advanced Specialty Gases, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Methane Gas Market Strategic Shifts
Catalytic purification systems are overtaking traditional cryogenic distillation as the dominant methane refinement pathway, compressing capital requirements and enabling modular deployment at fab-adjacent sites.
Membrane-based impurity rejection is overtaking pressure swing adsorption for moisture and oxygen removal in new installations. TSMC and Intel packaging facilities in Taiwan and Arizona are specifying membrane skids for their smaller footprint and faster startup cycles. This technology is overtaking legacy PSA units in brownfield expansions where cryogenic infrastructure cannot be retrofitted.
EPA emissions tracking rules are tightening feedstock provenance documentation for methane entering US-based purification facilities. The agency's Greenhouse Gas Reporting Program now requires facility-level disclosure of natural gas supplier carbon intensities, pushing buyers toward certified low-leakage pipeline networks and away from spot-market purchases. Semiconductor fabs in Oregon and Texas are responding by embedding emissions clauses into multi-year supply agreements.
Long-term take-or-pay contracts with embedded purity certification services are displacing spot cylinder purchases at research laboratories and smaller packaging houses. Distributors serving the academic and MEMS segments are unbundling gas delivery from analytical support, selling subscription-based chromatography verification that locks in recurring revenue. This pattern is most visible in Germany's Fraunhofer institute network and Japan's national university cleanroom consortiums.
High Purity Methane Gas Market Segmentation
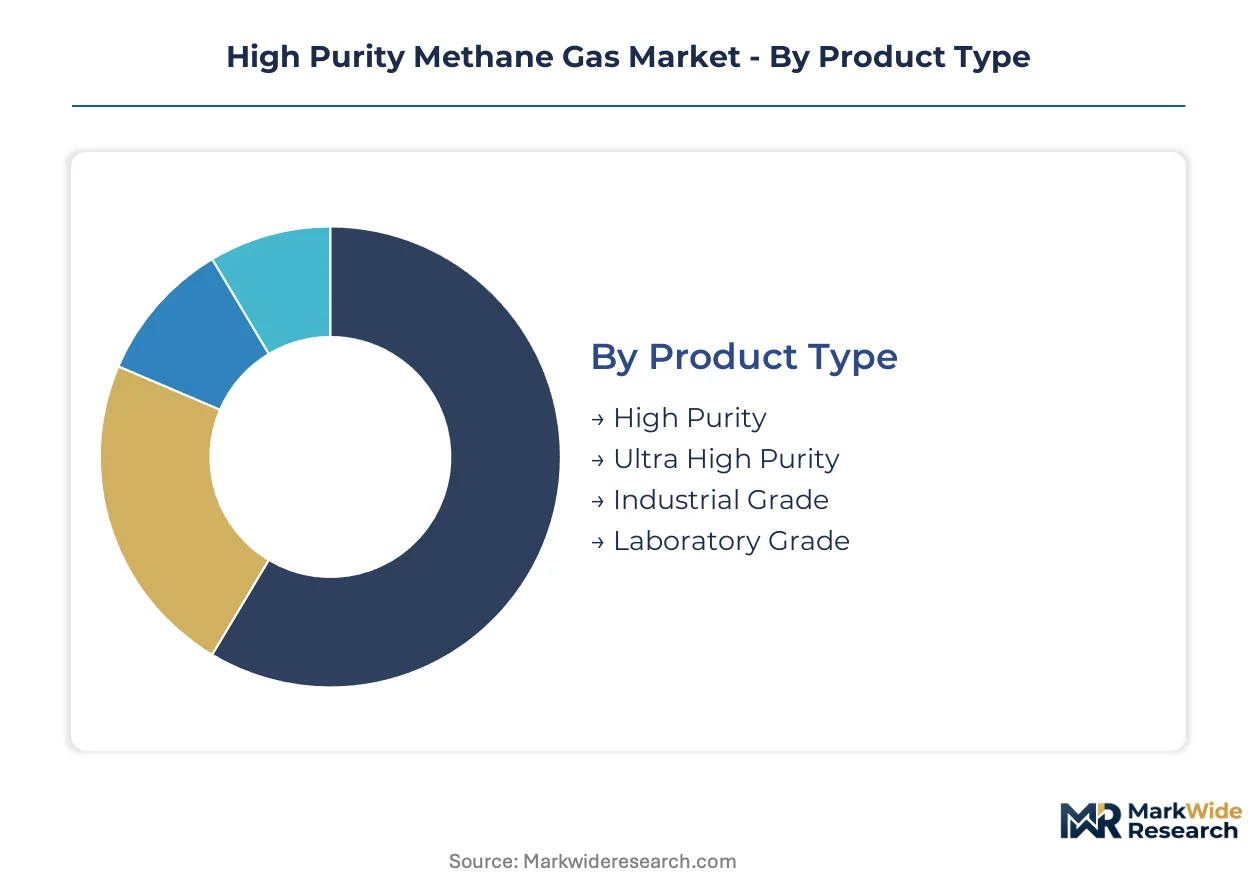
Segmentation in high purity methane gas separates volume-driven industrial procurement from precision-critical electronics applications where impurity thresholds differ by orders of magnitude. Purity grades, end-use specifications, and delivery mechanisms each reshape supplier economics and contract structures differently.
Product Type:
Ultra high purity commands premium pricing multiples while industrial grade moves through commodity-style volume contracts.
- Ultra High Purity:CH4 refined to 99.9999% (6N) or higher with sub-ppb limits on oxygen, moisture, and hydrocarbon contaminants. EUV lithography steps at TSMC and Samsung foundries in Taiwan and South Korea now mandate this grade for carbon precursor applications where trace impurities destroy wafer yields.
- High Purity:Typically 99.999% (5N) purity suitable for chemical vapor deposition and annealing atmospheres in mature semiconductor nodes. Legacy FinFET fabs in Japan and the United States continue bulk procurement of this grade as gate-all-around transitions lag at older facilities.
- Industrial Grade:Standard purity methane serving fuel cell membrane testing and non-critical chemical synthesis where 99.9% thresholds suffice.
- Laboratory Grade:Variable purity specifications tailored to academic research protocols and analytical instrument calibration with flexible certification requirements.
Today's leader: Ultra High Purity. Tomorrow's challenger: Laboratory Grade as research applications fragment procurement authority.
Application:
Electronics manufacturing concentrates revenue while fuel cell applications expand most quickly across hydrogen economy pilots.
- Electronics Manufacturing:Dominant demand segment encompassing chemical vapor deposition, atomic layer deposition, and EUV lithography carbon precursor steps. South Korea's K-Semiconductor Belt in Yongin and Pyeongtaek is aggregating six simultaneous fab construction projects that anchor multi-year methane supply contracts.
- Fuel Cell:Membrane electrode assembly testing and hydrogen carrier research at DOE-funded facilities in California and NEDO-sponsored pilots in Japan. Power-to-gas electrolysis projects in Denmark and the Netherlands are piloting synthetic methane that could bypass conventional purification for carbon-neutral claims.
- Chemical Processing:Methane as feedstock for hydrogen production and synthetic hydrocarbon synthesis at petrochemical complexes.
- Research:Academic and national laboratory procurement for combustion studies, atmospheric chemistry, and materials science requiring certified reference materials.
Electronics manufacturing anchors current revenue. Fuel cell applications are climbing the fastest as hydrogen infrastructure scales.
End User:
Semiconductor fabs drive contract consolidation while academic institutions fragment procurement across distributor networks.
- Semiconductor Industry:Foundries and integrated device manufacturers specifying ultra high purity methane with embedded certification services. Intel's Arizona packaging facilities and TSMC's Taiwan fabs are transitioning from cylinder delivery to on-site generation systems that eliminate transport contamination risk.
- Academic Institutions:Fragmented demand across university cleanrooms and national laboratory facilities. Germany's Fraunhofer institute network and Japan's national university consortiums are unbundling gas delivery from analytical support through subscription-based chromatography verification.
- Energy Sector:Fuel cell developers and hydrogen infrastructure operators procuring industrial and high purity grades for membrane testing.
- Labs:Independent research facilities and contract analytical services with variable volume requirements and flexible purity specifications.
Semiconductor industry concentration is forcing supplier qualification consolidation. Academic institutions are gaining share fastest as research funding diversifies.
Distribution Channel:
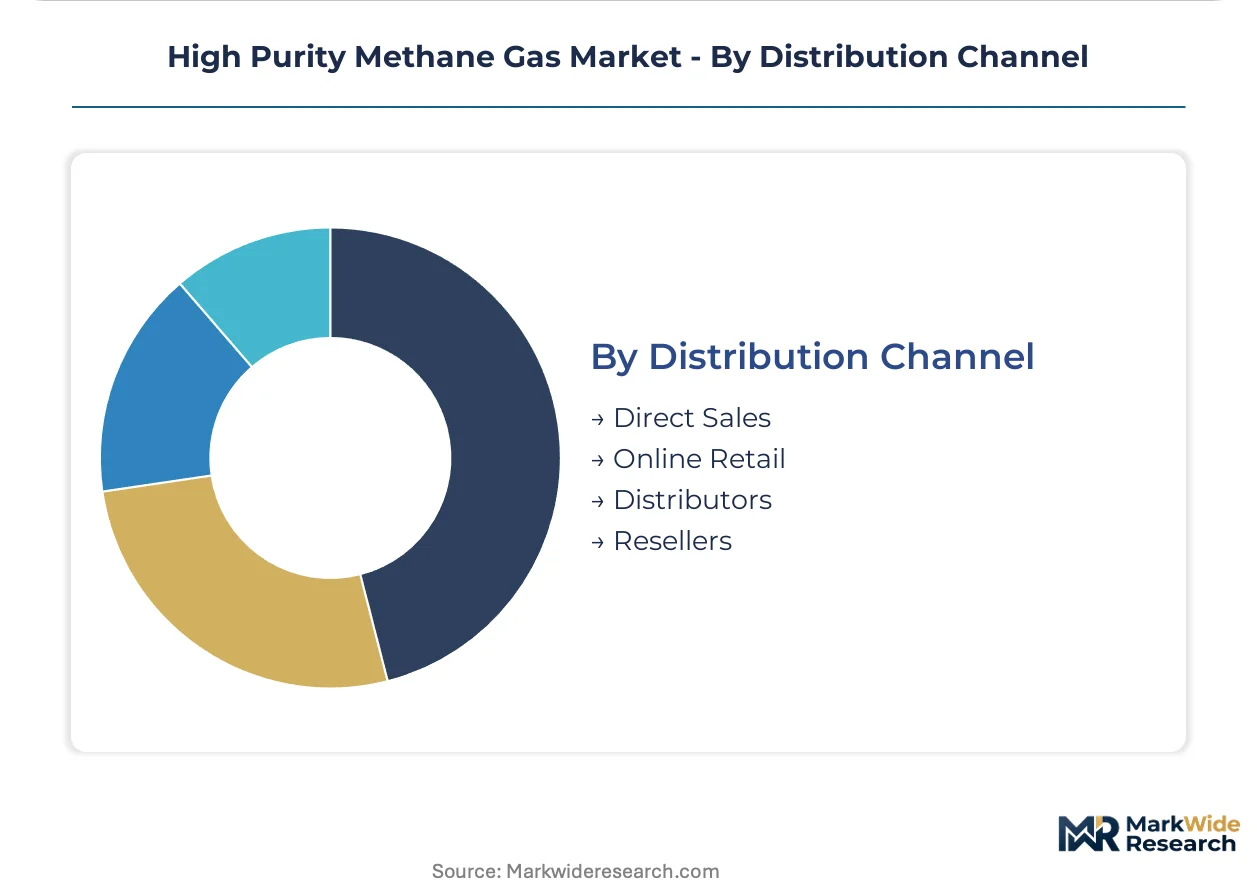
Direct sales capture high-volume contracts while distributor channels penetrate fragmented laboratory and emerging market segments.
- Direct Sales:Long-term take-or-pay agreements with embedded maintenance and purity certification services. Air Liquide and Linde anchor premium contracts with leading foundries through global cylinder fleets and on-site gas generation footprints.
- Distributors:Regional gas specialists serving academic, MEMS, and packaging house segments previously locked by volume contracts. Advanced packaging facilities in Malaysia and Vietnam are fragmenting procurement authority away from captive foundry systems.
- Online Retail:E-commerce platforms for small-volume laboratory procurement with standardized certification documentation.
- Resellers:Secondary market actors repackaging bulk purchases for geographic or application-specific niches with limited value-added services.
Direct sales dominate contract value. Distributors are expanding most quickly as packaging demand disperses across Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's K-Semiconductor Belt is aggregating six simultaneous fab construction projects while Taiwan's foundry expansion concentrates EUV lithography demand. Germany's chemical industry clusters anchor European purification capacity. The United States and Japan maintain divergent regulatory frameworks that reshape supplier qualification timelines.
United States
Intel's Arizona packaging facilities and Oregon fabs are transitioning from cylinder delivery to on-site methane generation systems. The EPA's Greenhouse Gas Reporting Program mandates facility-level disclosure of natural gas supplier carbon intensities. Texas and Oregon semiconductor corridors are embedding emissions clauses into multi-year supply agreements.
South Korea
Samsung and SK Hynix process migrations are consuming elevated carbon precursor gas volumes per wafer. The government's K-Semiconductor Belt initiative in Yongin and Pyeongtaek is aggregating demand from simultaneous fab construction. Pyeongtaek's cluster development is creating anchor contracts for on-site methane generation systems.
Taiwan
TSMC's advanced node shrinks below 3nm are multiplying EUV lithography steps and tightening impurity tolerances. The island's industrial regulator enforces purity certification aligned with SEMI standards. Hsinchu Science Park and Tainan fab complexes are certifying methane batches at parts-per-billion thresholds.
Germany
REACH amendments mandate Scope 3 tracking for industrial gases entering European semiconductor fabs. The country's chemicals regulator enforces carbon intensity disclosures under EU Green Deal frameworks. Dresden's Silicon Saxony cluster and Bavarian fab-adjacent facilities are qualifying suppliers with certified low-emission feedstock chains.
Japan
Tokyo Electron and Shin-Etsu supply chain requirements are propagating ultra high purity specifications through domestic gas distributors. METI administers JIS standards that certify purity grades for electronics manufacturing. Kyushu's Kumamoto and Hiroshima prefecture fab complexes are maintaining bulk procurement of 5N purity grades.
High Purity Methane Gas Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with industrial gas majors commanding premium electronics contracts and regional distributors penetrating fragmented laboratory procurement. The market structure consolidates around three to four global operators with captive purification infrastructure while specialist packaging houses occupy niche certification services. Strategic archetypes include integrated gas majors with cylinder fleet networks, regional specialists with fab-adjacent generation assets, and technology licensors with modular purification systems. Competitive dynamics center on backward integration into methane feedstock sourcing and geographic expansion through on-site generation partnerships.
Within the integrated gas major tier, Air Liquide S.A., Linde plc, and Taiyo Nippon Sanso Corporation occupy positions that exemplify divergent strategic emphases. Air Liquide S.A. represents the archetype of global cylinder fleet leverage and premium contract anchoring. Linde plc exemplifies backward integration into methane purification and regional air separation asset control. Taiyo Nippon Sanso Corporation sits within the specialized packaging protocols segment serving Japanese semiconductor fabs. These three entities collectively illustrate how geographic origin and corporate structure shape competitive positioning without converging on identical capability bundles.
| Leading Market Players |
|---|
| Air Liquide S.A. |
| Linde plc |
| Air Products and Chemicals Inc. |
| Taiyo Nippon Sanso Corporation |
| Messer Group GmbH |
| Osaka Gas Liquid Co., Ltd. |
| Matheson Tri-Gas, Inc. |
| Sumitomo Seika Chemicals Company, Ltd. |
| Advanced Specialty Gases |
| Others |
Value Chain & Pricing Dynamics
Cryogenic distillation energy costs cascade from natural-gas-linked electricity tariffs through three distinct pricing tiers for ultra high purity, high purity, and industrial grade methane. South Korean and Taiwanese foundries absorb premium markups for 6N certification while academic laboratories in Germany and Japan negotiate subscription-based chromatography verification that unbundles gas delivery from analytical support.
Pricing Analysis
Capacity additions in South Korea's K-Semiconductor Belt are reshaping price floors for ultra high purity methane as six simultaneous fab projects anchor long-term take-or-pay contracts. Three-tier pricing structure across premium, standard, and economy levels separates EUV lithography-grade 6N methane from legacy 5N FinFET applications and industrial fuel cell testing grades. Price differentiation hinges on certification timeline intensity—18-24 month SEMI qualification cycles lock in vendor switching costs that protect incumbent margins. Cost compression in laboratory-grade segments is intensifying because distributors fragment procurement authority across Fraunhofer institutes and Japanese national university consortiums. Academic institutions exhibit highest price sensitivity due to unbundled service models, while TSMC and Samsung fabs demonstrate lowest sensitivity given yield-loss risks from impurity thresholds.
Supply Chain Analysis
China's SAMR-administered GB standards and South Korea's domestic-content preferences for K-Semiconductor Belt projects are reshaping sourcing patterns for methane feedstock and purification equipment. Supply concentrates in the United States, South Korea, and Taiwan for electronics-grade methane, with Germany and Japan anchoring European and Asian laboratory distribution hubs. Raw material dependencies draw from certified low-leakage pipeline networks, renewable natural gas from agricultural digesters, and synthetic methane from Danish power-to-gas pilots. Single-source vulnerability runs through cryogenic equipment manufacturers concentrated at Air Liquide and Linde training centers. Distribution runs through direct sales channels for high-volume foundry contracts while regional distributors penetrate fragmented packaging facilities in Malaysia and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where gate-all-around transistor architectures and sub-3nm EUV lithography steps force specification upgrades that commoditized purification infrastructure cannot satisfy.
For Market Incumbents: Hedge against synthetic methane substitution by securing certified low-emission feedstock chains that satisfy EU Green Deal Scope 3 disclosures before power-to-gas electrolysis scales. Anchor premium positioning through backward integration into methane purification assets in Texas and Oregon semiconductor corridors, countering margin pressure from biogenic feedstock cost volatility linked to agricultural commodity cycles. For New Entrants and Emerging Players: Enter via India's PLI-subsidized fab commitments in Gujarat and Tamil Nadu before domestic purification capacity matures, capturing first-mover positioning in on-site generation system deployment. Target academic and MEMS segments in Southeast Asian packaging facilities where procurement authority fragments away from captive foundry gas systems, penetrating distributor channels previously locked by volume contracts through membrane-based purification skids with faster startup cycles. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with fab-adjacent generation assets because qualification timeline intensity—18-24 month SEMI certification cycles—creates defensive moats that deter new purification infrastructure investment. Target acquisition candidates with captive cylinder fleet networks and embedded maintenance contracts serving Japanese semiconductor fabs. Monitor synthetic methane pilot project scale-up in Denmark and the Netherlands as inflection indicator for carbon-neutral fab claims that could bypass conventional purification entirely.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methane Purification | Air Liquide and Linde secure feedstock control against biogenic cost volatility in Texas and Germany. |
| On-Site Generation System Deployment | TSMC and Intel packaging facilities eliminate transport contamination risk through fab-adjacent steam methane reforming. |
| Membrane-Based Purification Technology Adoption | TSMC and Intel specify membrane skids for moisture and oxygen removal with smaller footprint than legacy PSA units. |
| Long-Term Take-or-Pay Contract Structuring | South Korea's K-Semiconductor Belt anchors six simultaneous fab projects with embedded purity certification services. |
| Certified Low-Emission Feedstock Chain Development | REACH amendments and EPA Greenhouse Gas Reporting Program mandate Scope 3 tracking for European and US semiconductor fabs. |
Study Parameters
Direct dialogue with gas supply procurement managers at foundries, cryogenic systems technicians, SEMI standards committee members, and distributor channel heads grounded qualitative insights in operational reality. Secondary validation drew from EPA Greenhouse Gas Reporting Program disclosures, EU ETS emissions data, SAMR GB standard filings, and SEC 10-K filings from industrial gas majors. Bottom-up and top-down triangulation reconciled facility-level capacity announcements with regional demand aggregation models.
Segmented outputs across purity grades, end-use applications, and distribution channels fed into analytical framework spanning the projection horizon. Modeled dimensions included electronics manufacturing versus fuel cell demand splits, direct sales versus distributor channel penetration, and regional regulatory cluster differentiation. CAGRs derived from capacity-expansion timelines, node-shrink roadmaps, and feedstock cost trajectory assumptions. Industry-specific inputs encompassed EUV lithography step multiplication rates and gate-all-around transistor architecture adoption curves.
Inputs from foundry procurement disclosures and national regulator filings were available through the study window; gaps in real-time synthetic methane pilot production data introduce uncertainty bands around carbon-neutral substitution scenarios. Forecasts reflect documented assumptions regarding semiconductor node transition timelines and biogenic feedstock premium volatility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Neon Gas Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Noble Gas Market
Industrial Gases
Global Helium Gas Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
Argon Gas Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Gas Purifiers Market
Industrial Gases
Middle-East and Africa Syngas Market