
 Europe Syngas Market | 2026-2036
Europe Syngas Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Syngas Market Foresight
High-purity syngas specifications for blue and green hydrogen pathways is rotating capital toward advanced reforming and gasification assets. Haldor Topsoe A/S sustains technology leadership through its proprietary autothermal reforming catalysts deployed across North Sea hydrogen corridors. Linde plc anchors industrial gas infrastructure with large-scale syngas separation and carbon capture integration at Antwerp-Rotterdam chemical clusters. Air Liquide competes through electrolysis-to-syngas pilot installations tied to French nuclear-powered hydrogen ambitions.
Syngas is a manufactured fuel gas mixture dominated by hydrogen and carbon monoxide, produced through steam methane reforming, partial oxidation, or biomass gasification at operating temperatures typically exceeding 800°C, serving as an intermediate feedstock for chemicals, fuels, and hydrogen production. Steam methane reforming still occupies the dominant production technology position due to established infrastructure and cost structure, though biomass gasification is accelerating fastest as forestry residues and agricultural waste streams achieve scale under EU carbon accounting rules. Hydrogen production applications command expanding margin pools as offtake agreements from ammonia manufacturing and fuel cells harden, while Fischer-Tropsch synthesis for synthetic fuels remains capital-intensive with longer payback horizons.
The EU Green Deal and REPowerEU framework are channeling subsidy eligibility toward low-carbon syngas pathways, while ECHA REACH compliance governs catalyst chemistry and process safety standards across member state installations. Germany's KBA and national hydrogen regulator enforce transport-sector purity benchmarks that cascade back to syngas specification requirements. Stakeholders must track how EU Carbon Border Adjustment Mechanism implementation reshapes import competitiveness for syngas-derived chemicals against Middle Eastern and North American supply.
Market Dynamics
The EU Green Deal and REPowerEU framework are redirecting capital flows from conventional steam methane reforming toward biomass gasification and electrolysis-based syngas production, restructuring feedstock economics across chemical clusters.
Growth Catalysts
- REPowerEU hydrogen hub investments:Germany, the Netherlands, and France are channeling public capital into industrial cluster reconfigurations that harden offtake demand for low-carbon syngas.
- Chemicals manufacturing decarbonization:European ammonia and methanol producers are substituting naphtha and coal feedstocks with syngas to meet EU Carbon Border Adjustment Mechanism compliance thresholds.
- Biomass gasification scale-up:Forestry residues and agricultural waste streams are achieving commercial scale under EU carbon accounting rules that credit biogenic CO2 emissions.
Market Restraints
- Natural gas price volatility:Steam methane reforming economics remain tethered to TTF and NBP benchmark fluctuations that compress margin predictability for unhedged producers.
- Electrolyzer supply concentration:PEM and alkaline electrolyzer manufacturing capacity concentrates in China, creating import dependency risks for European green hydrogen-to-syngas projects.
- CCS infrastructure gaps:Carbon capture and storage deployment lags behind blue hydrogen pathway announcements, delaying bankability of autothermal reforming with carbon capture.
Strategic Opportunities
- Eastern European industrial retrofits:Poland and Czechia maintain legacy coal gasification assets suitable for biomass co-feeding or hydrogen blending upgrades.
- E-fuels offtake contracts:Aviation and maritime fuel mandates under ReFuelEU Aviation and FuelEU Maritime are creating long-term purchase agreements for Fischer-Tropsch synthetic fuels.
- Nuclear-powered electrolysis:France's 56-reactor fleet offers baseload electricity for high-capacity-factor syngas production via solid oxide electrolysis cell integration.
Industry Challenges
- High-temperature process engineering talent:Gasifier operation and catalyst management expertise pools narrowly in legacy petrochemical regions, constraining project staffing timelines.
- REACH compliance complexity:ECHA registration requirements for novel catalyst chemistries extend commercialization timelines by 18-36 months for reforming technology developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Syngas Market |
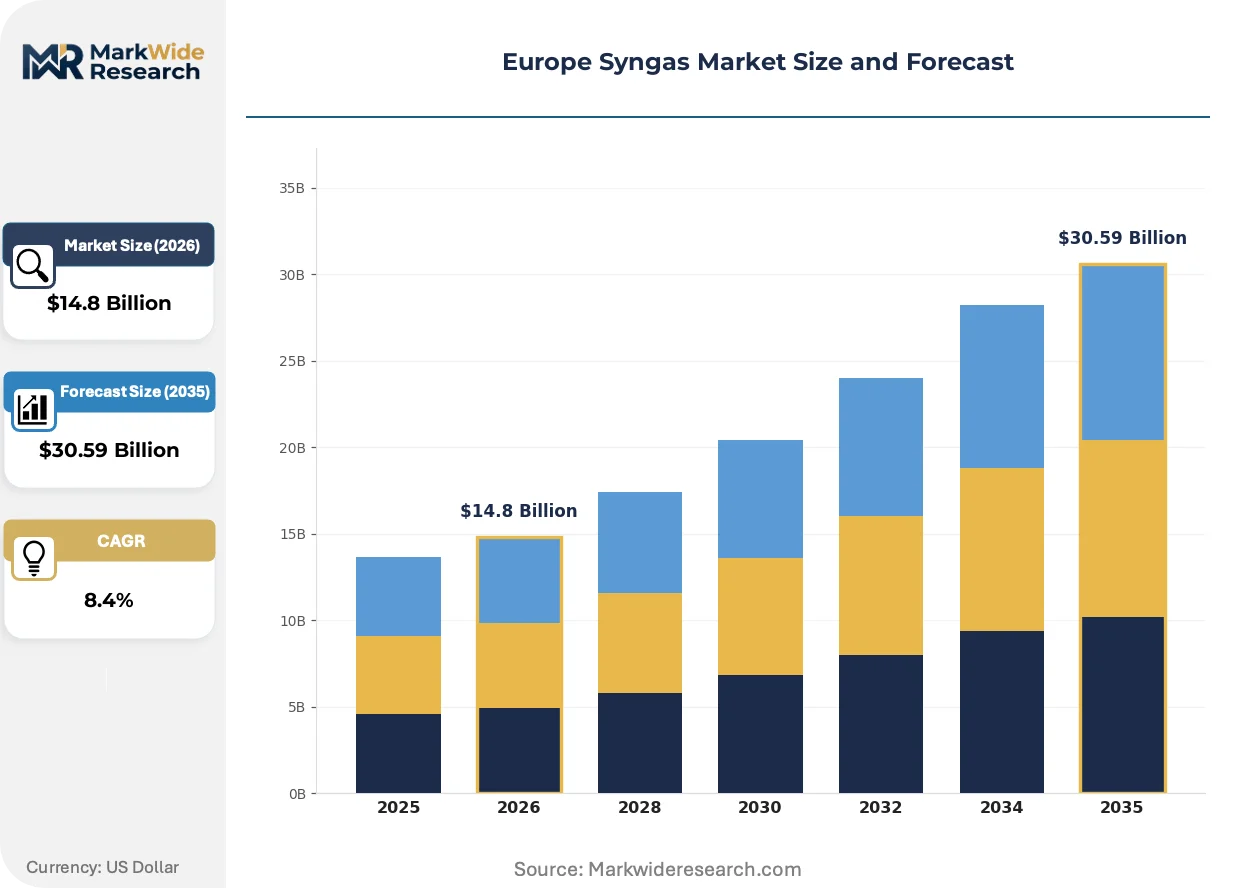
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Technology: Steam Methane Reforming, Partial Oxidation, Autothermal Reforming, Biomass Gasification, Electrolysis Feedstock Type: Natural Gas, Coal, Biomass, Waste, Light Hydrocarbons End Use Industry: Chemicals Manufacturing, Metal Processing, Fertilizer Production, Fuel Cells, Power Generation Application: Synthesis Gas for Fischer-Tropsch, Hydrogen Production, Methanol Synthesis, Ammonia Manufacturing, Renewable Energy |
| Companies Covered | Technip Energies NV, Royal Dutch Shell, Air Products and Chemicals, Inc., Haldor Topsoe A/S, Sasol Limited, Linde plc, Maire Tecnimont SpA, KBR Inc., Air Liquide, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Syngas Market Shifts & Advancements
Modular gasification systems and solid oxide electrolysis are compressing plant footprints while EU regulatory tightening on carbon intensity is forcing technology substitution decisions at existing chemical complexes.
Solid oxide electrolysis cell technology is miniaturizing through stack architecture improvements that reduce thermal cycling degradation. Chemical producers in the Antwerp-Rotterdam cluster are piloting 10-50 MW units for on-site syngas generation. This downsizing is enabling distributed production models that bypass pipeline infrastructure constraints.
EU Carbon Border Adjustment Mechanism implementation is reshaping import competitiveness for ammonia and methanol derivatives. Middle Eastern producers with lower carbon intensity scores are securing preferential access to EU chemical markets. German and Dutch offtakers are now requiring certified low-carbon syngas feedstock documentation for contract renewals.
Power purchase agreement structures are displacing traditional utility-offtake models for electrolysis-based syngas projects. Developers in Spain and Portugal are contracting directly with renewable asset owners to secure 15-20 year fixed-price electricity. This contractual innovation is concentrating project development in Iberian solar and wind corridors with the strongest resource profiles.
Europe Syngas Market Segmentation
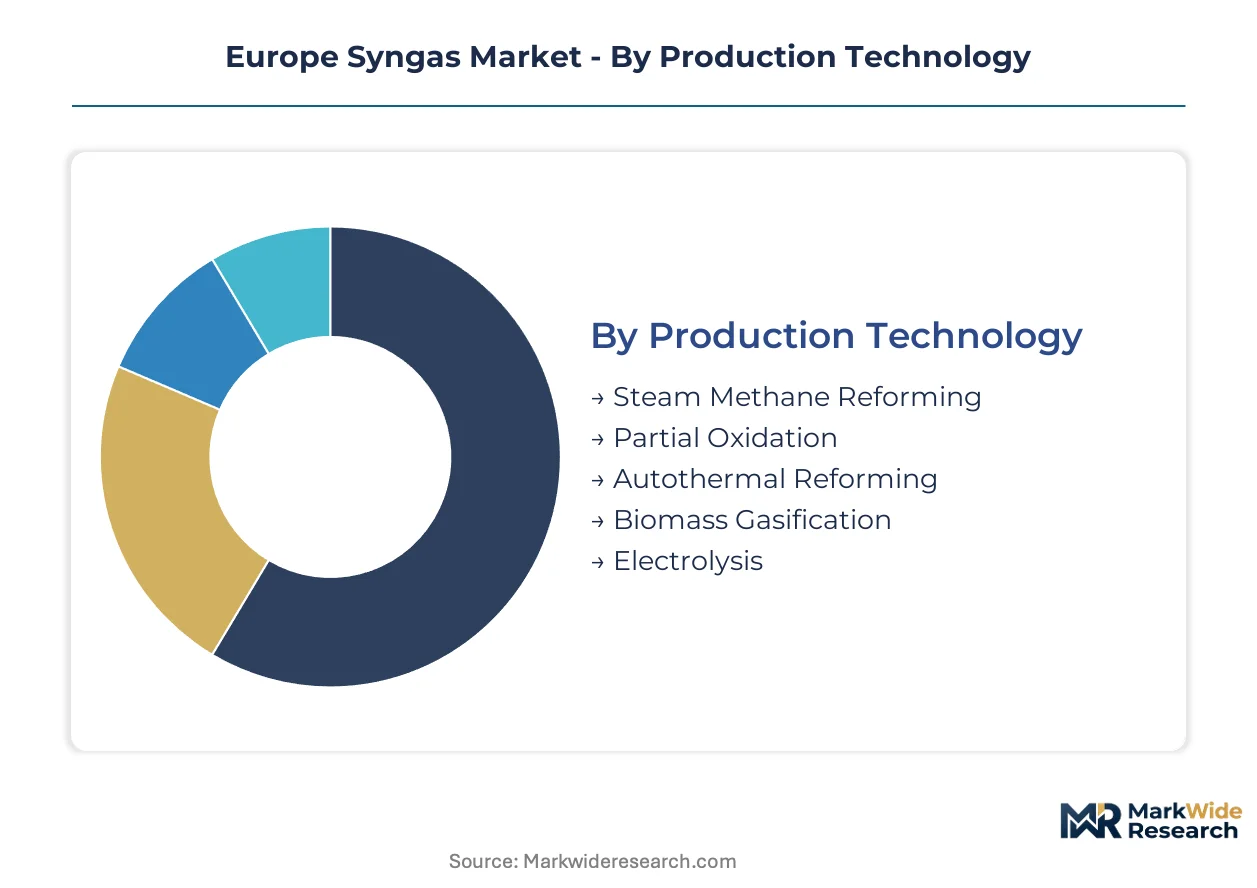
Europe's syngas market segments reflect divergent decarbonization pathways across national hydrogen hubs. Production technology choices and feedstock sourcing determine project bankability under EU carbon accounting rules. Understanding segment dynamics reveals where subsidy eligibility and offtake contracts are concentrating capital deployment.
Production Technology:
Domestic capacity expansion clusters in Germany, the Netherlands, and France, while export-oriented syngas derivatives flow from Belgian and Spanish production nodes.
- Steam Methane Reforming:Dominates installed base with 800-1000°C operating envelopes and nickel-alumina catalyst systems. Dutch and German chemical corridors maintain this infrastructure for ammonia and methanol feedstock, though unabated emissions face mounting CBAM exposure.
- Biomass Gasification:Fluidized-bed and entrained-flow designs process forestry residues at 700-1500°C. Scandinavian and Baltic producers leverage sustainable forest management certifications to access premium offtake contracts in German hydrogen hubs.
- Partial Oxidation:Heavy hydrocarbon feedstock conversion using oxygen-blown gasifiers. Refinery integration in Rotterdam and Antwerp clusters serves residual fuel upgrading.
- Autothermal Reforming:Combined steam and oxygen reforming achieves higher thermal efficiency. North Sea hydrogen corridor projects pair this with carbon capture for blue hydrogen pathways.
- Electrolysis:Solid oxide and alkaline systems split water using renewable or nuclear electricity. French nuclear-powered installations and Iberian solar-to-hydrogen projects are advancing fastest.
Steam Methane Reforming holds the largest share; momentum sits with Biomass Gasification.
Feedstock Type:
Cost structures stratify between pipeline-delivered molecules and waste-stream feedstocks with negative carbon intensity scoring.
- Natural Gas:TTF-indexed pricing governs reforming economics across Northwest European chemical clusters. Dutch and German producers hedge through long-term supply agreements with Norwegian and Qatari exporters.
- Biomass:Forestry residues, energy crops, and agricultural waste qualify for EU renewable energy directive compliance. Baltic and Nordic suppliers command premium pricing through sustainability certification chains.
- Coal:Legacy gasification in Poland and Czechia faces accelerated phase-out pressure under EU ETS tightening and Just Transition Mechanism timelines.
- Waste:Municipal solid waste and industrial off-gases divert from landfill or incineration. Circular economy incentives in Benelux and German federal states support project development.
- Light Hydrocarbons:Refinery LPG and naphtha streams serve dedicated partial oxidation units. Italian and Spanish refining complexes maintain this feedstock pathway for chemical integration.
Natural Gas dominates current throughput; Waste feedstocks are climbing the fastest under circular economy subsidies.
End Use Industry:
Application demand splits between established chemical intermediates and emerging hydrogen mobility sectors.
- Chemicals Manufacturing:Methanol, acetic acid, and oxo-alcohol synthesis consume high-purity syngas specifications. Antwerp-Rotterdam chemical cluster offtakers are contracting for certified low-carbon feedstock documentation.
- Fertilizer Production:Ammonia synthesis for nitrogen fertilizers represents volume anchor demand. German and Polish agricultural markets drive seasonal offtake patterns with hydrogen hub integration requirements.
- Metal Processing:Direct reduction iron and steelmaking applications substitute coke-based reduction. Swedish HYBRIT and German SALCOS initiatives are piloting industrial-scale deployment.
- Fuel Cells:PEM and solid oxide fuel cell systems require ultra-low contaminant syngas for hydrogen extraction. Transport and stationary power applications in German and French mobility corridors.
- Power Generation:IGCC and gas turbine blending applications remain marginal. Italian and Spanish flexible generation assets trial hydrogen cofiring percentages.
Chemicals Manufacturing commands the largest share; Fuel Cells show steepest expansion trajectory.
Application:
Product specifications vary by carbon intensity requirements and purity thresholds across downstream synthesis routes.
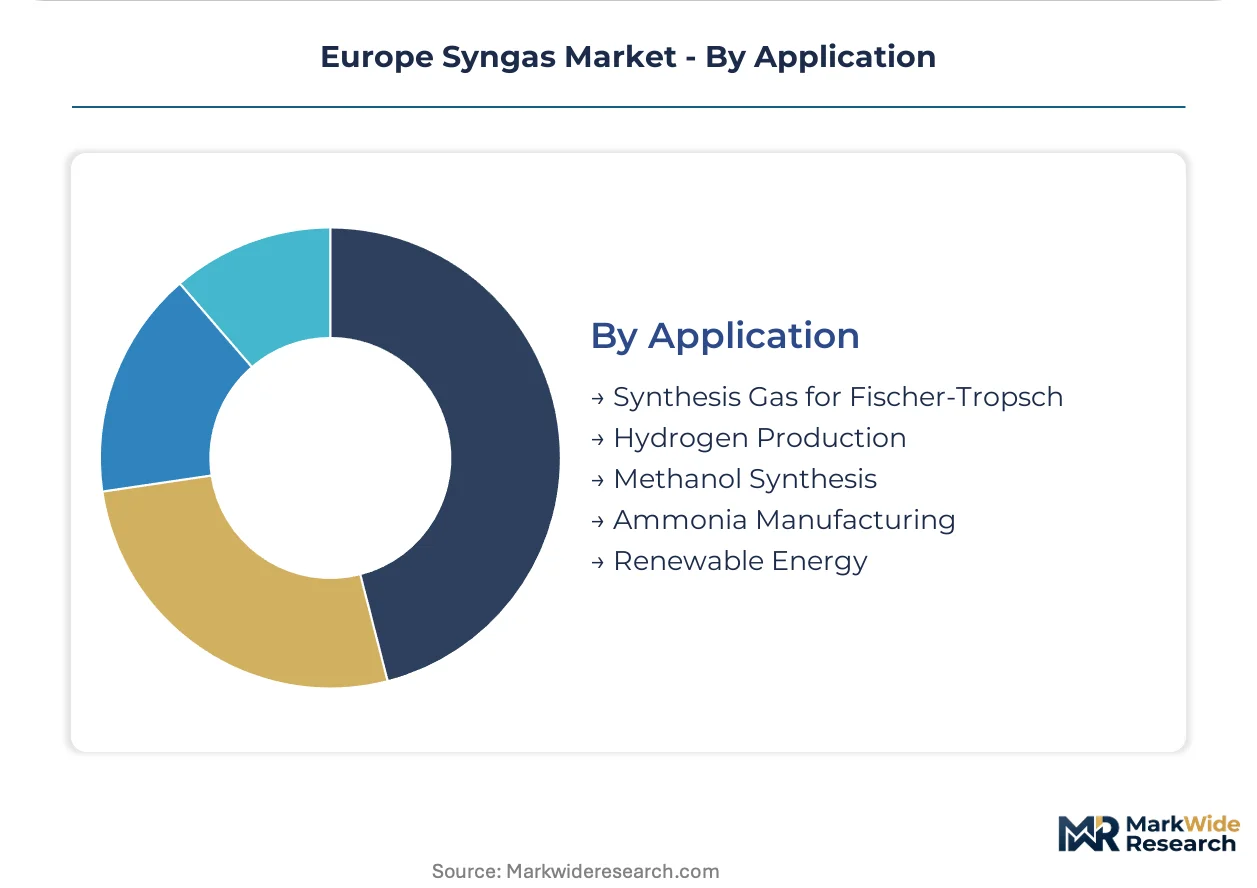
- Hydrogen Production:Water-gas shift and pressure swing adsorption separate high-purity H2 for ammonia and refining. German KBA transport-sector benchmarks cascade back to syngas specification requirements.
- Methanol Synthesis:Copper-zinc-alumina catalyst systems demand precise H2:CO ratios. Rotterdam and Antwerp methanol producers are retrofitting for biogenic and captured carbon feedstock.
- Ammonia Manufacturing:Haber-Bosch synthesis consumes the largest single syngas volume. Northwest European producers face CBAM-driven feedstock substitution pressure.
- Synthesis Gas for Fischer-Tropsch:Cobalt and iron catalyst systems convert syngas to synthetic diesel and jet fuel. ReFuelEU Aviation mandates are hardening long-term offtake for e-fuels production.
- Renewable Energy:Power-to-X and seasonal storage applications integrate with renewable asset portfolios. Iberian and Nordic developers pair electrolysis with wind and solar capacity.
Hydrogen Production holds the largest share; Synthesis Gas for Fischer-Tropsch is gaining share fastest under aviation fuel mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium exports syngas-derived methanol and ammonia derivatives to German chemical processors along the Rhine corridor. Rotterdam-Antwerp pipeline networks channel intermediate feedstocks toward Ruhr industrial consumers. Cross-border hydrogen hub coordination determines capacity allocation across Northwest European production nodes.
Germany
Steel decarbonization through SALCOS and HYBRIT initiatives consumes reforming-grade syngas for direct reduction iron. KBA enforces transport-sector hydrogen purity benchmarks that cascade to syngas specification requirements. The Rhine-Ruhr chemical corridor retrofits steam methane reforming assets for carbon capture integration.
Netherlands
Rotterdam port authorities prioritize biomass gasification for circular carbon feedstock to regional refineries. REPowerEU hydrogen hub funding accelerates electrolyzer deployment at Maasvlakte industrial zones. Shell and Air Products maintain partial oxidation capacity for residual fuel upgrading.
France
Nuclear-powered electrolysis leverages EDF's 56-reactor fleet for baseload syngas production via solid oxide cells. Air Liquide pilots grid-connected installations near Le Havre chemical clusters. ReFuelEU Aviation mandates harden long-term offtake for Fischer-Tropsch synthetic jet fuel.
Poland
Legacy coal gasification assets in Upper Silesia face Just Transition Mechanism phase-out timelines. Biomass co-feeding retrofits attract EU cohesion fund support for forestry residue utilization. Grupa Azoty contracts for low-carbon ammonia feedstock to meet CBAM compliance thresholds.
Spain
Iberian solar and wind corridors host power-to-X projects with 15-20 year renewable power purchase agreements. Repsol trials electrolysis-to-syngas integration at Tarragona petrochemical complexes. Port of Barcelona infrastructure supports e-fuels export to Northwest European aviation markets.
Europe Syngas Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and catalyst supply dimensions. The vendor base stratifies between integrated engineering contractors, industrial gas majors, and proprietary technology licensors. Three archetypes dominate: process technology licensors monetizing reforming patents, industrial gas operators controlling syngas separation infrastructure, and engineering contractors executing turnkey gasification projects. Capacity expansion and strategic technology partnerships constitute the dominant competitive moves.
Among Danish technology licensors, Haldor Topsoe A/S exemplifies the catalyst and reforming patent archetype. Industrial gas majors Linde plc and Air Liquide occupy positions spanning syngas separation, carbon capture integration, and electrolysis-to-syngas pilot development. These three entities represent distinct competitive vectors: proprietary catalysis, infrastructure scale, and renewable hydrogen integration.
| Leading Market Players |
|---|
| Technip Energies NV |
| Royal Dutch Shell |
| Air Products and Chemicals, Inc. |
| Haldor Topsoe A/S |
| Sasol Limited |
| Linde plc |
| Maire Tecnimont SpA |
| KBR Inc. |
| Air Liquide |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with take-or-pay clauses anchor supply access for Rotterdam and Antwerp chemical clusters while locking in price visibility against TTF benchmark volatility. These structures cascade risk allocation across German hydrogen hub offtakers and French nuclear-powered electrolysis developers under EU Carbon Border Adjustment Mechanism compliance timelines.
Pricing Analysis
Steam methane reforming assets trade at legacy cost structures while biomass gasification commands certification premiums and electrolysis-based production sits at prototype-scale economics. Three-tier pricing structure across certified low-carbon, transitional biogenic, and unabated fossil-derived syngas reflects carbon intensity scoring under EU ETS and CBAM frameworks. Cost compression in unabated reforming is intensifying because natural gas price volatility erodes margin predictability for unhedged Dutch and German producers. Ammonia manufacturers exhibit highest price sensitivity due to thin nitrogen fertilizer margins, while aviation offtakers under ReFuelEU Aviation mandates absorb premium pricing for e-fuels compliance.
Supply Chain Analysis
Norway and Qatar anchor pipeline-delivered natural gas feedstock for Northwest European reforming infrastructure, while the Baltic states and Sweden concentrate forestry residue supply for gasification pathways. Catalyst systems draw from specialized chemical manufacturing in Germany and Belgium, with electrolyzer stacks sourcing predominantly from East Asian fabrication centers. Single-source vulnerability concentrates in PEM electrolyzer membrane supply, exposing French and Iberian green hydrogen projects to import dependency risks. Distribution runs through Antwerp-Rotterdam pipeline networks and Rhine corridor barge terminals toward Ruhr industrial consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe syngas market tracks a cyclical recovery anchored to EU hydrogen hub capital deployment waves and industrial cluster reconfiguration timelines. Steel decarbonization initiatives and aviation fuel mandates provide demand-side momentum across the projection horizon.
For Market Incumbents: Secure carbon capture integration partnerships at existing steam methane reforming sites before CBAM phase-in tightens compliance thresholds. Linde plc and Air Liquide should deepen backward integration into electrolyzer supply chains to offset East Asian manufacturing concentration risks. Anchor long-term offtake positions with German steel and aviation sectors to defend margin pools against emerging biomass gasification entrants. For New Entrants and Emerging Players: Differentiate on nuclear-powered electrolysis or solid oxide cell integration to exploit France's baseload electricity advantage and Iberian renewable resource corridors. Target Polish and Czechian legacy coal gasification retrofit opportunities where EU cohesion fund subsidies lower capital barriers. Pursue project development partnerships with Scandinavian forestry residue suppliers to secure negative carbon intensity feedstock certification chains. For Investors and Strategic Acquirers: Capital is best deployed toward modular gasification technology licensors and solid oxide electrolyzer stack developers with demonstrated pilot-scale deployment. Long-term viability favors assets positioned at the intersection of circular carbon feedstock access and hydrogen hub infrastructure proximity. Watch for French nuclear reactor availability rates and German steel sector direct reduction iron commissioning schedules as inflection indicators for electrolysis-based syngas demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Rotterdam-Maasvlakte electrolyzer deployments harden REPowerEU hydrogen hub commitments. |
| Backward Integration | Catalyst manufacturers acquire forestry residue processing to control biogenic carbon supply chains. |
| Green Manufacturing Transition | Antwerp-Rotterdam clusters retrofit reforming assets for carbon capture integration under CBAM. |
| Long-term Supply Agreement | Iberian solar developers contract 15-20 year power purchase agreements with electrolysis-to-syngas projects. |
| Joint Venture | EDF and Air Liquide partner on nuclear-powered solid oxide electrolysis at Le Havre chemical clusters. |
Research Methodology
The analysis maps steam methane reforming, biomass gasification, partial oxidation, autothermal reforming, and electrolysis production pathways, each validated through interviews with plant operations directors, chemical procurement leads at ammonia and methanol producers, EPC contractors, and hydrogen hub project developers. Primary fieldwork combined with secondary validation from ECHA REACH filings, EU ETS emissions databases, Cefic chemical industry reports, and national hydrogen strategy documents. Bottom-up capacity installation tracking triangulates against top-down demand modeling from end-use industry consumption patterns.
Consistency checks validated volume and value outputs against external benchmarks including IEA hydrogen project databases and national energy agency deployment statistics. The analytical framework segments by production technology, feedstock type, end-use industry, and application across the projection horizon, with CAGRs derived from capacity expansion announcements and offtake contract timelines. Forecast inputs incorporate EU Carbon Border Adjustment Mechanism phase-in schedules, REPowerEU subsidy allocation patterns, and nuclear reactor availability assumptions for French electrolysis pathways.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal funding commitment or accelerated CCS infrastructure deployment would require recalibration. Forecasts reflect assumptions on carbon pricing trajectories, electrolyzer cost decline curves, and biomass feedstock sustainability certification scalability. Recalibration cycles align with material shifts in EU ETS allowance prices, hydrogen hub commissioning schedules, and aviation e-fuels mandate enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Gas Processing Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
3D Printing Gases Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Industrial Oxygen Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
US Specialty Gas Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
High Purity Argon Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Neon Gas Market