
 Argon Gas Market | 2026-2036
Argon Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Argon Gas Market Analysis
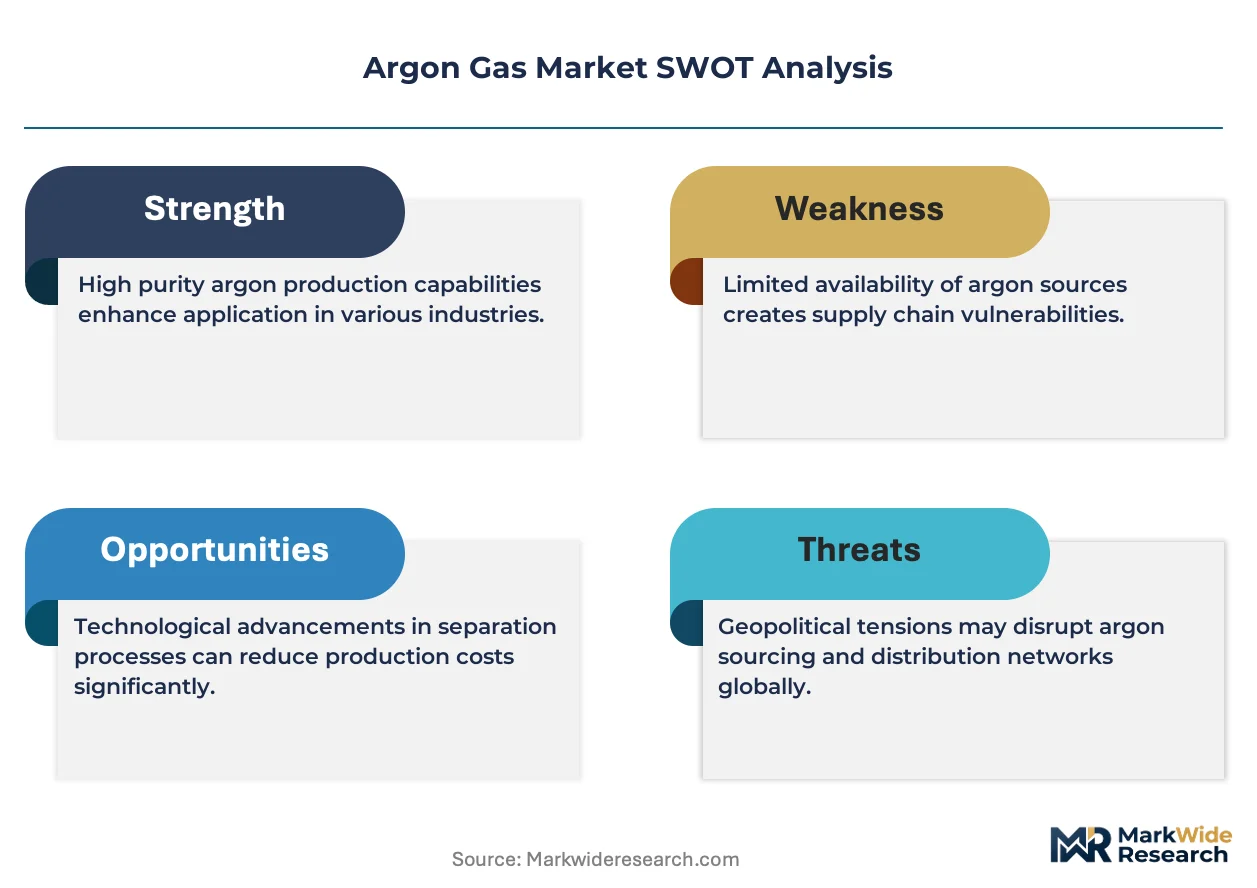
Long-term supply agreements and integrated gas management services are broadening what argon suppliers monetize beyond commodity molecules. Linde plc leverages its on-site generation infrastructure to anchor contracts with steel mills across multiple continents. Air Liquide sustains competitive positioning through R&D intensity in cryogenic separation efficiency. Messer Group specializes in regional distribution density across Central and Eastern European industrial corridors.
Argon is a monatomic noble gas constituting approximately 0.93% of Earth's atmosphere, typically recovered through cryogenic air separation units that liquefy and fractionate atmospheric gases at temperatures below -185°C; its chemical inertness makes it indispensable for shielding reactive molten metals from oxidation during welding and for creating controlled atmospheres in semiconductor fabrication. High-purity argon commands premium positioning in electronics manufacturing where even trace contaminants degrade chip yields, while liquid argon dominates volume flows into metal fabrication due to economies in bulk storage and transport. Gaseous argon retains mature demand profiles in smaller-scale welding operations, though argon mixtures containing carbon dioxide or oxygen are gaining traction as cost-optimized alternatives for specific alloy applications.
The US EPA and OSHA regulate workplace exposure limits and cylinder handling protocols, while the EU REACH framework governs chemical registration and safety documentation for industrial gas supply chains in Europe. China's GB standards and Ministry of Ecology and Environment directives increasingly influence global purity benchmarks given the country's production scale. Stakeholders must monitor how carbon-intensity disclosures under evolving climate frameworks reshape site-selection logic for new air separation capacity.
Market Dynamics
Steel mills and semiconductor fabs are locking in decade-long argon supply contracts to hedge against air separation capacity scarcity, compressing spot market liquidity and elevating integrated gas management services above commodity molecule sales.
Growth Catalysts
- Steel production expansion:China's Ministry of Ecology and Environment directives are tightening emission standards that favor electric arc furnaces, which consume triple the argon per ton versus blast furnaces.
- REACH framework compliance:The EU's chemical registration and safety documentation requirements are forcing industrial gas distributors to consolidate supply chains, advantaging certified bulk handlers with integrated logistics networks.
- Cryogenic separation efficiency gains:Advanced distillation column designs are extracting higher argon yields from atmospheric air, lowering unit costs for on-site generation at large-scale fabrication facilities.
Market Restraints
- Electricity cost volatility:Cryogenic air separation consumes 0.8-1.2 kWh per cubic meter of argon produced, exposing margins to grid price spikes in Germany and South Korea.
- Supply concentration in China:Over half of global air separation unit capacity sits within Chinese industrial parks, creating single-point-of-failure risk for international buyers.
- Helium substitution in leak detection:Semiconductor fabs are partially replacing argon-hydrogen mixtures with helium tracer gas for wafer chamber integrity testing, though helium's own supply constraints limit displacement velocity.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for semiconductor and display manufacturing are attracting air separation investments in Gujarat and Tamil Nadu industrial corridors.
- Dual carbon goals in China:The MIIT's energy efficiency mandates for heavy industry are accelerating on-site argon generation to reduce liquid transport emissions and secure green financing.
- Additive manufacturing atmosphere control:Laser powder bed fusion systems for titanium and aluminum alloys require ultra-high-purity argon shielding, opening premium pricing tiers for gas suppliers with 99.9999% certification capabilities.
Industry Challenges
- Cryogenic engineering talent scarcity:Qualified technicians for air separation unit maintenance and troubleshooting are concentrated at a handful of technical institutes in Germany, Japan, and the United States.
- GB standard certification timelines:China's national purity and cylinder testing protocols require 12-18 month validation cycles for imported argon equipment, delaying market entry for non-domestic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argon Gas Market |
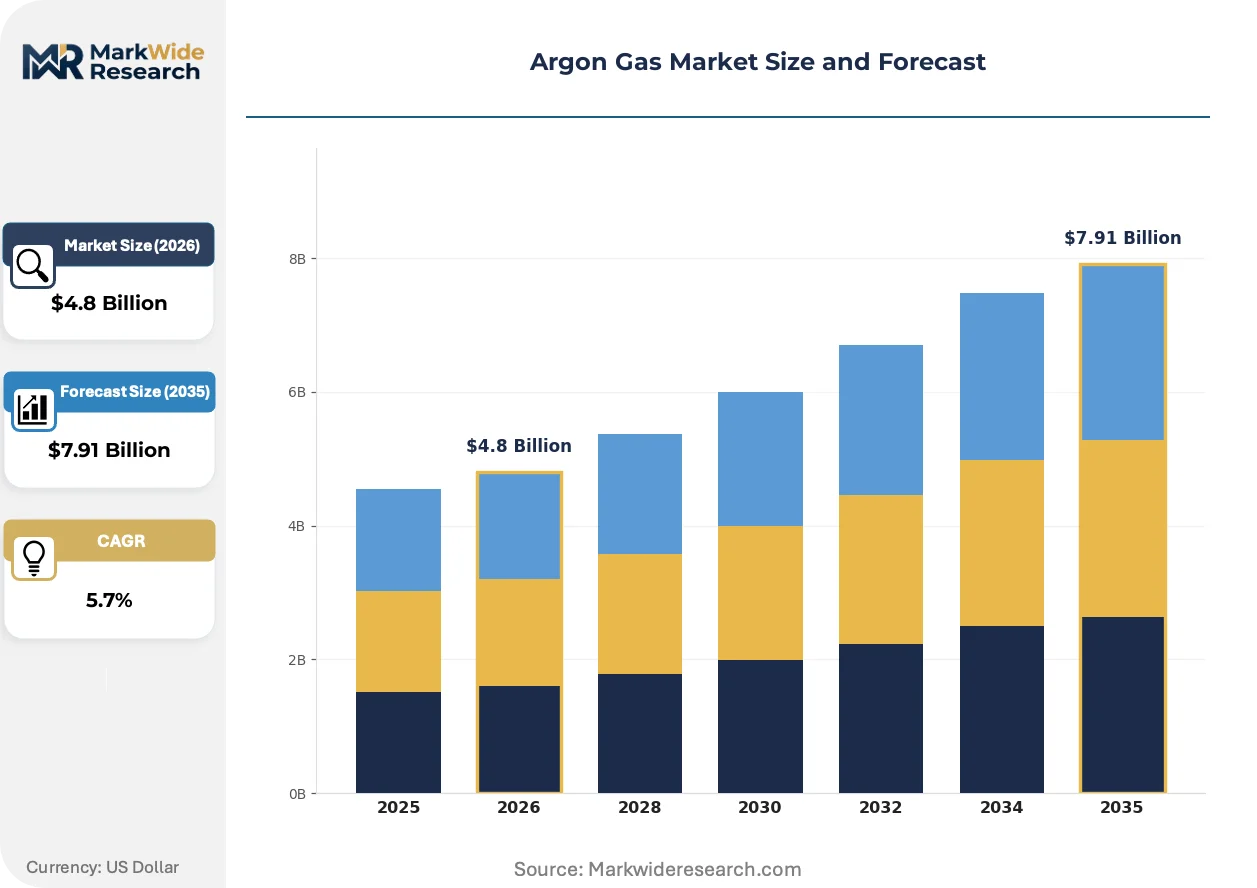
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Welding, Metal Fabrication, Insulation, Electronics Manufacturing Product Type: Liquid Argon, Gaseous Argon, Argon Mixtures, High-Purity Argon End User: Industrial, Healthcare, Research Institutions, Food Processing Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Linde plc, Air Liquide, Air Products, Messer Group, BASF SE, Iwatani Corporation, Taiyo Nippon Sanso, Matheson Tri-Gas, AMCS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argon Gas Market Emerging Trajectories
Membrane and pressure swing adsorption technologies are encroaching on cryogenic dominance in mid-scale applications, while regulatory carbon accounting and buyer procurement centralization are rewriting how argon contracts are structured and priced.
Membrane-based argon recovery systems are absorbing market share from traditional cryogenic units in steel mill auxiliary applications where purity requirements sit below 99.95%. Mid-scale fabricators in Poland and Mexico are piloting these units to avoid liquid bulk delivery infrastructure. The technology is absorbing capital that would otherwise flow to small cryogenic plants, compressing the addressable market for conventional equipment vendors in the 50-200 ton per day segment.
The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases is redirecting investment toward inert gas alternatives in semiconductor etching and chamber cleaning processes. Argon-fluorine mixtures are displacing perfluorocarbons in select dry etch applications, though throughput efficiency penalties persist. German and Dutch fabs are most affected, with equipment retrofits accelerating to maintain CE marking compliance ahead of 2030 reduction targets.
Centralized procurement consortia among automotive OEMs are consolidating argon purchasing across multi-plant welding networks, disintermediating regional distributors. Tier-1 suppliers in Detroit and Stuttgart are negotiating master service agreements directly with Linde and Air Liquide, bundling argon with carbon dioxide and oxygen into unified molecule-plus-logistics contracts. This behavior is most visible in North American automotive stamping operations, where plant consolidation has concentrated buying power at fewer decision nodes.
Argon Gas Market Segmentation
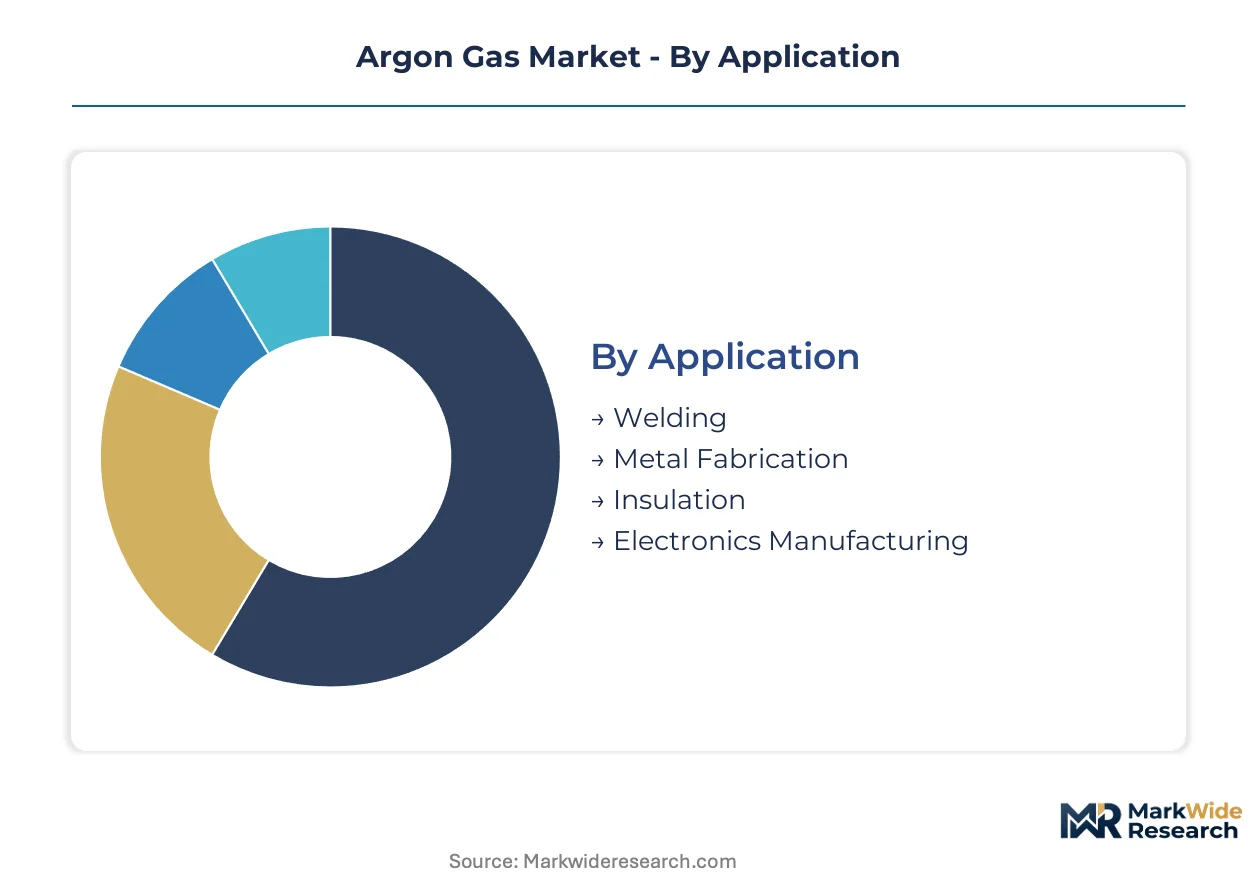
Argon gas segmentation reveals how purity grades, physical states, and delivery modes align with distinct economic logics across welding shops, semiconductor fabs, and research facilities. Understanding these splits exposes where suppliers can extract premium pricing versus where commodity volumes dominate.
Application:
Volume flows concentrate in metal-heavy industries where argon serves as oxidation shield, while premium pricing attaches to contamination-sensitive processes demanding 99.999%+ purity.
- Welding:Consumes the largest atmospheric volumes as shielding gas for TIG and MIG processes across automotive stamping and shipbuilding yards. Demand clusters in China's Yangtze River Delta steel corridors where electric arc furnace expansion triples argon intensity per ton of output.
- Metal Fabrication:Spans laser cutting, heat treatment, and powder metallurgy operations requiring controlled atmospheres. German automotive component suppliers in Baden-Württemberg are consolidating procurement across multi-plant networks to secure bulk pricing leverage.
- Insulation:Deploys argon between multi-pane glazing units to suppress thermal conductivity in high-performance building envelopes. European window manufacturers under EU Green Deal efficiency mandates are expanding specification.
- Electronics Manufacturing:Commands the steepest purity premiums for semiconductor crystal pulling and sputtering chamber backfill. Trace nitrogen or oxygen above 1 ppm degrades chip yields, locking in certified supply chains with 99.9999% documentation.
Mature deployment sits with Welding. Newer deployment is concentrated in Electronics Manufacturing.
Product Type:
Physical state and purity tier determine storage economics, transport radius, and customer switching costs across the value chain.
- Liquid Argon:Dominates bulk flows to steel mills and large fabrication facilities where cryogenic tankage enables 15-30 day inventory coverage. On-site vaporization eliminates cylinder handling labor at high-volume consumption points.
- Gaseous Argon:Serves job-shop welders and maintenance operations via high-pressure cylinder exchange programs. Distribution density in Poland's Silesian industrial belt allows Messer Group to sustain same-day delivery commitments.
- Argon Mixtures:Blend with carbon dioxide or oxygen to optimize arc characteristics for specific alloy systems. Cost-conscious shipyards in South Korea are adopting Ar-CO2 mixtures for mild steel hull welding to reduce pure argon consumption.
- High-Purity Argon:Requires additional purification stages after cryogenic separation to achieve semiconductor-grade specifications. Supply concentrates at facilities with dedicated rare gas extraction trains and contamination-controlled filling protocols.
Liquid Argon anchors established industrial supply relationships. High-Purity Argon is gaining share fastest in electronics cluster expansions.
End User:
Customer scale and technical sophistication fragment procurement behavior from spot cylinder purchases to decade-long on-site generation contracts.
- Industrial:Encompasses steel production, automotive manufacturing, and heavy machinery fabrication consuming 80%+ of merchant argon volumes. Long-term supply agreements with take-or-pay clauses hedge against air separation unit scarcity.
- Healthcare:Deploys argon in cryosurgery and ophthalmic procedures requiring medical-grade certification. Smaller volume profiles sustain cylinder-based distribution through specialized gas distributors.
- Research Institutions:Demands ultra-high-purity specifications for particle physics detectors and materials science experiments. CERN's liquid argon time projection chambers consume multi-ton quantities with extreme purity documentation.
- Food Processing:Utilizes argon for inert atmosphere packaging of sensitive products and wine preservation systems. Niche positioning limits scale relative to industrial applications.
Industrial end users represent entrenched demand concentration. Research Institutions are expanding most quickly in high-energy physics investments.
Distribution Channel:
Channel selection reflects customer density, consumption predictability, and the economics of last-mile cryogenic logistics.
- Direct Sales:Large steel mills and semiconductor fabs negotiate directly with Linde or Air Liquide for on-site generation or dedicated liquid bulk supply. Master service agreements bundle argon with oxygen, nitrogen, and carbon dioxide across multi-plant networks.
- Distributors:Regional gas specialists maintain cylinder fleets and local filling capabilities for mid-scale fabricators and maintenance shops. Central and Eastern European corridors favor this channel where national champions retain route density.
- Online Retail:Emerging channel for small-volume cylinder and disposable canister purchases by hobbyist welders and specialty contractors. Limited penetration in cryogenic bulk due to transport regulatory complexity.
- Others:Includes equipment leasing arrangements and toll processing agreements where gas supply ties to welding machine or laser system contracts.
Direct Sales commands the largest contract values. Distributors retain defensive positioning in geographically fragmented demand pockets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands over half of global air separation unit capacity, yet consumption clusters in steel corridors and electronics manufacturing zones across multiple continents. Production geography and demand geography diverge sharply, with cryogenic logistics networks bridging the gap through liquid bulk shipping and on-site generation deployments.
China
Electric arc furnace expansion under MIIT energy efficiency mandates triples argon intensity per ton of steel versus blast furnaces. The Ministry of Ecology and Environment enforces emission standards that favor cleaner furnace technologies. Yangtze River Delta industrial parks concentrate both air separation capacity and semiconductor fabrication demand.
United States
Automotive stamping consolidation in Detroit and Southeast corridors concentrates welding gas procurement at fewer decision nodes. OSHA workplace exposure limits and EPA purity standards tighten handling requirements. Gulf Coast petrochemical clusters anchor merchant liquid argon supply for downstream fabrication.
Germany
Baden-Württemberg automotive suppliers consolidate multi-plant argon procurement into master service agreements. The EU F-Gas Regulation phases down fluorinated gases, redirecting etching chemistry toward argon-fluorine mixtures. Ruhr industrial corridors maintain dense distributor networks for mid-scale fabricators.
India
PLI scheme incentives for semiconductor and display manufacturing attract air separation investments to Gujarat and Tamil Nadu. BIS certification requirements and DGFT import protocols structure equipment validation timelines. Delhi-Mumbai Industrial Corridor steel expansion drives shielding gas demand.
South Korea
Shipyards in Ulsan and Busan adopt argon-carbon dioxide mixtures to reduce pure argon consumption in hull welding. MFDS industrial gas regulations align with international purity benchmarks. Seoul Capital Area semiconductor fabs lock in decade-long supply contracts for crystal pulling operations.
Argon Gas Market Vendor Landscape
Top-tier vendors anchor integrated gas management services, while regional distributors defend position through route density in fragmented demand pockets. The structure concentrates around three strategic archetypes: global industrial gas majors with on-site generation infrastructure, national champions with cylinder fleet density, and equipment specialists with cryogenic engineering capabilities. Dominant competitive moves include long-term take-or-pay contract structures and backward integration into air separation unit ownership.
Among global industrial gas majors, Linde plc and Air Liquide occupy positions as archetypal integrated suppliers, while Messer Group exemplifies the regional density specialist model. These three represent the competitive spectrum from multinational on-site generation to geographically concentrated distribution networks. Their positioning reflects how contract duration, purity certification capabilities, and cryogenic logistics scale separate premium-tier vendors from commodity merchants.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products |
| Messer Group |
| BASF SE |
| Iwatani Corporation |
| Taiyo Nippon Sanso |
| Matheson Tri-Gas |
| AMCS Corporation |
| Others |
Supply Flow & Price Mechanics
Electricity futures indices in Germany and South Korea cascade through cryogenic air separation economics, compressing margins at merchant liquid argon suppliers while amplifying pricing power for integrated producers with captive generation assets. The cost pass-through mechanics split the market into volume-contract tiers versus spot-exposed positions.
Pricing Analysis
Cost-down pressure on gaseous argon accelerates because membrane separation technologies are absorbing mid-scale welding demand that previously sustained small cryogenic plant economics. Three-tier pricing structure across semiconductor-grade, industrial liquid, and cylinder-delivery tiers reflects purity certification and volume scale differentiation. Margin tightening in liquid bulk traces to electricity price volatility at Chinese and German grid nodes. Job-shop welders exhibit highest price sensitivity, while semiconductor fabs accept premium positioning for 99.9999% documented purity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese industrial parks hosting over half of global air separation unit capacity, exposing international buyers to concentrated production geography. Cryogenic separation equipment draws from German engineering specialists, Chinese steel fabrication, and Japanese compressor technology. Tariff exposure on ASU components threatens project timelines for Indian and Southeast Asian capacity additions. Distribution runs through liquid bulk tanker fleets for steel mills and cylinder exchange networks for maintenance operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The argon gas market sits in a technology-transition phase as membrane and pressure swing adsorption systems displace legacy cryogenic separation in mid-scale applications. This substitution dynamic rewrites competitive positioning across purity tiers and volume segments.
For Market Incumbents: Extend on-site generation infrastructure into steel mill anchor contracts to defend against membrane technology encroachment in auxiliary applications. Deepen backward integration into air separation unit ownership in India's Gujarat and Tamil Nadu corridors to preempt PLI-scheme entrants. Lock in decade-long take-or-pay structures with semiconductor fabs before alternative shielding technologies mature.
For New Entrants and Emerging Players: The EU F-Gas Regulation phasedown opens a window for argon-fluorine mixture specialists to capture displaced perfluorocarbon demand in German and Dutch etching applications. Target Poland's Silesian industrial belt and Mexico's mid-scale fabricator segments where distributor route density remains fragmented. Enter through equipment-leasing bundled with gas supply to bypass cylinder fleet capital requirements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional cylinder distributors with dense route networks in Central and Eastern European industrial corridors. The five-to-ten-year viability window hinges on additive manufacturing atmosphere control adoption in titanium and aluminum powder bed fusion. Watch membrane technology purity thresholds as the inflection signal—breach of 99.95% specifications would compress cryogenic addressable market materially.
| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Generation Expansion | Captures steel mill anchor contracts under China's MIIT energy efficiency mandates. |
| Membrane Technology Pilot Programs | Absorbs mid-scale welding demand in Poland and Mexico away from cryogenic units. |
| High-Purity Certification Investment | Secures semiconductor fab supply chains requiring 99.9999% documentation standards. |
| Regional Distribution Density Buildout | Defends position in geographically fragmented Central and Eastern European corridors. |
| Long-Term Supply Agreement Structuring | Hedges against air separation unit scarcity through take-or-pay contract mechanisms. |
Methodological Framework
Document review covered customs and trade flow databases, industrial gas association technical reports, and national regulator filings, complemented by interviews with air separation unit engineering directors, steel procurement leads, semiconductor fab supply chain managers, and cryogenic logistics operators. Secondary validation drew from EPA enforcement records, EU REACH registration databases, and Chinese GB standard documentation. Bottom-up capacity modeling and top-down demand estimation were triangulated against merchant pricing indices.
Volume and value trajectories across the projection horizon reflect segmented modeling by purity grade, physical state, delivery mode, and end-use industry intensity. CAGRs were derived from elasticity-adjusted consumption coefficients tied to steel production forecasts and semiconductor wafer starts. Cryogenic separation efficiency curves and electricity price scenario bands anchored the cost-side modeling.
The model assumes a particular technology adoption path; alternative pathways for membrane separation reaching semiconductor-grade purity thresholds would alter the outlook. Forecasts reflect documented assumptions around electric arc furnace penetration rates and REACH framework compliance timelines. Deviation in Chinese industrial policy or grid pricing reform would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
US Specialty Gas Market
Industrial Gases
Noble Gas Market
Industrial Gases
Syngas Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Nitrogen Gas Springs Market