
 Carbon Monoxide Market | 2026-2036
Carbon Monoxide Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Monoxide Market Intelligence
Hydrogen is pivoting toward partial substitution in select syngas blends, altering feedstock economics for carbon monoxide derivatives. Linde plc leverages its global hydrogen infrastructure to anchor syngas supply chains across major chemical corridors. Air Liquide sustains leadership in on-site carbon monoxide generation through proprietary partial oxidation technology. Celanese Corporation specializes in captive carbon monoxide consumption for acetic acid and derivatives manufacturing.
Carbon monoxide is a colorless, odorless gas with the chemical formula CO, produced industrially through steam methane reforming or partial oxidation of hydrocarbons at temperatures exceeding 900°C; its primary commercial purpose centers on chemical synthesis, particularly methanol, acetic acid, and phosgene production. Electrochemical sensors dominate the detection segment due to cost efficiency and reliability in industrial safety applications, while infrared technology captures premium positioning for high-precision monitoring in controlled atmosphere environments. Semiconductor-based detection occupies the economy tier for residential alarm deployment where sensitivity thresholds are less stringent.
The US EPA enforces National Ambient Air Quality Standards that limit carbon monoxide emissions from industrial sources, compelling facilities to invest in recovery and abatement systems. Europe's ECHA administers REACH registration requirements for carbon monoxide as a transported substance, shaping product handling protocols and cross-border trade documentation. OSHA mandates permissible exposure limits in workplace environments, directly driving demand for continuous monitoring equipment across manufacturing facilities. Stakeholders must evaluate feedstock flexibility against evolving purity requirements as process intensification reshapes chemical industry specifications.
Market Dynamics
Process intensification in chemical manufacturing is compressing purity tolerances for carbon monoxide feedstock, forcing suppliers to upgrade separation technologies and on-site generation capabilities.
Growth Catalysts
- Acetic acid capacity expansion:China maintains concentrated production clusters for acetic acid derivatives, sustaining concentrated demand for carbon monoxide feedstock at scale.
- OSHA workplace exposure mandates:Continuous monitoring requirements across US manufacturing facilities drive replacement cycles for detection equipment.
- Phosgene derivative demand:Isocyanate producers in polyurethane supply chains maintain steady consumption of high-purity carbon monoxide for chemical synthesis.
Market Restraints
- Natural gas price volatility:Steam methane reforming economics fluctuate with feedstock costs, compressing margins for merchant carbon monoxide suppliers.
- Merchant supply concentration:Industrial gas majors control pipeline distribution networks, limiting independent producer market access.
- Hydrogen substitution in syngas:Partial hydrogen replacement alters carbon monoxide demand ratios in methanol and Fischer-Tropsch applications.
Strategic Opportunities
- Carbon capture integration:CO₂-to-CO electrochemical reduction technologies offer pathways for circular carbon monoxide production.
- India specialty chemical expansion:Domestic acetic acid and derivative capacity investments create new regional demand centers.
- EU Green Deal industrial decarbonization incentives:Funding mechanisms support low-carbon carbon monoxide production technology deployment.
Industry Challenges
- Electrochemical sensor calibration expertise:Maintenance of detection accuracy requires specialized technical personnel scarce in developing manufacturing regions.
- Legacy control system integration:New continuous monitoring platforms face interoperability barriers with existing distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Monoxide Market |
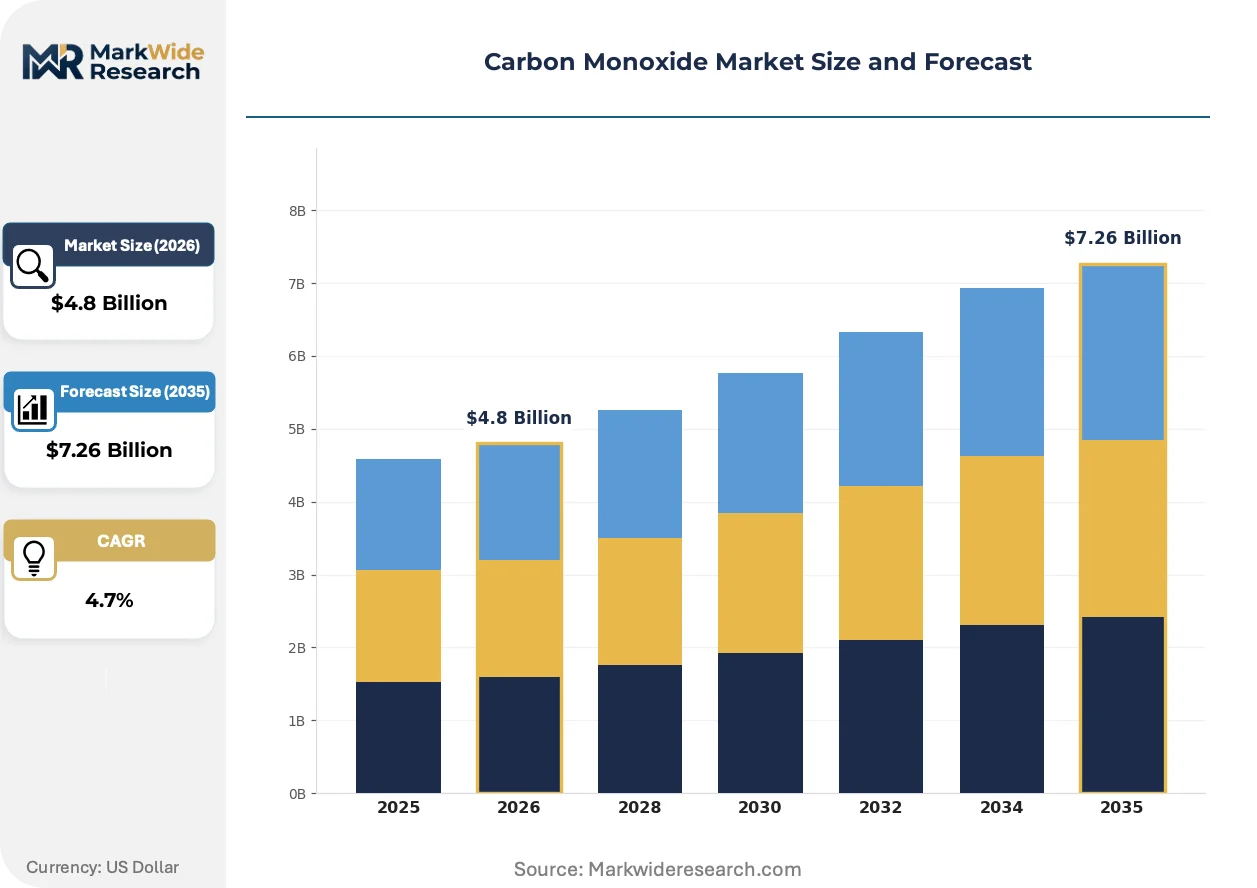
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Detectors, Alarms, Monitors, Sensors Application: Industrial, Residential, Automotive, Commercial Technology: Electrochemical, Photoionization, Semiconductor, Infrared End User: Manufacturers, Homeowners, Commercial Users, First Responders |
| Companies Covered | Air Liquide, Linde plc, Air Products and Chemicals, Inc., Messer SE & Co. KGaA, Celanese Corporation, Sipchem Company, American Gas Products, ATCO Atmospheric And Speciality Gases Private Limited, Axcel Gases, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Monoxide Market Strategic Shifts & Innovations
Electrochemical detection architectures are advancing precision thresholds while solid-state sensing platforms challenge incumbent technologies in residential and industrial safety applications.
Membrane separation technology is expanding into carbon monoxide purification workflows. Chemical producers in acetic acid and methanol corridors adopt polymer and metallic membrane systems to achieve higher feedstock purity without cryogenic distillation. This technology is expanding into mid-scale production facilities previously dependent on merchant gas supply.
REACH registration requirements for carbon monoxide as a transported substance impose documentation and handling protocols across European chemical corridors. ECHA oversight shapes cross-border trade flows and storage facility specifications. Bulk chemical distributors in Germany and the Netherlands invest in compliance infrastructure to maintain intra-EU supply continuity.
Buyer consolidation among multinational chemical producers concentrates procurement leverage. Large acetic acid and isocyanate manufacturers negotiate long-term tolling arrangements directly with industrial gas suppliers, compressing spot market volumes. This pattern is most visible across US Gulf Coast and Rotterdam-Antwerp chemical clusters where integrated production sites dominate consumption.
Carbon Monoxide Market Segmentation
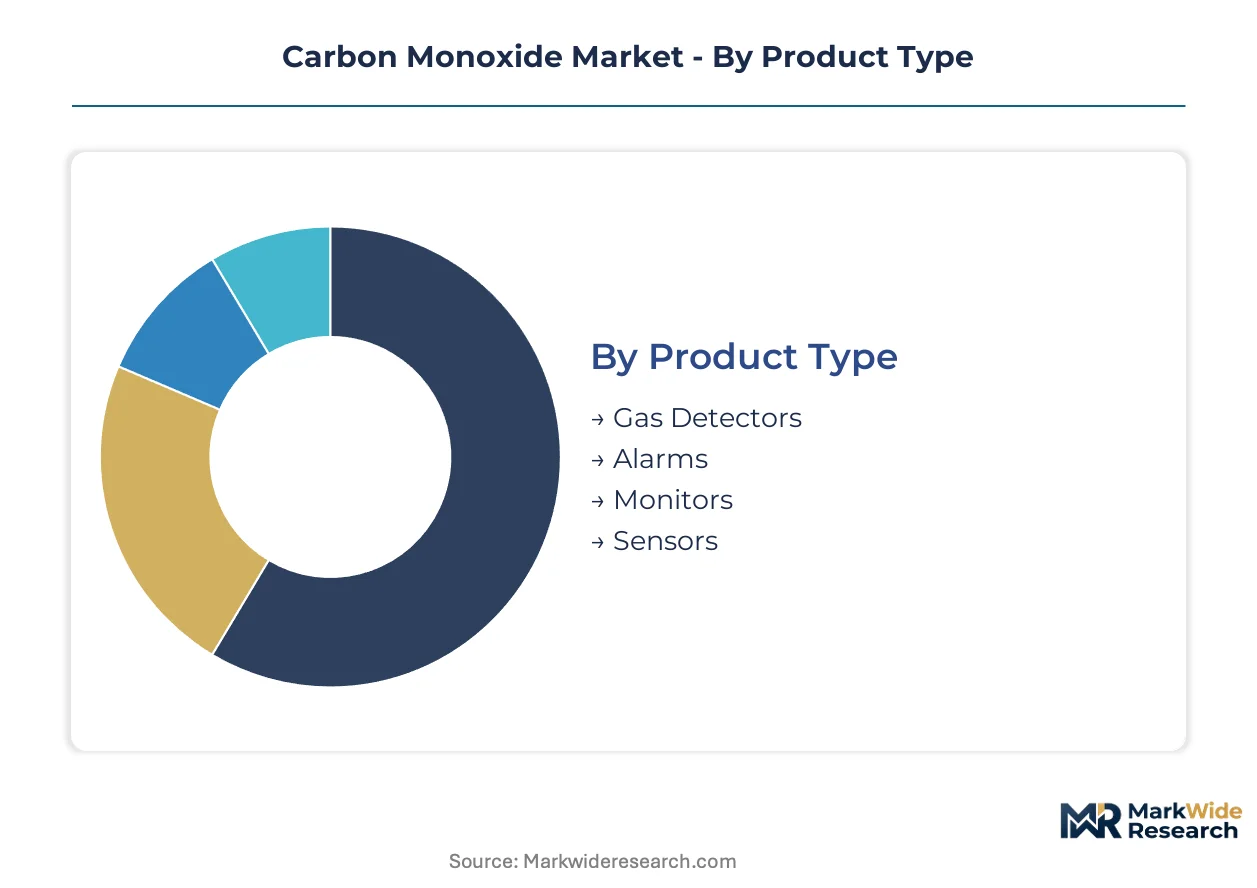
Carbon monoxide market segmentation reflects divergent buyer priorities across safety compliance, process control, and chemical synthesis applications. Equipment purchasers prioritize detection sensitivity thresholds and calibration intervals, while industrial gas buyers emphasize purity specifications and supply reliability.
Product Type:
Buyers in this category differentiate primarily by deployment environment and maintenance burden tolerance.
- Sensors:Compact electrochemical cells dominate industrial integration due to sub-ppm detection thresholds and standardized 4-20mA output signals. Chemical manufacturing facilities in Texas and Louisiana specify these for continuous perimeter monitoring around reformer units.
- Gas Detectors:Portable multi-gas units with CO-specific channels serve confined space entry protocols at petrochemical sites. OSHA inspection frequency in US Gulf Coast states drives replacement demand for legacy catalytic bead models.
- Alarms:Residential battery-powered devices with 10-year sealed lithium cells satisfy California and New York state mandate requirements for rental property compliance.
- Monitors:Fixed-point systems with data logging capabilities support EPA emissions reporting for steel mill blast furnace off-gas streams.
Sensors lead volumes today; detectors are gaining share fastest.
Application:
Cost tier separation distinguishes this category, with premium process control systems commanding multiples over basic safety compliance equipment.
- Industrial:High-purity carbon monoxide supply contracts for acetic acid and phosgene production require 99.5%+ specification with continuous compositional certification. Celanese Corporation and BASF SE facilities along the US Gulf Coast anchor concentrated demand for pipeline-delivered product.
- Residential:Standalone alarm units face commoditization pressure from big-box retail channel consolidation, with First Alert and Kidde brands competing on price points below thirty dollars per unit.
- Automotive:Cabin air quality sensors for premium vehicle segments integrate CO detection with particulate matter and VOC monitoring, driven by European WLTP certification requirements.
- Commercial:Building automation integration demands BACnet-compatible detectors for HVAC control loop feedback in multi-tenant office properties.
Industrial applications command the highest value per unit; residential represents the steepest expansion trajectory.
Technology:
Technology selection tracks required precision tier and operating environment severity.
- Electrochemical:Three-electrode cells with sulfur-resistant electrolyte formulations dominate refinery and chemical plant deployments where hydrogen sulfide cross-sensitivity would corrupt standard sensors.
- Infrared:Non-dispersive infrared benches serve laboratory and pharmaceutical cleanroom applications requiring interference-free measurement in oxygen-deficient atmospheres.
- Semiconductor:Metal oxide sensors at economy price points satisfy basic residential alarm functions where absolute accuracy matters less than presence indication.
- Photoionization:Broad-spectrum VOC detection with CO discrimination capability supports hazmat response scenarios where multiple contaminant identification accelerates evacuation decisions.
Electrochemical technology anchors current installed base; infrared is climbing the fastest among upgrade cycles.
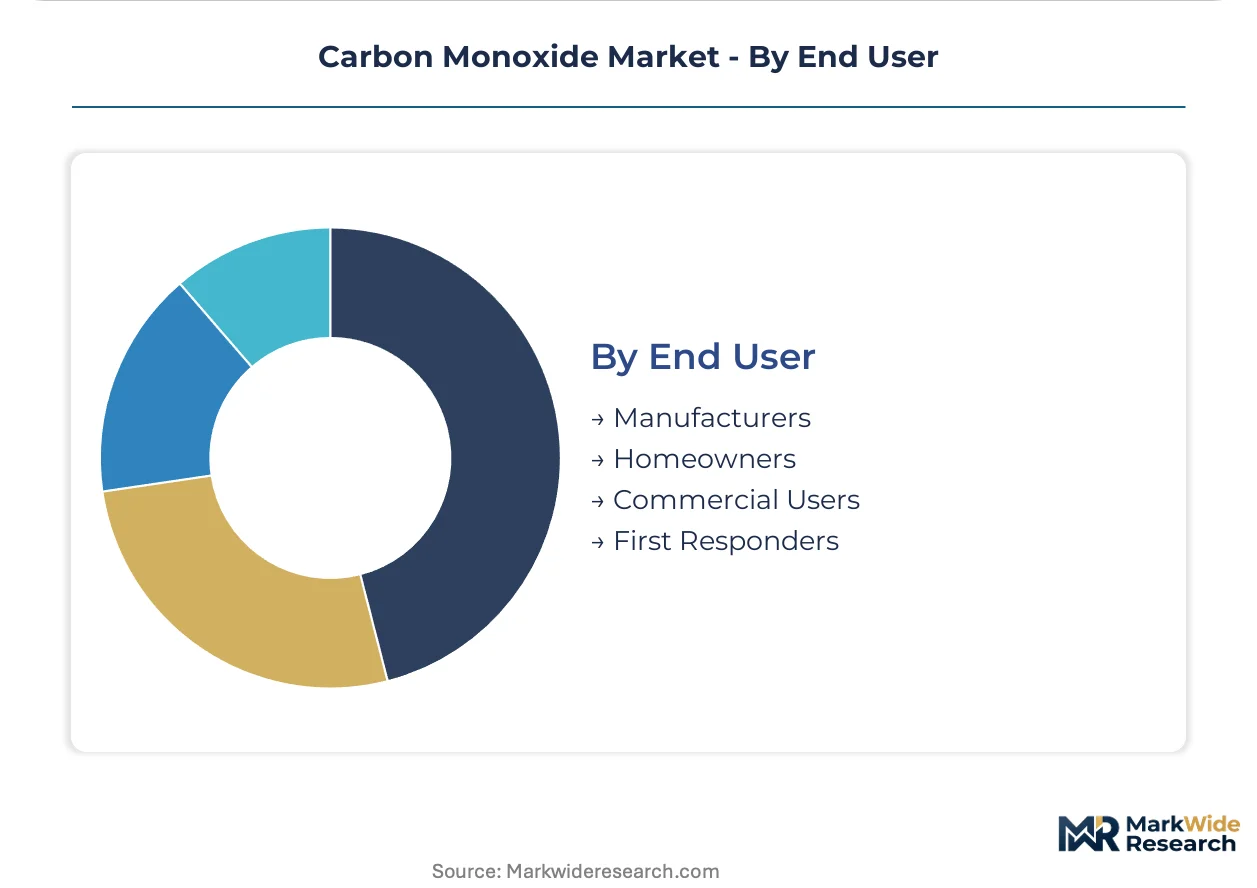
End User:
Procurement sophistication and volume scale separate buyers in this final category.
- Manufacturers:Chemical producers negotiate multi-year tolling agreements with Linde plc and Air Liquide for on-site carbon monoxide generation, embedding energy cost pass-through clauses to manage natural gas price exposure.
- First Responders:Fire departments and hazmat teams specify ruggedized portable units with five-year sensor warranty terms and simplified calibration procedures for field deployment.
- Homeowners:Retail channel purchasers show minimal brand loyalty, responding primarily to price promotion and installation simplicity messaging.
- Commercial Users:Facility managers prioritize networked detection systems with centralized alarm annunciation and maintenance scheduling software integration.
Manufacturers consume the largest absolute volumes; first responder procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast chemical corridor anchors carbon monoxide demand through concentrated acetic acid and methanol production. China maintains the largest single-country consumption base. European regulatory frameworks reshape trade flows and handling protocols.
United States
OSHA workplace exposure mandates drive continuous monitoring equipment replacement across Texas and Louisiana refineries. The EPA enforces National Ambient Air Quality Standards that compel steel mills to install recovery systems for blast furnace off-gas streams. Celanese Corporation facilities along the Houston Ship Channel anchor merchant carbon monoxide demand through long-term tolling arrangements with industrial gas suppliers.
China
Acetic acid capacity expansion in Jiangsu and Shandong provinces sustains concentrated feedstock consumption at scale. The Ministry of Ecology and Environment enforces dual carbon goals that push chemical producers toward higher-purity recovery technologies. Ningbo and Nanjing industrial clusters host integrated production sites where manufacturers negotiate directly with on-site generation providers.
Germany
REACH registration requirements for transported carbon monoxide impose documentation protocols across Rhine-Ruhr chemical corridors. The EU Green Deal channels funding toward low-carbon production technology deployment in Ludwigshafen and Leverkusen manufacturing hubs. BASF SE operations exemplify buyer consolidation through direct tolling arrangements that compress spot market volumes.
India
Domestic specialty chemical expansion creates new regional demand centers in Gujarat and Maharashtra. The Bureau of Indian Standards oversees industrial gas quality specifications that shape import handling procedures. Dahej and Mundra port clusters attract acetic acid derivative investments requiring captive carbon monoxide supply arrangements.
Saudi Arabia
Petrochemical integration projects in Jubail Industrial City sustain merchant gas demand for methanol and derivative production. The Saudi Food and Drug Authority regulates industrial chemical handling protocols across Kingdom manufacturing zones. SABIC-affiliated operations anchor syngas supply chain development through partnerships with global industrial gas majors.
Carbon Monoxide Market Key Industry Players
Capacity expansion dominates the current landscape as industrial gas majors extend pipeline networks and on-site generation capabilities. The vendor base concentrates around three integrated industrial gas conglomerates controlling merchant supply distribution. Two strategic archetypes prevail: global infrastructure players leveraging hydrogen-syngas integration, and captive chemical producers consuming self-generated feedstock. M&A activity and strategic tolling partnerships represent the dominant competitive moves reshaping supply relationships.
Within the global infrastructure tier, Linde plc and Air Liquide exemplify scale-driven positioning through pipeline network control and proprietary partial oxidation technology deployment. Air Products and Chemicals, Inc. occupies a complementary position emphasizing on-site generation systems for chemical corridor customers. Celanese Corporation represents the captive consumption archetype, embedding carbon monoxide demand within integrated acetic acid manufacturing rather than merchant market participation.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products and Chemicals, Inc. |
| Messer SE & Co. KGaA |
| Celanese Corporation |
| Sipchem Company |
| American Gas Products |
| ATCO Atmospheric And Speciality Gases Private Limited |
| Axcel Gases |
| Others |
Cost & Logistics Intelligence
Specialized electrochemical sensor calibration expertise concentrated in Germany and the US Midwest creates labor-cost differentials that widen pricing-tier spreads between premium industrial-grade monitors and economy residential alarms. Natural gas feedstock volatility feeds directly into merchant carbon monoxide supply contracts, compressing margins for tolling arrangements while elevating spot market premiums.
Pricing Analysis
Input-cost pass-through clauses dominate long-term tolling agreements between chemical producers and industrial gas suppliers, embedding natural gas price exposure directly into carbon monoxide delivery contracts. Pricing stratifies across premium, standard, and economy tiers based on purity certification grade and volume commitment scale. Cost compression in the residential alarm segment intensifies because big-box retail channel consolidation concentrates buyer leverage. Homeowners exhibit the highest price sensitivity, while acetic acid manufacturers negotiating multi-year pipeline contracts demonstrate the least.
Supply Chain Analysis
Dual-sourcing requirements from OSHA-mandated safety system redundancy compel industrial facilities to qualify multiple electrochemical sensor suppliers, fragmenting procurement across domestic and Asian manufacturers. Merchant carbon monoxide supply concentrates in the United States, China, and Germany where pipeline infrastructure and on-site generation capabilities cluster. Production draws from natural gas feedstock, reformer catalysts, and membrane separation equipment. Single-source vulnerability around specialized sulfur-resistant electrolyte formulations poses structural risk. Distribution runs through direct pipeline delivery for industrial gas customers and retail channels for residential safety equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Process intensification in chemical manufacturing is compressing purity tolerances, shifting demand toward premium-specification carbon monoxide feedstock with continuous compositional certification.
For Market Incumbents: Cement pipeline network control through capacity additions in the US Gulf Coast and Rotterdam-Antwerp chemical corridors. Deepen backward integration into natural gas reforming infrastructure to offset feedstock volatility exposure. Invest in proprietary membrane separation R&D to defend against emerging solid-state sensing platforms threatening electrochemical detection dominance.
For New Entrants and Emerging Players: Solid-state CO sensing technology offers a technology-first wedge into residential and light commercial safety markets where calibration simplicity commands premium positioning. Target India's specialty chemical expansion in Gujarat and Maharashtra where domestic acetic acid capacity investments outrun local merchant gas infrastructure. Pursue tolling partnerships with regional industrial gas distributors rather than competing against established pipeline networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale membrane technology specialists with proven chemical plant integration track records. Long-term viability hinges on carbon capture integration capabilities as EU Green Deal funding channels toward low-carbon production pathways. Watch for inflection in electrochemical reduction technology cost curves signaling circular carbon monoxide production economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Gas Reforming | Celanese Corporation's captive consumption model eliminates merchant supply exposure and stabilizes feedstock costs. |
| Membrane Separation Technology Deployment | Polymer and metallic membrane adoption at BASF SE facilities achieves higher purity without cryogenic distillation capital. |
| Long-term Tolling Arrangement Expansion | Linde plc's pipeline-delivered contracts across Texas and Louisiana anchor demand visibility through energy cost pass-through clauses. |
| Carbon Capture Integration Partnership | EU Green Deal funding mechanisms support CO₂-to-CO electrochemical reduction pilots in Ludwigshafen manufacturing hubs. |
| Joint Venture in India Specialty Chemical Corridor | Dahej and Mundra port clusters attract acetic acid investments requiring localized on-site generation capabilities. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at acetic acid facilities, procurement leads at polyurethane producers, distribution channel partners in industrial gas supply, and technical R&D directors at detection equipment manufacturers. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings from listed chemical producers, EPA emissions databases, and ECHA REACH registration documentation. Bottom-up segment sizing and top-down macroeconomic anchoring provided cross-check triangulation.
Comparable-period anchoring established baseline demand patterns from historical acetic acid capacity utilization, methanol production runs, and safety equipment replacement cycles before projecting forward across the analysis window. The forecast framework modeled segmentation dimensions including purity grade tier, end-use application, detection technology type, and regional production hub clustering. CAGRs were derived from trend extrapolation of feedstock demand elasticities and regulatory-driven equipment replacement mandates. Industry-specific inputs incorporated OSHA inspection frequency data and EPA National Ambient Air Quality Standards enforcement patterns.
The model holds under stable natural gas pricing and continued OSHA workplace exposure mandate enforcement; deviation in hydrogen substitution rates for syngas applications or abrupt regulatory relaxation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
US Specialty Gas Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Asia-Pacific Syngas Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
North America Syngas Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Global Helium Gas Market