
 Micro-Magnetic Resonance Imaging Market | 2026-2036
Micro-Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Magnetic Resonance Imaging Market Intelligence
ISO 13485 certification is rotating the competitive set, forcing vendors to rebuild quality management systems around medical device directives before commercial traction. Siemens leverages its superconducting magnet foundry in Erlangen to sustain vertical control over field homogeneity. Bruker anchors the preclinical segment through cryogen-free micro-MRI architectures. Philips competes on integrated coil arrays that reduce scan times for small-animal protocols.
Micro-magnetic resonance imaging denotes high-field systems operating at 4.7 Tesla to 21 Tesla with bore diameters under 40 millimeters, engineered for ex vivo tissue specimens and rodent models requiring isotropic resolution below 100 micrometers. Gradient echo sequences dominate product configurations due to speed advantages in functional neuroimaging, while diffusion MRI technology captures the fastest growth as pharmaceutical sponsors adopt quantitative biomarkers for neurodegeneration trials. Spin echo protocols retain mature positions in oncology applications where T2 contrast differentiates tumor margins. Closed MRI systems concentrate margin pools through superconducting infrastructure lock-in, whereas extremity MRI configurations serve decentralized research budgets with lower capital barriers.
FDA 21 CFR Part 820 and EU MDR frameworks govern device qualification, with the former mandating design history files that extend premarket timelines and the latter imposing post-market surveillance obligations on importers. The EU AI Act introduces additional documentation burdens for reconstruction algorithms classified as high-risk medical software. Stakeholders must monitor how FDA guidance on quantitative imaging biomarkers reshapes reimbursement pathways for micro-MRI-derived endpoints in drug development contracts.
Market Dynamics
Superconducting magnet supply concentration in Germany and helium-3 isotope scarcity are compressing field homogeneity specifications while extending qualification timelines for preclinical imaging vendors.
Growth Catalysts
- Preclinical neuroscience protocols:Pharmaceutical sponsors require isotropic resolution below 100 micrometers for rodent functional neuroimaging, pulling high-field micro-MRI systems into toxicology and efficacy studies.
- FDA 21 CFR Part 820:Design history file requirements for medical device quality systems are filtering out undercapitalized entrants, concentrating procurement among qualified vendors with established regulatory track records.
- Cryogen-free architectures:Closed-cycle refrigeration technology eliminates liquid helium dependency, reducing operational fragility for imaging facilities in regions with constrained cryogenic logistics.
Market Restraints
- Helium-3 isotope supply:Nuclear non-proliferation treaties constrain polarized gas production for hyperpolarized MRI, limiting diffusion lung imaging expansion in preclinical respiratory studies.
- Gradient coil copper:Electromagnetic interference specifications for 21 Tesla systems require oxygen-free high-conductivity copper that concentrates among Japanese and German specialty metal processors.
- EU MDR post-market surveillance:Importer obligations for vigilance reporting extend liability chains, deterring smaller research institutions from direct procurement of non-EU manufactured systems.
Strategic Opportunities
- India preclinical CRO expansion:Contract research organizations in Hyderabad and Bengaluru are building small-animal imaging capacity to serve Western pharmaceutical outsourcing, creating pull for mid-field systems.
- AI reconstruction algorithms:Machine learning-based denoising converges with compressed sensing acquisition, enabling reduced scan times without gradient hardware upgrades.
- Japan METI innovation subsidies:National funding for quantum sensing infrastructure extends to high-field magnet development, supporting domestic vendor capability building.
Industry Challenges
- RF engineer scarcity:Specialized coil design expertise for sub-millimeter resolution at 4.7 Tesla and above concentrates among aging cohorts in Erlangen and Boston academic centers.
- ISO 13485 certification timelines:Medical device quality management system implementation stretches 18-24 months for preclinical equipment vendors transitioning from research-grade to regulated commercial supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Magnetic Resonance Imaging Market |
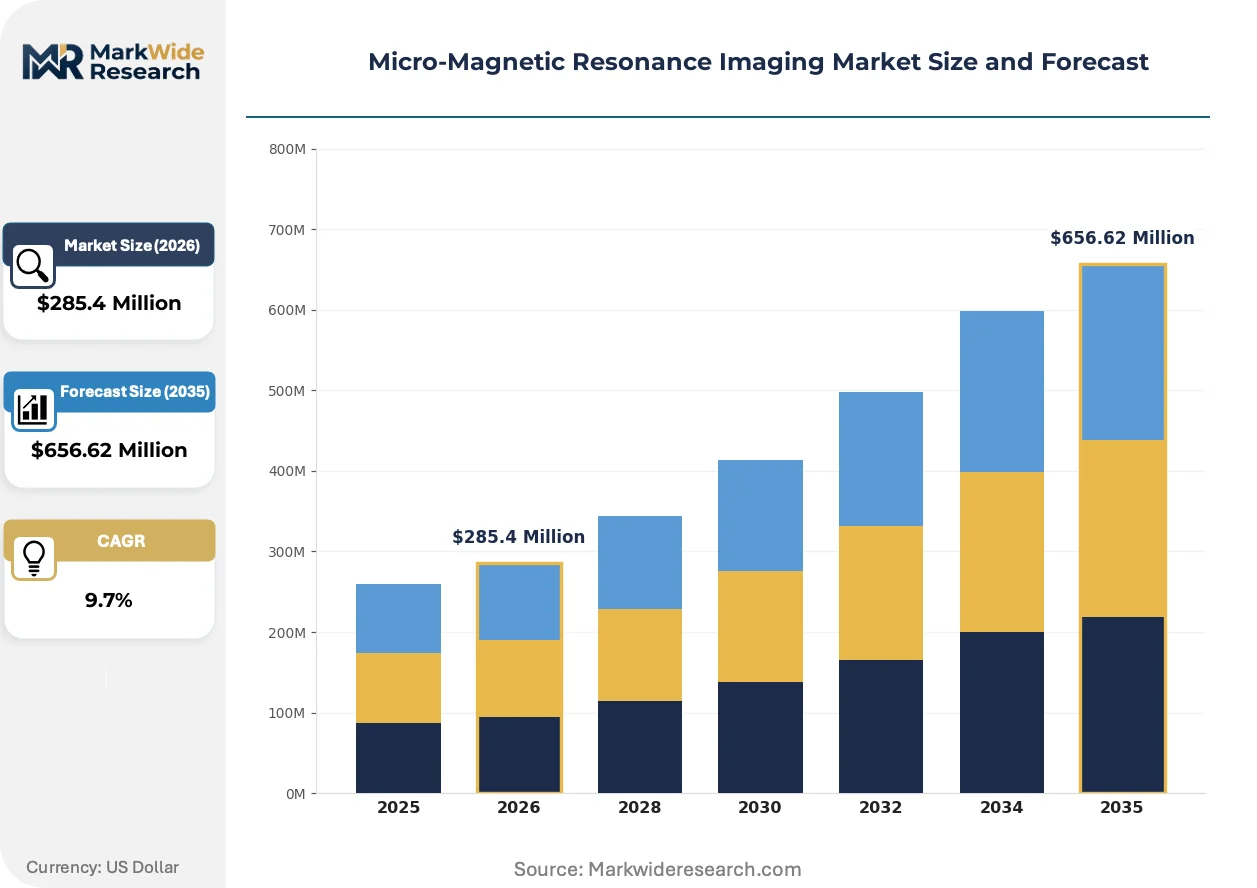
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $656.62 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Diagnostic Centers, Research Facilities, Academic Institutions Technology: Gradient Echo, Spin Echo, Echo Planar, Diffusion MRI Application: Neurology, Oncology, Musculoskeletal, Cardiovascular |
| Companies Covered | Siemens, General Electric, Koninklijke Philips N.V., Hitachi Ltd., CANON MEDICAL SYSTEMS CORPORATION, Aspect Imaging Ltd., ESAOTE SPA, Bruker, FONAR Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Magnetic Resonance Imaging Market Strategic Shifts & Innovations
Diffusion MRI protocols are capturing pharmaceutical sponsor attention as quantitative biomarkers enter neurodegeneration trial endpoints, while reconstruction algorithms face escalating documentation burdens under software-as-medical-device frameworks.
Cryogen-free superconducting magnets are supplanting liquid helium bath designs in preclinical installations. Contract research organizations operating multi-site toxicology programs prioritize these architectures to eliminate supply chain exposure to helium market volatility. The shift compresses total cost of ownership calculations and enables imaging facilities in helium-constrained geographies to field 9.4 Tesla systems previously restricted to major academic medical centers.
The EU AI Act's high-risk medical software classification is reshaping algorithm validation requirements for MRI reconstruction pipelines. Vendors must maintain technical documentation and post-market monitoring systems for deep learning-based image enhancement tools. European preclinical imaging facilities are responding by consolidating procurement around suppliers with established quality management systems rather than experimental academic spin-outs.
Pharmaceutical sponsors are unbundling hardware acquisition from service contracts, separating capital expenditure approval from operational support decisions. Research institutions now negotiate coil maintenance, gradient amplifier replacement, and field homogeneity certification as distinct line items. This pattern is most pronounced in North American academic medical centers where centralized procurement offices impose category management disciplines on preclinical imaging infrastructure.
Micro-Magnetic Resonance Imaging Market Segmentation
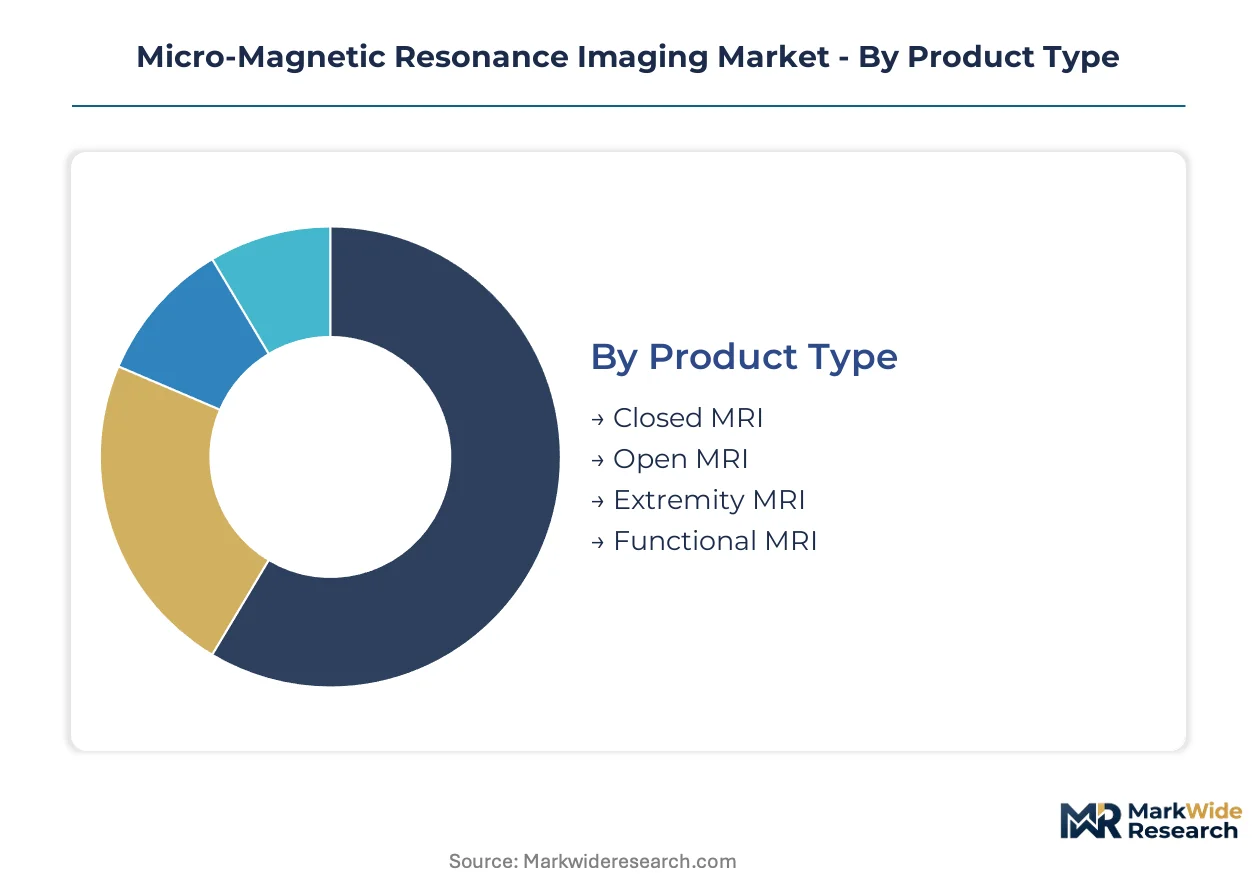
Micro-MRI segmentation reveals distinct procurement patterns across closed superconducting architectures and portable research configurations. Field strength requirements and regulatory qualification status determine vendor selection more than price in this capital-intensive equipment category.
Product Type:
Closed MRI systems concentrate manufacturing in Germany for export to North American and Asian research hubs, while extremity MRI configurations serve domestic markets with lower capital barriers.
- Closed MRI:Superconducting magnets operating at 4.7 Tesla to 21 Tesla with cryogen-free architectures eliminate liquid helium dependency. Pharmaceutical sponsors in Boston and Basel specify these systems for GLP-compliant toxicology studies requiring isotropic resolution below 100 micrometers.
- Extremity MRI:Lower-field permanent magnet designs target decentralized research budgets. Contract research organizations in Hyderabad and Bengaluru deploy these systems for preliminary screening before committing to high-field validation studies.
- Open MRI:C-shaped magnet geometries accommodate larger specimen chambers for non-rodent preclinical models. Academic medical centers prioritize these configurations for interventional imaging protocols.
- Functional MRI:Blood-oxygen-level-dependent sequences require specialized gradient coils with sub-millisecond switching. Neuroscience institutes in Cambridge and Stanford anchor demand for these research-dedicated platforms.
Closed MRI commands the established base. The steepest expansion runs through extremity MRI as emerging CRO markets prioritize capital efficiency.
End User:
Research facilities drive volume procurement through multi-system tenders, while academic institutions concentrate geographically around established magnet engineering clusters.
- Research Facilities:Preclinical imaging cores at pharmaceutical headquarters and dedicated CRO campuses operate 9.4 Tesla and 11.7 Tesla systems for IND-enabling studies. FDA 21 CFR Part 820 qualification requirements filter procurement toward vendors with established design history file capabilities.
- Academic Institutions:University imaging centers balance service revenue against grant-funded investigator access. Helium-3 isotope scarcity constrains hyperpolarized lung imaging expansion at these budget-sensitive sites.
- Hospitals:Clinical translation units bridge preclinical and patient imaging with 3 Tesla to 7 Tesla platforms. Radiation oncology departments specify micro-MRI for ex vivo tumor margin assessment.
- Diagnostic Centers:Independent imaging providers rarely field micro-MRI directly, instead outsourcing specialized preclinical protocols to academic partners or dedicated CRO networks.
Research facilities command the established base. The steepest expansion runs through academic institutions as national quantum sensing subsidies in Japan and Germany expand infrastructure grants.
Technology:
Gradient echo sequences dominate throughput-sensitive applications, while diffusion MRI captures sponsor investment as quantitative biomarkers enter neurodegeneration trial endpoints.
- Diffusion MRI:Quantitative tensor imaging generates biomarker data for pharmaceutical sponsors tracking white matter integrity in rodent neurodegeneration models. EU MDR documentation requirements for software-as-medical-device classification extend validation timelines for reconstruction algorithms.
- Gradient Echo:Rapid acquisition protocols enable functional neuroimaging with temporal resolution sufficient for hemodynamic response mapping. T2*-weighted contrast supports blood-oxygen-level-dependent signal detection in preclinical psychiatry studies.
- Spin Echo:T1 and T2 weighting retains mature positions in oncology applications where tissue contrast differentiation determines tumor margin delineation. Radiation therapy planning departments specify these sequences for treatment response assessment.
- Echo Planar:Single-shot acquisition reduces motion artifact in cardiac gating protocols. Cardiovascular research programs at academic medical centers prioritize these sequences for small-animal heart failure models.
Gradient echo commands the established base. The steepest expansion runs through diffusion MRI as regulatory qualification pathways for imaging-derived endpoints mature.
Application:
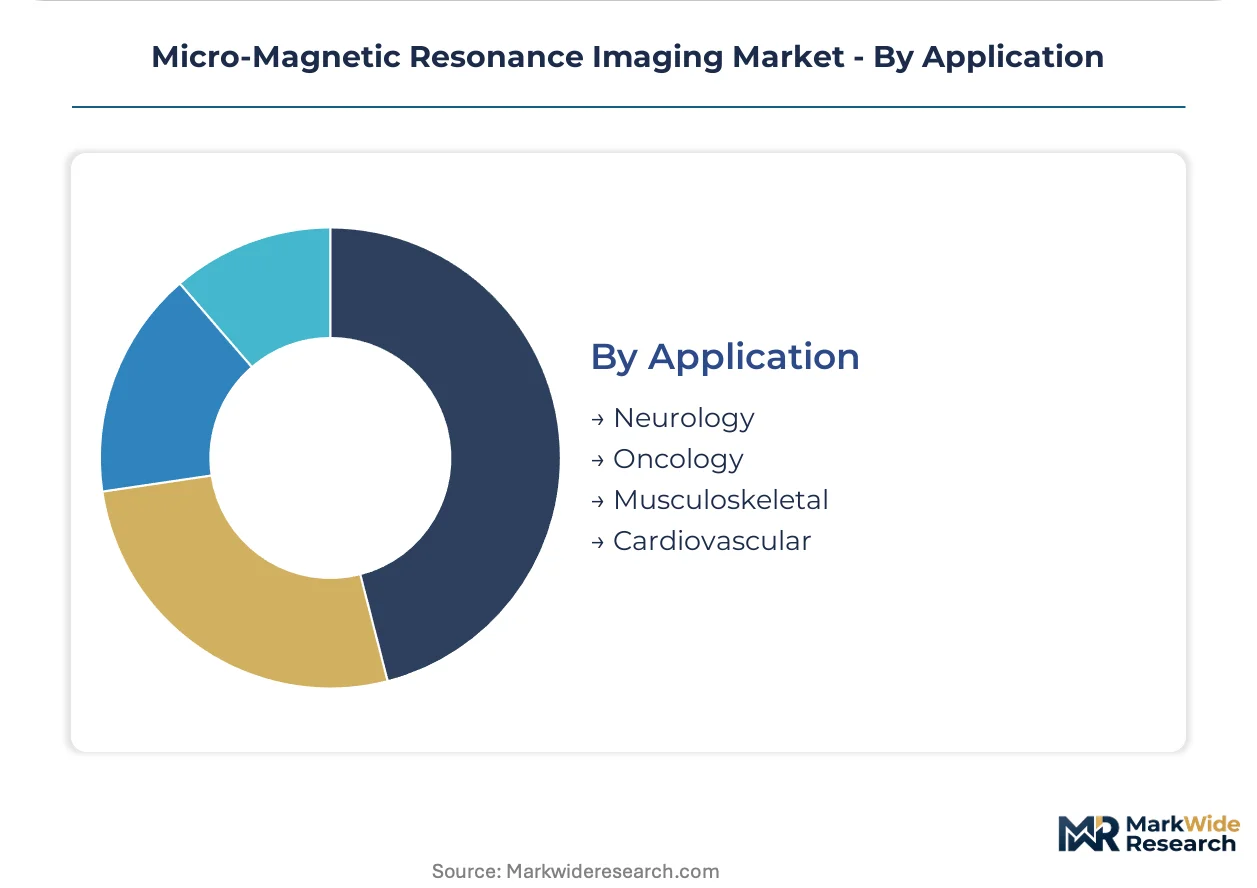
Neurology concentrates demand in high-field systems, while musculoskeletal applications tolerate lower field strengths with faster scan protocols.
- Neurology:Functional and structural neuroimaging at sub-100-micrometer resolution requires 7 Tesla and above for cortical layer delineation in rodent models. Preclinical CROs in Germany and Massachusetts anchor global demand for these specifications.
- Oncology:Tumor volume quantification and treatment response monitoring utilize T2-weighted contrast from spin echo sequences. Imaging cores at NCI-designated cancer centers standardize these protocols across multi-site trials.
- Musculoskeletal:Bone and soft tissue contrast at 4.7 Tesla serves orthopedic implant research and arthritis progression studies. Lower capital requirements expand addressable market to mid-tier research institutes.
- Cardiovascular:Cardiac gating and flow quantification protocols require specialized hardware configurations. Limited vendor expertise in radiofrequency coil design for small-animal cardiac imaging constrains segment expansion.
Neurology commands the established base. The steepest expansion runs through oncology as immuno-oncology trials adopt imaging-derived secondary endpoints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government innovation subsidies and specialized magnet engineering clusters are redrawing procurement geography for high-field preclinical imaging systems. National funding programs in quantum sensing infrastructure accelerate vendor capability building while regulatory qualification requirements concentrate demand among established manufacturing bases.
United States
Pharmaceutical sponsors in Boston and the San Francisco Bay Area anchor demand for GLP-compliant toxicology studies requiring sub-100-micrometer resolution. FDA 21 CFR Part 820 design history file requirements filter procurement toward vendors with established medical device track records. Academic medical centers in these coastal clusters operate multi-system imaging cores serving IND-enabling research contracts.
Germany
Bruker and Siemens maintain dense concentrations of precision magnet engineering expertise in Erlangen and Karlsruhe. EU MDR post-market surveillance obligations extend liability chains for importers, favoring domestic procurement. The country's superconducting magnet foundries sustain vertical control over field homogeneity specifications for export markets.
Japan
METI innovation subsidies for quantum sensing infrastructure extend to high-field magnet development programs. Domestic vendors leverage national funding to build capabilities in cryogen-free architectures. Research institutes in the Kanto region prioritize these systems to eliminate helium supply chain exposure.
India
Contract research organizations in Hyderabad and Bengaluru are constructing small-animal imaging capacity to serve Western pharmaceutical outsourcing. CDSCO medical device regulations shape importer qualification timelines for non-domestic equipment. Mid-field extremity MRI systems capture initial procurement as facilities balance capital constraints against validation study requirements.
China
NMPA medical device registration pathways extend premarket timelines for imported high-field systems. Domestic research hospitals in Beijing and Shanghai concentrate demand for preclinical neuroimaging platforms. National programs for scientific instrumentation self-sufficiency accelerate local vendor development in permanent magnet and gradient coil technologies.
Micro-Magnetic Resonance Imaging Market Key Industry Players
Listed leaders compete with private specialists across regulatory qualification capabilities and magnet engineering depth. The vendor set concentrates around three tiers: diversified conglomerates with medical device divisions, dedicated imaging equipment specialists, and component technology providers. Archetypal positioning separates full-system integrators from gradient or radiofrequency subsystem suppliers. Competitive moves center on cryogen-free architecture licensing and ISO 13485 certification acceleration.
Among diversified conglomerates, Siemens AG and General Electric occupy positions exemplifying integrated medical device supply. Bruker Corporation represents the dedicated preclinical imaging specialist archetype, anchoring demand in pharmaceutical toxicology segments. Koninklijke Philips N.V. sits within the tier emphasizing integrated coil array technologies for throughput-sensitive protocols. These three entities collectively illustrate how regulatory track records and magnet manufacturing control determine procurement access in high-field segments.
| Leading Market Players |
|---|
| Siemens |
| General Electric |
| Koninklijke Philips N.V. |
| Hitachi Ltd. |
| CANON MEDICAL SYSTEMS CORPORATION |
| Aspect Imaging Ltd. |
| ESAOTE SPA |
| Bruker |
| FONAR Corp. |
| Others |
Cost & Logistics Intelligence
FDA 21 CFR Part 820 quality system regulation gates both vendor qualification timelines and price stratification in micro-MRI procurement, concentrating premium pricing among ISO 13485-certified manufacturers while relegating research-grade suppliers to discounted tiers. Pharmaceutical sponsors in Boston and Basel absorb certification premiums for GLP-compliant toxicology systems, whereas academic institutions negotiate capital-efficient configurations with deferred service contracts.
Pricing Analysis
Certification level creates the primary spread across micro-MRI procurement tiers, with FDA-grade and CE-marked systems commanding substantial premiums over research-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects gradient field homogeneity specifications and coil array complexity. Cost compression in mid-field extremity configurations is intensifying because emerging CRO markets in India prioritize capital efficiency over peak performance specifications. Contract research organizations exhibit highest price sensitivity, while pharmaceutical headquarters procurement offices demonstrate lowest elasticity due to IND-enabling study requirements.
Supply Chain Analysis
Germany and Japan anchor superconducting magnet fabrication and specialty copper processing for high-field gradient coils. Oxygen-free high-conductivity copper draws from Japanese and German specialty metal processors, while liquid helium supply chains feed from Qatar and Algeria extraction facilities. Single-source vulnerability concentrates in polarized helium-3 isotope production constrained by nuclear non-proliferation treaties. Distribution runs through manufacturer-direct sales for closed superconducting systems, with regional service subsidiaries handling field homogeneity certification and gradient amplifier maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pharmaceutical procurement offices running multi-system tenders, fragmenting vendor pricing leverage across standardized specification sheets. This consolidation pressures margin retention for equipment specialists lacking differentiated service architectures.
For Market Incumbents: Fortify cryogen-free magnet manufacturing capabilities in Erlangen and Karlsruhe to sustain vertical control over field homogeneity specifications. Accelerate ISO 13485 certification pathways for reconstruction algorithms before EU AI Act documentation requirements harden competitive barriers. Lock in pharmaceutical sponsors through bundled coil maintenance and gradient amplifier replacement contracts that extend beyond capital depreciation cycles. For New Entrants and Emerging Players: Differentiate on AI reconstruction algorithm specialization for diffusion MRI protocols serving neurodegeneration trial endpoints. Target mid-field extremity MRI procurement at Indian CRO facilities in Hyderabad and Bengaluru where capital constraints outrank peak performance demands. Pursue licensing arrangements with established magnet foundries rather than greenfield manufacturing investments. For Investors and Strategic Acquirers: EU MDR post-market surveillance obligations reshape the acquisition landscape toward vendors with established quality management systems rather than experimental academic spin-outs. Long-term viability centers on regulatory track record durability and service contract recurrence over hardware shipment cycles. Monitor FDA guidance on quantitative imaging biomarkers as the inflection signal for reimbursement pathway expansion in drug development contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Architecture Licensing | Eliminates helium supply chain exposure for imaging facilities in constrained geographies. |
| ISO 13485 Certification Acceleration | Filters procurement access toward qualified vendors with established design history file capabilities. |
| AI Reconstruction Algorithm Validation | Addresses EU AI Act documentation burdens for deep learning-based image enhancement tools. |
| Service Contract Unbundling | Separates capital expenditure approval from operational support decisions in academic procurement. |
| India CRO Partnership Development | Captures Western pharmaceutical outsourcing demand for small-animal imaging capacity. |
Research Approach
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and pharmaceutical sponsor imaging protocol specifications preceded structured interviews with preclinical imaging core directors, regulatory affairs leads at device manufacturers, and procurement managers at contract research organizations. Secondary validation drew from SEC 10-K disclosures, patent filings in superconducting magnet architectures, and national quantum sensing program announcements. Bottom-up system shipment estimates triangulated against top-down pharmaceutical R&D expenditure allocations for imaging-derived endpoints.
Variance decomposition across product type, field strength tier, end-user category, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Diffusion MRI protocol adoption rates, cryogen-free architecture penetration curves, and AI reconstruction algorithm qualification timelines served as industry-specific forecast inputs. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion constraints.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical R&D expenditure growth or helium isotope supply stabilization would require recalibration. Forecasts reflect assumptions regarding regulatory pathway maturation for imaging-derived biomarkers and national subsidy program continuity for quantum sensing infrastructure. Recalibration cycles align with material shifts in FDA guidance publication and EU MDR enforcement precedent.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Visualiser Market
Imaging
IP Camera Market
Imaging
Global 3D Camera Market
Imaging
Global Image Processing Systems Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Global Mobile Image Sensor Market
Imaging
Global AI in Computer Vision Market
Imaging
Middle East and Africa Image Sensors Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Photography Equipment Market
Imaging
Global Whole Slide Imaging Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Global Image Sensors Market
Imaging
X Ray Tubes Market
Imaging
Camera Stabilizer Market