
 APAC Image Sensors Market | 2026-2036
APAC Image Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Image Sensors Market Outlook
Stack disaggregation between pixel processing and signal conditioning is fragmenting traditional integrated sensor architectures across the APAC Image Sensors Market. Sony Corporation leverages captive wafer capacity in Kumamoto to sustain leadership in high-resolution CMOS designs. Samsung Electronics Co., Ltd. anchors its foundry-linked sensor division through backward integration into 3nm logic processes. OmniVision Technologies, Inc. competes aggressively in automotive qualification tiers where tier-one OEMs demand ASIL-certified supply chains.
Image sensors are solid-state optoelectronic devices that convert photonic energy into electrical signals through arrays of photosensitive pixels, typically fabricated on silicon substrates using backside-illumination or stacked-die architectures, enabling machine vision, computational photography, and environmental perception. Their primary commercial purpose spans consumer device imaging, vehicular sensing, and industrial automation. CMOS technology dominates unit economics due to lower power draw and on-chip integration, while infrared segments capture premium margins in security and thermal fusion applications. Automotive application demand outpaces consumer electronics growth as lane-keeping and cabin-monitoring mandates proliferate across APAC vehicle fleets.
China's MIIT enforces GB standards for automotive camera modules and cybersecurity in connected vehicles, directly shaping sensor qualification pathways for domestic and foreign suppliers. Japan's METI coordinates national semiconductor strategies that channel subsidies toward image sensor R&D and domestic fab expansion. South Korea's MFDS and KATS frameworks govern medical imaging device certifications where endoscopic and dermatological sensors require biocompatibility and electromagnetic compliance. Stakeholders must monitor diverging national subsidy regimes and localization requirements that increasingly determine market access across Chinese, Japanese, and Korean supply ecosystems.
Market Dynamics
Stack disaggregation between pixel processing and signal conditioning is fragmenting traditional integrated sensor architectures across the APAC Image Sensors Market. This structural shift forces incumbents to defend captive wafer capacity while challengers exploit foundry-linked modular designs.
Growth Catalysts
- China's GB Standards:MIIT-enforced vehicle safety mandates for lane-keeping and cabin-monitoring systems are accelerating automotive camera module qualification cycles for domestic and foreign suppliers.
- Automotive ADAS Adoption:Tier-one OEMs across Japan, South Korea, and China are embedding multi-camera arrays into mass-market vehicle platforms, expanding addressable sensor volumes beyond premium segments.
- Silicon Cluster Concentration:Yangtze River Delta semiconductor foundries and Kyushu's silicon corridor provide captive substrate access that compresses time-to-market for next-generation backside-illumination designs.
Market Restraints
- Advanced Node Cost Escalation:Sub-28nm logic-layer integration for stacked-CIS devices requires capital-intensive EUV lithography, raising breakeven volumes for new product families.
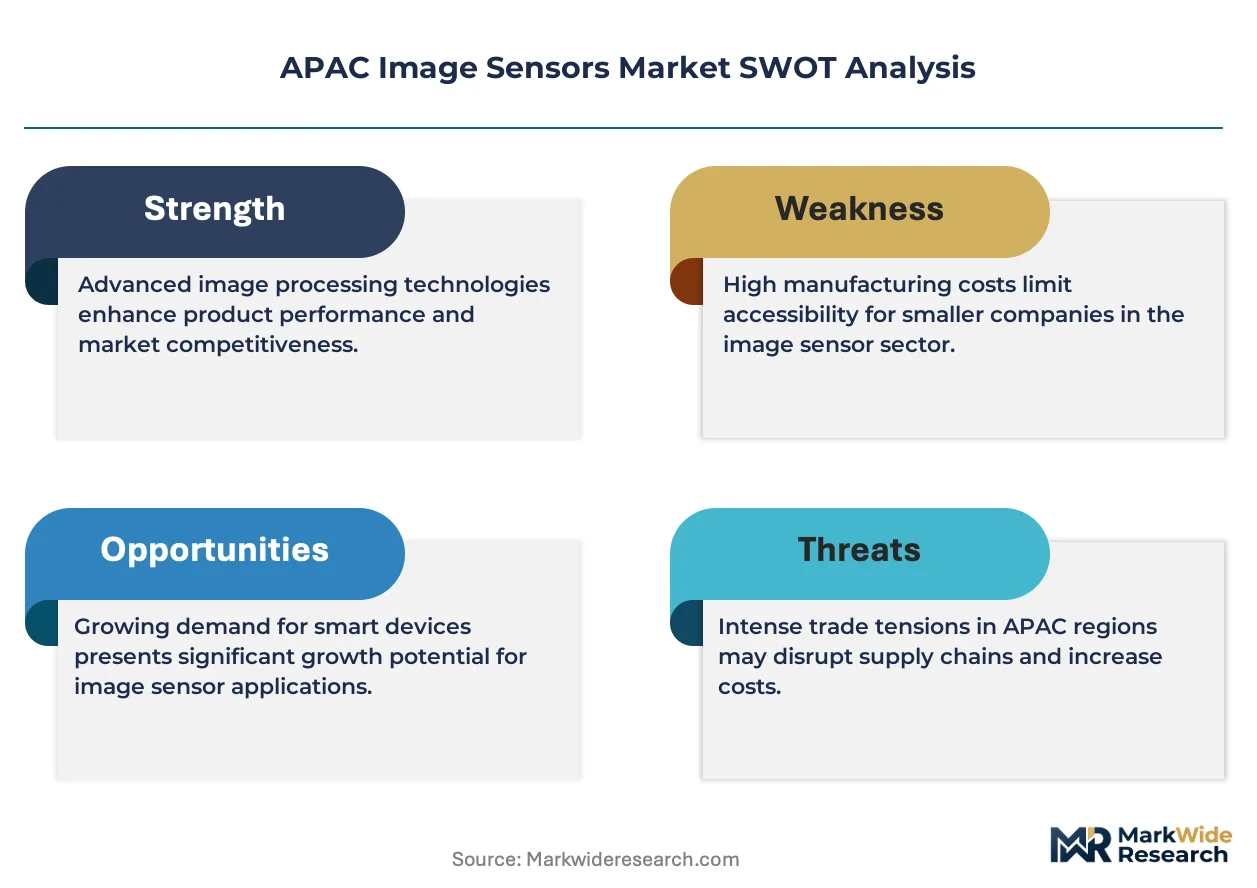
- Geographic Supply Concentration:Japan and South Korea control over 80% of specialized CIS wafer capacity, creating vulnerability to seismic disruption or export control friction.
- Infrared Sensor Substitution:Thermal fusion modules for night-driving applications compete directly with silicon-based near-infrared enhanced pixels in cost-sensitive vehicle segments.
Strategic Opportunities
- Southeast Asia Medical Imaging:Vietnam and Indonesia's expanding hospital networks drive demand for endoscopic and dermatological sensors requiring biocompatibility certification under MFDS-equivalent frameworks.
- 3nm Logic Convergence:Foundry-linked sensor divisions are integrating AI inference engines directly onto die, enabling real-time object classification without external ISP chips.
- India PLI Incentive Window:The country's production-linked incentive scheme for electronics manufacturing is attracting camera module assembly investments that localize final test and calibration stages.
Industry Challenges
- ASIL Certification Timelines:Automotive functional safety qualification for image sensors requires 18-24 month validation cycles that delay revenue recognition from design wins.
- Specialized Talent Scarcity:Mixed-signal pixel designers with expertise in backside-illumination quantum efficiency optimization command premium compensation that strains R&D budgets.
- IP Licensing Complexity:Patent thickets around stacked-die interconnect and phase-detection autofixel architectures create royalty stacking that erodes margins on mid-range products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Image Sensors Market |
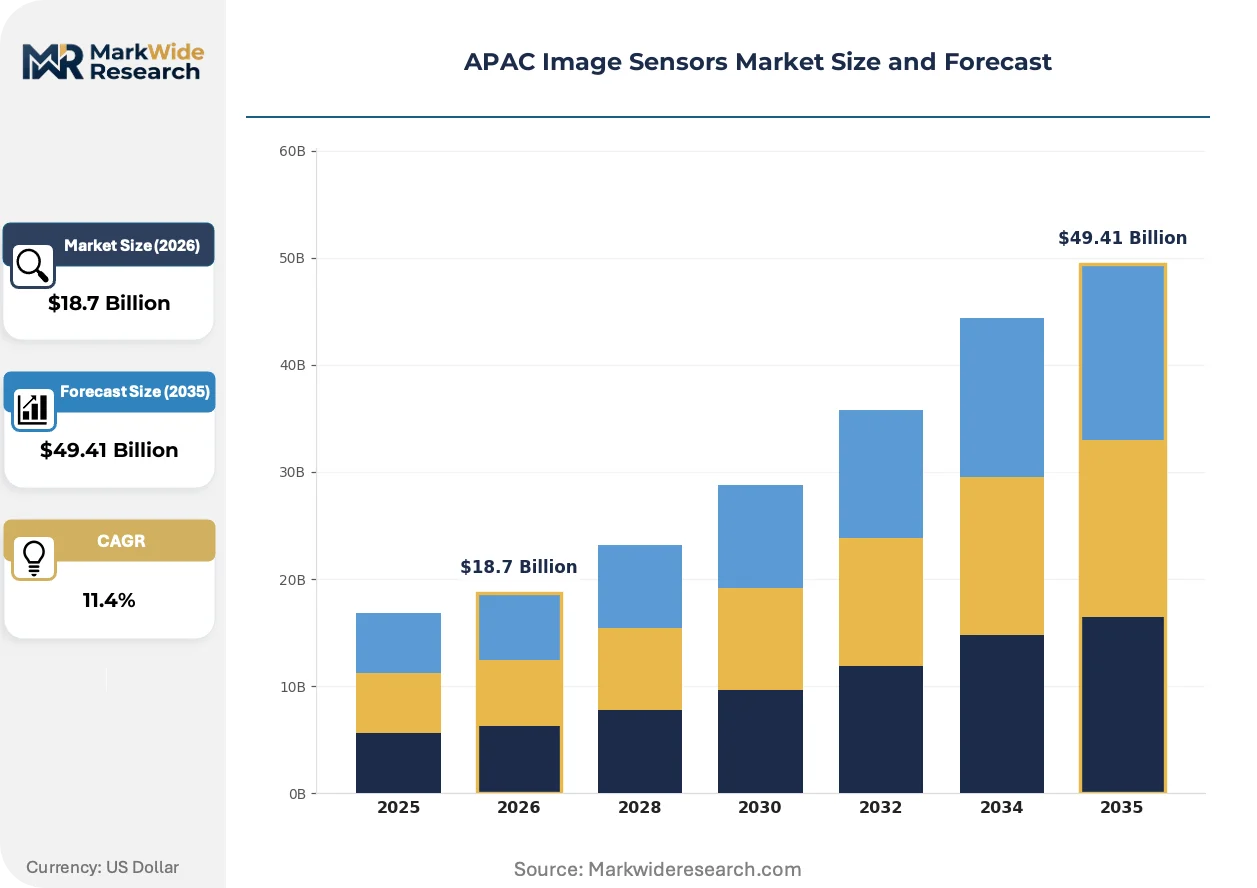
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
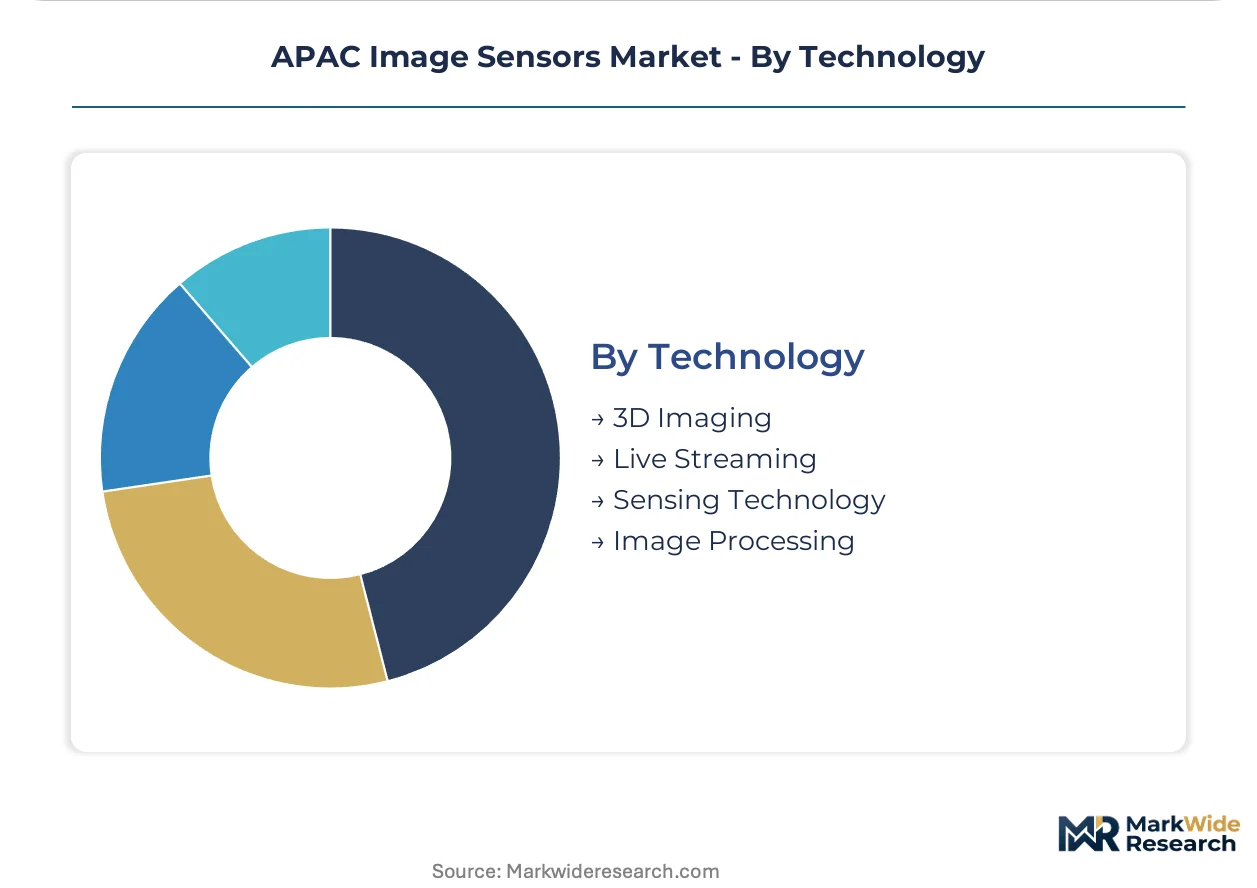
| Segmentation | Product Type: CCD, CMOS, Foveon, Infrared Application: Consumer Electronics, Automotive, Security & Surveillance, Medical Imaging End User: Manufacturers, Distributors, Retailers, Service Providers Technology: 3D Imaging, Live Streaming, Sensing Technology, Image Processing |
| Companies Covered | Sony Corporation, Samsung Electronics Co., Ltd., Canon Inc., OmniVision Technologies, Inc., ON Semiconductor Corporation, STMicroelectronics N.V., Panasonic Holdings Corporation, GalaxyCore Shanghai Limited Corporation, SK Hynix Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Image Sensors Market Strategic Shifts
Computational photography requirements and vehicular perception mandates are driving rapid architectural evolution in APAC sensor design. Three interconnected developments are compressing traditional development cycles and redrawing competitive boundaries.
Monolithic pixel-digital integration is collapsing the historical separation between photodiode arrays and signal processing blocks. Automotive OEMs in China and Japan are adopting these fused architectures for cabin-monitoring systems where latency constraints preclude off-chip data movement. The technology is collapsing the market for discrete ISP companion chips while elevating foundry process expertise as the primary competitive differentiator.
METI's national semiconductor strategy channels subsidies toward domestic image sensor R&D and Kumamoto fab expansion, directly shaping supplier qualification pathways for Japanese automotive tier-ones. The policy accelerates localization requirements that foreign competitors must satisfy through joint ventures or technology transfer agreements. Medical imaging device segments face parallel pressure from PMDA biocompatibility mandates that favor domestic supply chain documentation.
Direct foundry relationships are displacing traditional fabless-design-house intermediation in procurement patterns for high-volume smartphone and automotive programs. Chinese OEMs now negotiate wafer starts directly with Yangtze River Delta foundries, compressing margin capture by traditional sensor vendors. This channel shift is most visible in Shenzhen and Dongguan electronics corridors where module assemblers integrate die from multiple sources under white-label arrangements.
APAC Image Sensors Market Segmentation
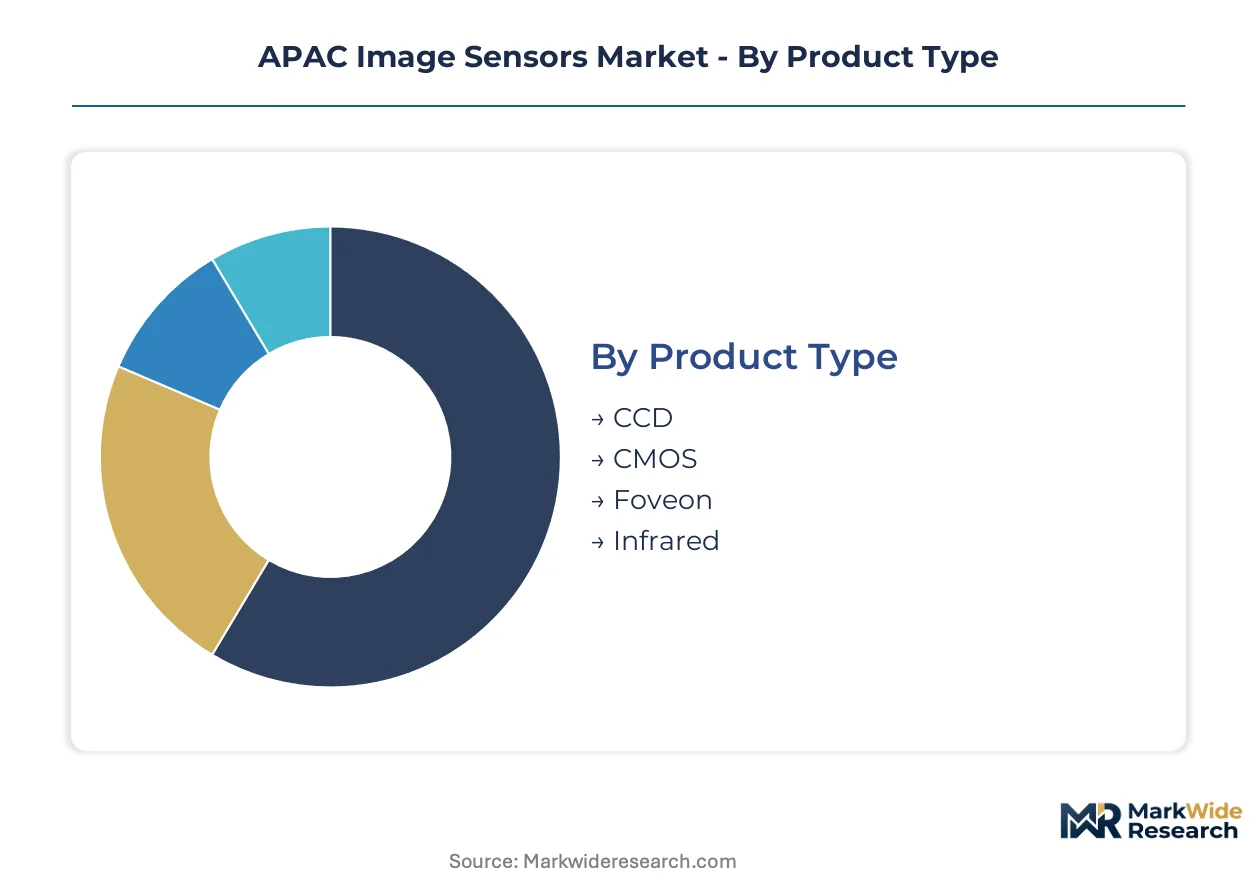
APAC image sensor procurement patterns diver sharply across end-use requirements, with automotive functional safety mandates and consumer miniaturization pressures driving incompatible specification roadmaps. Technology choices cascade through manufacturing economics, as backside-illumination and stacked-die architectures command premium wafer capacity that smaller segments cannot access.
Product Type:
Use-case spectrum spans legacy industrial inspection through emerging thermal fusion, with each technology occupying distinct performance-cost coordinates.
- CMOS:Dominant architecture employing active-pixel sensors with on-chip readout circuitry, enabling low-power integration for smartphone and automotive applications. China's Yangtze River Delta foundries and Japan's Kyushu corridor concentrate captive wafer supply for next-generation backside-illumination designs. Demand concentrates in smartphone camera modules where pixel-die stacking compresses module height.
- Infrared:Sensors detecting thermal radiation beyond 700nm wavelength, fabricated from indium gallium arsenide or microbolometer materials rather than silicon. South Korea's defense and security integrators drive adoption for perimeter monitoring and night-vision automotive systems. Premium margins reflect compound semiconductor material costs and limited foundry capacity.
- CCD:Charge-coupled devices with superior quantum efficiency for scientific and legacy industrial inspection, though CMOS displacement accelerates outside niche applications.
- Foveon:Vertical color separation architecture capturing full RGB data per pixel site, retaining relevance in professional photography segments requiring color fidelity.
Established volume favors CMOS; emerging adoption favors Infrared.
Application:
Cost tier stratification separates commodity consumer modules from ASIL-certified automotive programs requiring 18-24 month qualification cycles.
- Automotive:Multi-camera arrays for ADAS and cabin monitoring, subject to China's GB standards and Japan's vehicle type approval. Tier-one OEMs in Japan, South Korea, and China embed lane-keeping and driver-monitoring systems into mass-market platforms. MIIT-enforced mandates compress supplier qualification timelines for domestic and foreign module vendors.
- Consumer Electronics:Smartphone, tablet, and wearable camera modules where pixel-count competition and module height constraints dominate procurement. Chinese OEMs negotiate directly with Yangtze River Delta foundries, displacing traditional fabless intermediation.
- Security & Surveillance:Fixed and pan-tilt-zoom cameras for commercial and government infrastructure, with 4K resolution and low-light performance as primary differentiators.
- Medical Imaging:Endoscopic and dermatological sensors requiring biocompatibility certification under South Korea's MFDS and Japan's PMDA frameworks.
Consumer Electronics commands unit volume; Automotive climbs the fastest on regulatory mandate density.
End User:
Customer type determines margin capture, with manufacturers retaining value through captive design and retailers extracting distribution premiums.
- Manufacturers:Smartphone OEMs, automotive tier-ones, and medical device producers specifying custom sensor designs. Direct foundry relationships in Shenzhen and Dongguan electronics corridors enable white-label module integration from multiple die sources.
- Distributors:Channel intermediaries serving industrial automation and security integrators with lower volume, higher mix procurement patterns.
- Retailers:Consumer electronics chains and e-commerce platforms for replacement action cameras, webcams, and hobbyist equipment.
- Service Providers:Installation and maintenance contractors for surveillance infrastructure requiring field-replaceable sensor modules.
Manufacturers concentrate design-in value; Service Providers expand on installed base maintenance.
Technology:
Supply concentration in pixel-digital integration favors foundries with advanced logic-node capability.
- 3D Imaging:Time-of-flight and structured-light sensors enabling depth mapping for facial authentication and AR applications. Apple's supply chain in China and Japan drives VCSEL integration requirements.
- Image Processing:On-die ISP and AI inference engines collapsing discrete companion chip markets. Samsung's foundry-linked sensor division integrates 3nm logic for real-time object classification.
- Sensing Technology:Phase-detection autofixel and dual-pixel architectures for smartphone rapid-focus applications.
- Live Streaming:Optimized readout circuits for continuous video capture with reduced thermal drift.
Image Processing captures R&D investment; 3D Imaging gains share fastest on biometric authentication proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports high-resolution CMOS designs to automotive tier-ones in Germany and the United States, while China's Yangtze River Delta foundries supply die for smartphone assemblers across Southeast Asia. This trade-flow pattern concentrates advanced pixel processing in Japanese and Korean silicon corridors, with Chinese module integration dominating downstream assembly.
China
Automotive ADAS camera modules and smartphone sensors drive procurement volumes, with MIIT-enforced GB standards compressing supplier qualification timelines for lane-keeping systems. The country's dual carbon goals accelerate energy-efficient sensor designs for electric vehicle fleets. Yangtze River Delta foundries in Shanghai and Suzhou provide captive wafer capacity that shortens time-to-market for backside-illumination architectures.
Japan
High-resolution CMOS designs for professional imaging and automotive perception systems anchor demand, with METI's national semiconductor strategy channeling subsidies toward Kumamoto fab expansion. PMDA biocompatibility mandates favor domestic supply chain documentation for medical imaging segments. Kyushu's silicon corridor concentrates specialized CIS wafer capacity that serves tier-one OEMs across Asia and Europe.
South Korea
Smartphone camera modules and automotive multi-sensor arrays consume the majority of domestic production, with MFDS frameworks governing endoscopic sensor certifications for medical device exports. The country's foundry-linked sensor divisions exploit backward integration into advanced logic nodes. Busan-Ulsan industrial complexes anchor packaging and test operations for stacked-die architectures.
Vietnam
Expanding hospital networks and security infrastructure installations drive demand for endoscopic and surveillance sensors, with regulatory frameworks adopting MFDS-equivalent biocompatibility standards. The country's electronics manufacturing zones attract camera module assembly investments from Chinese and Korean vendors. Ho Chi Minh City and Hanoi corridors concentrate final test and calibration stages for regional distribution.
India
Production-linked incentive schemes for electronics manufacturing attract camera module assembly investments that localize final test operations, with automotive tier-ones embedding driver-monitoring systems into mass-market platforms. The country's central pharmaceutical regulator enforces electromagnetic compliance for medical imaging imports. Delhi-NCR and Tamil Nadu industrial corridors host module integration facilities serving domestic OEMs.
APAC Image Sensors Market Competitive Environment
Channel-controlling players compete with product-specialist players across the APAC Image Sensors Market, with consolidated wafer capacity in Japanese and Korean hands facing modular challenges from foundry-linked fabless designers. The structure tiers between captive fabs with backward integration into substrate supply and design houses relying on Yangtze River Delta foundry partnerships. Three archetypes dominate: vertically integrated conglomerates with logic-process capabilities, fabless specialists in automotive qualification tiers, and module assemblers exploiting white-label die sourcing. Competitive moves concentrate on strategic partnerships for ASIL-certified supply chains and capacity expansion in 3nm logic-layer integration.
Within the vertically integrated tier, Sony Corporation and Samsung Electronics Co., Ltd. occupy positions that exemplify foundry-captive sensor production, while OmniVision Technologies, Inc. sits within the fabless specialist archetype competing aggressively in automotive qualification tiers. GalaxyCore Shanghai Limited Corporation represents the module-assembly vector exploiting direct foundry relationships in Chinese electronics corridors. These three anchors illustrate the strategic divergence between substrate control and design flexibility that defines competitive positioning across the region.
| Leading Market Players |
|---|
| Sony Corporation |
| Samsung Electronics Co., Ltd. |
| Canon Inc. |
| OmniVision Technologies, Inc. |
| ON Semiconductor Corporation |
| STMicroelectronics N.V. |
| Panasonic Holdings Corporation |
| GalaxyCore Shanghai Limited Corporation |
| SK Hynix Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Japan's Kyushu silicon corridor and South Korea's specialized CIS wafer fabs is compressing supplier pricing power while accelerating foundry-linked modular sourcing from Yangtze River Delta alternatives. China's MIIT-enforced GB standards for automotive camera modules tighten qualification thresholds that segment buyers by certification tier, with ASIL-certified supply chains commanding structural premiums over consumer-grade alternatives.
Pricing Analysis
Next-generation stacked-CIS devices at sub-28nm logic nodes carry 40-60% wafer cost premiums over prior-generation backside-illumination designs, while legacy CCD architectures face accelerating price erosion from CMOS displacement. Pricing stratifies across premium, standard, and economy tiers based on ASIL certification grade and volume scale, with automotive tier-ones least price-sensitive due to 18-24 month qualification lock-ins. Cost compression in smartphone camera modules intensifies because Chinese OEMs negotiate wafer starts directly with Yangtze River Delta foundries, bypassing traditional sensor vendor margins.
Supply Chain Analysis
Export-control friction around EUV lithography equipment and advanced-node logic processes is fragmenting traditional supplier relationships across the APAC Image Sensors Market. Geographic supply concentration centers on Japan, South Korea, and China, with raw material dependencies spanning silicon substrates from Shin-Etsu, specialized photoresists, and indium gallium arsenide for infrared segments. Single-source vulnerability in Kumamoto and Busan-Ulsan packaging clusters creates seismic and geopolitical exposure. Distribution runs through Shenzhen and Dongguan electronics corridors where module assemblers integrate white-label die from multiple foundry sources.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC Image Sensors Market sits at an inflection where automotive ADAS mandates and computational photography requirements are collapsing traditional architectural boundaries. China's GB standards and Japan's METI semiconductor subsidies are accelerating localization requirements that reshape competitive positioning.
For Market Incumbents: Build captive wafer capacity moats through backward integration into substrate supply and 3nm logic-layer processes. Sony Corporation and Samsung Electronics Co., Ltd. should expand Kumamoto and Pyeongtaek fab allocations to defend against foundry-linked challengers exploiting Yangtze River Delta partnerships. Invest in ASIL-D certification pipelines to lock in automotive tier-one design wins before 18-24 month validation cycles delay revenue recognition for competitors. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia's medical imaging segments where MFDS-equivalent biocompatibility frameworks create qualification barriers lower than automotive tiers. Target endoscopic and dermatological sensor applications in Ho Chi Minh City and Hanoi hospital networks. Pursue direct foundry relationships with Yangtze River Delta foundries for white-label module integration, bypassing traditional fabless-design-house intermediation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across stacked-die CIS architectures requiring EUV lithography, favoring asset-light fabless specialists with automotive qualification expertise over vertically integrated conglomerates. Over the projection horizon, acquisition targets should demonstrate ASIL-certified supply chains and direct OEM relationships in China's GB-standard compliance pathways. Monitor MIIT subsidy disbursement velocity as the signal indicating domestic supplier preference intensity.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL Certification Pipeline Investment | Accelerates revenue recognition from automotive tier-one design wins under China's GB standards. |
| Direct Foundry Partnership Establishment | Compresses margin capture by traditional sensor vendors in Shenzhen module assembly corridors. |
| 3nm Logic-Layer Integration | Enables real-time AI inference on-die for cabin-monitoring systems in Japanese automotive platforms. |
| Southeast Asia Medical Imaging Expansion | Captures endoscopic demand from Vietnam's hospital network growth under MFDS-equivalent frameworks. |
| Kumamoto Fab Capacity Expansion | Secures captive substrate access for high-resolution CMOS designs serving European automotive exports. |
Study Parameters
A spread of perspectives from automotive tier-one procurement officers, CMOS foundry process engineers, medical device regulatory affairs leads, and smartphone OEM supply chain managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation from MIIT GB standard filings, METI semiconductor subsidy disclosures, PMDA biocompatibility registration databases, and Yangtze River Delta foundry capacity announcements. Bottom-up segment sizing triangulated against top-down semiconductor trade flow data from customs authorities across Japan, South Korea, China, and Vietnam.
Demand-supply balance modeling anchored forecast outputs, with segmentation dimensions spanning product type, application tier, technology node, and end-user archetype across the analysis window. CAGRs derived from installed base projections for automotive camera modules and smartphone unit shipments, cross-referenced with pixel-density roadmaps and ASP erosion curves. Industry-specific inputs included ASIL certification timeline distributions, EUV lithography capacity ramps, and biocompatibility framework adoption lags in Southeast Asian medical device markets.
Sensitivities concentrate around export-control escalation affecting EUV equipment shipments, seismic disruption in Kyushu's silicon corridor, and MIIT subsidy retrenchment altering domestic supplier qualification pathways. Forecasts reflect assumptions about GB standard enforcement consistency and METI funding continuity. Material shifts in automotive ADAS mandate timelines or foundry node transition delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
Biophotonics Market
Imaging
Global Mobile Image Sensor Market
Imaging
Automotive 3D Imaging Market
Imaging
Semiconductor CD-SEM Systems Market
Imaging
CMOS Camera Market
Imaging
Europe Machine Vision Systems Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Global Image Signal Processor Market
Imaging
Global CMOS Image Sensors Market
Imaging
CCD Image Sensors Market
Imaging
X-Ray Market
Imaging
Printed Image Sensors Market
Imaging
Global Pathology Imaging Systems Market
Imaging
Photo Kiosk Market
Imaging
Ultra-Wide Field Imaging Device Market