
 Whole Slide Imaging Systems Market | 2026-2036
Whole Slide Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Whole Slide Imaging Systems Market Analytics
The Whole Slide Imaging Systems market is restructuring around a sharp split between premium multispectral platforms and commodity brightfield scanners. Hamamatsu Photonics K.K. leverages its photomultiplier tube heritage to dominate fluorescence-capable instruments. Leica Biosystems anchors the clinical workflow segment with tightly integrated slide preparation-to-imaging pipelines. Nikon Corporation competes on optical precision for research-intensive buyers who prioritize resolution over throughput.
Whole slide imaging systems digitize glass pathology slides at sub-micron resolution, typically capturing 20x or 40x magnification across tissue sections up to 25 x 75 mm, producing multi-gigabyte image files for remote diagnosis and computational analysis. Scanner hardware claims the largest revenue pool as capital equipment refresh cycles shorten. Software solutions represent the fastest-expanding margin category as pathologists demand AI-powered quantification tools. Cloud-based solutions are displacing on-premise storage architectures in multi-site hospital networks.
FDA 510(k) pathways and the EU Medical Device Regulation shape product development timelines and clinical validation requirements for manufacturers seeking diagnostic claims. ISO 15189 accreditation standards for pathology laboratories drive scanner reliability specifications and calibration protocols. Stakeholders must monitor evolving reimbursement decisions for digital pathology services by Medicare and national health authorities, as these determine hospital procurement budgets and scanner utilization rates.
Market Dynamics
Scanner hardware commoditization is squeezing margins for brightfield-only vendors while AI-integrated platforms command pricing premiums. The FDA's digital pathology guidance update is compressing clinical validation timelines and forcing R&D budget reallocations toward algorithm development.
Growth Catalysts
- Telepathology reimbursement maturation:Medicare's expanded coverage for remote diagnostic services in the United States is accelerating hospital procurement cycles for multi-site compatible systems.
- AI-assisted diagnostic algorithms:Machine learning tools for quantitative immunohistochemistry are reducing pathologist review time and driving software attach rates.
- Academic medical center digitization:Research-intensive institutions in Germany and Japan are deploying multispectral platforms for translational oncology studies.
Market Restraints
- Photomultiplier tube supply concentration:Japanese and Dutch suppliers dominate fluorescence detection components, creating input bottlenecks for multispectral scanner production.
- EU Medical Device Regulation compliance costs:Clinical validation requirements for diagnostic claims are extending product development timelines by 18-24 months.
- Storage infrastructure requirements:Multi-gigabyte image files demand enterprise-grade PACS integration, limiting adoption in resource-constrained community hospitals.
Strategic Opportunities
- Cloud-native pathology platforms:Multi-site hospital networks in the United States are displacing on-premise storage with subscription-based image management.
- Companion diagnostic workflows:Pharmaceutical sponsors require standardized digital pathology data packages for oncology trial submissions.
- Japan's regulatory streamlining:PMDA's accelerated review pathway for AI-enabled devices is attracting algorithm developers seeking early market entry.
Industry Challenges
- Computational pathology talent scarcity:Hybrid skill sets combining histology expertise with machine learning implementation remain rare in diagnostic laboratories.
- Legacy LIS integration complexity:Proprietary data formats from incumbent scanner vendors create interoperability friction with third-party AI tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whole Slide Imaging Systems Market |
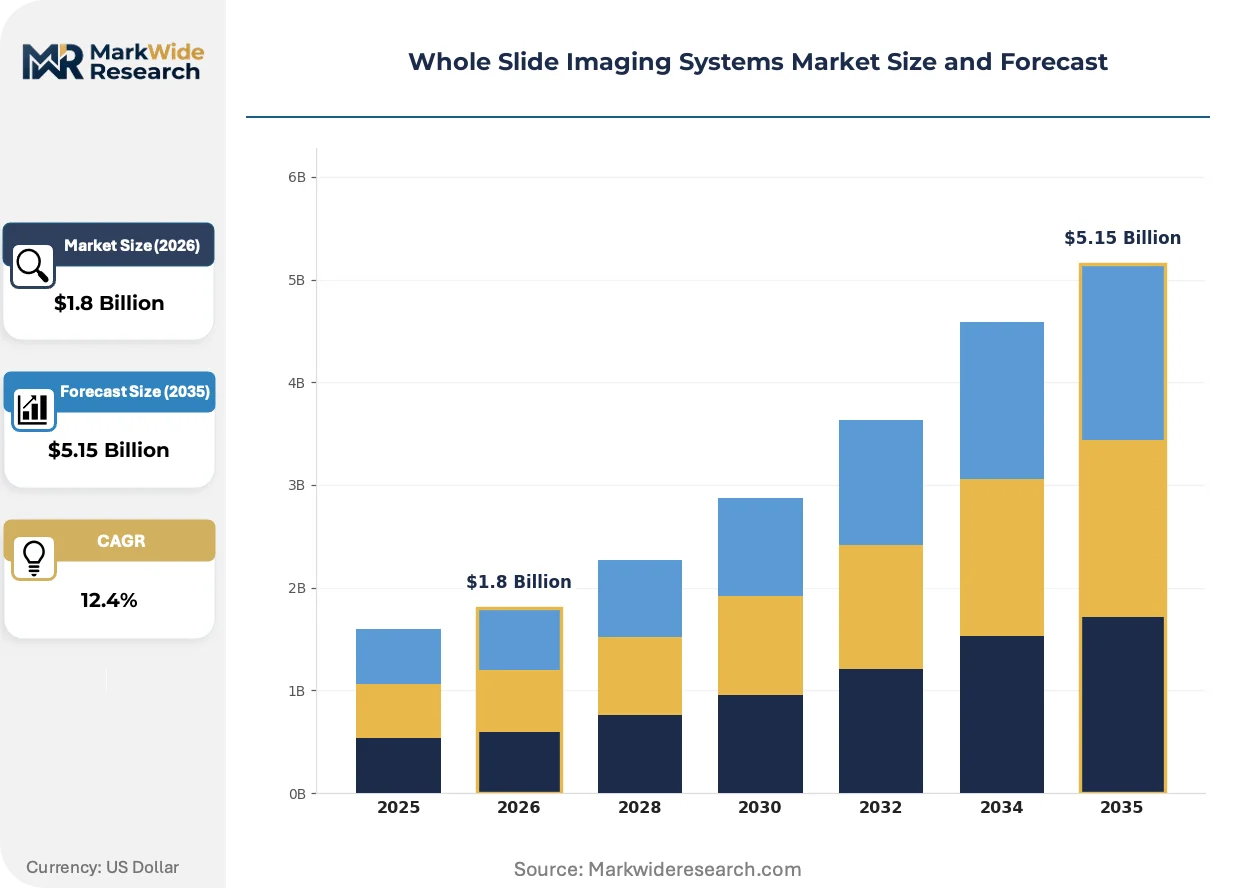
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscope Systems, Scanners, Software Solutions, Accessories End User: Pathology Labs, Research Institutes, Educational Institutions, Hospitals Technology: Digital Imaging, Whole Slide Scanning, Image Analysis, Cloud-Based Solutions Application: Diagnostics, Research, Education, Telepathology |
| Companies Covered | Koninklijke Philips N.V., Nikon Corporation, Hamamatsu Photonics K.K., Indica Labs, Visiopharm, Leica Biosystems, Olympus Corporation, Akoya Biosciences, 3DHISTECH Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whole Slide Imaging Systems Market Evolving Landscape
Fluorescence multiplexing capabilities are differentiating next-generation platforms from commodity brightfield scanners. Regulatory frameworks for algorithm-based diagnostic claims are evolving faster than clinical validation standards can adapt.
Multiplexed immunofluorescence imaging is rewriting tissue biomarker quantification workflows. Oncology pathology departments at tertiary centers are adopting 30-plex panels for immune profiling. This capability is compressing the timeline from tissue acquisition to comprehensive biomarker reporting.
EU AI Act risk classification rules are reshaping liability frameworks for diagnostic algorithms. Manufacturers must demonstrate clinical robustness across diverse patient populations. High-risk pathology AI tools face conformity assessment requirements that favor established players with regulatory affairs infrastructure.
Pathology service unbundling is fragmenting traditional vendor relationships. Academic medical centers now procure scanners, image analysis software, and storage infrastructure from separate suppliers. Germany's university hospital networks exhibit the most advanced multi-vendor procurement sophistication.
Whole Slide Imaging Systems Market Segmentation
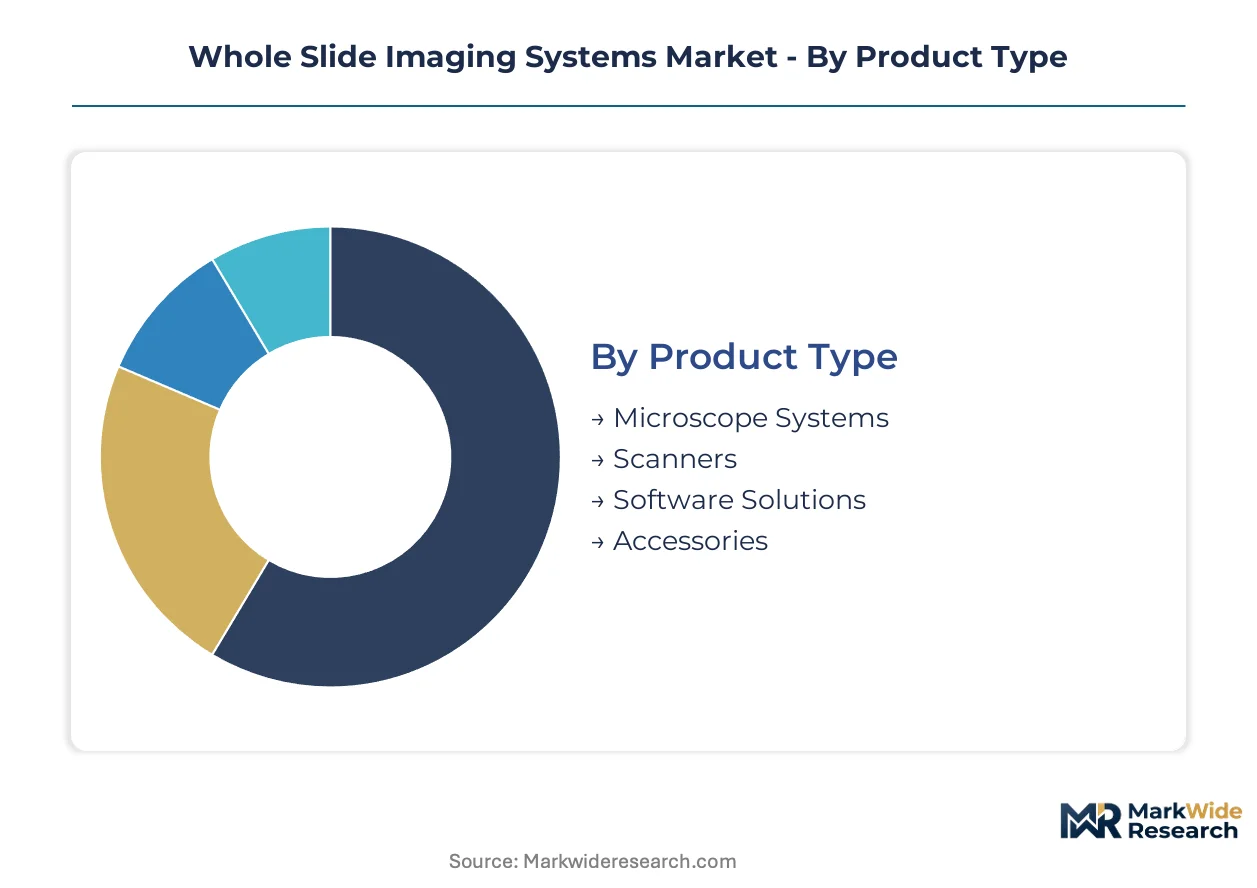
Capital allocation across product tiers determines competitive positioning in whole slide imaging. Scanner hardware absorbs the largest procurement budgets while software attach rates drive margin expansion for integrated vendors.
Product Type:
Scanner platforms demand the steepest upfront capital outlays, with fluorescence-capable multispectral instruments commanding premium pricing over brightfield-only units.
- Scanners:Automated slide digitization systems capture 20x or 40x magnification across tissue sections up to 25 x 75 mm, producing multi-gigabyte image files. Academic medical centers in Germany prioritize fluorescence multiplexing capabilities for translational oncology workflows.
- Software Solutions:AI-powered quantification tools for immunohistochemistry analysis reduce pathologist review time and command recurring subscription revenue. Cloud-native platforms are displacing on-premise storage in United States multi-site hospital networks.
- Microscope Systems:Traditional optical microscopes with digital camera attachments serve entry-level digitization needs in resource-constrained settings.
- Accessories:Slide loaders, barcode readers, and calibration standards ensure scanner throughput and regulatory compliance.
Most installed capacity flows through Scanners. Expansion is steepest in Software Solutions.
End User:
Procurement authority and reimbursement access create distinct customer tiers, with hospital networks leveraging scale for pricing leverage unavailable to standalone laboratories.
- Hospitals:Integrated delivery networks in the United States deploy enterprise-grade whole slide imaging across multiple sites, driven by Medicare's expanded telepathology reimbursement. IT infrastructure budgets accommodate cloud-based storage architectures.
- Pathology Labs:Commercial diagnostic laboratories prioritize throughput and turnaround time, favoring high-capacity brightfield scanners with minimal fluorescence capability. EU Medical Device Regulation compliance costs constrain capital refresh cycles.
- Research Institutes:Japan's translational oncology centers adopt 30-plex multiplexed immunofluorescence panels for immune profiling studies.
- Educational Institutions:Medical schools require basic digitization for remote teaching, with procurement constrained by institutional budget cycles.
Procurement volume concentrates in Hospitals. Research Institutes show the steepest technology upgrade frequency.
Technology:
Architecture choices between on-premise and cloud deployment reshape vendor competitive dynamics and customer switching costs.
- Whole Slide Scanning:Core digitization technology producing sub-micron resolution images across entire tissue sections. Scanner hardware refresh cycles are shortening as AI integration becomes standard.
- Cloud-Based Solutions:Subscription image management platforms enable multi-site collaboration without enterprise PACS infrastructure. United States hospital networks lead displacement of on-premise storage.
- Image Analysis:Computational algorithms for quantitative biomarker assessment face EU AI Act conformity assessment requirements for high-risk diagnostic claims.
- Digital Imaging:Foundational capture technology encompassing sensor arrays, optical path engineering, and color calibration protocols.
Deployment volume runs through Whole Slide Scanning. Cloud-Based Solutions are climbing the fastest.
Application:
Reimbursement maturation and regulatory validation requirements segment addressable markets by time-to-revenue for algorithm developers.
- Diagnostics:Clinical-grade whole slide imaging for primary diagnosis requires FDA 510(k) clearance or EU MDR conformity assessment. Medicare reimbursement decisions in the United States determine hospital procurement urgency.
- Telepathology:Remote diagnostic services leverage digitized slides for pathologist consultation across geographic distances. Germany's reimbursement frameworks for telepathology have matured ahead of other European markets.
- Research:Non-diagnostic applications bypass clinical validation timelines, accelerating algorithm iteration for pharmaceutical companion diagnostic development.
- Education:Teaching workflows prioritize accessibility and annotation tools over diagnostic-grade image quality or regulatory compliance.
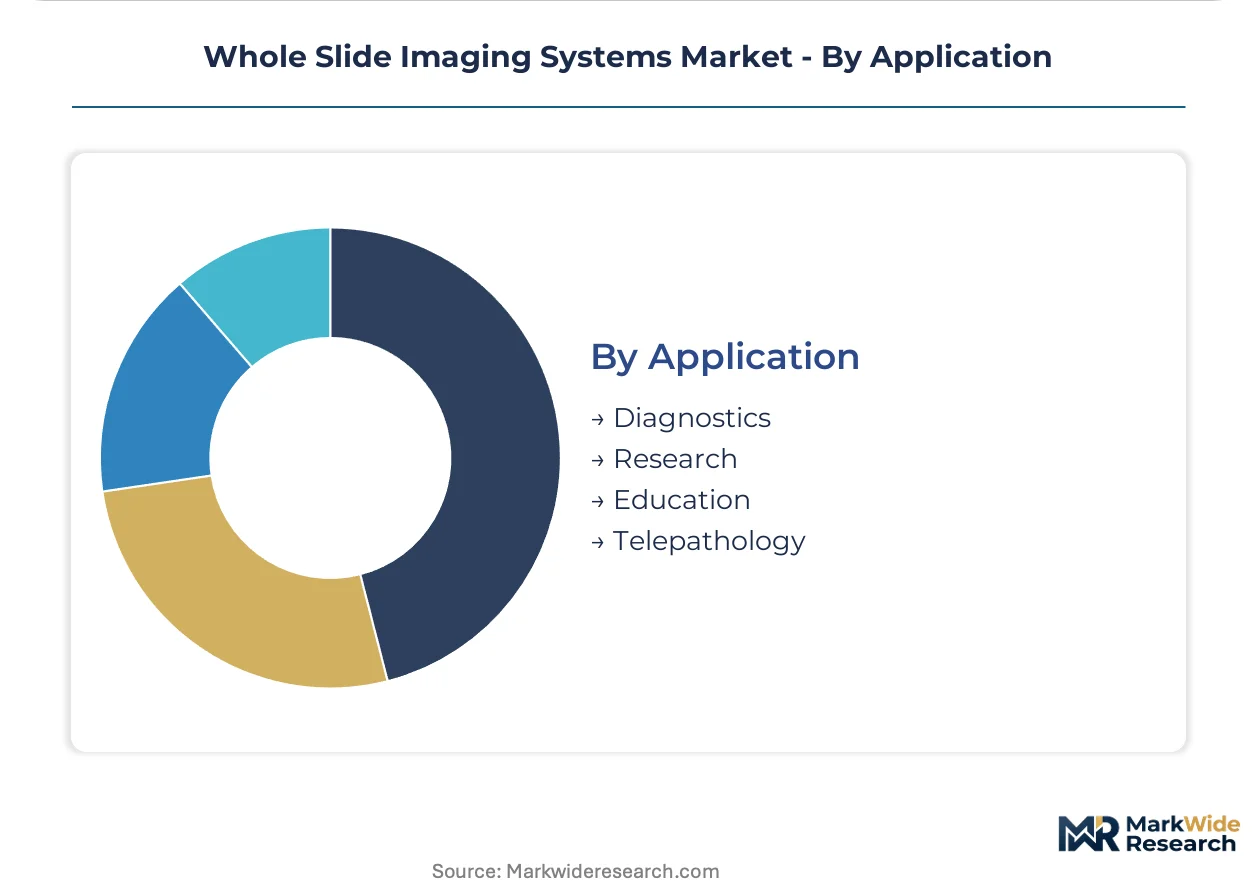
Revenue concentration sits in Diagnostics. Telepathology is gaining share fastest as reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pathologist density and research infrastructure concentration shape geographic deployment patterns for whole slide imaging systems. The United States, Germany, and Japan anchor procurement volumes through mature reimbursement frameworks and translational oncology investment.
United States
Medicare's expanded telepathology reimbursement accelerates hospital procurement cycles for multi-site compatible systems. The FDA's digital pathology guidance update compresses clinical validation timelines for AI-assisted diagnostic algorithms. The Boston-Cambridge corridor concentrates biopharma R&D spending, driving demand for companion diagnostic workflow standardization.
Germany
University hospital networks exhibit advanced multi-vendor procurement sophistication for translational oncology platforms. The EU Medical Device Regulation shapes product development timelines through clinical validation requirements for diagnostic claims. Heidelberg and Munich anchor multispectral scanner deployment for immune profiling studies.
Japan
PMDA's accelerated review pathway for AI-enabled devices attracts algorithm developers seeking early market entry. METI funding for digital health infrastructure supports pathology laboratory modernization. Tokyo and Osaka metropolitan areas concentrate fluorescence-capable instrument installations for cancer research institutes.
United Kingdom
NHS pathology network consolidation creates procurement leverage for enterprise-grade imaging platforms. MHRA alignment with EU MDR standards maintains regulatory continuity for scanner manufacturers. The Cambridge-London corridor drives demand for cloud-native image management in academic medical centers.
China
NMPA regulatory streamlining for innovative medical devices accelerates market entry for digitization platforms. National cancer center designation programs expand pathology infrastructure budgets. Shanghai and Beijing concentrate domestic scanner assembly capacity and AI algorithm development.
Whole Slide Imaging Systems Market Competitive Landscape
Top-tier vendors anchor the premium multispectral segment, while mid-tier specialists compete on throughput optimization for clinical workflows. The vendor base stratifies across fluorescence-capable platforms, brightfield-optimized systems, and AI-integrated software stacks. Optical heritage players and digital-native entrants represent distinct strategic archetypes. Competitive moves concentrate on regulatory pre-clearance partnerships and cloud infrastructure alliances.
Among Japanese precision optics specialists, Hamamatsu Photonics K.K. and Nikon Corporation occupy positions reflecting photomultiplier tube heritage and research-grade optical engineering respectively. Leica Biosystems represents the clinical workflow integration archetype. These three exemplify how vendor origin shapes competitive positioning—Hamamatsu anchors fluorescence detection capabilities, Nikon serves resolution-prioritizing research buyers, and Leica tightens slide preparation-to-imaging pipelines.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Nikon Corporation |
| Hamamatsu Photonics K.K. |
| Indica Labs |
| Visiopharm |
| Leica Biosystems |
| Olympus Corporation |
| Akoya Biosciences |
| 3DHISTECH Ltd. |
| Others |
Value Network & Pricing Analysis
Computational pathology specialists concentrated in Boston-Cambridge and Heidelberg widen pricing-tier spreads between premium AI-integrated platforms and commodity brightfield scanners, as labor-cost differentials in algorithm development cascade through vendor margin structures.
Pricing Analysis
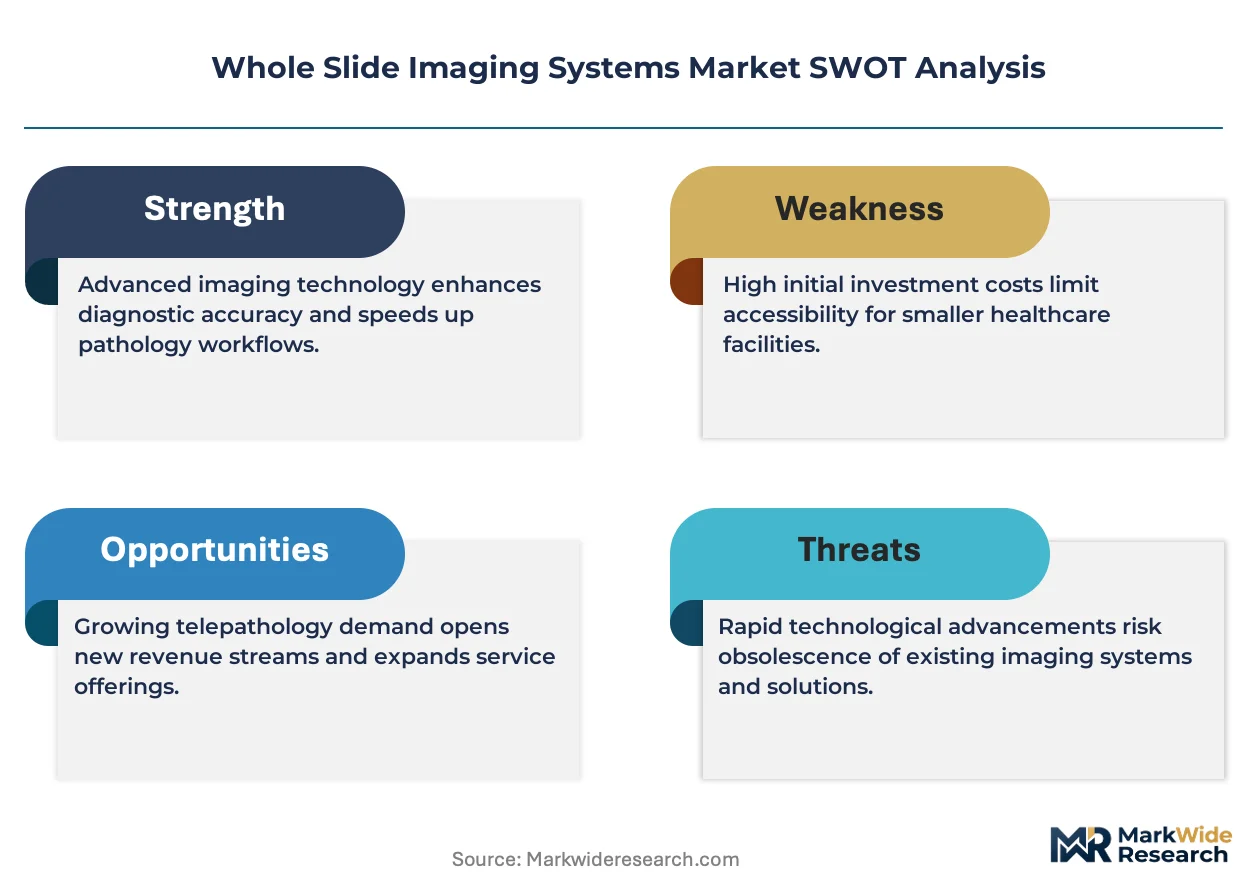
The bundled-vs-unbundled service split separates scanner-hardware vendors from standalone software providers. Three-tier pricing structure across premium multispectral, standard brightfield, and economy refurbished levels tracks FDA certification status and fluorescence capability. Pricing pressure stems from hardware commoditization in brightfield-only segments. Community hospital buyers exhibit acute price sensitivity, while academic medical centers prioritize capability over unit cost.
Supply Chain Analysis
Workforce-availability constraints in Japanese and Dutch photomultiplier tube manufacturing geographies limit fluorescence-detector output. Component supply concentrates in Japan, Germany, and the Netherlands for optical assemblies, sensors, and precision motion systems. Production draws from single-source dependencies for high-sensitivity detectors. Tariff exposure on precision optical components threatens margin stability. Distribution runs through direct vendor-hospital relationships and specialized microscopy distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Whole Slide Imaging Systems market functions as a stable compounder, with Medicare telepathology reimbursement decisions in the United States providing predictable procurement-cycle visibility.
For Market Incumbents: Cement regulatory pre-clearance advantages by deepening FDA 510(k) submission pipelines and acquiring cloud-native image-management platforms. Cloud-native entrants threaten installed-base retention. Certification investment in EU MDR conformity assessment preserves European pricing power. For New Entrants and Emerging Players: Cloud-based SaaS distribution routes offer the lowest-friction entry path for algorithm developers. White-space concentrates in community hospital telepathology and pharmaceutical companion-diagnostic data packaging. Target United States pathology labs with subscription-based AI quantification tools. Reimbursement-coding advisory services differentiate go-to-market positioning. For Investors and Strategic Acquirers: Diagnostic laboratory chains are the most active acquirer in this space, consolidating scanner fleets and software stacks under single procurement umbrellas. Long-term viability hinges on AI algorithm attach rates exceeding hardware refresh cycles. Acquisition targets should demonstrate regulatory affairs infrastructure and hospital GPO contract access. Watch FDA digital pathology guidance updates as inflection signals for algorithm-validation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Advancement | Pre-market notification clearance accelerates clinical validation timelines for AI-assisted diagnostic algorithms. |
| Cloud-Native Platform Integration | Multi-site hospital networks in the United States displace on-premise storage with subscription architectures. |
| Companion Diagnostic Partnership | Pharmaceutical sponsors require standardized digital pathology data packages for oncology trial submissions. |
| Fluorescence Capability Expansion | Multispectral instruments command pricing premiums over commodity brightfield-only scanners. |
| EU MDR Conformity Assessment | Clinical validation requirements for diagnostic claims extend product development timelines substantially. |
Research Methodology
Multiple input streams — primary interviews with pathologists and hospital procurement officers, regulatory filing analysis, and reimbursement database review — were reconciled to construct market estimates. Conversations with biomedical engineers, GPO contracts managers, and digital pathology software developers informed demand-side assumptions. Secondary sources included FDA 510(k) clearances, EU MDR notified body opinions, CMS Medicare reimbursement decisions, and hospital procurement records. Bottom-up scanner shipment estimates and top-down pathology-laboratory spending analysis were cross-validated.
Historical vendor revenue trajectories were cross-referenced against expert panel inputs regarding telepathology reimbursement maturation. Segmentation modeling encompassed product type, end-user category, deployment architecture, and application across the projection horizon. CAGRs were derived from fitted growth curves incorporating capital-equipment refresh cycles and software attach-rate trends. Forecast inputs included PMDA accelerated review pathway utilization rates and academic medical center digitization budgets.
The model assumes a particular technology adoption path; alternative pathways for cloud-native image management would alter the outlook. Forecasts reflect assumptions regarding Medicare reimbursement stability and EU MDR implementation consistency. Material deviation in FDA digital pathology guidance or photomultiplier tube supply availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Printed Image Sensors Market
Imaging
Global Acoustic Cameras Market
Imaging
Digital Microscope Market
Imaging
Live Cell Imaging Market
Imaging
Borescope Market
Imaging
CMOS Camera Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Mobile Camera Module Market
Imaging
Low-Light Imaging Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
EUV Mask Inspection System Market
Imaging
360-Degree Camera Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Global 4K Camera Market