
 ESG Sensor Data Quality and Validation Test Platforms Market | 2026-2036
ESG Sensor Data Quality and Validation Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
ESG Sensor Data Quality and Validation Test Platforms Market Insights
Platform bundling with embedded calibration protocols is hardening as the dominant procurement pattern for certification agencies and utility providers. Honeywell International leverages its distributed sensing hardware portfolio to anchor hybrid validation architectures across industrial sites. Siemens competes through deep automation integration, while Bureau Veritas sustains its position via accredited third-party verification workflows tied to regulatory disclosure cycles.
ESG Sensor Data Quality and Validation Test Platforms comprise integrated systems that verify accuracy, completeness, and traceability of environmental, social, and governance data captured through IoT sensor networks, typically processing throughput rates exceeding 10,000 readings per second with sub-1% tolerance thresholds. These platforms serve industrial and commercial operators requiring auditable data streams for regulatory filings, carbon accounting, and supply chain attestation. Hardware-based platforms still occupy the largest revenue share due to capital-intensive calibration infrastructure, though cloud-native deployments are recording the fastest expansion as manufacturers seek elastic compute for seasonal reporting spikes. Machine learning technology leads R&D allocation among platform developers, while regulatory compliance applications generate the most consistent procurement volume from certification agencies facing expanded CSRD audit scopes.
The EU Green Deal and CSRD framework mandate granular sustainability disclosures that directly expand demand for ISO-compliant validation infrastructure across European industrial operators. EMA environmental guidelines and ECHA substance reporting protocols further tighten data quality specifications for pharmaceutical and chemical manufacturers. Stakeholders must monitor how rapidly national regulators transpose EU-level disclosure mandates into enforceable audit standards that determine platform certification requirements.
Market Dynamics
CSRD audit scope expansion is compressing procurement cycles for certification-grade validation infrastructure as European industrial operators face binding disclosure deadlines with traceability mandates.
Growth Catalysts
- EU Green Deal disclosure mandates:Binding sustainability reporting requirements under CSRD force industrial operators to deploy ISO-compliant sensor validation systems for auditable environmental data streams.
- Financial services climate stress-testing:Banks and insurers deploying scenario analysis tools require verified sensor inputs for portfolio-level carbon exposure modeling and regulatory capital allocation.
- Machine learning inference at edge:Embedded AI processors in validation hardware enable real-time anomaly detection without cloud latency, accelerating adoption in continuous emissions monitoring.
Market Restraints
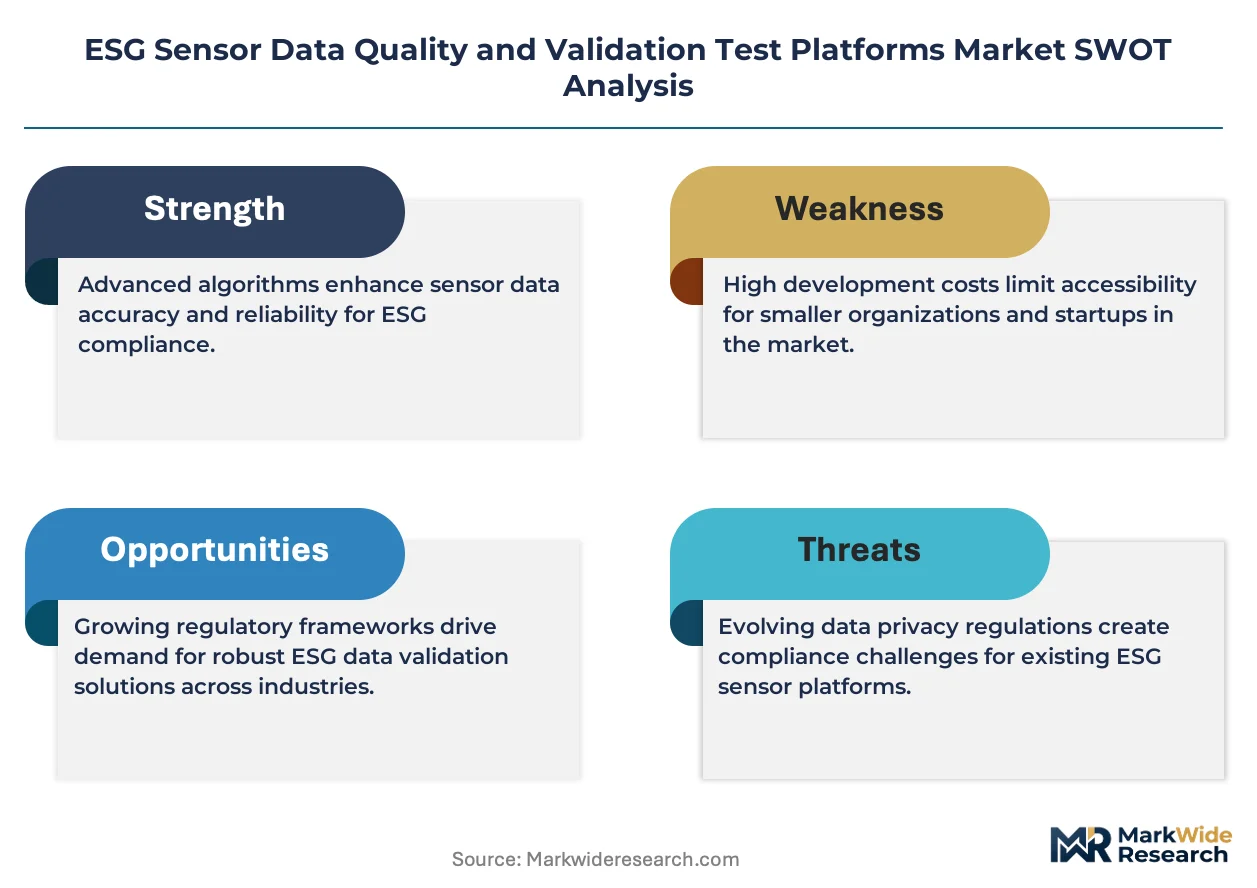
- Calibration infrastructure capex:Reference-grade metrology equipment and climate-controlled laboratory facilities impose fixed cost barriers for mid-scale platform providers.
- Specialized sensor supply concentration:High-precision electrochemical and optical sensing elements depend on limited German and Swiss component manufacturers.
- Cross-border data residency friction:GDPR localization requirements complicate cloud-native platform architectures for multinational industrial operators with distributed sensor fleets.
Strategic Opportunities
- India industrial decarbonization:BIS standards alignment with international sustainability frameworks creates demand for import-compatible validation platforms as domestic manufacturing scales.
- Digital twin convergence:Integration between sensor validation systems and industrial simulation software enables predictive calibration scheduling and reduced downtime.
- Subscription-based validation services:Equipment-as-a-service models lower entry barriers for smaller certification agencies facing intermittent CSRD audit volumes.
Industry Challenges
- Metrology talent scarcity:Shortage of calibration engineers with ISO 17025 accreditation extends implementation timelines for complex multi-sensor deployments.
- Legacy SCADA integration complexity:Proprietary protocols in installed industrial automation systems require custom middleware development for seamless data traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESG Sensor Data Quality and Validation Test Platforms Market |
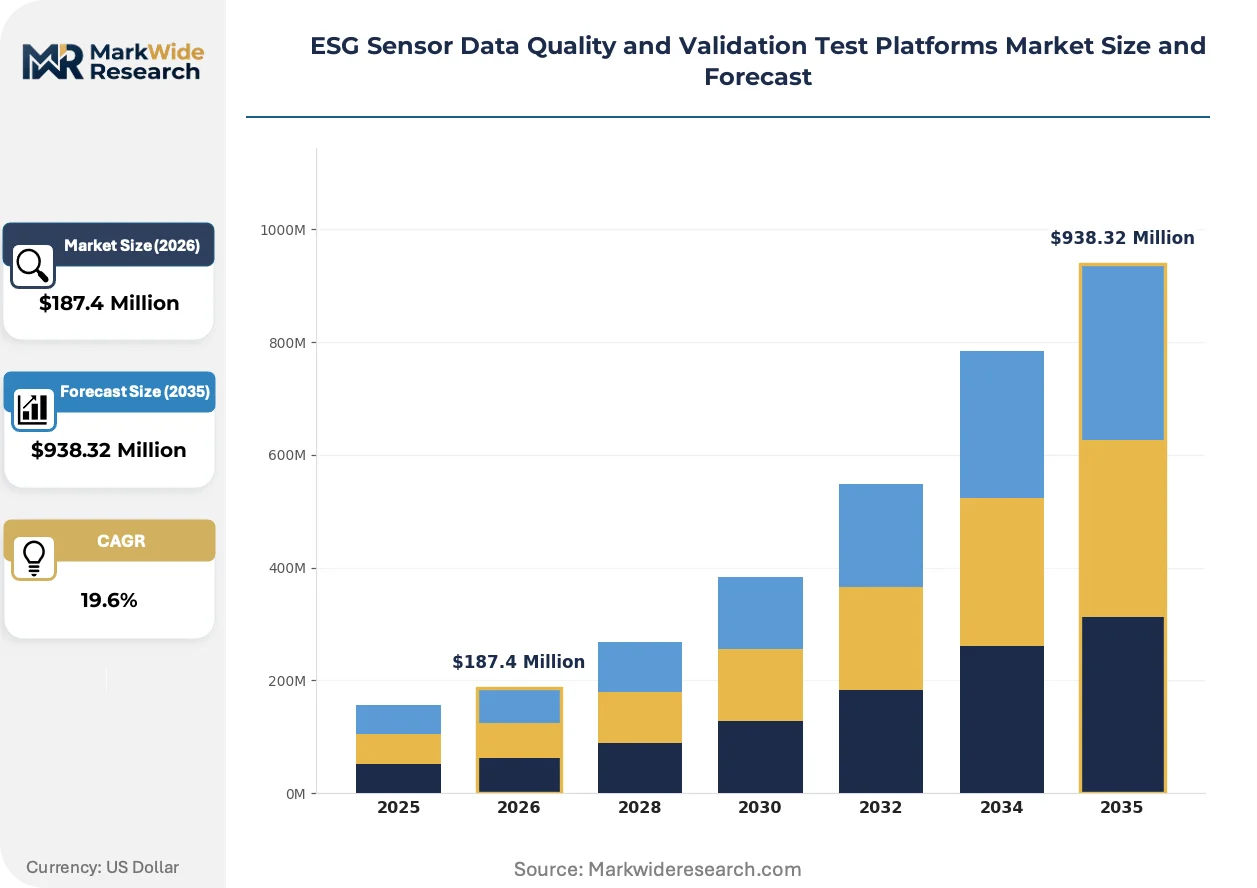
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $938.32 Million |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Hardware-Based, Software-Based, Hybrid, Cloud-Native Technology: IoT Analytics, Machine Learning, Edge Computing, Blockchain Application: Environmental Monitoring, Supply Chain Transparency, Energy Management, Regulatory Compliance End User: Manufacturers, Utility Providers, Certification Agencies, Research Institutions |
| Companies Covered | Honeywell International, Siemens, ABB, Emerson Electric, British Standards Institution, Bureau Veritas, DNV, SGS, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESG Sensor Data Quality and Validation Test Platforms Market Trends and Innovations
Distributed ledger architectures and federated learning protocols are restructuring how validation platforms establish data provenance without centralizing sensitive industrial telemetry.
Edge-native machine learning inference is absorbing pattern-recognition workloads that previously required round-trip cloud processing. Chemical manufacturers with continuous emissions monitoring obligations are deploying tensor-processing units directly on validation gateways. This compression of compute geography is absorbing latency-sensitive use cases from centralized SaaS architectures.
CSRD phased implementation timelines are forcing disclosure granularity upgrades across EU member states. Industrial conglomerates in Germany face the earliest compliance windows, accelerating procurement of dual-redundant validation chains. Certification agencies are responding by pre-positioning accredited third-party verification capacity ahead of national transposition deadlines.
Consolidated procurement by industrial platform vendors is displacing direct sensor manufacturer relationships. Large automation integrators in the Rhine-Ruhr manufacturing corridor now specify validation requirements across entire facility footprints. This bundling concentrates specification-setting power with systems integrators rather than end-use operators.
ESG Sensor Data Quality and Validation Test Platforms Market Segmentation
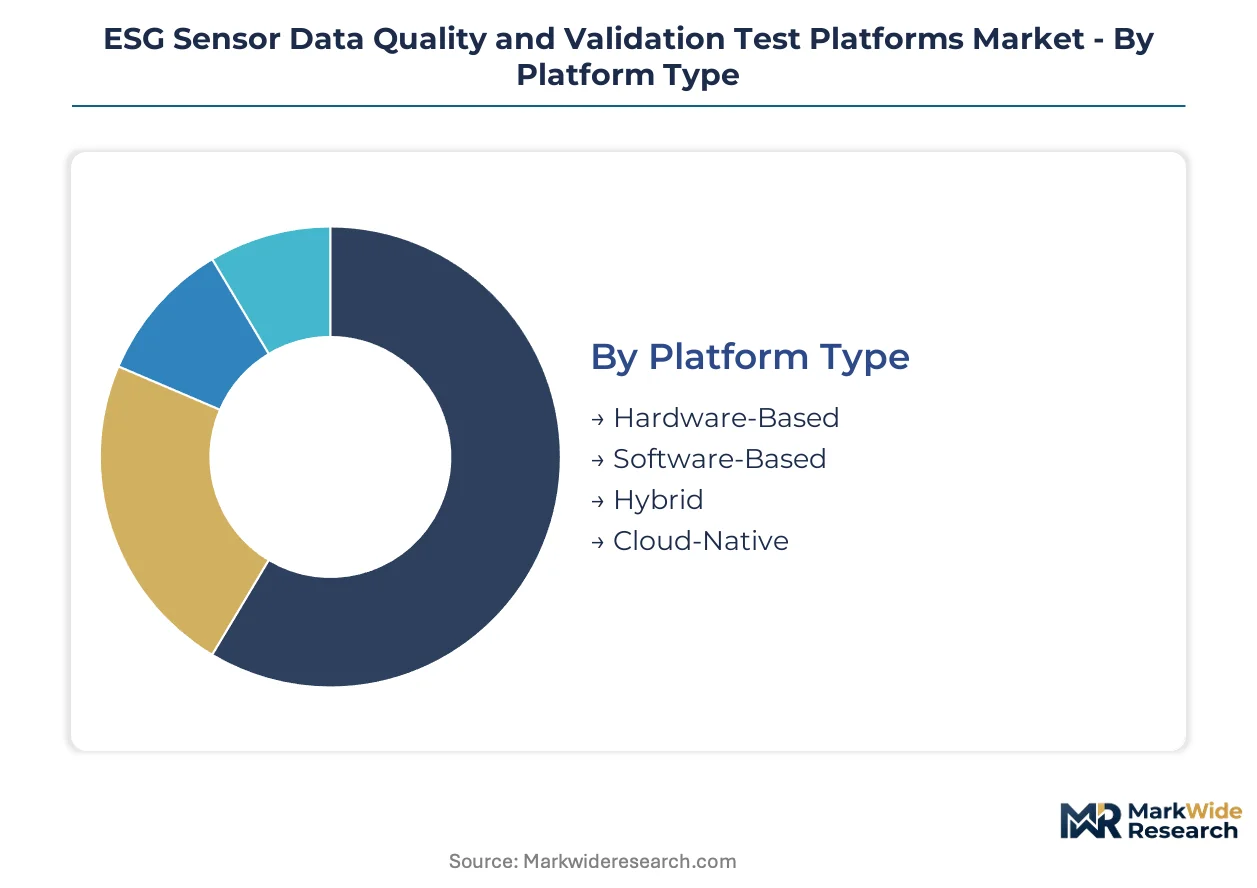
Segmentation in this market reflects divergent capital deployment strategies and compliance urgency across buyer types. Platform architecture choices directly determine audit trail integrity, calibration frequency, and total cost of ownership for CSRD-aligned disclosure programs.
Platform Type:
Volume concentration sits with capital-intensive hardware installations, while premium expansion flows toward elastic cloud architectures.
- Hardware-Based:Capital-intensive calibration infrastructure with reference-grade metrology equipment and climate-controlled laboratory facilities anchors revenue concentration. German industrial conglomerates facing accelerated CSRD deadlines drive procurement of redundant validation chains with sub-1% tolerance thresholds.
- Cloud-Native:Elastic compute architectures process seasonal reporting spikes without fixed infrastructure commitment. Manufacturers with intermittent audit volumes favor subscription models that bypass calibration laboratory capex barriers.
- Software-Based:Middleware layers enabling sensor data normalization across heterogeneous IoT fleets.
- Hybrid:Distributed edge gateways paired with centralized analytics for latency-sensitive continuous emissions monitoring.
Today's leader: Hardware-Based. Tomorrow's challenger: Cloud-Native.
Technology:
Development resource allocation tilts toward inference capabilities, while provenance verification attracts regulatory-driven procurement.
- Machine Learning:Embedded AI processors in validation hardware execute real-time anomaly detection without cloud latency. Tensor-processing units deployed directly on validation gateways absorb pattern-recognition workloads from centralized SaaS architectures.
- IoT Analytics:Stream processing engines handling throughput rates exceeding 10,000 readings per second with protocol normalization for legacy SCADA integration.
- Edge Computing:Compute geography compression serving continuous emissions monitoring obligations in chemical manufacturing.
- Blockchain:Distributed ledger architectures establishing data provenance without centralizing sensitive industrial telemetry.
Machine Learning commands current R&D budgets. Blockchain offers the steepest expansion trajectory as CSRD traceability mandates harden.
Application:
Compliance applications generate consistent procurement volume, while supply chain use cases accelerate with Scope 3 disclosure requirements.
- Regulatory Compliance:ISO-compliant validation systems producing auditable environmental data streams for mandatory sustainability disclosures. Certification agencies facing expanded CSRD audit scopes represent the most reliable demand segment.
- Supply Chain Transparency:Multi-tier sensor validation enabling Scope 3 carbon accounting and supplier attestation workflows.
- Environmental Monitoring:Continuous emissions verification with real-time threshold alerting for industrial site operators.
- Energy Management:Validated consumption data supporting carbon intensity reduction targets and green tariff qualification.
Regulatory Compliance anchors near-term revenue. Supply Chain Transparency is gaining share fastest as downstream disclosure obligations cascade.
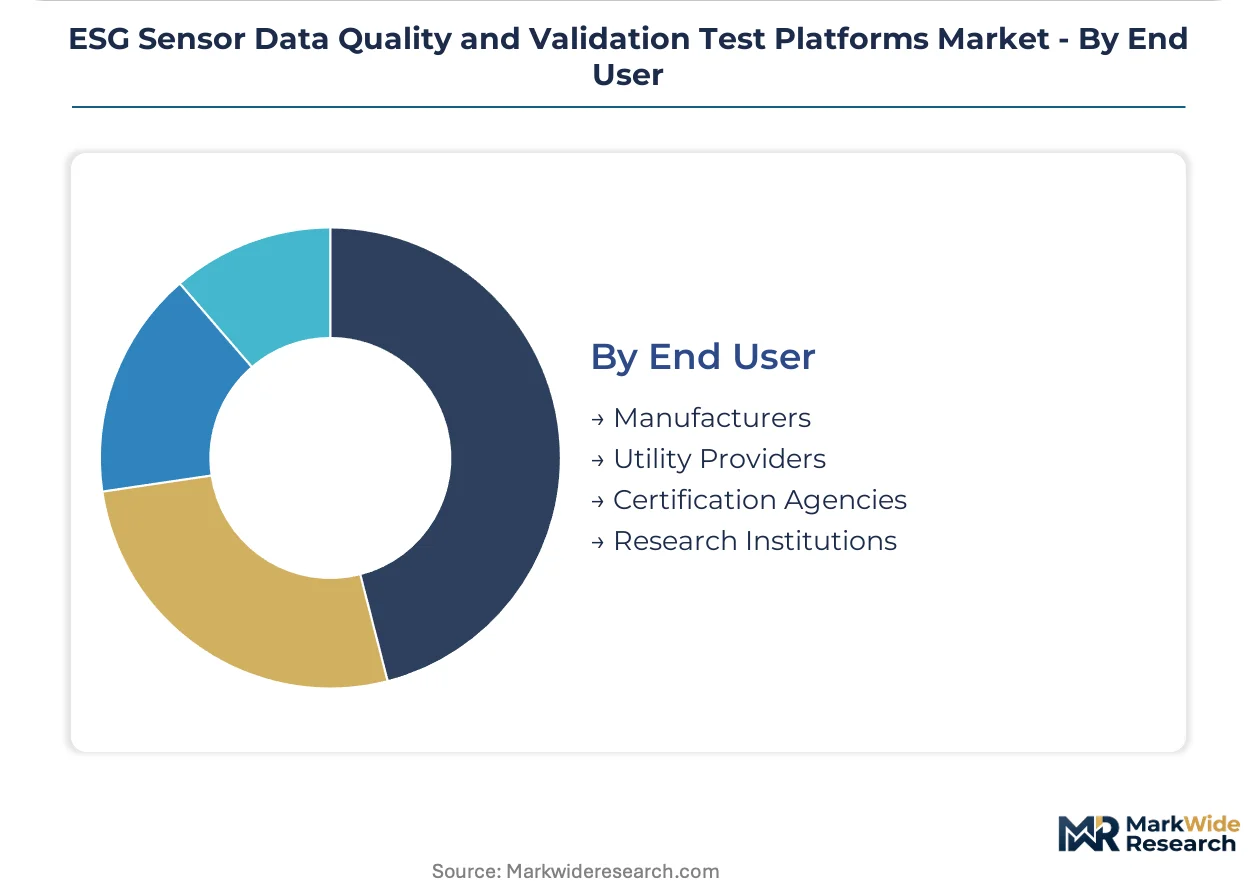
End User:
Procurement authority is concentrating with systems integrators rather than end-use operators across the Rhine-Ruhr manufacturing corridor.
- Certification Agencies:Accredited third-party verification workflows tied to regulatory disclosure cycles generate recurring platform demand. Pre-positioning capacity ahead of national transposition deadlines accelerates procurement cycles.
- Manufacturers:Industrial conglomerates deploying validation infrastructure across entire facility footprints through consolidated automation integrator relationships.
- Utility Providers:Grid operators requiring validated sensor inputs for portfolio-level carbon exposure modeling and regulatory capital allocation.
- Research Institutions:Methodology development and standard-setting participation driving early-stage platform evaluation.
Certification Agencies dominate current procurement volume. Utility Providers represent the emerging growth vector as climate stress-testing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial sensor validation infrastructure first scaled within German manufacturing clusters during the 2010s Industry 4.0 wave. Today procurement concentrates in jurisdictions with binding disclosure mandates and dense automation ecosystems.
Germany
Rhine-Ruhr industrial conglomerates drive hardware-based validation procurement ahead of accelerated CSRD compliance windows. The EU Green Deal's mandatory sustainability disclosure requirements tighten data integrity standards across reporting frameworks. Bavarian chemical manufacturers deploy dual-redundant validation chains for continuous emissions monitoring obligations.
United States
Financial institutions deploying climate risk stress-testing tools represent a rapidly expanding buyer segment for verified sensor inputs. EPA emissions monitoring protocols and SEC climate disclosure rules expand audit-grade data requirements. Houston petrochemical clusters and Silicon Valley cloud providers anchor hybrid validation architectures.
India
Domestic manufacturing scale-up under BIS standards alignment creates demand for import-compatible validation platforms. The central government's industrial decarbonization mandates and PLI scheme incentives accelerate sensor deployment. Gujarat and Maharashtra industrial corridors concentrate procurement of cloud-native solutions for intermittent audit volumes.
United Kingdom
Certification agencies pre-position accredited third-party verification capacity ahead of national transposition deadlines. The British Standards Institution framework and post-Brexit sustainability reporting rules maintain ISO compliance pressure. London financial services clusters drive climate stress-testing tool adoption for portfolio carbon exposure modeling.
China
Dual carbon goals and MIIT smart manufacturing standards expand environmental data verification requirements. GB standards alignment with international sustainability frameworks shapes platform specification. Yangtze River Delta manufacturing hubs deploy edge-native validation for latency-sensitive continuous monitoring.
ESG Sensor Data Quality and Validation Test Platforms Market Competitive Landscape
Premium-margin players sit above commodity-margin players across calibration infrastructure depth and regulatory accreditation breadth. The vendor base stratifies between capital-intensive hardware specialists and elastic cloud-native providers. Three archetypes dominate: diversified automation conglomerates with distributed sensing portfolios, accredited certification bodies with third-party verification workflows, and industrial software vendors with deep SCADA integration capabilities. Competitive moves concentrate on strategic partnerships with systems integrators and portfolio diversification into subscription-based validation services.
Within the diversified automation tier, Honeywell International and Siemens exemplify distinct strategic vectors. Honeywell anchors hybrid validation architectures through distributed sensing hardware portfolios across industrial sites. Siemens occupies a position defined by deep automation integration and edge computing capabilities. Among accredited certification specialists, Bureau Veritas represents the third-party verification archetype with workflows tied to regulatory disclosure cycles. These three companies collectively illustrate how procurement authority concentrates with platform bundlers rather than component manufacturers.
| Leading Market Players |
|---|
| Honeywell International |
| Siemens |
| ABB |
| Emerson Electric |
| British Standards Institution |
| Bureau Veritas |
| DNV |
| SGS |
| Intertek Group |
| Others |
Pricing and Supply Chain Analysis
High-precision electrochemical sensor component indices cascade through validation platform supply chains into three-tier pricing stratification across premium certification-grade, standard industrial, and economy-tier hardware configurations. German and Swiss component concentration amplifies cost pass-through volatility for mid-scale platform providers facing fixed calibration laboratory infrastructure requirements.
Pricing Analysis
Subscription-based validation services with elastic compute provisioning anchor the fastest-expanding pricing architecture, separating premium ISO 17025-accredited certification tiers from standard industrial monitoring packages and economy-tier self-service analytics modules. Price differentiation rests on calibration traceability depth and CSRD audit-grade documentation completeness. Cost compression in hardware-based tiers is intensifying as cloud-native alternatives bypass fixed metrology capex barriers. Certification agencies with recurring disclosure cycle obligations demonstrate the lowest price sensitivity, while intermittent audit-volume manufacturers favor pay-per-use elasticity.
Supply Chain Analysis
Single-source vulnerability sits with German precision sensor manufacturers and Swiss optical component specialists, concentrating reference-grade metrology equipment production in Central European industrial corridors. Raw material dependencies span high-purity silicon substrates, rare-earth-doped optical fibers, and specialized electrochemical membranes. Tariff exposure on precision instrumentation imports into India and China complicates multinational platform deployment strategies. Distribution runs through consolidated automation integrators in the Rhine-Ruhr manufacturing corridor rather than direct sensor manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ESG Sensor Data Quality and Validation Test Platforms Market functions as a stable compounder, with CSRD disclosure mandate expansion providing predictable procurement visibility across European industrial operators.
For Market Incumbents: Extend calibration infrastructure footprints into India and China ahead of BIS and GB standards alignment deadlines, while deepening machine learning R&D allocation to defend against edge-native AI processor commoditization. Backward integration into high-precision sensor component supply reduces exposure to German and Swiss supplier concentration. Certification accreditation breadth across multiple regulatory jurisdictions anchors pricing power. For New Entrants and Emerging Players: Embedded AI inference at the validation gateway offers a technology-first wedge into continuous emissions monitoring applications where latency-sensitive anomaly detection commands premium positioning. Cloud-native subscription models targeting mid-tier certification agencies with intermittent CSRD audit volumes represent the most penetrable white-space segment. Partnership with systems integrators in the Rhine-Ruhr corridor accelerates specification-setting access. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid platform specialists combining distributed edge hardware with centralized SaaS analytics, positioned for digital twin convergence and predictive calibration scheduling workflows. Long-term viability over the coming decade hinges on regulatory accreditation moats and SCADA integration depth. Watch for national transposition deadlines of EU-level CSRD mandates as inflection indicators for accelerated procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Digital Twin Architectures | Enables predictive calibration scheduling for chemical manufacturers under EMA continuous monitoring obligations. |
| Accreditation Expansion into BIS-Aligned Jurisdictions | Positions validation platforms for India's industrial decarbonization procurement under PLI scheme incentives. |
| Subscription-Based Validation Service Launch | Lowers entry barriers for certification agencies facing expanded CSRD audit scopes with intermittent volumes. |
| Edge-Native Machine Learning Hardware Development | Absorbs latency-sensitive pattern-recognition workloads from centralized SaaS architectures in emissions monitoring. |
| Strategic Partnership with Systems Integrators | Captures specification-setting power across entire facility footprints in German industrial conglomerates. |
Research Methodology
Coverage spans Germany, the United States, India, the United Kingdom, and China, with primary inputs from each market cluster combining interviews with certification agency technical directors, industrial automation integrators, platform engineering leads, and regulatory compliance officers with secondary validation from SEC filings, EU regulatory transposition documents, BIS standards publications, and customs trade data. Bottom-up sensor deployment estimates triangulate against top-down disclosure mandate expansion projections.
Granularity-level modeling addresses platform type, technology stack, application use case, and end-user procurement authority across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with aggregate market expansion constraints. Forecast inputs incorporate CSRD implementation timeline phasing, machine learning inference cost curves, and cloud-native adoption elasticity patterns.
The model holds under steady regulatory enforcement intensity and stable electrochemical component supply; deviation in trade policy restrictions or accelerated national transposition deadlines would shift volume timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Europe Nondestructive Testing Equipment Market
Test and Measurement
Psophometer Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
Test Benches Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Sound Meter Market
Test and Measurement
Global Platform Electronic Laboratory Balance Market
Test and Measurement
Vibration Analyzer Market
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
Electromagnetic NDT Market
Test and Measurement
Modular Test Equipment Market
Test and Measurement
LAN Tester Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market