
 Short-Wave Infrared (SWIR) Camera Market | 2026-2036
Short-Wave Infrared (SWIR) Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Short-Wave Infrared (SWIR) Camera Market Analytics
The EU Green Deal's industrial emissions monitoring mandates is pivoting process industries toward non-contact thermal measurement tools. Teledyne FLIR leverages its captive InGaAs foundry capacity to anchor supply security for European automation buyers. Xenics competes through compact sensor modules purpose-built for drone-mounted agricultural inspection. Hamamatsu Photonics sustains dominance in scientific-grade cooled detectors for semiconductor failure analysis.
Short-Wave Infrared (SWIR) cameras capture electromagnetic radiation in the 0.9–1.7 micrometer wavelength band using indium gallium arsenide (InGaAs) focal plane arrays, enabling imaging through fog, silicon substrates, and certain plastic films that block visible light. InGaAs Detectors occupy the core technology tier where wafer-scale manufacturing maturity supports cost reduction for volume applications. SWIR Sensors represent the fastest-growing product type as module suppliers disintegrate camera functions for embedded machine vision. Optical Inspection within the application dimension concentrates margin pools, since semiconductor fabs pay premiums for sub-micron defect detection at production-line speeds.
FDA device classification rules for diagnostic imaging systems shape product validation pathways for Medical Imaging deployments, while REACH chemical restrictions on mercury-containing compounds constrain HgCdTe detector supply chains serving European defense contractors. ISO 9001 quality management and IEC 60825 laser safety standards further gate market access for industrial OEM integrations. Stakeholders must monitor how export control expansions on focal plane array technology reshape supplier geography and captive production investments.
Market Dynamics
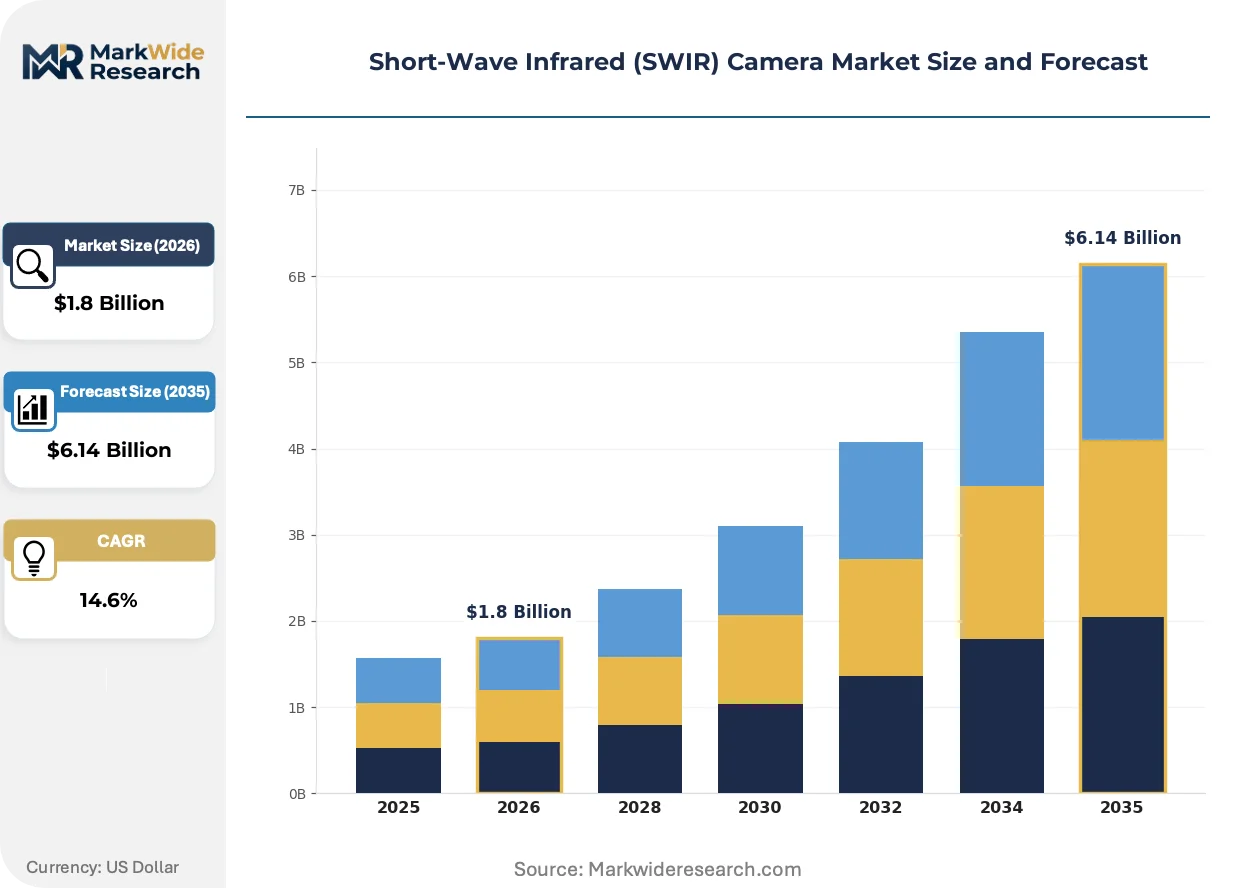
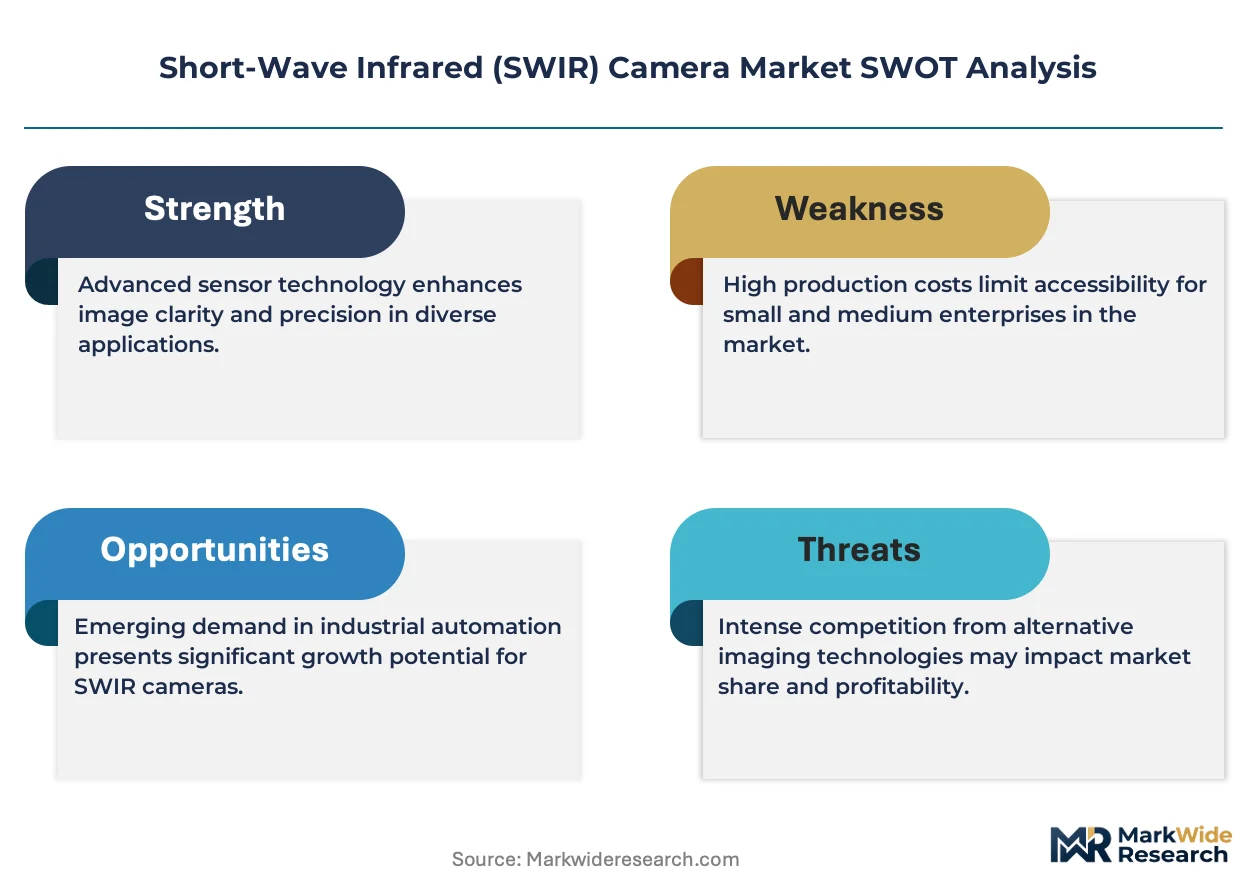
The SWIR camera market is being restructured by the divergence between defense-grade cooled detectors and cost-optimized uncooled modules for industrial automation, forcing suppliers to choose between margin-rich niche volumes and scale-driven commoditization paths.
Growth Catalysts
- EU AI Act compliance requirements:Automated visual inspection systems in European automotive plants now require auditable sensor performance documentation, accelerating replacement of legacy visible-light cameras with SWIR-equipped machine vision stations.
- Silicon wafer thickness reduction:Semiconductor manufacturers below 3nm nodes deploy SWIR transmission imaging for backside defect detection through increasingly opaque substrates, embedding cameras directly into lithography-adjacent metrology loops.
- German precision manufacturing clusters:Stuttgart and Munich industrial corridors sustain concentrated demand for sub-micron inspection systems, with local automation integrators specifying InGaAs sensors as standard for food-sorting and pharmaceutical packaging lines.
Market Restraints
- InGaAs wafer supply concentration:Epitaxial foundry capacity for sensor-grade indium gallium arsenide concentrates among three Asian suppliers, exposing European and North American camera OEMs to allocation risk during semiconductor cycle upturns.
- Mercury-cadmium-telluride substitution ceiling:Extended-wavelength applications beyond 1.7μm remain locked to HgCdTe detectors restricted by REACH mercury compound limitations, fragmenting R&D investment across incompatible material platforms.
- High-resolution sensor yield economics:Defect-free 1280×1024 InGaAs arrays require military-grade epitaxial growth controls, keeping unit costs at 8-12× premium over silicon CMOS imagers and gating mass-market consumer applications.
Strategic Opportunities
- India pharmaceutical packaging inspection:CDSCO serialization mandates for export-oriented drug manufacturers create first-mover advantage for SWIR camera suppliers offering through-container seal verification without line-speed reduction.
- Hyperspectral-SWIR fusion systems:Agricultural drone operators in Japan's Hokkaido prefecture are testing combined short-wave infrared and spectral imaging payloads for early-stage crop stress detection, opening service-contract revenue models beyond hardware sales.
- US Inflation Reduction Act clean energy provisions:Domestic content bonuses for solar panel manufacturing equipment are pulling SWIR camera procurement toward US-based module assemblers qualifying for federal tax credits.
Industry Challenges
- InGaAs epitaxial engineering talent scarcity:Compound semiconductor fabrication expertise concentrates among aging workforces at legacy defense contractors, constraining foundry expansion plans and elongating new supplier qualification timelines.
- FDA 510(k) pathway complexity for diagnostic imaging:SWIR-based tissue perfusion monitors face extended validation cycles when predicate device comparisons require novel clinical evidence generation, compressing effective patent life for first entrants.
- Multi-sensor calibration integration:Machine vision integrators report 40% of deployment delays stem from SWIR-visible-thermal fusion alignment, as wavelength-dependent optical path variations demand custom mechanical design for each installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short-Wave Infrared (SWIR) Camera Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SWIR Cameras, SWIR Sensors, SWIR Modules, SWIR Imaging Systems Technology: InGaAs Detectors, HgCdTe Detectors, Quantum Dot Sensors, Indium Antimonide End User: Aerospace, Surveillance, Industrial Inspection, Medical Imaging Application: Thermal Imaging, Night Vision, Optical Inspection, Remote Sensing |
| Companies Covered | Teledyne FLIR, Allied Vision Technologies, Xenics, Sensors Unlimited, Lynred, New Imaging Technologies, Princeton Infrared Technologies, Raptor Photonics, Hamamatsu Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short-Wave Infrared (SWIR) Camera Market Evolving Landscape
Sensor miniaturization and computational imaging are collapsing the traditional distinction between standalone cameras and embedded vision modules, redrawing competitive boundaries around software-defined image processing rather than hardware specifications alone.
Wafer-scale InGaAs-on-silicon integration is unifying photodetection and readout circuitry onto monolithic substrates, eliminating hybrid bonding steps that previously constrained yield. Automotive LiDAR suppliers in Germany and Japan are sampling these devices for 1550nm wavelength operation, where eye-safety regulations favor SWIR over 905nm alternatives. The structural consequence is compressing price differentials between SWIR and near-infrared sensors, enabling volume economics previously reserved for silicon imagers.
REACH chemical restrictions on mercury compounds are forcing European defense contractors to accelerate indium gallium arsenide extended-wavelength development programs, redirecting procurement away from legacy HgCdTe suppliers. The industrial consequence is diverting R&D budgets toward strained-layer superlattice alternatives and type-II superlattice architectures. Night-vision system integrators in France and Germany report qualification timelines extending 18-24 months as they validate replacement detector platforms.
Japanese semiconductor equipment buyers are consolidating machine vision procurement under fab-level framework agreements, displacing historically decentralized tool-by-tool purchasing. Equipment OEMs in Yokohama and Kyoto are responding by bundling SWIR inspection modules into process tool sales rather than selling cameras as separate line items. This concentration is most visible in 300mm wafer fabs, where single-source supplier relationships now govern metrology subsystem selection across multiple lithography and etch platforms.
Short-Wave Infrared (SWIR) Camera Market Segmentation
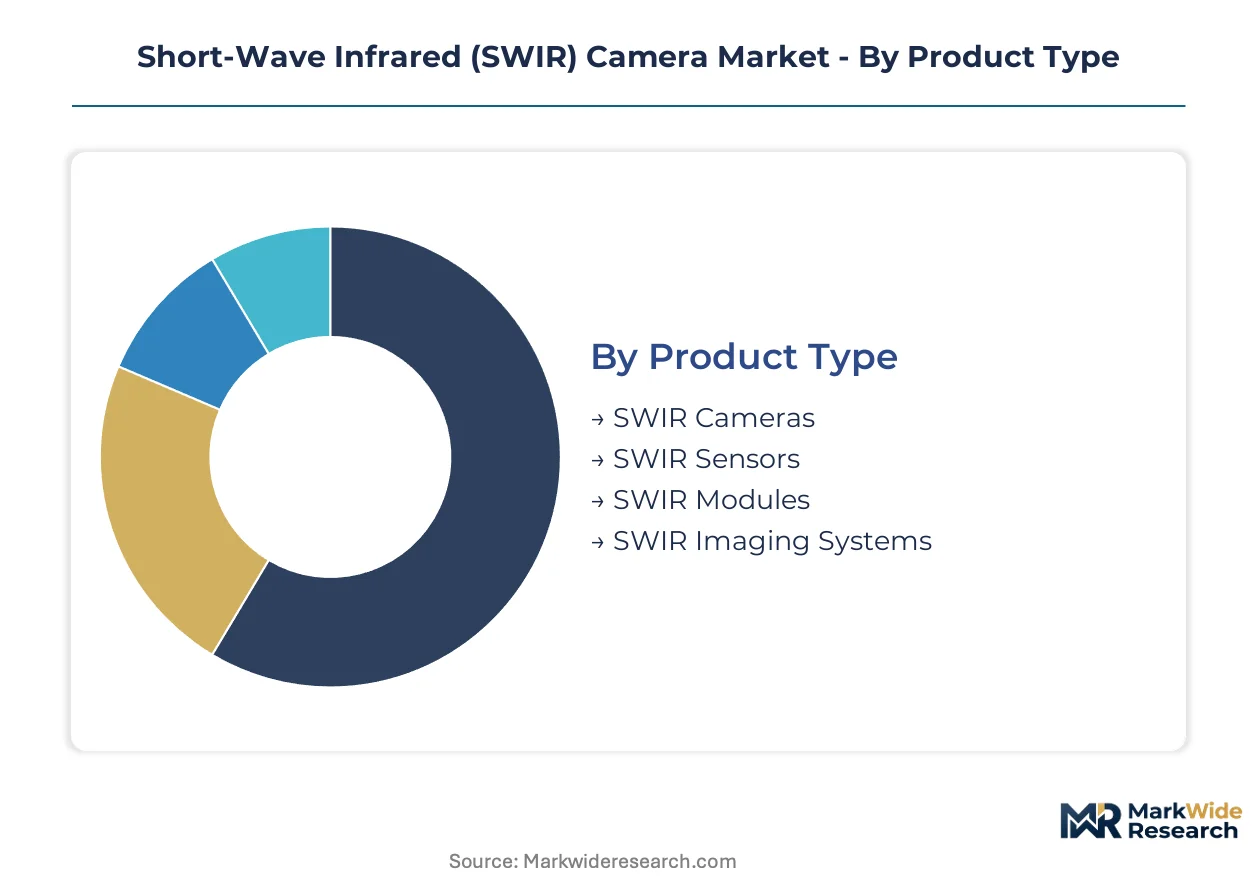
SWIR camera procurement splits sharply between standalone vision systems and embedded sensor modules, with integration depth determining margin structures and supplier relationships across defense, industrial, and medical verticals.
Product Type:
Standalone cameras dominate high-value defense and scientific deployments, while embedded sensors and modules capture volume growth in automated manufacturing lines.
- SWIR Cameras:Self-contained imaging systems with integrated optics, cooling, and data interfaces. German automotive fabs and US defense contractors specify these for lithography metrology and night-vision platforms where performance trumps unit cost.
- SWIR Sensors:Bare focal plane arrays and readout circuits for OEM integration. Japanese semiconductor equipment makers in Yokohama and Kyoto are consolidating procurement under fab-level framework agreements, embedding these directly into process tools.
- SWIR Modules:Compact sub-assemblies combining detector, lens mount, and interface electronics. Drone operators in Japan's Hokkaido prefecture deploy these for agricultural crop stress monitoring where payload weight constraints dominate.
- SWIR Imaging Systems:Turnkey solutions with software, calibration, and service contracts. European process industries under EU Green Deal emissions mandates specify these for non-contact thermal measurement in steel and chemical plants.
SWIR Cameras lead volumes today; SWIR Sensors are gaining share fastest.
Technology:
Material platforms diverge between mature InGaAs volume production and restricted HgCdTe alternatives, with emerging quantum architectures targeting cost-sensitive industrial applications.
- InGaAs Detectors:Indium gallium arsenide focal plane arrays manufactured on 3-inch and 6-inch InP substrates. Wafer-scale integration with silicon readout circuits is collapsing cost differentials against near-infrared sensors, enabling automotive LiDAR sampling at 1550nm.
- HgCdTe Detectors:Mercury-cadmium-telluride devices extending sensitivity beyond 1.7μm for long-range surveillance. REACH chemical restrictions on mercury compounds are forcing French and German defense contractors into 18-24 month qualification cycles for replacement platforms.
- Quantum Dot Sensors:Colloidal nanocrystal films tunable across SWIR wavelengths through size control. These promise roll-to-roll manufacturing compatibility absent in epitaxial InGaAs growth.
- Indium Antimonide:III-V compound detectors offering extended wavelength response to 5.5μm for missile warning systems. Production concentrates at legacy defense contractors with aging compound semiconductor workforces.
InGaAs Detectors anchor current revenue; Quantum Dot Sensors show steepest expansion trajectory.
End User:
Defense procurement sustains premium pricing for cooled detectors, while industrial automation and medical imaging drive uncooled module volumes through regulatory compliance mandates.
- Aerospace:Satellite earth observation and space situational awareness programs. German and Japanese procurement offices specify radiation-hardened InGaAs arrays for orbital platforms.
- Surveillance:Border monitoring and critical infrastructure protection. US Inflation Reduction Act domestic content bonuses are pulling SWIR camera procurement toward US-based module assemblers.
- Industrial Inspection:Semiconductor defect detection, food sorting, and pharmaceutical packaging verification. Stuttgart and Munich automation corridors specify InGaAs sensors as standard for sub-micron inspection systems.
- Medical Imaging:Tissue perfusion monitoring and surgical navigation. FDA 510(k) pathway complexity extends validation cycles when predicate comparisons require novel clinical evidence.
Industrial Inspection generates the largest unit volumes; Medical Imaging climbs fastest on diagnostic AI integration.
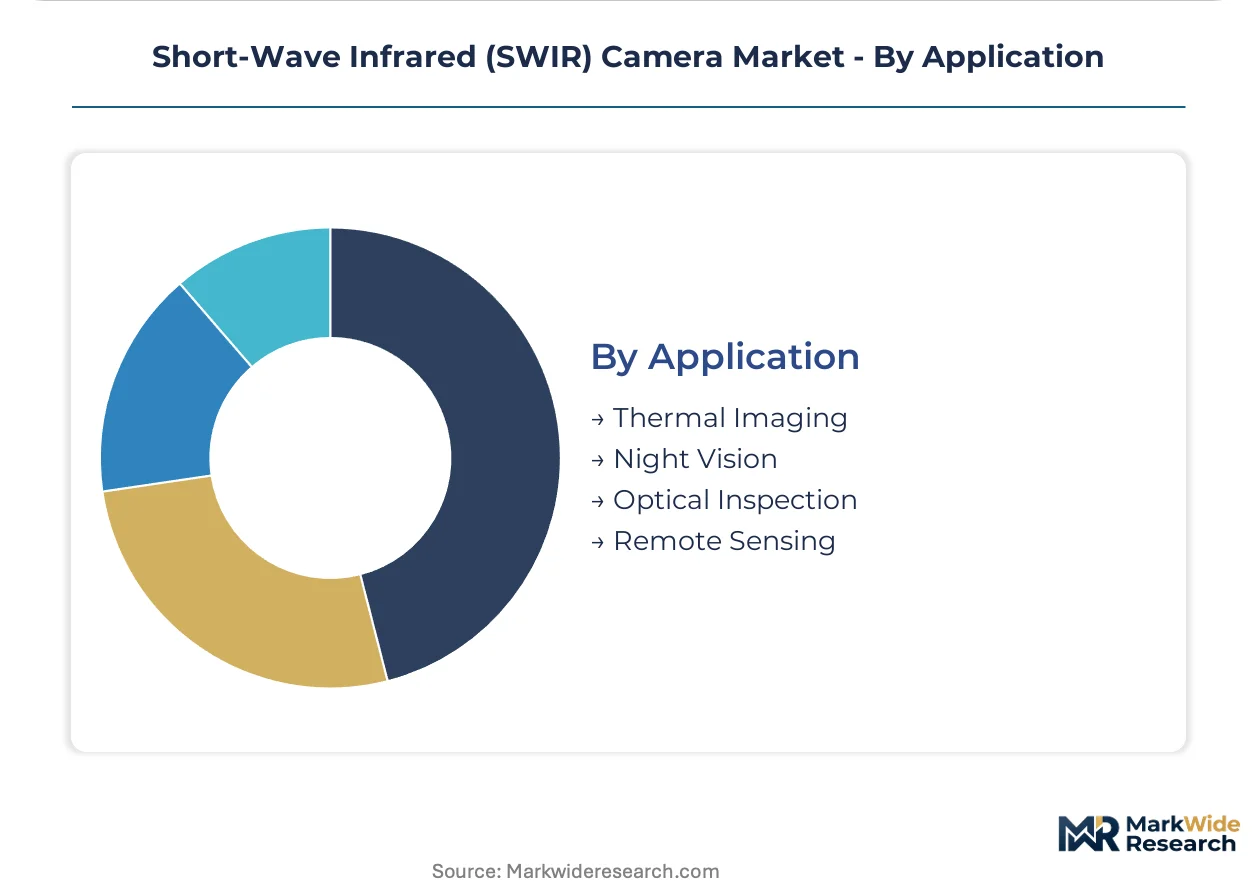
Application:
Use cases span passive imaging through active illumination systems, with optical inspection commanding margin premiums for production-line speed requirements.
- Thermal Imaging:Non-contact temperature measurement for process control. EU Green Deal industrial emissions monitoring mandates are pivoting steel and chemical producers toward SWIR-based thermal tools.
- Night Vision:Low-light and no-light imaging for defense and security. French and German integrators face extended timelines validating HgCdTe replacements under REACH constraints.
- Optical Inspection:Sub-micron defect detection in semiconductor manufacturing. Below-3nm node fabs deploy SWIR transmission imaging for backside defect detection through silicon substrates.
- Remote Sensing:Agricultural, environmental, and geological survey from airborne and satellite platforms. Hyperspectral-SWIR fusion payloads in Japan are opening service-contract revenue models beyond hardware sales.
Optical Inspection captures the highest margins; Remote Sensing expands most quickly on drone payload miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Short-wave infrared imaging originated in defense and scientific laboratories of the United States and Japan during the 1980s, with compound semiconductor expertise later concentrating in German precision manufacturing clusters. Production capabilities now span three continents, though sensor-grade epitaxial foundry capacity remains geographically concentrated.
United States
Defense procurement programs and FDA-regulated medical imaging validation sustain demand for high-performance cooled detectors. The Inflation Reduction Act's domestic content bonuses for clean energy manufacturing equipment are redirecting SWIR camera procurement toward US-based module assemblers. Automation integrators in Michigan and Texas specify InGaAs sensors for automotive quality-control lines.
Germany
Stuttgart and Munich industrial corridors anchor European demand for sub-micron inspection systems, with EU AI Act compliance requirements accelerating machine vision upgrades. REACH chemical restrictions on mercury compounds are forcing defense contractors into extended qualification cycles for HgCdTe replacements. Fraunhofer Institute research partnerships support local foundry development.
Japan
Semiconductor equipment makers in Yokohama and Kyoto are consolidating procurement under fab-level framework agreements, embedding SWIR modules directly into process tools. METI-supported agricultural technology programs in Hokkaido are testing hyperspectral-SWIR fusion payloads for crop stress detection. Domestic InGaAs epitaxial capacity serves both scientific and industrial automation verticals.
China
Domestic solar panel manufacturing scale and NMPA-regulated medical device development are driving uncooled module demand. Local compound semiconductor foundries are expanding 6-inch InP substrate capacity to reduce import dependence. MIIT industrial automation initiatives in the Yangtze River Delta specify SWIR-equipped vision systems for electronics assembly lines.
India
CDSCO serialization mandates for pharmaceutical export packaging are creating first-mover opportunities for through-container seal verification systems. PLI scheme incentives for electronics manufacturing are attracting SWIR module assembly investments. Automation integrators in Maharashtra and Gujarat are specifying InGaAs sensors for food-sorting and quality-control applications.
Short-Wave Infrared (SWIR) Camera Market Competitive Landscape
Capital-heavy producers with captive epitaxial foundry capacity compete with asset-light designers outsourcing sensor fabrication to merchant foundries. The market structure bifurcates between defense-grade cooled detector specialists and industrial automation module suppliers pursuing cost-optimized scale. Three archetypes dominate: vertically integrated compound semiconductor manufacturers, vision system integrators with software-defined imaging platforms, and merchant focal plane array suppliers. Competitive moves center on wafer-scale integration investments and strategic partnerships with machine vision OEMs.
Among US-based defense and industrial imaging specialists, Teledyne FLIR and Sensors Unlimited exemplify the vertically integrated archetype with captive InGaAs production capabilities. Xenics occupies a position within the European compact module tier, while Hamamatsu Photonics anchors the scientific-grade cooled detector segment. These three represent divergent strategic postures: foundry-backed supply security, miniaturization for embedded applications, and precision instrumentation for semiconductor failure analysis.
| Leading Market Players |
|---|
| Teledyne FLIR |
| Allied Vision Technologies |
| Xenics |
| Sensors Unlimited |
| Lynred |
| New Imaging Technologies |
| Princeton Infrared Technologies |
| Raptor Photonics |
| Hamamatsu Photonics |
| Others |
Value Network & Pricing Analysis
Performance-grade bifurcation between cooled defense detectors and uncooled industrial modules manifests in divergent pricing architectures and supply chain configurations. Cooled InGaAs arrays for semiconductor failure analysis command 8-12× premiums over silicon CMOS alternatives, while wafer-scale integration is collapsing cost differentials in automotive LiDAR sampling at 1550nm. German automation buyers under EU AI Act mandates absorb higher unit costs for auditable sensor documentation, whereas Indian pharmaceutical packagers prioritize throughput-per-dollar in through-container seal verification systems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes the SWIR camera market. Premium tiers attach to FDA-validated medical imaging systems and radiation-hardened satellite payloads, while standard tiers serve German automotive metrology and Japanese semiconductor equipment bundling. Price differentiation centers on epitaxial grade and cooling architecture, with military-spec InGaAs growth controls sustaining premiums. Cost compression in uncooled modules intensifies as wafer-scale InGaAs-on-silicon integration eliminates hybrid bonding steps. Indian pharmaceutical packaging integrators exhibit highest price sensitivity, whereas US defense contractors prioritize performance guarantees over unit economics.
Supply Chain Analysis
ISO 9001 and IEC 60825 certification gating restricts supplier qualification timelines to 18-24 months for European defense contractors replacing REACH-constrained HgCdTe platforms. InGaAs epitaxial foundry capacity concentrates in Japan, the United States, and select German research partnerships, with sensor-grade indium gallium arsenide drawing from three Asian substrate suppliers. Raw material dependencies center on 3-inch and 6-inch InP wafers, indium metal feedstock, and mercury-cadmium-telluride for extended-wavelength alternatives. Single-source vulnerability in epitaxial growth equipment exposes OEMs to allocation risk during semiconductor cycle upturns. Distribution runs through fab-level framework agreements in Japanese semiconductor equipment and direct OEM integration in European process industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SWIR camera market functions as a stable compounder anchored by irreversible regulatory mandates for automated inspection and emissions monitoring. Industrial automation procurement under EU AI Act and FDA diagnostic imaging rules sustains replacement cycles independent of discretionary capital expenditure cycles.
For Market Incumbents: Acquire compound semiconductor epitaxial engineering talent pools before demographic retirement accelerates. Foundry-backed suppliers like Teledyne FLIR should expand captive InGaAs capacity in Germany through Fraunhofer partnerships, insulating European automation buyers from Asian allocation risk. Defense-grade specialists must accelerate strained-layer superlattice R&D to capture HgCdTe substitution demand under REACH mercury compound restrictions. For New Entrants and Emerging Players: Capture Indian pharmaceutical packaging inspection white space created by CDSCO serialization mandates for export-oriented drug manufacturers. Agricultural drone service contracts in Japan's Hokkaido prefecture offer recurring revenue models beyond hardware sales, with hyperspectral-SWIR fusion payloads penetrating faster than standalone camera sales. Partner with Yokohama-based semiconductor equipment OEMs to embed modules into lithography-adjacent metrology tools. For Investors and Strategic Acquirers: Asymmetric upside sits with merchant focal plane array suppliers possessing qualified foundry relationships but lacking downstream integration. Five-to-ten-year viability hinges on wafer-scale integration economics converging with silicon CMOS cost structures. Watch for US Inflation Reduction Act domestic content bonus qualification thresholds as inflection indicators pulling procurement toward US-based module assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Scale Integration Investment | Monolithic InGaAs-on-silicon substrates eliminate hybrid bonding yield losses for automotive LiDAR sampling. |
| REACH-Compliant Detector Qualification | French and German defense contractors require 18-24 month validation cycles for HgCdTe replacement platforms. |
| Fab-Level Framework Agreement | Yokohama and Kyoto equipment OEMs consolidate SWIR procurement under single-source metrology subsystem relationships. |
| Agricultural Service Contract Model | Hokkaido drone operators shift from hardware sales to recurring crop stress monitoring subscriptions. |
| Domestic Content Bonus Capture | US module assemblers qualify for Inflation Reduction Act tax credits in solar panel manufacturing equipment. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's precision manufacturing clusters and defense procurement offices. The research combines structured interviews with semiconductor equipment procurement directors, machine vision integration engineers, compound semiconductor foundry managers, and biomedical imaging regulatory affairs specialists. Secondary validation draws from FDA 510(k) device classifications, ECHA REACH restriction updates, SEC filings of listed sensor manufacturers, and customs trade data for InP substrate movements. Bottom-up unit economics triangulate against top-down market sizing across defense, industrial, and medical verticals.
Granularity-level modeling disaggregates volume and value across product type, technology platform, end-use vertical, and application use case, with additional segmentation by cooling architecture and wavelength sensitivity band. CAGRs derive from regression analysis of historical procurement patterns overlaid with regulatory mandate implementation timelines. Forecast inputs incorporate EU AI Act compliance deadlines, FDA diagnostic imaging guidance evolution, and semiconductor node transition schedules for backside defect detection requirements.
Export control expansions on focal plane array technology, InGaAs wafer supply allocation shocks, and HgCdTe substitution program delays are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about regulatory implementation pacing and foundry capacity expansion timelines. A model refresh is warranted upon material change in US Bureau of Industry and Security focal plane array licensing thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Specific Imaging Solution Market
Imaging
Digital Image Processing Market
Imaging
Cinematographic Camera Market
Imaging
Camera Accessories Market
Imaging
Hybrid Imaging Systems Market
Imaging
Global Trail Camera Market
Imaging
Global Image Signal Processor Market
Imaging
Global Thermal Imager Market
Imaging
Light Field Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Multi Camera System Market
Imaging
Global High-Speed Digital Camera Market
Imaging
Video Capture Card Market
Imaging
Compact Camera Module Market
Imaging
AI Camera Market
Imaging
Global Optical Preclinical Imaging Market