
 Image Based Barcode Reader Market | 2026-2036
Image Based Barcode Reader Market Size, Share, and Industry Trends Forecast 2026-2036
Image Based Barcode Reader Market Foresight
Embedded machine vision architectures with deep-learning decode algorithms is reshaping how image based barcode readers process damaged, low-contrast, and high-density symbologies in real time. Zebra Technologies leverages its vertically integrated camera module production to control cost curves across handheld and fixed-mount portfolios. Honeywell International anchors North American channel density through distribution partnerships with industrial automation integrators. Cognex Corporation specializes in high-speed 2D image recognition systems for semiconductor and pharmaceutical packaging lines.
An image based barcode reader captures two-dimensional optical data through CMOS or CCD sensors, then applies digital image processing algorithms to decode linear, stacked, and matrix symbologies at speeds exceeding sixty frames per second. Its primary commercial purpose is to eliminate manual data entry, reduce line stoppages, and enable item-level traceability across serialized supply chains. Fixed-mount scanners dominate manufacturing conveyor applications where continuous hands-free operation drives volume, while mobile computers represent the fastest-expanding segment as warehouse operators replace single-function devices with Android-based multifunction terminals. Healthcare end users concentrate procurement in 2D image recognition configurations to meet FDA Unique Device Identification compliance for implantable devices.
FDA Unique Device Identification rules and EPA electronics disposal directives shape product design cycles, forcing manufacturers to prioritize firmware upgradeability and mercury-free illumination sources. The FCC Part 15 emissions framework governs wireless-enabled reader deployments in retail and logistics environments, creating pre-certification cost barriers for new entrants. Buyers should monitor how ISO 15415 and ISO 15416 print quality standards evolve to support emerging GS1 Digital Link URI encoding, as this will determine next-generation reader resolution and optics requirements.
Market Dynamics
Deep-learning decode algorithms are compressing error rates in high-velocity sortation environments, forcing hardware manufacturers to redesign optical architectures around neural inference engines rather than traditional template-matching pipelines.
Growth Catalysts
- FDA Unique Device Identification mandate:Pharmaceutical and medical device manufacturers must deploy 2D image readers to serialize implantable products, creating sustained procurement volume in healthcare supply chains.
- E-commerce fulfillment center automation:Parcel sortation hubs in the United States and Germany are retrofitting conveyor lines with fixed-mount image readers to handle polybag and damaged-label exceptions without manual intervention.
- CMOS sensor cost curves:Semiconductor foundries in Taiwan and South Korea have driven high-resolution imager prices downward, enabling mid-tier reader vendors to offer decode performance previously reserved for premium tiers.
Market Restraints
- Specialized optics supply concentration:Precision lens assemblies for industrial-grade readers rely heavily on Japanese and German optical component suppliers, exposing assemblers to extended lead times during demand surges.
- FCC Part 15 pre-certification costs:Wireless-enabled mobile terminals require extensive electromagnetic compliance testing before retail and logistics deployment, elevating barriers for new hardware entrants.
- Smartphone camera substitution:Last-mile delivery operators increasingly equip drivers with consumer-grade devices for proof-of-delivery scanning, eroding addressable volume for dedicated single-function readers in certain logistics segments.
Strategic Opportunities
- Indian pharmaceutical export compliance:CDSCO serialization requirements for active pharmaceutical ingredients destined for regulated markets will drive image reader deployment across packaging lines in Gujarat and Hyderabad clusters.
- GS1 Digital Link URI encoding:The transition from traditional barcodes to web-resolvable identifiers demands higher-resolution optics and upgraded firmware, creating refresh cycles among installed base users.
- Edge-AI convergence with 5G private networks:Manufacturing facilities are piloting distributed decode architectures where image readers stream pre-processed data to local inference nodes, reducing central server load.
Industry Challenges
- Machine vision engineer scarcity:Deployment of deep-learning-enabled readers requires specialists capable of training custom decode models for damaged or low-contrast symbologies, a skill set concentrated among integrators in Germany and Japan.
- Legacy WMS integration friction:Warehouse operators running decade-old management software face middleware complexity when connecting modern Android-based mobile terminals to existing inventory databases.
- ISO 15415 print quality variance:Inconsistent substrate and inkjet coding quality across supplier tiers forces reader vendors to over-engineer optical tolerance, compressing margin on standard-configuration units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Image Based Barcode Reader Market |
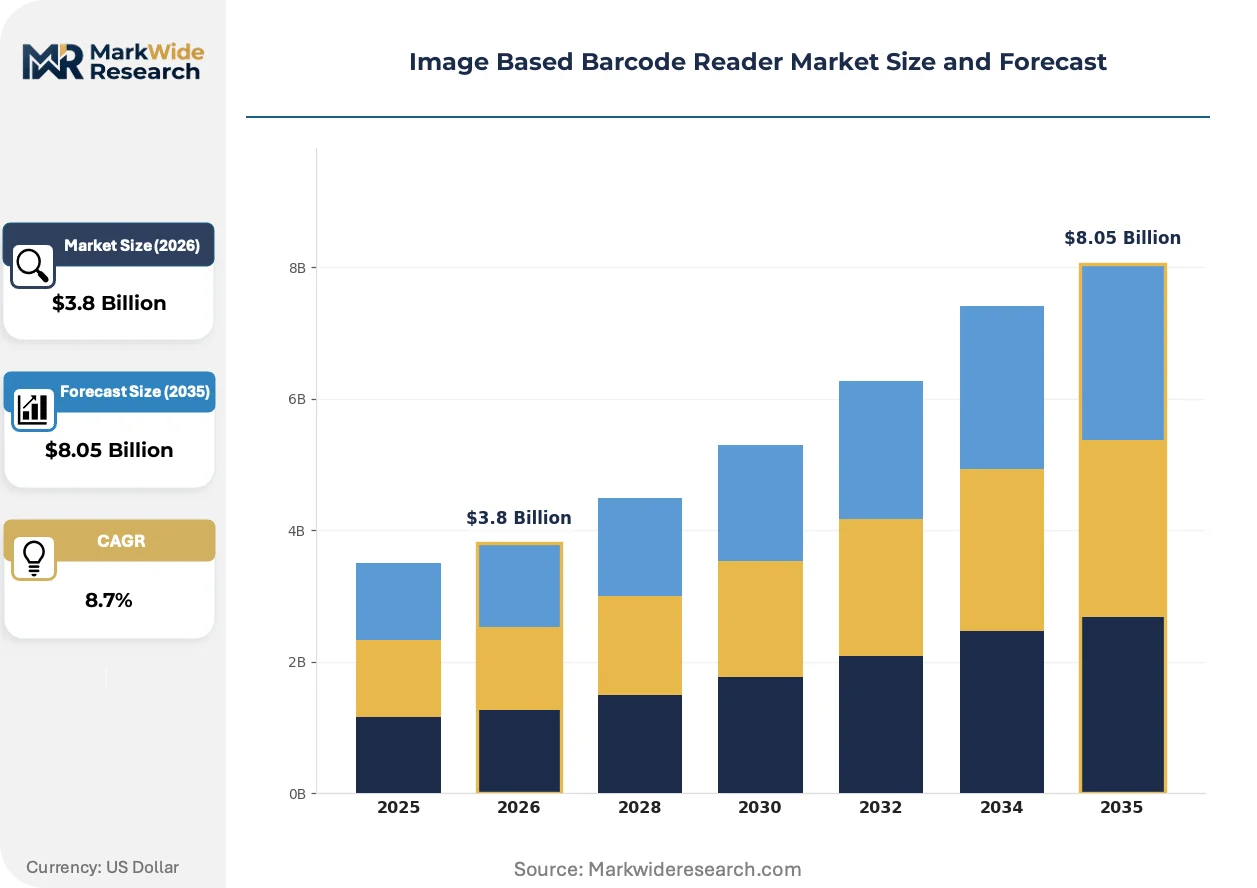
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Scanners, Fixed-Mount Scanners, Mobile Computers, Desktop Scanners Technology: 2D Image Recognition, Laser Scanning, Optical Character Recognition, RFID End User: Retail, Logistics, Manufacturing, Healthcare Installation: Integrated, Portable, Standalone, Cloud-Based |
| Companies Covered | Zebra Technologies, Honeywell International, Cognex Corporation, Datalogic, Keyence Corporation, SICK AG, Omron Corporation, Microscan, Newland AIDC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Image Based Barcode Reader Market Shifts & Advancements
Decode intelligence is migrating from centralized servers to embedded inference engines, compressing latency in time-critical sortation while reducing bandwidth dependencies in distributed warehouse architectures.
Neural network-based symbology recognition is migrating from cloud-based processing to on-device inference. E-commerce fulfillment operators in the United States and Germany are deploying fixed-mount readers with dedicated AI accelerators to handle damaged-label exceptions locally. This architecture eliminates round-trip latency to central servers, enabling sub-50-millisecond decode cycles on high-speed conveyor lines.
REACH substance restrictions and RoHS amendments are phasing mercury-containing illumination from industrial scanner designs. European packaging equipment OEMs now specify LED-only light sources in procurement tenders, compelling Asian component suppliers to retool production lines. The transition accelerates firmware-upgradeable reader platforms that allow field replacement of light engines without hardware obsolescence.
Buying patterns among third-party logistics providers are consolidating around multifunction Android terminals that combine scanning, voice communication, and workflow management. Single-purpose laser scanners are losing shelf space in North American distribution channels as warehouse operators standardize on ruggedized mobile computers. This preference shift favors vendors with vertically integrated mobile computer portfolios over pure-play scanner specialists.
Image Based Barcode Reader Market Segmentation
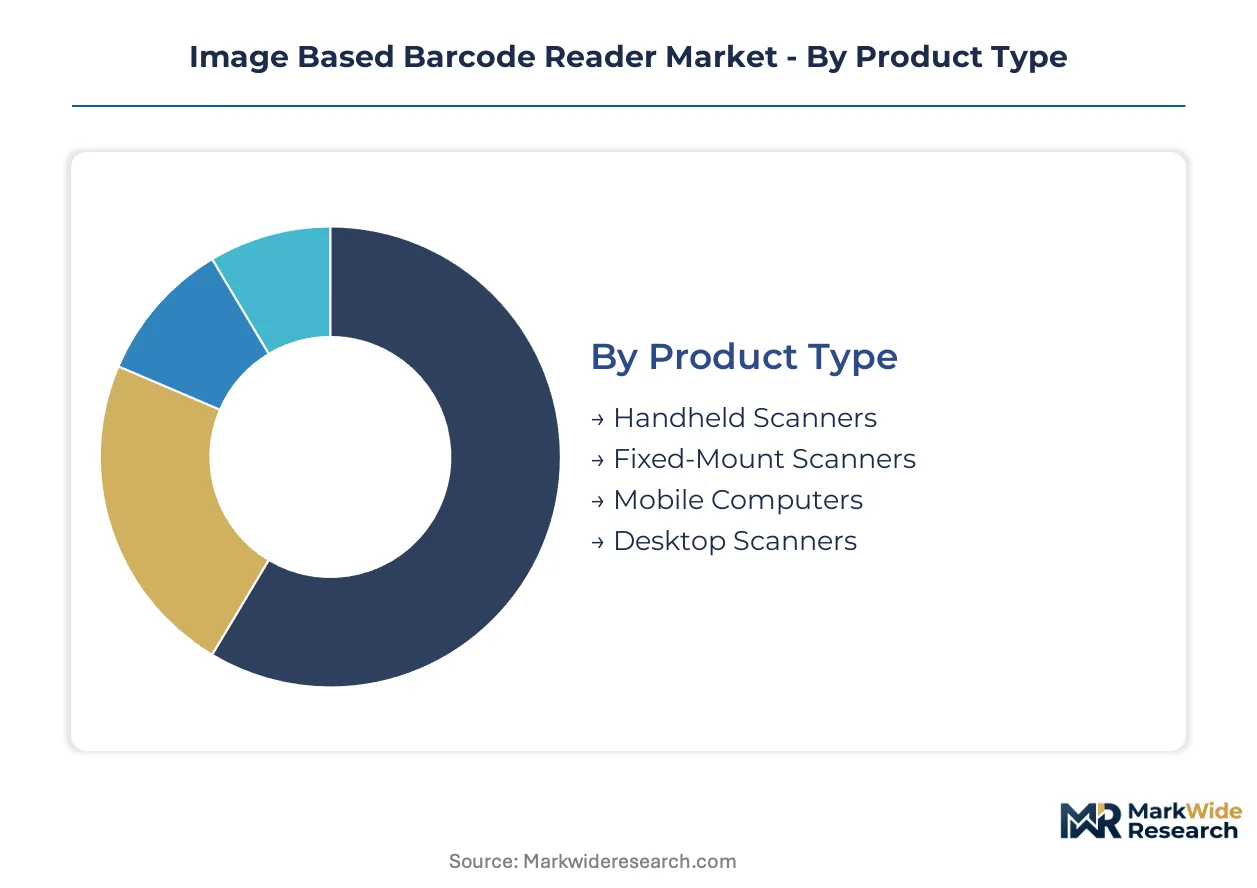
Segmentation in the image based barcode reader market reveals distinct service intensity profiles across hardware categories. Product architecture determines firmware update frequency, lens calibration needs, and integration complexity with warehouse management systems.
Product Type:
After-sales service intensity varies sharply across product architectures, with fixed-mount installations demanding continuous optical alignment support while handheld units require battery and housing replacement programs.
- Fixed-Mount Scanners:These units embed permanently on conveyor infrastructure with IP67-rated housings and triggered LED illumination arrays. Pharmaceutical packaging lines in the United States and Germany concentrate procurement here, driven by FDA UDI serialization mandates requiring continuous hands-free verification of implantable devices at speeds exceeding sixty frames per second.
- Mobile Computers:Android-based multifunction terminals combine 2D imagers with voice communication and workflow management in ruggedized form factors. E-commerce fulfillment centers in the United States represent the steepest expansion trajectory as operators consolidate from single-function laser scanners to unified mobile platforms.
- Handheld Scanners:Pistol-grip devices with CMOS sensors serve intermittent scanning tasks in retail backrooms and small warehouses.
- Desktop Scanners:Stationary units with presentation-mode optics target pharmacy counters and document processing stations.
Fixed-Mount Scanners hold the largest share; momentum sits with Mobile Computers.
Technology:
Cost tier differentiation separates premium deep-learning-enabled 2D systems from legacy laser architectures, with price spreads exceeding three-to-one at equivalent scan rates.
- 2D Image Recognition:CMOS and CCD sensor arrays capture matrix and stacked symbologies through neural inference engines rather than template-matching pipelines. Healthcare end users in the United States concentrate procurement in this configuration to meet FDA Unique Device Identification compliance for implantable devices.
- Laser Scanning:Rotating mirror and laser diode assemblies decode linear barcodes through reflected light intensity modulation. Legacy warehouse operations retain these units for one-dimensional pallet labeling, though RFID and 2D image recognition are displacing installations in high-velocity sortation environments.
- Optical Character Recognition:Software algorithms convert printed text to machine-readable data for shipping labels and expiration dates.
- RFID:Radio frequency identification readers capture tag data without line-of-sight requirements for bulk container tracking.
2D Image Recognition dominates revenue; RFID is gaining share fastest in closed-loop asset tracking applications.
End User:
Application-specific environmental demands dictate sealing ratings, drop specifications, and decode algorithm optimization across vertical markets.
- Logistics:Parcel sortation hubs and last-mile distribution centers deploy fixed-mount readers on high-velocity conveyors and mobile computers for yard management. E-commerce fulfillment operators in the United States and Germany drive volume, retrofitting polybag handling lines with damage-tolerant decode systems.
- Healthcare:Hospitals and pharmaceutical manufacturers prioritize 2D image recognition for FDA UDI compliance on implantable devices and unit-dose packaging. Procurement concentrates in configurations with antimicrobial housings and wireless connectivity for operating theater integration.
- Retail:Point-of-sale and inventory management applications favor handheld and presentation-mode desktop units.
- Manufacturing:Automotive and electronics assembly lines specify industrial-grade fixed-mount readers with Ethernet/IP connectivity.
Logistics commands the largest installed base; Healthcare shows the steepest expansion trajectory on regulatory compliance investment.
Installation:
Customer type segmentation separates enterprise buyers seeking centralized management from small operators prioritizing plug-and-play deployment.
- Integrated:Readers embed directly into OEM packaging machinery and conveyor systems through standardized mounting interfaces and industrial communication protocols. Semiconductor and pharmaceutical packaging equipment manufacturers in Taiwan and Germany specify these configurations for line-integrated traceability.
- Cloud-Based:Firmware and decode algorithms update over-the-air with usage analytics streamed to central dashboards. Third-party logistics providers in the United States pilot these architectures for distributed fleet management across multi-site operations.
- Portable:Battery-powered units with wireless connectivity serve popup retail and event logistics applications.
- Standalone:Self-contained readers with onboard processing require no external host connection for basic decode operations.
Integrated installations retain the largest share; Cloud-Based deployment is climbing the fastest on 5G private network convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural trade surplus in image-based barcode reader technology, exporting integrated fixed-mount systems to pharmaceutical packaging lines in Germany and Taiwan while importing CMOS sensor modules from South Korean and Taiwanese foundries.
United States
FDA Unique Device Identification mandates drive pharmaceutical serialization investments across implantable device manufacturers. The FCC Part 15 emissions framework governs wireless-enabled mobile terminal deployments in retail and logistics environments. E-commerce fulfillment clusters in California and Pennsylvania retrofit high-velocity conveyor lines with damage-tolerant decode systems for polybag handling.
Germany
Industrial automation integrators anchor European channel density for fixed-mount scanner installations in automotive and electronics assembly. REACH substance restrictions and RoHS amendments phase mercury-containing illumination from industrial scanner designs procured by packaging equipment OEMs. Machine vision engineering capabilities concentrate in Bavaria and Baden-Württemberg, supporting custom decode model training for damaged symbologies.
China
Domestic pharmaceutical manufacturers deploy 2D image readers to meet NMPA serialization requirements for export-bound active pharmaceutical ingredients. GB standards and MIIT regulations shape local product certification pathways for industrial-grade readers. Semiconductor packaging lines in the Yangtze River Delta and Pearl River Delta drive procurement of high-speed image recognition systems.
India
CDSCO serialization requirements for active pharmaceutical ingredients destined for regulated markets accelerate image reader deployment across packaging operations. The PLI scheme for electronics manufacturing incentivizes local assembly of CMOS-based scanning modules. Pharmaceutical formulation clusters in Gujarat and Hyderabad retrofit lines with FDA-compliant traceability systems.
Japan
Precision lens assembly suppliers in Osaka and Nagoya anchor the optical component supply chain for industrial-grade readers. METI industrial automation initiatives promote edge-AI convergence with private 5G networks in manufacturing facilities. Semiconductor equipment manufacturers in Kyushu specify high-resolution 2D image recognition for wafer-level packaging traceability.
Image Based Barcode Reader Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated hardware manufacturers with captive camera module production and neural inference engine capabilities. Three strategic archetypes dominate: full-stack mobile computer vendors controlling silicon-to-software pipelines, pure-play machine vision specialists focused on high-speed industrial decode, and optical component suppliers backward-integrating into finished reader assemblies. Dominant competitive moves include strategic partnerships with warehouse management system integrators and firmware-upgradeable platform architectures that extend hardware lifecycles against regulatory shifts.
Among North American technology conglomerates, Zebra Technologies and Honeywell International exemplify the vertically integrated archetype through in-house production of camera modules and Android-based mobile terminals. Cognex Corporation occupies a specialist position within high-speed 2D image recognition for semiconductor and pharmaceutical packaging applications. These three anchors illustrate the segmentation between broad mobile computing portfolios and concentrated industrial machine vision expertise.
| Leading Market Players |
|---|
| Zebra Technologies |
| Honeywell International |
| Cognex Corporation |
| Datalogic |
| Keyence Corporation |
| SICK AG |
| Omron Corporation |
| Microscan |
| Newland AIDC |
| Others |
Supply & Pricing Matrix
Taiwanese CMOS foundry capacity dynamics in Hsinchu Science Park directly determine downstream pricing power for mid-tier image-based reader vendors competing against vertically integrated leaders. Semiconductor fabrication output constraints in East Asia cascade through optical module costs, compressing margins for assemblers lacking captive sensor supply.
Pricing Analysis
Next-generation deep-learning-enabled readers command three-to-one premiums over legacy laser architectures, while prior-generation CMOS-based units face accelerating price erosion. Three-tier pricing structure across premium neural-inference systems, standard industrial-grade units, and economy handheld devices reflects certification grade differentiation and after-sales service bundling. Cost compression in economy tiers is intensifying because smartphone camera substitution erodes dedicated scanner volume in last-mile logistics. Third-party logistics providers show highest price sensitivity, while pharmaceutical manufacturers under FDA UDI mandates demonstrate lowest sensitivity due to compliance-driven procurement.
Supply Chain Analysis
Export-control restrictions on advanced CMOS fabrication equipment limit technology transfer to certain foundry jurisdictions, constraining high-resolution sensor availability for neural-inference reader architectures. Precision lens assemblies draw from Japanese and German optical component suppliers, while CMOS sensors rest on Taiwanese and South Korean semiconductor output. Single-source vulnerability concentrates in Japanese precision optics, where Osaka and Nagoya suppliers anchor industrial-grade reader illumination subsystems. Distribution runs through industrial automation integrators in Germany and North American channel partners serving warehouse management system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as FDA UDI serialization mandates and GS1 Digital Link transitions create specialized decode capability niches beyond generalist vendor reach. Demand-side regulatory complexity rewards focused engineering investment over broad portfolio breadth.
For Market Incumbents: Insulate core pharmaceutical and semiconductor packaging accounts by deepening firmware-upgradeable platform architectures that extend hardware lifecycles against regulatory shifts. Prioritize captive CMOS module production to defend margin position against Taiwanese foundry cost-curve advantages. Channel control through warehouse management system integrators remains critical as e-commerce fulfillment operators consolidate procurement around Android-based multifunction terminals.
For New Entrants and Emerging Players: Mid-market Indian pharmaceutical packaging lines in Gujarat and Hyderabad clusters represent the most penetrable entry point, where CDSCO serialization requirements create demand without entrenched incumbent relationships. Edge-AI decode modules for 5G private network deployments in German automotive assembly facilities offer second white-space target. Go-to-market through industrial automation system integrators in Bavaria bypasses direct channel competition with Zebra and Honeywell.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play machine vision specialists with trained neural decode models over diversified mobile computer vendors facing smartphone substitution pressure. Long-term viability hinges on edge-AI inference engine differentiation rather than hardware scale. Acquisition target archetype: mid-cap firms with FDA-validated pharmaceutical packaging deployments and embedded AI accelerator IP. Signal to watch: GS1 Digital Link URI encoding adoption rates in European retail, which would trigger resolution and optics upgrade cycles across installed base.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Upgradeable Platform Architecture | Extends hardware lifecycle against REACH and RoHS regulatory amendments without full replacement. |
| Neural Inference Engine Development | Enables sub-50-millisecond damaged-label decode for high-velocity e-commerce sortation lines. |
| Channel Partnership with WMS Integrators | Secures embedded position in warehouse automation retrofit cycles across California and Pennsylvania clusters. |
| CMOS Sensor Backward Integration | Reduces dependency on Taiwanese foundry pricing volatility for mid-tier reader cost structures. |
| GS1 Digital Link Compliance Investment | Positions for next-generation resolution and optics requirements in pharmaceutical serialization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with warehouse automation directors, pharmaceutical packaging engineers, industrial machine vision integrators, and CMOS sensor procurement leads at reader manufacturers. Secondary validation drew from FDA UDI guidance documents, FCC Part 15 filings, SEC 10-K disclosures of listed automation vendors, and ISO 15415/15416 print quality standards. Bottom-up unit shipment estimates by product architecture were triangulated against top-down value projections derived from semiconductor foundry output data and optical component trade flows.
Calibration against historical adoption curves in comparable automation equipment categories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, decode technology generation, end-use vertical, and installation type, with regional regulatory cluster as an additional industry-specific layer. CAGRs were derived from installed base replacement cycles and greenfield automation investment intensity, incorporating FDA UDI compliance deadlines and e-commerce fulfillment center buildout trajectories as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles at third-party logistics providers and semiconductor fabrication capacity expansion timing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology substitution rates. Material shifts in FCC wireless certification requirements or REACH substance restriction amendments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Ingaas Image Sensor Market
Imaging
CMOS X-Ray Detectors Market
Imaging
Latin America IP Camera Market
Imaging
Digitizer Market
Imaging
Global Ingaas Camera Market
Imaging
X-Ray Microscopes Market
Imaging
Machine Vision System and Services Market
Imaging
Hyperspectral Cameras Market
Imaging
Video Capture Card Market
Imaging
Side View Camera System Market
Imaging
Microscope Digital Cameras Market
Imaging
Short-Wave Infrared (SWIR) Camera Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Uncooled Infrared Imaging Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Fiducial Markers Market