
 Global Microscopy Market | 2026-2036
Global Microscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microscopy Market Outlook
Equipment leasing and pay-per-use service contracts is reconfiguring capital deployment across the microscopy value chain. Carl Zeiss AG leverages its captive financing arm to place super-resolution systems in mid-tier research institutes without upfront purchase. Thermo Fisher Scientific sustains competitive density through integrated workflow bundles that combine electron microscopy with sample preparation automation. JEOL Ltd. anchors its position in materials science through dedicated field service networks spanning Asia-Pacific manufacturing corridors.
Microscopy denotes the technical practice of magnifying specimens beyond the resolving power of unaided human vision, employing electromagnetic radiation or particle beams with numerical apertures exceeding 1.4 in oil-immersion optical systems and sub-angstrom resolution in aberration-corrected electron optics. Its primary commercial purpose spans quality assurance in semiconductor fabrication, diagnostic pathology in healthcare, and structural biology research. Electron microscopes command the dominant margin pool due to vacuum system complexity and proprietary electron column manufacturing, while super-resolution microscopy represents the fastest-expanding technology segment as live cell imaging protocols displace fixed-sample workflows. Optical microscopes retain volume leadership in education and routine clinical settings where capital constraints limit electron beam adoption.
The FDA enforces 21 CFR Part 820 quality systems for medical device microscopy, while the EMA's In Vitro Diagnostic Regulation tightens performance validation for digital pathology platforms entering European healthcare networks. ISO 10993 biocompatibility standards and IEC 61010-1 safety specifications further constrain product design cycles and certification timelines. China's NMPA accelerates local type testing requirements for imported analytical instruments, compressing market access windows for foreign manufacturers. Stakeholders must monitor how converging AI-enabled image analysis and evolving pre-market submission pathways reshape R&D prioritization and regional commercialization sequencing.
Market Dynamics
Equipment leasing structures and pay-per-use service contracts are reconfiguring capital deployment across the microscopy value chain, compressing traditional upfront purchase cycles and shifting margin capture toward recurring revenue streams.
Growth Catalysts
- EUV Lithography Scaling:Semiconductor manufacturers in Taiwan and South Korea are expanding metrology budgets as lithography nodes shrink below 3nm, driving demand for aberration-corrected electron microscopy systems capable of sub-angstrom resolution.
- 21 CFR Part 820:The FDA's quality system regulation for medical devices elevates validation requirements for pathology imaging systems, creating replacement demand for compliant digital pathology platforms in US healthcare networks.
- Live Cell Imaging Protocols:Super-resolution fluorescence techniques are displacing fixed-sample workflows in structural biology research, accelerating instrument refresh cycles at institutes pursuing real-time molecular dynamics studies.
Market Restraints
- Helium Supply Concentration:Cryogenic electron microscopy systems depend on helium-3 and helium-4 isotopes sourced from concentrated natural gas processing regions, exposing operators to price volatility and allocation constraints.
- Vacuum System Complexity:Electron microscope manufacturing requires proprietary electron column fabrication and ultra-high vacuum engineering capabilities concentrated among a limited supplier base, constraining production scaling.
- Optical Diffraction Limits:Conventional optical microscopy remains bounded by the Abbe limit of approximately 200 nanometers for visible light, restricting adoption for nanoscale semiconductor defect inspection without super-resolution augmentation.
Strategic Opportunities
- India's PLI Scheme:The Production Linked Incentive scheme for electronics manufacturing is attracting semiconductor fabrication investments that will require localized metrology and inspection microscopy capabilities.
- AI-Enabled Image Analysis:Convergence of deep learning segmentation algorithms with high-throughput slide scanning creates workflow automation opportunities in clinical pathology laboratories seeking diagnostic efficiency gains.
- Service Contract Penetration:Mid-tier research institutes in Germany's Baden-Württemberg cluster represent underpenetrated accounts for comprehensive maintenance and reagent supply agreements beyond initial instrument placement.
Industry Challenges
- Aberration-Correction Engineering Talent:The specialized physics and precision optics expertise required for electron column design exceeds available workforce supply, extending R&D timelines for next-generation instruments.
- Multi-Modal Integration Complexity:Correlative microscopy workflows combining light and electron imaging demand software interoperability across proprietary vendor platforms, complicating data pipeline standardization for materials science researchers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microscopy Market |
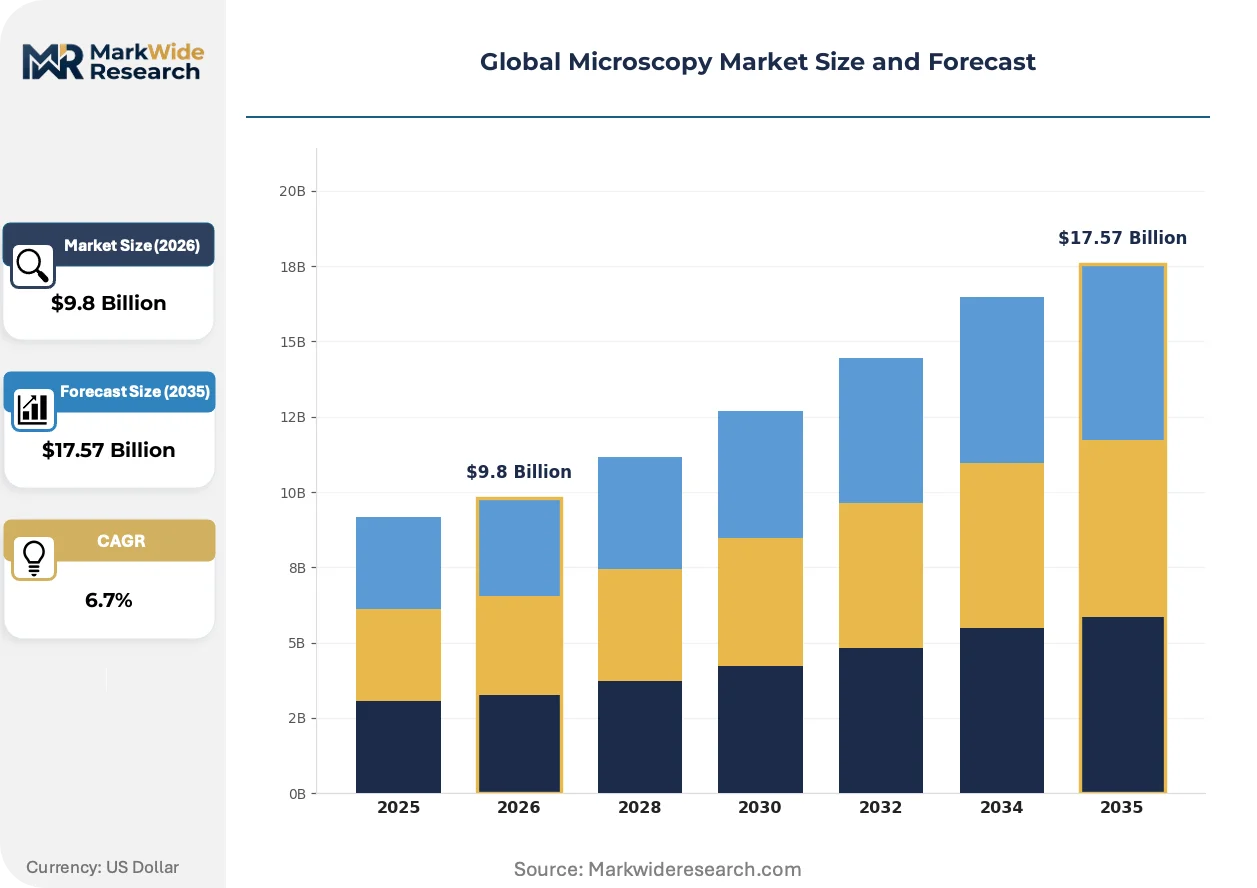
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Microscopes, Electron Microscopes, Scanning Probe Microscopes, Confocal Microscopes End User: Research Institutes, Healthcare Facilities, Pharmaceutical Companies, Material Science Organizations Technology: Fluorescence Microscopy, Phase Contrast Microscopy, Live Cell Imaging, Super-resolution Microscopy Application: Cell Biology, Genetics, Pathology, Nanotechnology |
| Companies Covered | Carl Zeiss AG, Thermo Fisher Scientific, Nikon Corporation, Danaher Corporation, Olympus Corporation, JEOL Ltd., Hitachi High-Tech Corporation, Oxford Instruments plc, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microscopy Market Strategic Shifts
Computational imaging methods and artificial intelligence integration are compressing hardware requirements while expanding analytical capabilities, fundamentally altering how resolution and contrast are achieved in both optical and electron microscopy modalities.
Super-resolution localization microscopy is collapsing the boundary between optical and electron imaging regimes by reconstructing sub-diffraction structures from stochastic fluorophore activation. Pharmaceutical discovery teams at contract research organizations are adopting these systems for protein-protein interaction mapping. The technology is collapsing capital barriers that previously forced researchers to choose between live-cell compatibility and nanoscale resolution.
REACH restrictions on per- and polyfluoroalkyl substances are compelling manufacturers to reformulate immersion oils and anti-reflective coatings used in high-NA optical systems. The European Chemicals Agency's substance evaluation process is accelerating substitution timelines for fluorinated compounds. German precision optics suppliers are responding with silicone-based alternatives that require recalibration of existing instrument validation protocols.
Consolidated purchasing by multi-site hospital networks is compressing vendor negotiation cycles and demanding enterprise-wide service level agreements. Procurement teams at US academic medical centers are unbundling instrument acquisition from reagent supply and maintenance contracts. This pattern is most visible in the Northeast corridor, where integrated delivery networks are standardizing on single-vendor digital pathology platforms to reduce training and interoperability costs.
Global Microscopy Market Segmentation
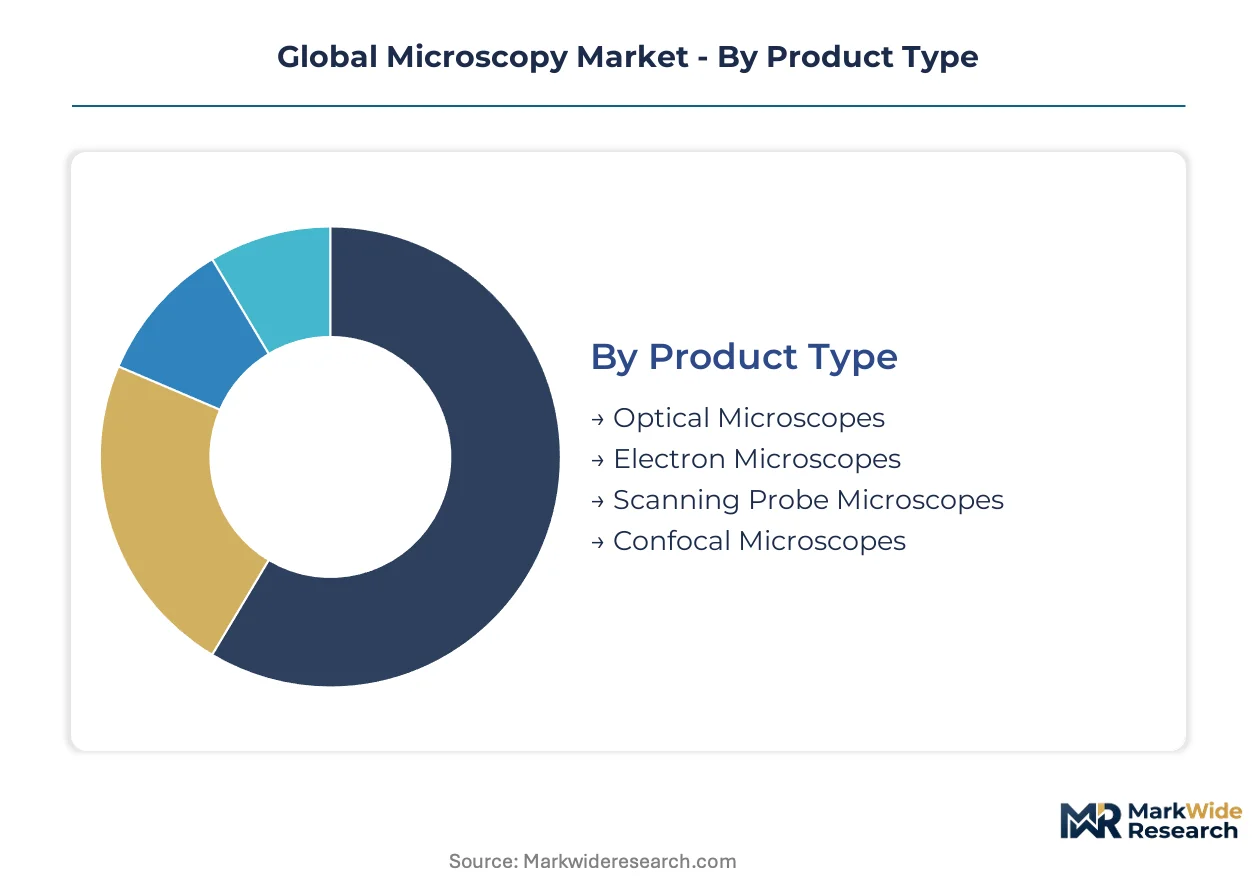
Microscopy market segmentation reveals distinct service intensity profiles across product architectures, with electron beam systems demanding specialized field engineering while optical platforms rely on standardized maintenance protocols. End-use concentration in semiconductor fabrication and clinical diagnostics creates divergent procurement patterns that reshape vendor commercial strategies.
Product Type:
After-sales service intensity varies dramatically across instrument architectures, with vacuum-dependent systems requiring dedicated field engineering networks and optical platforms sustaining margins through standardized maintenance contracts.
- Optical Microscopes:These systems employ visible light and glass objective lenses with numerical apertures reaching 1.4 in oil-immersion configurations. Demand clusters in Germany's Baden-Württemberg precision optics corridor, where educational institutions and routine clinical laboratories prioritize capital efficiency over resolution extremes. Service contracts focus on lamp replacement and alignment calibration rather than vacuum system maintenance.
- Electron Microscopes:Aberration-corrected systems achieve sub-angstrom resolution through proprietary electron column design and ultra-high vacuum engineering. Taiwan and South Korea semiconductor manufacturers drive replacement cycles as EUV lithography nodes advance below 3nm, requiring metrology capabilities beyond optical diffraction limits. Field service networks concentrate in Asia-Pacific manufacturing corridors where uptime guarantees command premium pricing.
- Scanning Probe Microscopes:Atomic force and scanning tunneling variants map surface topography through mechanical probe interaction. Materials science departments at research institutes represent the core installed base.
- Confocal Microscopes:Laser scanning architectures with pinhole apertures eliminate out-of-focus light for thick specimen optical sectioning. Pharmaceutical discovery teams adopt these for three-dimensional cellular imaging.
Electron microscopes hold the largest share; momentum sits with super-resolution optical systems collapsing the resolution gap for live-cell applications.
End User:
Procurement sophistication diverges sharply across customer types, with semiconductor manufacturers negotiating enterprise service agreements while academic institutes prioritize instrument leasing flexibility.
- Research Institutes:Structural biology laboratories pursue real-time molecular dynamics through super-resolution fluorescence techniques, accelerating instrument refresh cycles. US academic medical centers in the Northeast corridor unbundle acquisition from reagent supply contracts.
- Healthcare Facilities:Multi-site hospital networks consolidate purchasing power and demand standardized digital pathology platforms to reduce training costs. FDA 21 CFR Part 820 compliance elevates validation requirements for pathology imaging systems.
- Pharmaceutical Companies:Contract research organizations adopt localization microscopy for protein-protein interaction mapping in drug discovery workflows.
- Material Science Organizations:Correlative microscopy combining light and electron imaging demands software interoperability across proprietary vendor platforms.
Healthcare facilities command the largest share; pharmaceutical companies are expanding most quickly as outsourcing reshapes discovery economics.
Technology:
Margin capture concentrates in proprietary hardware-software bundles, with integrated workflow automation commanding pricing premiums over standalone imaging systems.
- Fluorescence Microscopy:Widefield and confocal variants employ excitation-emission spectral separation for specific molecular labeling. Life science research institutes represent the mature installed base.
- Phase Contrast Microscopy:Optical path length variations convert refractive index differences into intensity contrast without staining. Routine clinical settings favor this capital-efficient approach for live cell observation.
- Live Cell Imaging:Environmental control systems maintain physiological conditions during extended observation periods. Super-resolution techniques are displacing fixed-sample workflows as researchers pursue dynamic molecular processes.
- Super-resolution Microscopy:Stochastic optical reconstruction and structured illumination methods break the Abbe diffraction limit through computational post-processing. Pharmaceutical discovery teams adopt these systems where nanoscale resolution must combine with live-cell compatibility.
Fluorescence microscopy holds the largest share; super-resolution modalities are gaining share fastest as computational imaging compresses hardware requirements.
Application:
Regulatory validation requirements fragment by use case, with diagnostic pathology facing FDA pre-market submission pathways that research applications bypass.
- Cell Biology:Organelle dynamics and membrane trafficking studies drive demand for high temporal resolution imaging. Live cell protocols now dominate over fixed preparation methods.
- Genetics:Chromosomal imaging and fluorescence in situ hybridization require precise spatial mapping capabilities. Research institutes anchor this segment.
- Pathology:Digital slide scanning and AI-enabled image analysis create workflow automation opportunities in clinical laboratories. EMA In Vitro Diagnostic Regulation tightens performance validation for European healthcare network entry.
- Nanotechnology:Semiconductor defect inspection and materials characterization demand aberration-corrected electron microscopy with sub-angstrom resolution.
Pathology holds the largest share; nanotechnology is climbing the fastest as EUV lithography scaling intensifies metrology requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabricators in Taiwan and South Korea anchor equipment procurement, while German precision optics clusters and US academic medical centers concentrate demand for diagnostic and research systems.
United States
FDA 21 CFR Part 820 quality system regulations elevate validation requirements for digital pathology platforms entering US healthcare networks. Multi-site hospital networks in the Northeast corridor consolidate purchasing power and demand enterprise-wide service level agreements. Boston-Cambridge research institutes accelerate super-resolution fluorescence adoption for live-cell molecular dynamics studies.
Germany
Baden-Württemberg precision optics corridor hosts Carl Zeiss and Leica Microsystems manufacturing operations serving European semiconductor and life science demand. ECHA REACH restrictions on per- and polyfluoroalkyl substances compel reformulation of immersion oils and anti-reflective coatings. Stuttgart-based suppliers develop silicone-based alternatives requiring instrument recalibration protocols.
Taiwan
TSMC and foundry competitors expand metrology budgets as EUV lithography nodes advance below 3nm, requiring aberration-corrected electron microscopy for sub-angstrom defect inspection. National Development Council programs support domestic analytical instrument capabilities. Hsinchu Science Park concentrates field service engineering networks for uptime-critical manufacturing support.
South Korea
Samsung Electronics and SK Hynix drive replacement cycles for electron beam systems capable of advanced node characterization. MFDS medical device regulations align with international standards for pathology imaging equipment validation. Seoul-Pangyo corridor attracts vendor technical centers supporting both semiconductor and biomedical research demand.
China
NMPA accelerates local type testing requirements for imported analytical instruments, compressing market access windows for foreign manufacturers. Dual carbon policy goals shape energy efficiency specifications for electron microscope vacuum systems. Yangtze River Delta research institutes expand super-resolution microscopy procurement for structural biology applications.
Global Microscopy Market Competitive Environment
Channel-controlling players compete with product-specialist players across a consolidated vendor base where captive financing and integrated workflow bundles determine account access. Three strategic archetypes dominate: precision optics conglomerates with captive financing arms, diversified life science platforms bundling instrumentation with consumables, and dedicated electron beam specialists with field service density. Competitive moves center on equipment leasing structures displacing upfront purchase cycles, and AI-enabled software integration commanding pricing premiums over standalone hardware.
Within the precision optics tier, Carl Zeiss AG exemplifies channel control through captive financing placement of super-resolution systems in capital-constrained research institutes. Thermo Fisher Scientific occupies a position as diversified platform bundling electron microscopy with automated sample preparation workflows. JEOL Ltd. anchors the electron beam specialist archetype through Asia-Pacific field service networks concentrated in semiconductor manufacturing corridors.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| Thermo Fisher Scientific |
| Nikon Corporation |
| Danaher Corporation |
| Olympus Corporation |
| JEOL Ltd. |
| Hitachi High-Tech Corporation |
| Oxford Instruments plc |
| Bruker Corporation |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ningbo container corridor freight cost volatility feeds directly into landed price spreads between aberration-corrected electron microscopy systems and routine optical platforms, amplifying margin compression for mid-tier vendors while reinforcing pricing power at the vacuum engineering specialist tier.
Pricing Analysis
Cost-plus contracts with helium-3 indexation dominate service agreements for cryogenic electron microscopy systems, transferring commodity volatility risk from operators to vendors. Pricing stratifies across aberration-corrected electron platforms, bundled workflow automation suites, and standalone optical instruments based on vacuum system complexity and proprietary electron column certification. Price erosion runs through routine clinical optical segments as leasing structures displace upfront purchase cycles. Academic medical centers exhibit highest price sensitivity due to unbundled procurement mandates, while Taiwan semiconductor fabricators accept premium pricing for uptime-guaranteed field service density.
Supply Chain Analysis
Export controls on aberration-correction electron optics and extreme ultraviolet metrology equipment limit technology flows from Germany, Japan, and the United States to Chinese research institutes and emerging fabrication facilities. Proprietary electron column fabrication draws from concentrated precision optics suppliers in Baden-Württemberg, helium isotope processing in Qatar and Algeria, and ultra-high vacuum component machining in Japan. Single-source vulnerability concentrates in aberration-correction coil winding and electron source manufacturing. Distribution runs through direct field engineering networks for electron beam systems and authorized dealer channels for optical platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensive moats in microscopy rest on regulatory entrenchment: FDA 21 CFR Part 820 validation protocols and EMA In Vitro Diagnostic Regulation compliance create multi-year certification barriers that lock out unqualified entrants and cement incumbent replacement cycles.
For Market Incumbents: Insulate core electron beam margins through captive helium-4 supply contracting and backward integration into vacuum pump manufacturing. Defend against AI-enabled software entrants by embedding proprietary image analysis algorithms into hardware lease agreements, creating switching costs that extend beyond instrument refresh cycles. Prioritize certification investment for EUV lithography metrology systems as Taiwan and South Korea nodes advance below 3nm.
For New Entrants and Emerging Players: Mid-tier research institutes in India's emerging semiconductor fabrication corridor represent the most penetrable entry point for localized service contract penetration. Super-resolution optical systems for live cell imaging in contract research organizations offer second white-space targeting, capitalizing on pharmaceutical outsourcing economics. Pursue pay-per-use commercialization models that circumvent capital purchase committee approval thresholds.
For Investors and Strategic Acquirers: Field service engineering specialists with Asia-Pacific semiconductor corridor density command scarcity premiums in acquisition scenarios. Long-term viability favors vendors with integrated workflow automation capabilities spanning sample preparation through image analysis. Watch for inflection in India's PLI scheme disbursement velocity as signal for localized metrology demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Financing Arm Expansion | Carl Zeiss AG's leasing structures unlock capital-constrained research institute access without upfront purchase barriers. |
| AI-Enabled Image Analysis Integration | Deep learning segmentation algorithms embedded in digital pathology platforms command workflow automation premiums in clinical laboratories. |
| Helium Supply Contracting | Long-term helium-3 and helium-4 offtake agreements insulate cryogenic electron microscopy operators from allocation constraints. |
| Regional Field Service Density Buildout | JEOL Ltd.'s Asia-Pacific engineering networks sustain uptime guarantees that justify premium pricing for semiconductor manufacturers. |
| Regulatory Certification Investment | FDA 21 CFR Part 820 and EMA IVD compliance create multi-year validation barriers that entrench incumbent replacement demand. |
Study Parameters
A spread of perspectives from electron microscope field service engineers, semiconductor metrology directors, hospital purchasing committee members, and pathology laboratory managers converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation against SEC 10-K filings, NMPA registration databases, EMA IVD technical documentation, and EUV lithography node roadmaps. Bottom-up instrument shipment tracking and top-down end-use budget analysis triangulated market sizing across the analysis window.
Demand-supply-balance framing anchored the forecast framework, modeling procurement cycles across research institute, healthcare facility, pharmaceutical company, and materials science organization end-use segments. Technology dimensions spanned optical, electron beam, scanning probe, and super-resolution architectures. Application segmentation captured cell biology, pathology, nanotechnology, and genetics use cases. CAGRs derived from replacement cycle analysis, node transition timelines, and regulatory compliance mandate schedules. EUV lithography scaling intensity and AI-enabled diagnostic adoption curves served as primary demand drivers.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, helium commodity pricing, or research funding appropriations would shift the trajectory. Forecasts reflect assumptions on regulatory harmonization timelines and technology substitution elasticities. Material shifts in export control regime stringency or EUV node transition velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Handheld Imager Market
Imaging
Global Broadcast Cameras Market
Imaging
Photoconductor Drums Market
Imaging
X-Ray Microscopes Market
Imaging
Chemical Imaging Systems Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Gige Camera Market
Imaging
Global Waterproof Camera Market
Imaging
Global AI in Computer Vision Market
Imaging
Facial Recognition Machine Market
Imaging
Global 3D Camera Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Global Digital Photo Frame Market
Imaging
Hybrid Imaging Systems Market