
 On-Chip Color Filters Market | 2026-2036
On-Chip Color Filters Market Size, Share, and Industry Trends Forecast 2026-2036
On-Chip Color Filters Market Insights
Buyer concentration among smartphone camera module vendors is hardening as tier-one OEMs consolidate supplier lists around qualified filter sources. Sony Corporation leverages captive CMOS image sensor fabrication to anchor vertical control over spectral deposition stages. Samsung Electronics competes through in-house polymer filter engineering tied to Exynos ISP roadmaps. OmniVision Technologies, Inc. specializes in cost-optimized dye-based architectures for mid-tier handset designs.
On-chip color filters constitute micron-scale spectral-selective layers deposited directly atop photodiode arrays, typically employing patterned organic dyes or interference thin-films tuned to red, green, and blue passbands with sub-pixel alignment tolerances below two micrometers. These structures enable demosaicing in solid-state imagers without discrete optical components. Thin-film interference filters command premium positioning in automotive LiDAR and medical endoscopy where thermal stability outweighs cost, while dye-based filters dominate smartphone camera volumes through photolithographic patterning scalability. Nanostructured film approaches are gaining traction in wearable devices seeking polarization-insensitive spectral selectivity.
Japan's METI enforces JIS standards governing organic material outgassing in image sensor packages, directly constraining polymer technology formulation choices for suppliers targeting Japanese camera module integrators. China's SAMR administers GB standards for electronic component environmental compliance, creating divergent certification burdens for filter material vendors serving domestic versus export-bound sensor foundries. South Korea's MFDS maintains medical device imaging component guidelines that elevate barrier-to-entry for healthcare application segments. Stakeholders must monitor evolving spectral efficiency mandates from automotive regulators and medical imaging standards bodies as next-generation sensor fusion architectures redefine filter performance thresholds.
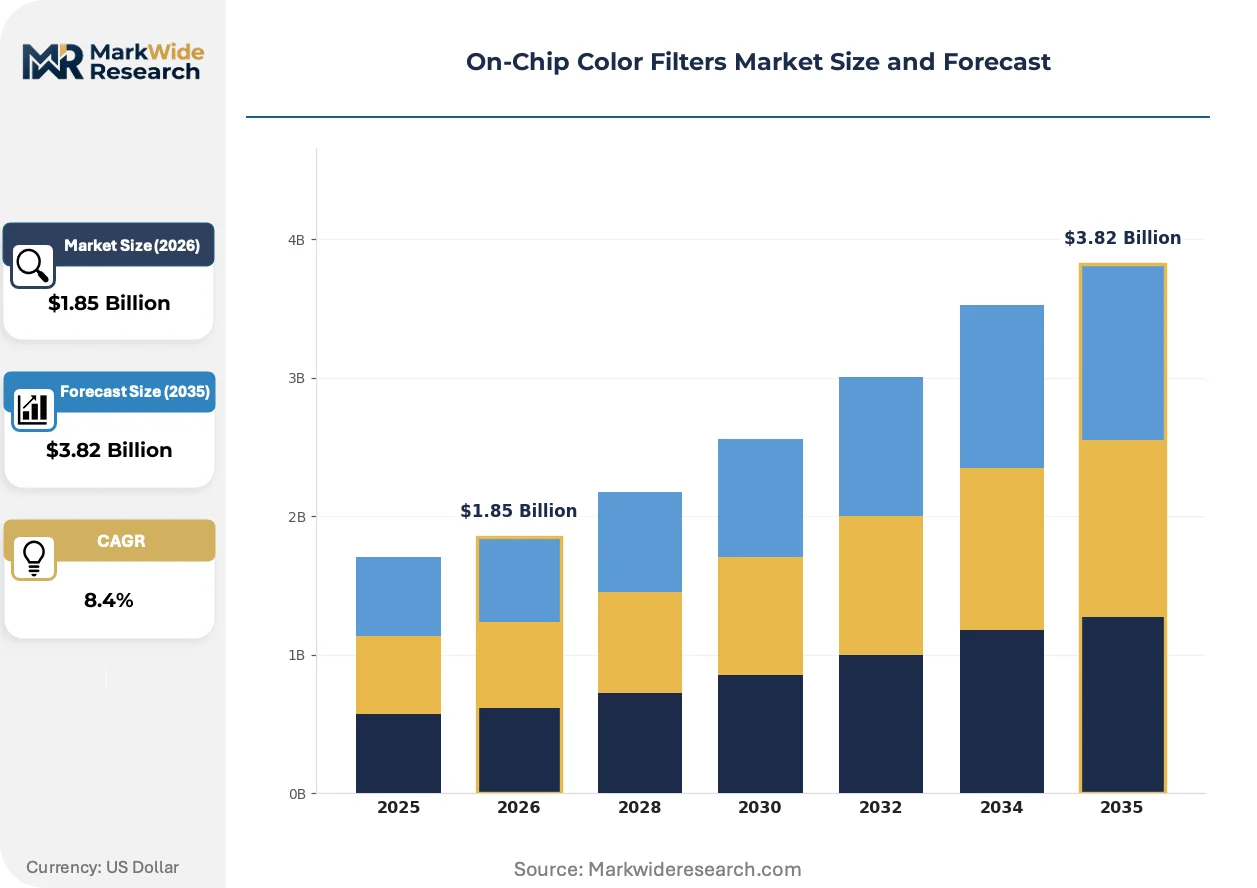
Market Dynamics
CMOS image sensor foundries in East Asia are consolidating captive filter deposition capacity, creating supply-side bottlenecks that reshape procurement leverage for fabless camera module vendors.
Growth Catalysts
- Automotive LiDAR spectral requirements:NHTSA's updated vehicle safety guidelines mandate higher wavelength precision for autonomous perception systems, pulling interference thin-film architectures into ADAS sensor stacks.
- GB standards compliance:China's SAMR environmental directives for electronic components force material purity upgrades across semiconductor-grade dye supply chains serving domestic foundries.
- Polymer engineering advances:Photolithographic patterning scalability for dye-based filters is accelerating throughput for mid-tier smartphone camera modules.
Market Restraints
- Organic dye thermal degradation:Dye-based filters face hard performance ceilings above 85°C operating temperatures, excluding them from engine-compartment automotive imaging.
- East Asian supply concentration:Deposition equipment and qualified polymer chemistries cluster in South Korean and Japanese fabrication corridors, amplifying disruption risk from regional logistics constraints.
- Outgassing certification friction:Japan's METI JIS standards impose multi-quarter validation timelines for organic material packages, extending time-to-revenue for new filter formulations.
Strategic Opportunities
- Medical endoscopy miniaturization:South Korea's MFDS imaging component guidelines create certified demand for thermal-stable interference filters in disposable endoscope designs.
- Wearable polarization insensitivity:Nanostructured film approaches are capturing design wins in health-monitoring wearables where spectral selectivity must function under variable illumination angles.
- EU Green Deal material incentives:REACH-compliant solvent-free deposition processes qualify for circular economy R&D funding, offsetting capex for European filter material entrants.
Industry Challenges
- Sub-micron alignment talent scarcity:Photodiode array patterning demands process engineers with compound semiconductor lithography experience, a skill set concentrated at Japanese and South Korean equipment vendors.
- Cross-certification complexity:Filter suppliers serving both Chinese domestic and export-bound sensor foundries must maintain parallel GB standards and REACH compliance documentation, doubling quality system overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Chip Color Filters Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film Filters, Micromirror Devices, Liquid Crystal Displays, Dye-Based Filters Technology: Polymer Technology, Nanostructured Films, Photolithography, Digital Light Processing Application: Smartphone Cameras, Automotive Displays, Wearable Devices, Medical Imaging End User: Consumer Electronics, Automotive Manufacturers, Healthcare Providers, Industrial Equipment |
| Companies Covered | OmniVision Technologies, Inc., Fujifilm Holdings Corporation, Sony Corporation, Dolby Laboratories, Inc., Canon Inc., Samsung Electronics, ON Semiconductor, Metahelios, Toppan Printing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Chip Color Filters Market Trends and Innovations
Spectral deposition architectures are bifurcating along thermal performance lines, with interference films penetrating heat-critical applications while dye-based platforms defend cost-sensitive volumes through manufacturing scale.
Interference thin-film filter stacks are expanding into automotive LiDAR and medical endoscopy where thermal stability overrides unit economics. Tier-one automotive Tier suppliers are qualifying these architectures for 125°C continuous operation. The technology is expanding into sensor fusion modules that combine visible imaging with near-infrared depth sensing.
REACH substance restrictions are tightening permissible organic solvents in photolithographic patterning processes, forcing reformulation of dye carrier chemistries. European filter material vendors are accelerating water-based deposition R&D to preempt regulatory displacement. Medical imaging OEMs are prioritizing REACH-compliant suppliers to streamline EU MDR device certification.
Camera module vendors are compressing supplier qualification cycles from eighteen months to nine months as smartphone OEMs consolidate approved vendor lists around three qualified filter sources. Long-tail dye suppliers are losing access to tier-one RFQs. South Korean foundries are most aggressive in supplier base rationalization, driven by Exynos ISP roadmap synchronization requirements.
On-Chip Color Filters Market Segmentation
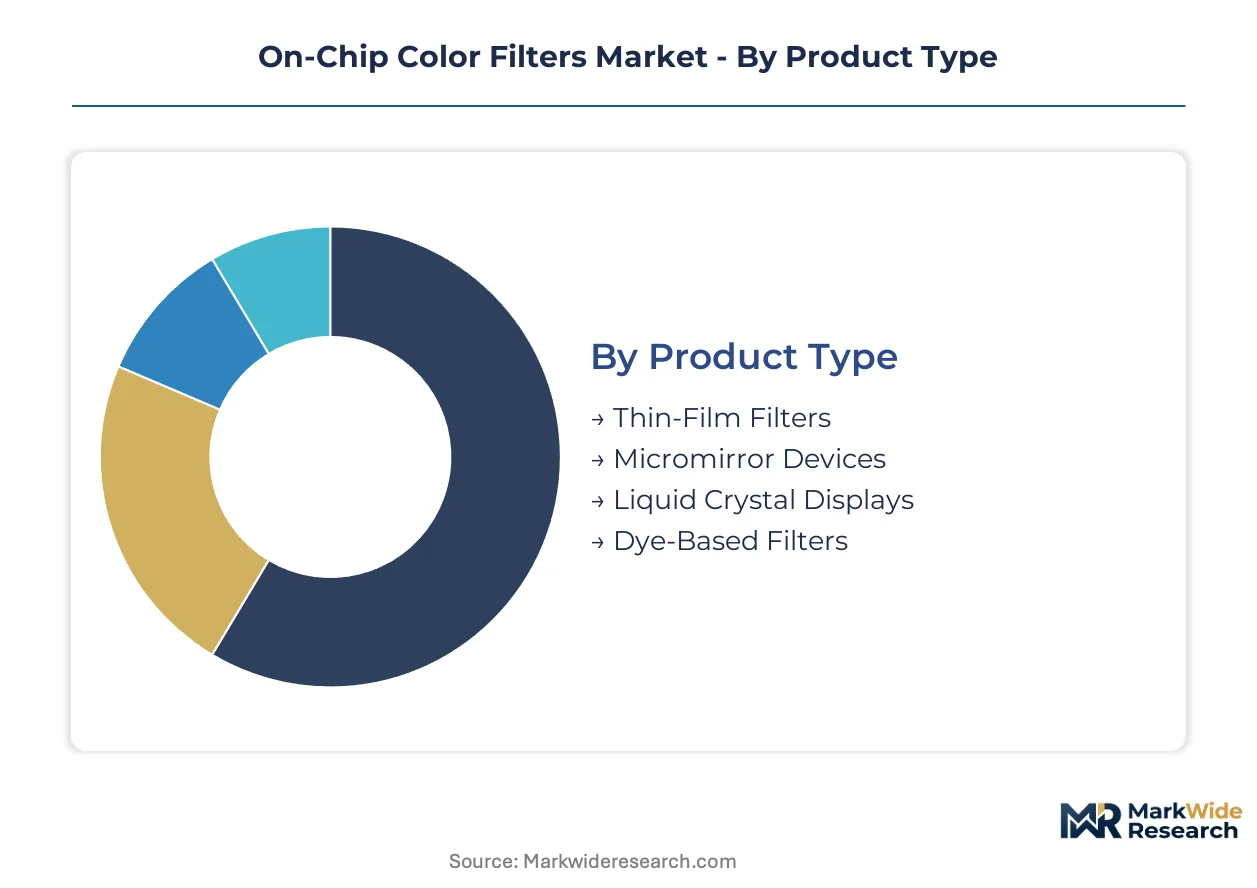
Filter architectures diverge sharply across thermal tolerance requirements and patterning economics. Product type selection determines foundry equipment compatibility and directly constrains which end-use verticals remain accessible to suppliers.
Product Type:
Dye-based platforms dominate smartphone volumes while interference films capture premium thermal-critical applications.
- Thin-Film Filters:Alternating dielectric layers create wavelength-selective interference with 125°C thermal stability. Automotive LiDAR and medical endoscopy in South Korea and Japan anchor demand as NHTSA guidelines tighten spectral precision mandates.
- Dye-Based Filters:Patterned organic photoresists enable sub-micron alignment at photolithographic scale. Smartphone camera module manufacturers in East Asian fabrication clusters absorb the majority of volume, though thermal degradation above 85°C excludes engine-compartment applications.
- Micromirror Devices:MEMS-actuated reflective arrays for projection systems requiring dynamic spectral modulation.
- Liquid Crystal Displays:Electrically tunable birefringence layers for polarization-controlled filtering in specialized imaging.
Today's leader: Dye-Based Filters. Tomorrow's challenger: Thin-Film Filters.
Technology:
Patterning scalability separates volume winners from niche specialists.
- Polymer Technology:Spin-coated organic dye matrices patterned through i-line or DUV lithography. Samsung Electronics and Sony Corporation foundries in South Korea and Japan maintain captive deposition capacity, locking in supply-side leverage over fabless module vendors.
- Photolithography:Mask-based UV exposure systems defining sub-pixel geometries with sub-micron overlay precision. China's SAMR GB standards compliance now mandates reformulation of carrier chemistries to reduce solvent emissions.
- Nanostructured Films:Subwavelength pillar arrays delivering polarization-insensitive spectral selectivity for wearable health monitors.
- Digital Light Processing:Micromirror array modulation for projection and spatial light engine applications.
Photolithography commands current volume. Nanostructured Films show steepest expansion trajectory in wearable segments.
Application:
Smartphone saturation is redirecting R&D toward automotive and medical heat-tolerant designs.
- Smartphone Cameras:Triple and quad-array modules demand RGB filter patterning at 0.7-micron pixel pitch. Tier-one OEM qualification cycles have compressed from eighteen to nine months, consolidating supplier lists around three qualified sources.
- Automotive Displays:In-cabin gesture recognition and driver monitoring systems require thermal cycling resistance. NHTSA updated safety guidelines are pulling interference thin-film architectures into ADAS sensor stacks.
- Wearable Devices:Health-monitoring bands and smartwatches prioritize polarization insensitivity under variable illumination angles.
- Medical Imaging:South Korea's MFDS guidelines create certified demand for disposable endoscope designs using thermal-stable interference filters.
Smartphone Cameras generate current margin pools. Medical Imaging offers the highest pricing persistence.
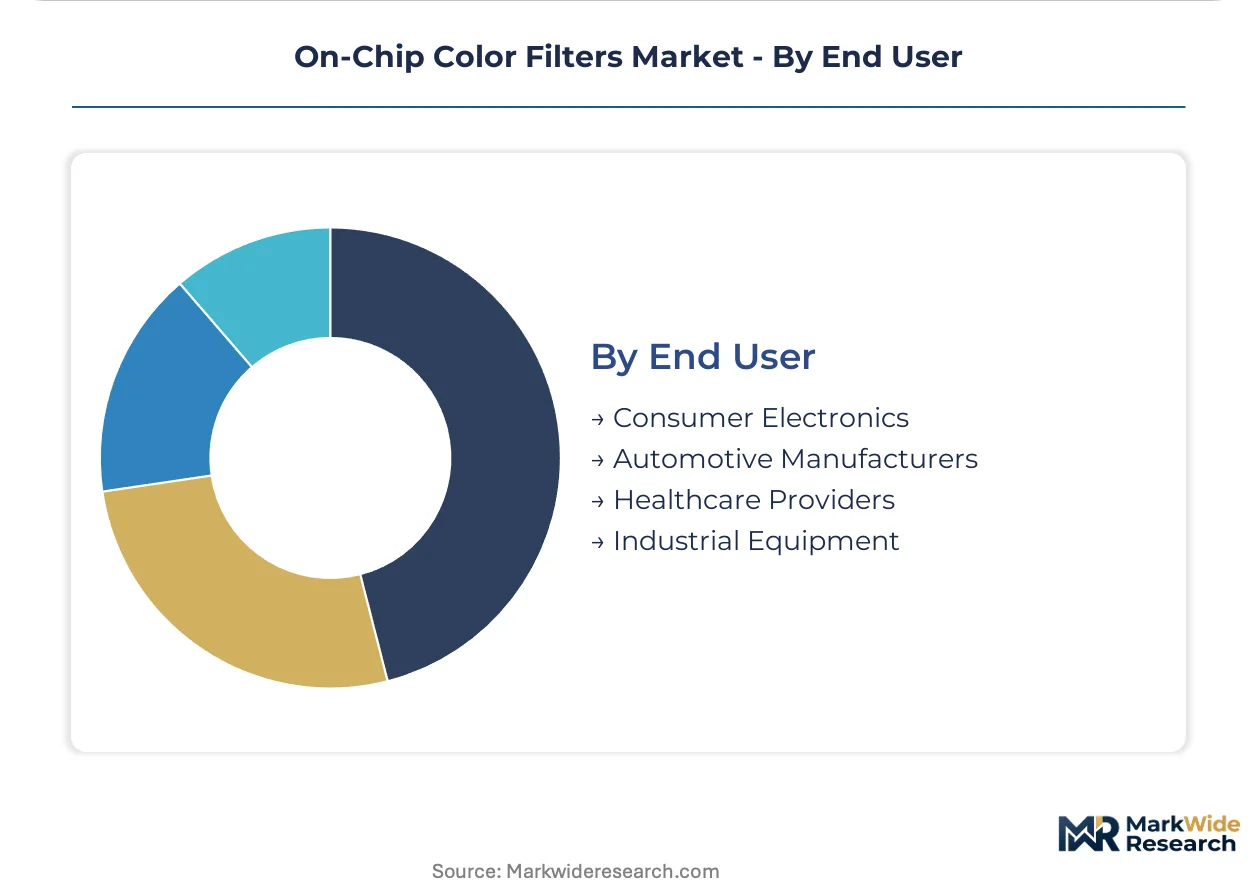
End User:
Procurement concentration varies dramatically across vertical integration strategies.
- Consumer Electronics:Smartphone and tablet OEMs with consolidated supplier lists. Camera module vendors face hardening buyer concentration as tier-one manufacturers reduce qualified filter sources.
- Automotive Manufacturers:Tier-one ADAS suppliers qualifying interference filters for 125°C continuous operation. Sensor fusion modules combining visible imaging with near-infrared depth sensing expand addressable content per vehicle.
- Healthcare Providers:Medical imaging OEMs prioritizing REACH-compliant suppliers to streamline EU MDR device certification pathways.
- Industrial Equipment:Machine vision and inspection systems with moderate thermal requirements and extended qualification timelines.
Consumer Electronics drives volume scale. Healthcare Providers sustain premium pricing through regulatory certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic foundry expansion contrasts with Japan's precision equipment dominance as both nations reshape procurement corridors for spectral deposition materials.
China
Domestic CMOS image sensor foundries are absorbing semiconductor-grade dye volumes at unprecedented scale. SAMR's GB standards for electronic component environmental compliance force material purity upgrades across supply chains serving Yangtze River Delta fabrication clusters. Shanghai and Suzhou house the densest concentrations of qualified filter deposition capacity for export-bound smartphone camera modules.
South Korea
Exynos ISP roadmap synchronization demands are compressing supplier qualification cycles to nine months. MFDS medical device imaging component guidelines create certified demand for thermal-stable interference filters in Seoul Capital Area endoscope manufacturing. Samsung Electronics anchors vertical control over polymer filter engineering through captive Busan-Ulsan fabrication corridors.
Japan
Photodiode array patterning equipment vendors concentrate lithography talent in Kanto and Chubu regions. METI enforces JIS standards governing organic material outgassing, extending validation timelines for new filter formulations. Nagoya and Osaka maintain the deepest benches of process engineers with compound semiconductor lithography experience.
United States
NHTSA updated vehicle safety guidelines mandate higher wavelength precision for autonomous perception systems. Automotive Tier suppliers are qualifying interference thin-film architectures for 125°C continuous operation in Michigan and California sensor fusion design centers. FDA oversight of medical imaging components elevates documentation burdens for REACH-compliant filter material vendors.
Germany
REACH substance restrictions are tightening permissible organic solvents in photolithographic patterning processes. ECHA regulatory pressure forces reformulation of dye carrier chemistries among Bavarian and Baden-Württemberg material vendors. Stuttgart and Munich host the primary R&D clusters for water-based deposition processes qualifying for EU Green Deal circular economy funding.
On-Chip Color Filters Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deposition technology tiers. The vendor base stratifies around three qualified filter sources for tier-one smartphone OEM qualification lists. Captive foundry operators anchor supply-side leverage through in-house polymer filter engineering. Strategic moves concentrate on supplier base rationalization and parallel GB standards documentation systems for dual-market access.
Within the diversified technology conglomerate tier, Sony Corporation and Samsung Electronics exemplify vertical control strategies through captive CMOS image sensor fabrication. Fujifilm Holdings Corporation occupies a position representing precision chemical and optical material heritage. These three anchors illustrate how East Asian fabrication clusters concentrate both demand absorption and supply-side leverage within integrated corporate structures.
| Leading Market Players |
|---|
| OmniVision Technologies, Inc. |
| Fujifilm Holdings Corporation |
| Sony Corporation |
| Dolby Laboratories, Inc. |
| Canon Inc. |
| Samsung Electronics |
| ON Semiconductor |
| Metahelios |
| Toppan Printing Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals and tightening GB standards for semiconductor-grade dyes gate qualified supply access and premium-tier pricing power, forcing filter material vendors to absorb compliance costs or exit tier-one procurement lists entirely.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for photolithographic patterning services as Samsung Electronics expands captive Busan-Ulsan deposition corridors. Three-tier pricing structure across premium interference films, standard dye-based filters, and economy photoresist grades separates thermal-stable automotive qualification tiers from smartphone volume contracts. Cost compression in mid-tier smartphone modules intensifies as camera module vendors consolidate around three qualified sources, squeezing long-tail dye suppliers. Automotive LiDAR manufacturers exhibit least price sensitivity due to NHTSA wavelength precision mandates, while mid-tier handset OEMs drive hardest bargain on per-unit filter costs.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers in Kanto and Chubu regions, with i-line and DUV lithography chemistries drawing from concentrated polymer engineering talent pools. High-purity organic dyes, dielectric thin-film materials, and photomask blanks feed from South Korean, Japanese, and German specialty chemical corridors. Single-source vulnerability in qualified deposition equipment creates chokepoint risk for fabless module vendors seeking foundry slot allocation. Distribution runs through East Asian fabrication clusters where CMOS image sensor foundries maintain captive filter deposition capacity, locking in upstream control over spectral material flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The On-Chip Color Filters Market compounds steadily as automotive LiDAR spectral precision mandates pull interference thin-film architectures into expanding ADAS sensor stacks, creating durable demand foundations across thermal-critical applications.
For Market Incumbents: Deepen captive polymer filter engineering through backward integration into photoresist formulation, defending against emerging nanostructured film specialists targeting wearable polarization-insensitive segments. Anchor capacity additions in South Korean and Japanese fabrication corridors to synchronize with Exynos and ISP roadmap requirements. Prioritize parallel GB standards and REACH compliance documentation systems to maintain dual-market access without qualification duplication.
For New Entrants and Emerging Players: Medical imaging OEMs present the most penetrable channel partner type for REACH-compliant interference filter suppliers, as EU MDR certification pathways elevate barriers against incumbent dye-based architectures. Target disposable endoscope designs under South Korea's MFDS guidelines where thermal-stable thin-film demand outpaces qualified supply. Pursue water-based deposition R&D partnerships with Bavarian material vendors to preempt ECHA solvent restrictions.
For Investors and Strategic Acquirers: Roll-up economics work for specialized thin-film deposition equipment vendors because automotive LiDAR qualification timelines extend competitive moats beyond typical technology cycles. Five-to-ten year viability rests on interference film penetration into sensor fusion modules combining visible imaging with near-infrared depth sensing. Watch NHTSA wavelength precision mandate expansion as the inflection signal indicating accelerated thin-film share capture in heat-critical automotive tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Captive Deposition | Samsung Electronics and Sony Corporation anchor supply-side leverage through Busan-Ulsan and Nagoya fabrication corridors. |
| REACH-Compliant Solvent Transition | Water-based photoresist R&D in Stuttgart and Munich qualifies for EU Green Deal circular economy funding pools. |
| Automotive LiDAR Qualification | Tier-one ADAS suppliers in Michigan and California validate interference films for 125°C continuous operation. |
| Medical Device Certification Investment | MFDS-compliant filter suppliers capture Seoul Capital Area disposable endoscope manufacturing demand. |
| Backward Integration into Photoresist | In-house polymer engineering locks in photolithographic patterning scalability for mid-tier smartphone volumes. |
Research Methodology
Bottom-up CMOS image sensor foundry modeling reconciled against top-down spectral deposition capacity tracking forms the analytical core of this study. Primary interviews with camera module procurement directors, polymer R&D leads at Japanese equipment vendors, SAMR compliance officers, and automotive Tier 1 sensor fusion engineers combined with secondary validation from SEC 10-K filings, ECHA REACH substance databases, NHTSA vehicle safety guideline updates, and MFDS medical device registration records. Top-down and bottom-up triangulation reconciles foundry utilization rates against smartphone OEM bill-of-materials disclosures.
Historical trendline analysis of dye-based filter shipment volumes and interference thin-film qualification milestones informed projection parameters across the analysis window. Segmentation modeling spans filter architecture type, patterning technology tier, end-use vertical, and regional fabrication cluster. CAGRs derived from equipment vendor order backlogs and foundry capex disclosures, with automotive LiDAR content-per-vehicle and medical endoscope miniaturization trajectories serving as industry-specific demand anchors.
Revisions become necessary when NHTSA wavelength precision mandates expand beyond current ADAS tiers, ECHA solvent restrictions accelerate beyond water-based deposition readiness, or East Asian logistics disruptions persist beyond quarterly equipment delivery windows. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Camera Stabilizer Market
Imaging
Chemiluminescence Imaging Market
Imaging
Global Thermal Imager Market
Imaging
Biophotonics Market
Imaging
Photo Kiosk Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Mobile Imaging Services Market
Imaging
CMOS X-Ray Detectors Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Cooled IR Camera Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
SDI Camera Market
Imaging
US Near Infrared Imaging Market
Imaging
Cinematographic Camera Market
Imaging
Vintage Cameras Market